
 Australia Office Furniture Market | 2026-2036
Australia Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Office Furniture Market Analysis
The Australian office furniture supply base is consolidating around two distinct performance tiers: premium ergonomic systems commanding extended lead times and commodity flat-pack lines competing on delivery speed. Steelcase leverages its research-driven seating portfolio to anchor high-value corporate accounts in Sydney and Melbourne. Herman Miller / MillerKnoll (WorkArena) differentiates through healthcare and education sector specialization, while Officeworks controls volume distribution across suburban SME channels.
Australian office furniture encompasses workstations, seating, storage, and partitioning systems engineered for commercial interior environments, typically fabricated from engineered timber substrates, powder-coated steel frames, and upholstery textiles meeting AS/NZS 4443 flammability protocols. The product category serves knowledge-worker productivity, spatial flexibility, and occupational health compliance in leased and owned commercial premises. Chairs and desks occupy the largest revenue pools, with metal-framed height-adjustable desks recording the fastest specification growth among corporate end users. Wood and fabric material segments retain premium positioning, while plastic components face substitution pressure from recycled-content mandates.
The Australian Building Codes Board and Work Health and Safety regulators enforce workstation dimensional standards and load-bearing specifications that filter allowable product designs. GECA certification and FSC chain-of-custody documentation increasingly determine eligibility for government and institutional procurement panels. Stakeholders must monitor how evolving WHS psychological safety guidelines reshape spatial planning requirements and furniture specification criteria.
Market Dynamics
The Australian office furniture market is restructuring around the Australian Building Codes Board's updated workplace ergonomics guidelines, which are compressing specification timelines and forcing rapid product portfolio adjustments among domestic distributors and manufacturers.
Growth Catalysts
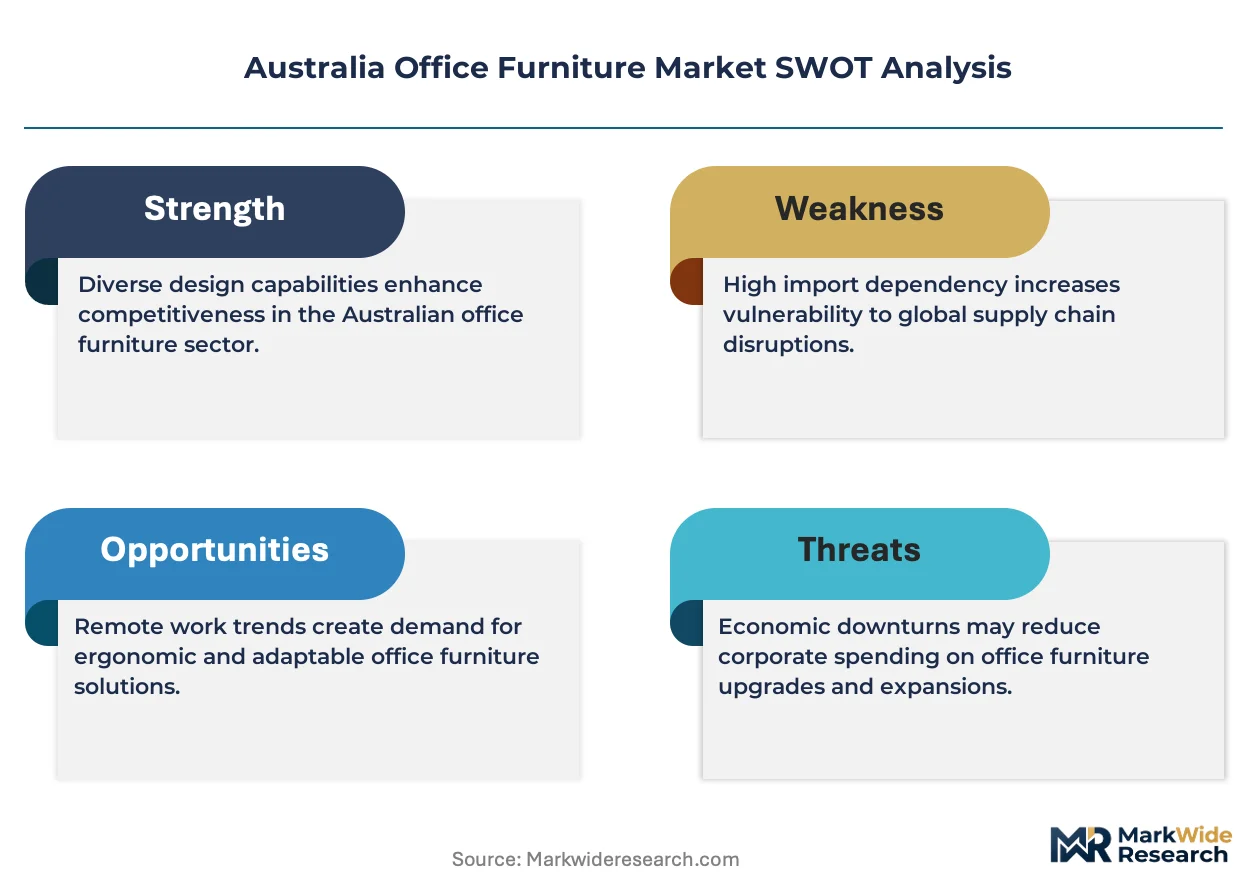
- Technology Sector Fit-Outs:Sydney and Melbourne commercial property developers are expanding fit-out programs for technology sector tenants, creating concentrated demand for premium ergonomic workstations in New South Wales and Victoria.
- AS/NZS 4443 Compliance Mandates:Flammability protocol updates are filtering allowable product designs and eliminating non-compliant imports from specification channels.
- Adjustable-Height Workstation Specification:Corporate headquarters refurbishments across eastern seaboard states are specifying metal-framed height-adjustable desks at accelerating rates.
Market Restraints
- Timber Substrate Cost Volatility:Engineered timber input costs fluctuate with Australian plantation harvest cycles and import dependency on Southeast Asian suppliers.
- Premium Tier Supply Concentration:Extended lead times for research-driven seating portfolios constrain rapid deployment for large-scale corporate rollouts.
- Recycled-Content Substitution Pressure:Plastic components face displacement mandates under evolving GECA certification criteria for government procurement eligibility.
Strategic Opportunities
- Queensland and Western Australia Underpenetration:Corporate headquarters concentration in Brisbane and Perth remains below Sydney-Melbourne levels, offering whitespace for ergonomic system specification.
- Healthcare and Education Sector Specialization:Institutional procurement panels outside traditional corporate channels seek dedicated seating and storage configurations.
- FSC Chain-of-Custody Documentation:Government and institutional procurement panels increasingly require verified sustainable sourcing, creating competitive differentiation for certified domestic fabricators.
Industry Challenges
- Work Health and Safety Psychological Safety Integration:Evolving WHS guidelines reshape spatial planning requirements, forcing furniture specification criteria updates without standardized implementation frameworks.
- Ergonomic Certification Timeline Compression:Rapid regulatory iteration accelerates product testing cycles and compresses return-on-development windows for domestic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Office Furniture Market |
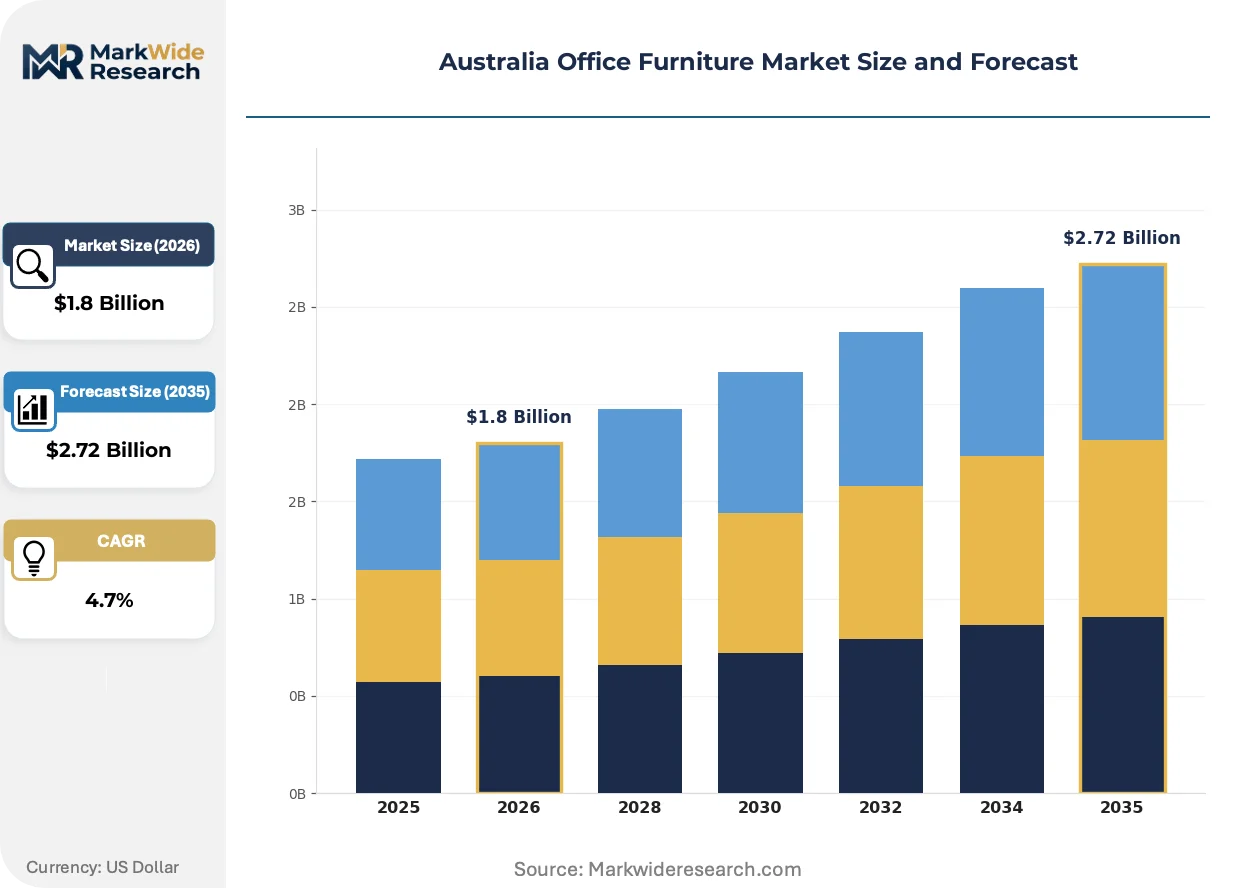
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Cubicles, Storage Units Material: Wood, Metal, Plastic, Fabric End User: Corporations, Startups, Educational Institutions, Government Distribution Channel: Online Retail, Showrooms, Wholesalers, Direct Sales |
| Companies Covered | Steelcase, Workspace Commercial Furniture, Officeworks, JasonL, Infinity Commercial Furniture, Herman Miller / MillerKnoll (WorkArena), Winc Australia, Krost, IKEA Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Office Furniture Market Emerging Trajectories
Sensor-integrated furniture systems are penetrating Australian corporate fit-outs, converting static workstations into data-generating assets that feed facility management platforms and reshape how landlords monetize tenant amenities.
Embedded occupancy and posture sensors within height-adjustable desk frames is electrifying the workstation category, converting hardware into connected infrastructure. ASX-listed corporate tenants in Sydney CBD towers are specifying these systems for wellness program integration. The technology is electrifying competitive positioning by compressing the traditional furniture-hardware-software vendor boundaries.
The Australian Building Codes Board's ergonomic guideline updates are mandating dimensional standards and load-bearing specifications that filter allowable product designs. Domestic manufacturers must retest existing portfolios against revised protocols. Corporate end users in New South Wales and Victoria are responding by consolidating procurement around pre-certified supplier relationships.
Consolidated procurement through national facilities management providers is displacing fragmented branch-level purchasing across suburban SME channels. Officeworks volume distribution networks face compression as enterprise buyers centralize specification authority. This concentration is most visible in Melbourne's technology corridor, where tenant improvement allowances now flow through integrated workplace strategy consultancies rather than traditional dealer channels.
Australia Office Furniture Market Segmentation
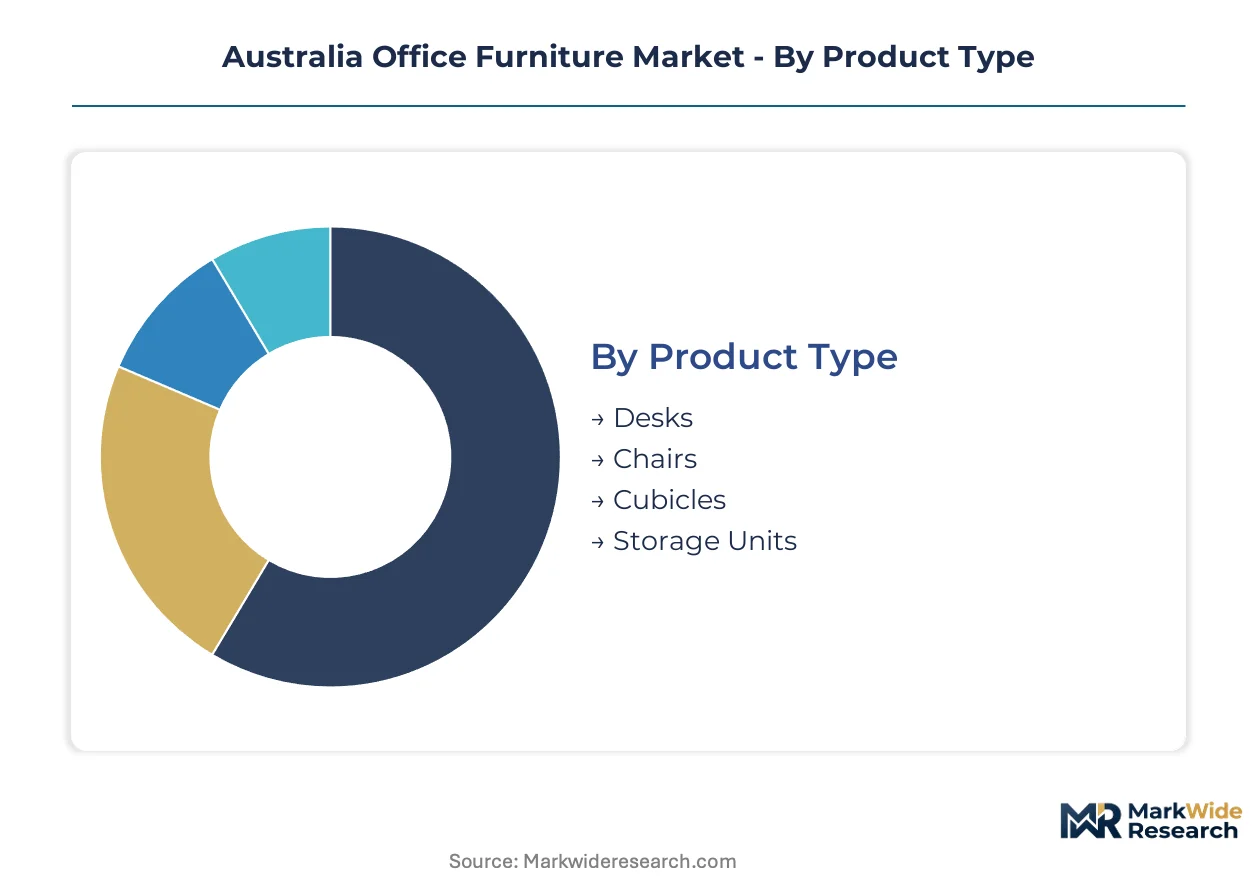
Segmentation in Australian office furniture reveals how procurement authority concentrates differently across product categories and channel structures. Understanding these splits enables suppliers to align certification investments and inventory positioning with actual specification behavior.
Product Type:
Volume concentration favors seating and surface categories, while premium margins attach to integrated systems requiring installation coordination.
- Desks:Metal-framed height-adjustable configurations dominate corporate headquarters refurbishments across New South Wales and Victoria. The Australian Building Codes Board's updated ergonomic guidelines are compressing specification timelines for workstation dimensional compliance.
- Chairs:Research-driven ergonomic seating commands extended lead times and anchors high-value accounts in Sydney and Melbourne technology sector fit-outs. Upholstery textiles must meet AS/NZS 4443 flammability protocols for commercial eligibility.
- Cubicles:Partitioning systems serve spatial flexibility requirements in leased premises, with demand concentrating in tenant improvement programs.
- Storage Units:Filing and locker configurations support compliance-driven document retention in government and institutional procurement panels.
Mature deployment sits with chairs. Newer deployment is concentrated in desks.
Material:
Cost tier separation runs through substrate selection, with certified sustainable materials accessing government procurement eligibility unavailable to conventional alternatives.
- Wood:Engineered timber substrates retain premium positioning despite cost volatility tied to Australian plantation harvest cycles. FSC chain-of-custody documentation increasingly determines eligibility for institutional specification.
- Metal:Powder-coated steel frames anchor height-adjustable desk specifications, climbing the fastest among corporate end users seeking durability and load-bearing compliance.
- Plastic:Components face substitution pressure from recycled-content mandates under evolving GECA certification criteria.
- Fabric:Upholstery textiles meeting AS/NZS 4443 protocols serve seating and soft partitioning applications in premium ergonomic portfolios.
Conventional specification favors metal and fabric pairings. Emerging procurement is redirecting toward wood with verified chain-of-custody.
End User:
Customer type determines whether purchasing flows through centralized facilities management or fragmented branch-level authority.
- Corporations:ASX-listed tenants in Sydney CBD towers are consolidating procurement through integrated workplace strategy consultancies, displacing traditional dealer channels.
- Startups:Technology sector tenants in Melbourne's corridor drive concentrated demand for premium ergonomic workstations through developer-managed fit-out programs.
- Educational Institutions:Healthcare and education sector specialization creates dedicated seating and storage configuration requirements outside traditional corporate channels.
- Government:Procurement panels enforce GECA certification and FSC documentation as gatekeeping criteria for supplier eligibility.
Established procurement discipline sits with government. Accelerating specification volume is concentrated in corporations.
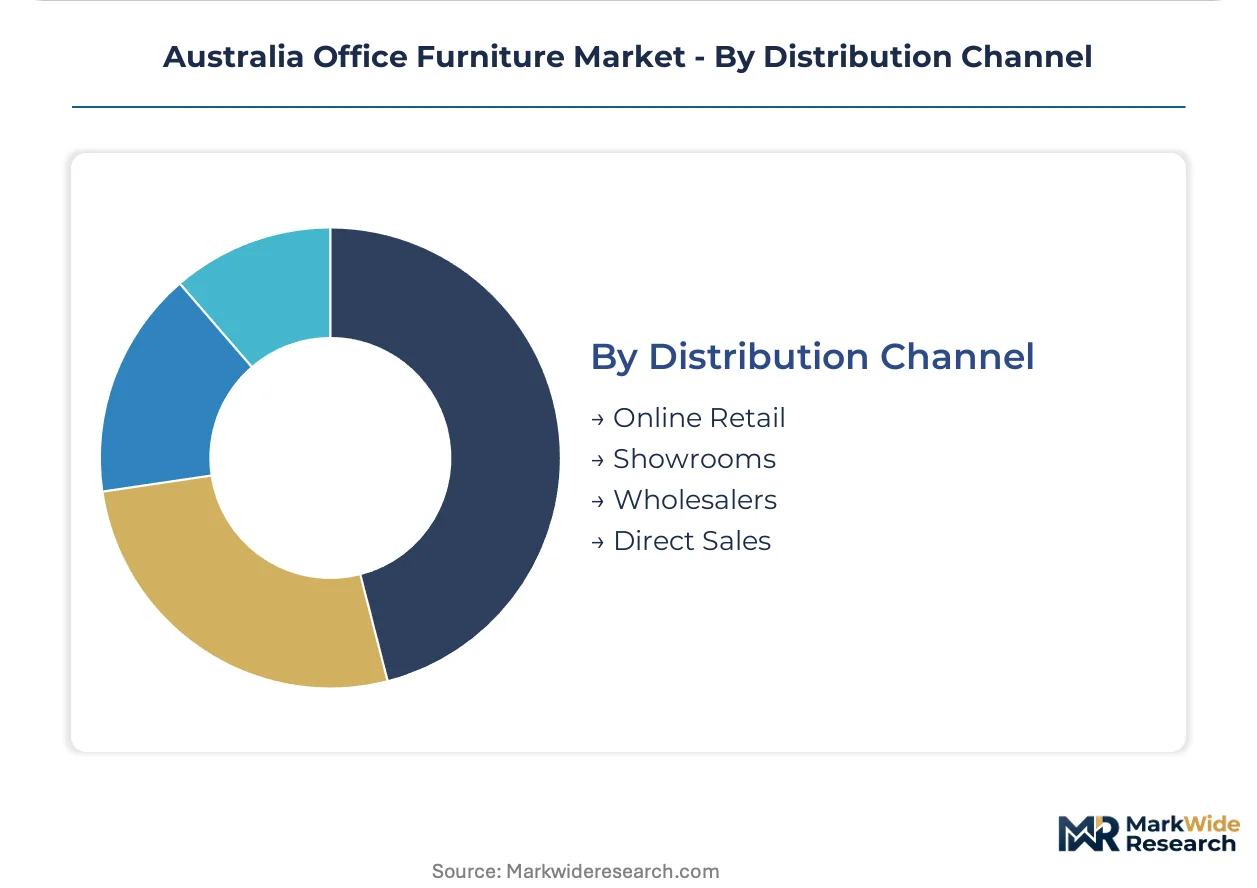
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with enterprise centralization compressing volume distribution networks.
- Online Retail:Suburban SME channels favor delivery speed over configuration consultation, though enterprise buyers are reducing branch-level purchasing fragmentation.
- Showrooms:Physical specification environments support ergonomic seating trials and workstation configuration for corporate headquarters refurbishments.
- Wholesalers:Volume distribution networks face compression as national facilities management providers consolidate procurement authority.
- Direct Sales:Research-driven seating portfolios rely on manufacturer-direct relationships to anchor high-value accounts with extended lead time coordination.
Traditional wholesale volume sits with showrooms. Channel expansion is concentrated in direct sales for premium ergonomic systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne commercial property developers anchor Australian office furniture demand through technology sector fit-out programs concentrated in New South Wales and Victoria.
New South Wales
Technology sector tenants in Sydney CBD towers drive premium ergonomic workstation specifications through developer-managed improvement allowances. The Australian Building Codes Board enforces updated workplace ergonomics guidelines that compress certification timelines for domestic distributors. Parramatta's emerging commercial corridor attracts satellite headquarters requiring rapid furniture deployment.
Victoria
Corporate headquarters refurbishments across Melbourne's technology corridor specify metal-framed height-adjustable desks at accelerating rates. Work Health and Safety regulators mandate workstation dimensional standards that filter allowable product designs for commercial eligibility. Southbank and Docklands precincts concentrate ASX-listed tenant fit-out activity.
Queensland
Brisbane commercial development lags Sydney-Melbourne concentration, creating whitespace for ergonomic system specification in emerging headquarters. State procurement panels enforce GECA certification as gatekeeping criteria for government furniture contracts. Fortitude Valley's technology startup cluster generates nascent demand for flexible workstation configurations.
Western Australia
Perth's resource sector headquarters maintain conservative furniture replacement cycles compared to eastern seaboard technology tenants. State government infrastructure programs channel institutional procurement through certified supplier relationships. Subiaco and West Perth commercial precincts show gradual specification migration toward adjustable-height workstations.
South Australia
Adelaide's defense and healthcare institutional procurement creates dedicated seating and storage configuration requirements outside corporate channels. State sustainability mandates accelerate FSC chain-of-custody documentation requirements for government panel eligibility. The Lot Fourteen innovation precinct generates limited but growing technology sector furniture demand.
Australia Office Furniture Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification complexity and specification lead time dimensions. The supply base organizes around research-driven ergonomic portfolios commanding extended delivery windows versus flat-pack lines competing on suburban delivery speed. Three archetypes dominate: multinational research-driven specialists, domestic volume distributors, and integrated workplace strategy consultancies. Competitive moves concentrate on portfolio certification acceleration and direct sales relationship anchoring.
Among research-driven specialists, Steelcase and Herman Miller / MillerKnoll (WorkArena) exemplify premium-tier positioning through ergonomic seating portfolios. Officeworks occupies the volume distribution archetype across suburban SME channels. These three anchors illustrate how specification authority concentrates differently across corporate headquarters and fragmented branch-level purchasing.
| Leading Market Players |
|---|
| Steelcase |
| Workspace Commercial Furniture |
| Officeworks |
| JasonL |
| Infinity Commercial Furniture |
| Herman Miller / MillerKnoll (WorkArena) |
| Winc Australia |
| Krost |
| IKEA Australia |
| Others |
Supply Flow & Price Mechanics
Ergonomic certification specialists concentrated in Melbourne and Sydney manufacturing corridors command wage premiums that compress margin spreads between commodity flat-pack lines and premium research-driven seating portfolios. Labor-cost differentials across these certification tiers translate directly into pricing stratification across premium, standard, and economy levels.
Pricing Analysis
Outcome-based pricing anchored to workstation productivity metrics and wellness program integration separates premium ergonomic systems from commodity alternatives. Certification grade under GECA protocols and FSC chain-of-cody documentation status constitute primary price differentiation drivers. Cost compression in standard-tier metal-framed desks is intensifying because engineered timber input volatility feeds through to landed costs. Suburban SME channels exhibit highest price sensitivity, while ASX-listed corporate tenants prioritize specification compliance over unit economics.
Supply Chain Analysis
Container freight rates from Southeast Asian engineered timber suppliers and powder-coated steel frame manufacturers in China dictate working capital requirements for domestic distributors. Australian fabrication draws from Malaysian plantation timber, Chinese steel components, and domestic upholstery textile finishing. Single-source vulnerability concentrates in height-adjustable desk actuator mechanisms sourced from Taiwanese electromechanical specialists. Distribution runs through national facilities management providers consolidating procurement authority previously fragmented across branch-level channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australian office furniture market operates as a supply-constrained environment where extended lead times for research-driven ergonomic portfolios prop pricing power for certified domestic fabricators.
For Market Incumbents: Cement pre-certified supplier relationships with ASX-listed corporate tenants ahead of Australian Building Codes Board guideline iterations. Anchor capacity addition in Victorian manufacturing corridors to compress delivery windows for Sydney and Melbourne technology sector fit-outs. Certification investment in psychological safety-compliant spatial planning capabilities defends against integrated workplace strategy consultancies displacing traditional dealer channels.
For New Entrants and Emerging Players: Launch via direct sales relationships targeting Queensland and Western Australia corporate headquarters whitespace, where ergonomic system penetration lags eastern seaboard concentration. Prioritize Brisbane and Perth developer-managed fit-out programs as the most penetrable geography. Differentiate through FSC chain-of-custody documentation bundled with rapid deployment timelines unavailable to multinational research-driven specialists.
For Investors and Strategic Acquirers: Re-rating potential sits with domestic mid-cap fabricators possessing GECA certification and established government procurement panel relationships given accelerating institutional sustainability mandates. Long-term viability hinges on vertical integration into engineered timber substrate supply to mitigate Southeast Asian import dependency. Monitor Australian Building Codes Board ergonomic guideline revision announcements as the signal to watch for specification authority consolidation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Acceleration Program | GECA and FSC pre-certification unlocks government and institutional procurement panel eligibility ahead of competitors. |
| Sensor-Integration Partnership | Embedded occupancy and posture sensor alliances convert static workstations into data-generating assets for ASX-listed tenants. |
| Queensland Distribution Expansion | Brisbane and Perth showroom presence captures whitespace in underpenetrated corporate headquarters markets. |
| Timber Substrate Backward Integration | Captive supply of engineered timber mitigates Malaysian plantation harvest cycle volatility and import cost exposure. |
| Psychological Safety Compliance Development | Work Health and Safety guideline anticipation positions portfolios for evolving spatial planning specification criteria. |
Methodological Framework
Document review covered Australian Bureau of Statistics construction activity data, ASX-listed corporate tenant disclosure filings, and Work Health and Safety regulatory guidance, complemented by interviews with facilities management procurement directors, commercial property developer fit-out managers, ergonomic seating R&D leads, and domestic furniture fabricator operations heads. Secondary validation drew from Australian Building Codes Board technical standards, GECA certification databases, and FSC chain-of-custody registry records. Bottom-up demand modeling triangulated against top-down market sizing from construction pipeline analysis.
Segmentation outputs across product type, material substrate, end user category, and distribution channel structure informed the analytical framework over the projection horizon. CAGRs were derived from regression analysis against commercial construction approvals and tenant improvement allowance trends. Height-adjustable desk specification velocity and sensor-integrated workstation penetration served as industry-specific forecast inputs.
Regulatory guideline revision timing, plantation timber harvest cycle disruption, and corporate tenant consolidation behavior are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Standing Desk Balance Boards Market
Office Furniture
Furniture and Home Furnishings Market
Office Furniture
Office Seat Cushion Market
Office Furniture
Brazil Office Furniture Market
Office Furniture
Luxury Office Furniture Market
Office Furniture
United States Furniture Market
Office Furniture
Home Office Spending Market
Office Furniture
Office Furniture Edgebands Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
Germany Office Furniture Market
Office Furniture
China Office Furniture Market
Office Furniture
Europe Home Office Furniture Market
Office Furniture
Desk Chairs Market
Office Furniture
Office Furniture Market