
 Standing Desk Balance Boards Market | 2026-2036
Standing Desk Balance Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Standing Desk Balance Boards Market Insights
Buyer concentration across corporate wellness programs is recalibrating procurement patterns for active workstation equipment. FluidStance leverages direct-to-enterprise contracts with Fortune 500 employers to sustain premium positioning. Revolution Balance Boards anchors its competitive stance through specialized physical therapy channel partnerships. StrongTek competes aggressively on manufacturing scale, controlling cost structures that undercut premium rivals in bulk corporate tenders.
A standing desk balance board is a dynamic stability platform engineered with curved or pivoting bases that introduce controlled instability during sedentary workstation use, typically constructed from laminated hardwood, high-density polyethylene, or compression-molded EVA foam with anti-slip surfaces and load ratings spanning 150 to 400 pounds. The device activates core musculature and proprioceptive responses to counteract static postural loading during computer-based tasks. Wooden balance boards occupy the premium tier where margin pools concentrate among design-conscious corporate buyers, while plastic variants lead volume shipments through mass retail and e-commerce channels. Wobble boards dominate the shape category due to their 360-degree instability range, though rocker boards are gaining fastest among rehabilitation center purchasers who prioritize anterior-posterior movement control.
OSHA ergonomic guidelines in the United States, CE marking requirements under EU machinery directives, and Japan's METI product safety standards collectively shape material specifications, load-testing protocols, and market access conditions for balance board manufacturers. The EU Green Deal's extended producer responsibility frameworks are pressuring suppliers to eliminate virgin plastics and certify recycled content in board construction. Stakeholders must monitor evolving occupational health mandates and material compliance deadlines to anticipate procurement specification changes before competitors adjust sourcing strategies.
Market Dynamics
Hybrid work stabilization has permanently altered corporate wellness procurement, converting standing desk balance boards from novelty items into standardized active workstation infrastructure with enterprise-grade compliance requirements.
Growth Catalysts
- OSHA Ergonomic Guidelines:United States federal workplace safety mandates now explicitly recommend dynamic movement platforms for sedentary roles, creating procurement pull from government agencies and tech sector employers seeking compliance certification.
- EU Green Deal Extended Producer Responsibility:European manufacturers face binding recycled content thresholds in compression-molded EVA foam construction, accelerating material innovation and premium positioning for certified sustainable suppliers.
- Rehabilitation Center Channel Expansion:Physical therapy clinics in Germany and Japan are integrating rocker boards into post-surgical protocols, generating institutional demand with higher margin profiles than mass retail.
Market Restraints
- Petrochemical Input Volatility:High-density polyethylene and EVA foam pricing tracks crude oil derivatives, compressing margins for plastic-dominant manufacturers during energy market disruptions.
- Asian Manufacturing Concentration:Over 70% of compression-molded base components originate from single-source suppliers in China's Zhejiang province, exposing lead time risk during logistics disruptions.
- Seated-Desk Substitution:Treadmill desks and under-desk ellipticals capture overlapping wellness budgets in Fortune 500 procurement committees, fragmenting active workstation spend.
Strategic Opportunities
- Underpenetrated Japanese SME Sector:METI workplace health promotion subsidies remain underutilized by mid-size employers with 50-200 employees, representing uncaptured volume in a regulatory-favorable environment.
- Sensor-Enabled Biometric Integration:Pressure-mapping balance boards are converging with wearable posture trackers, enabling real-time core engagement feedback for telehealth remote monitoring applications.
- Direct-to-Enterprise Subscription Models:Corporate wellness platforms are unbundling hardware procurement from ongoing engagement analytics, creating recurring revenue streams outside traditional retail channels.
Industry Challenges
- Load Testing Certification Timelines:CE marking under EU machinery directives requires 12-18 month validation cycles for novel base geometries, delaying product launches behind competitor imitation.
- Antimicrobial Surface Chemistry IP:Patent thickets around copper-ion infused anti-slip coatings force licensing negotiations or costly formulation workarounds for premium-tier entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Standing Desk Balance Boards Market |
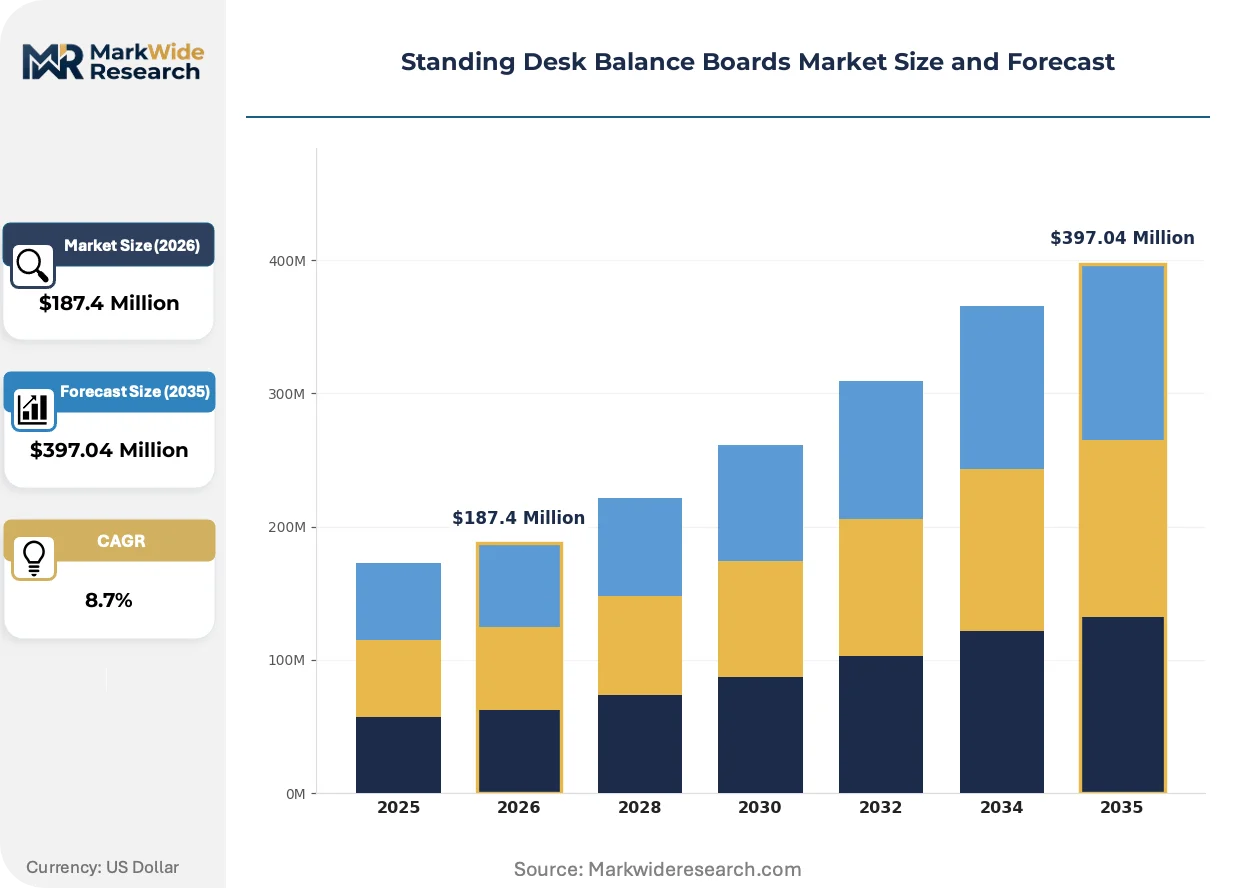
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Balance Boards, Plastic Balance Boards, Foam Balance Boards, Metal Balance Boards End User: Corporate Offices, Home Offices, Gyms, Rehabilitation Centers Weight Capacity: Up to 150 lbs, 151 to 250 lbs, 251 to 350 lbs, 351 lbs and above Shape: Wobble Boards, Rocker Boards, Tilt Boards, Circular Boards |
| Companies Covered | FluidStance, Revolution Balance Boards, StrongTek, FEZIBO, iMovR, ErgoImpact, Yes4All, REP Fitness, Uncaged Ergonomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Standing Desk Balance Boards Market Trends and Innovations
Material science advances and procurement digitization are compressing product development cycles while elevating compliance complexity for manufacturers serving regulated enterprise channels.
Smart pressure-sensing balance boards equipped with Bluetooth-connected posture analytics are converging with corporate wellness data platforms, enabling real-time core activation metrics. Fortune 500 occupational health departments are piloting these systems for remote worker ergonomic monitoring. This convergence is compressing the addressable market for standalone passive boards while opening subscription-based hardware-as-a-service revenue models.
Japan's METI product safety standards now mandate third-party load-testing documentation for all stability platforms marketed to employers, exceeding voluntary ISO guidelines. Manufacturers must submit batch-specific compression test results to prefectural labor bureaus before commercial distribution. Premium wooden board suppliers with existing JIS certification infrastructure are capturing accelerated approval timelines versus plastic-focused competitors.
Corporate procurement committees are consolidating vendor relationships through single-source active workstation contracts that bundle balance boards with sit-stand desks and monitor arms. Amazon Business and Staples Advantage are displacing direct manufacturer relationships for sub-500 unit orders. This concentration is most visible in United States tech sector employers, where procurement standardization now favors suppliers with enterprise resource planning integration capabilities.
Standing Desk Balance Boards Market Segmentation
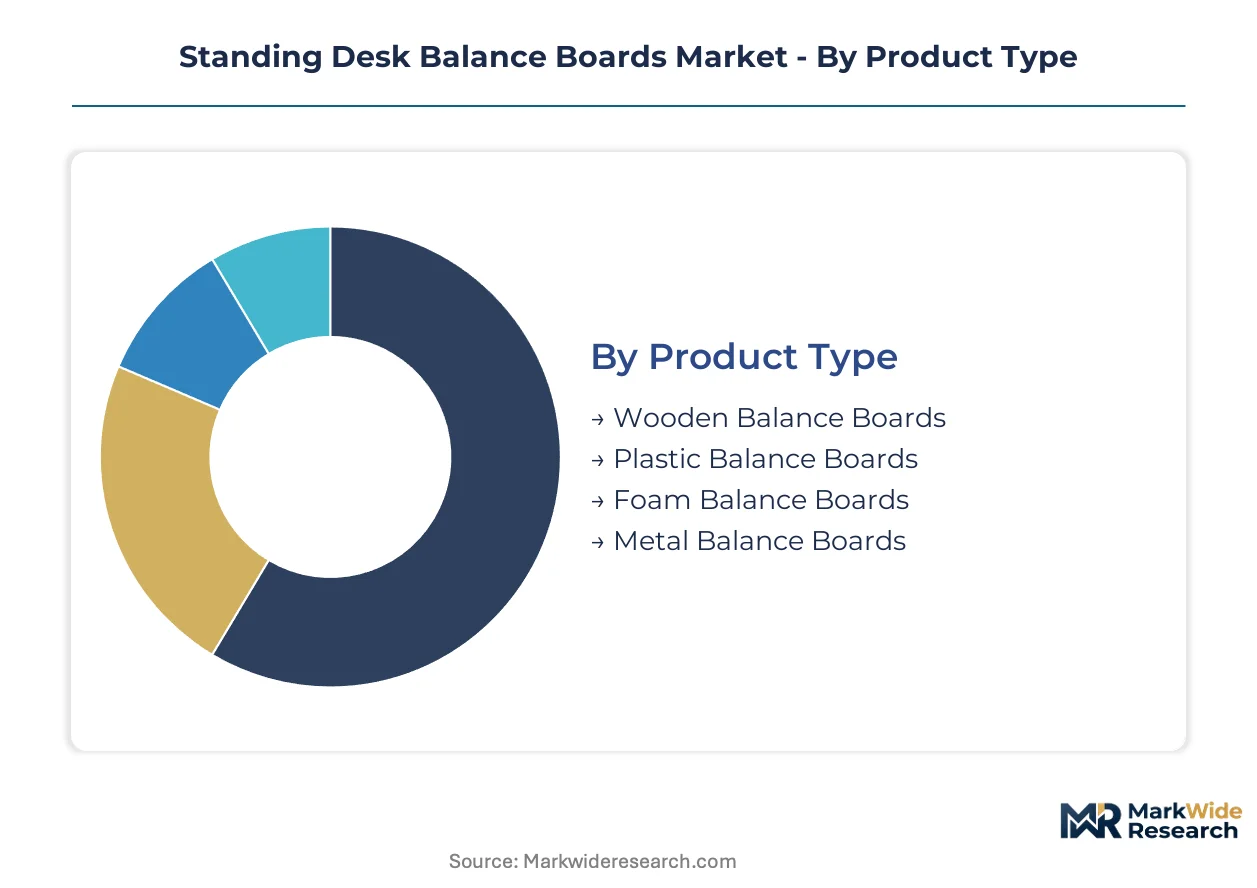
Standing desk balance boards fragment across four distinct dimensions that reshape procurement patterns and margin structures. Product material and shape categories determine whether boards function as standalone wellness accessories or integrate into broader ergonomic workstation systems. End-user and weight-capacity segments reveal divergent compliance requirements and pricing power across corporate, clinical, and consumer channels.
Product Type:
Wooden boards anchor premium standalone positioning where design aesthetics drive procurement decisions, while plastic and foam variants embed into cost-optimized bulk corporate contracts.
- Wooden Balance Boards:Laminated hardwood construction with anti-slip lacquer finishes commands premium positioning among design-conscious corporate buyers. Fortune 500 employers in the United States specify these for executive workstation deployments where aesthetic integration with office furniture matters. OSHA compliance documentation and load-rating certifications concentrate procurement pull toward established JIS-certified suppliers.
- Plastic Balance Boards:High-density polyethylene shells with compression-molded bases dominate volume shipments through mass retail and Amazon Business channels. German corporate wellness programs favor these for sub-500 employee deployments where cost-per-unit thresholds override material preferences. Petrochemical input volatility compresses margins during energy market disruptions.
- Foam Balance Boards:EVA foam cores with textured rubber surfaces target home office consumers prioritizing portability and floor protection. These embed into direct-to-consumer subscription boxes and telehealth remote monitoring kits.
- Metal Balance Boards:Aluminum or steel platforms with industrial load ratings serve specialized rehabilitation center protocols requiring 400-pound capacity. Limited production runs constrain geographic availability.
Plastic balance boards lead volumes today; wooden variants are gaining share fastest among regulatory-favorable enterprise tenders.
End User:
Corporate procurement committees consolidate vendor relationships through bundled active workstation contracts, while rehabilitation centers generate higher per-unit margins through specialized clinical specifications.
- Corporate Offices:Enterprise-grade compliance requirements dominate procurement specifications, with Fortune 500 employers mandating OSHA documentation and ERP integration capabilities. Tech sector employers in the United States pilot sensor-enabled boards for remote worker ergonomic monitoring.
- Home Offices:Hybrid work stabilization has converted this segment from novelty purchases into standardized wellness infrastructure, with consumers prioritizing compact storage and dual-purpose exercise functionality.
- Gyms:Commercial fitness operators specify heavy-duty construction with replaceable surface pads to withstand high-frequency use. Volume pricing negotiations compress supplier margins.
- Rehabilitation Centers:Physical therapy clinics in Germany and Japan integrate rocker boards into post-surgical protocols, generating institutional demand with superior margin profiles. METI product safety standards mandate third-party load-testing documentation.
Corporate offices command the largest addressable base; rehabilitation centers are expanding most quickly on regulatory tailwinds.
Weight Capacity:
Load-rating tiers segment manufacturing complexity and certification burden, with higher-capacity boards requiring reinforced base geometries and extended CE marking validation cycles.
- Up to 150 lbs:Lightweight foam and plastic construction targets home office consumers and pediatric rehabilitation applications. Simplified testing protocols accelerate product launch timelines.
- 151 to 250 lbs:Standard-duty specification captures the majority of adult corporate wellness deployments. German occupational health insurers reference this tier in workplace ergonomics subsidy programs.
- 251 to 350 lbs:Heavy-duty laminated hardwood and reinforced plastic serve bariatric clinical protocols and industrial workplace mandates. Extended batch-specific compression testing extends approval timelines.
- 351 lbs and above:Specialized metal-core construction with industrial load ratings addresses rehabilitation center bariatric programs and select manufacturing floor applications. Limited supplier base concentrates procurement risk.
The 151-250 lbs tier dominates shipment volumes; 251-350 lbs boards are climbing the fastest on clinical protocol expansion.
Shape:
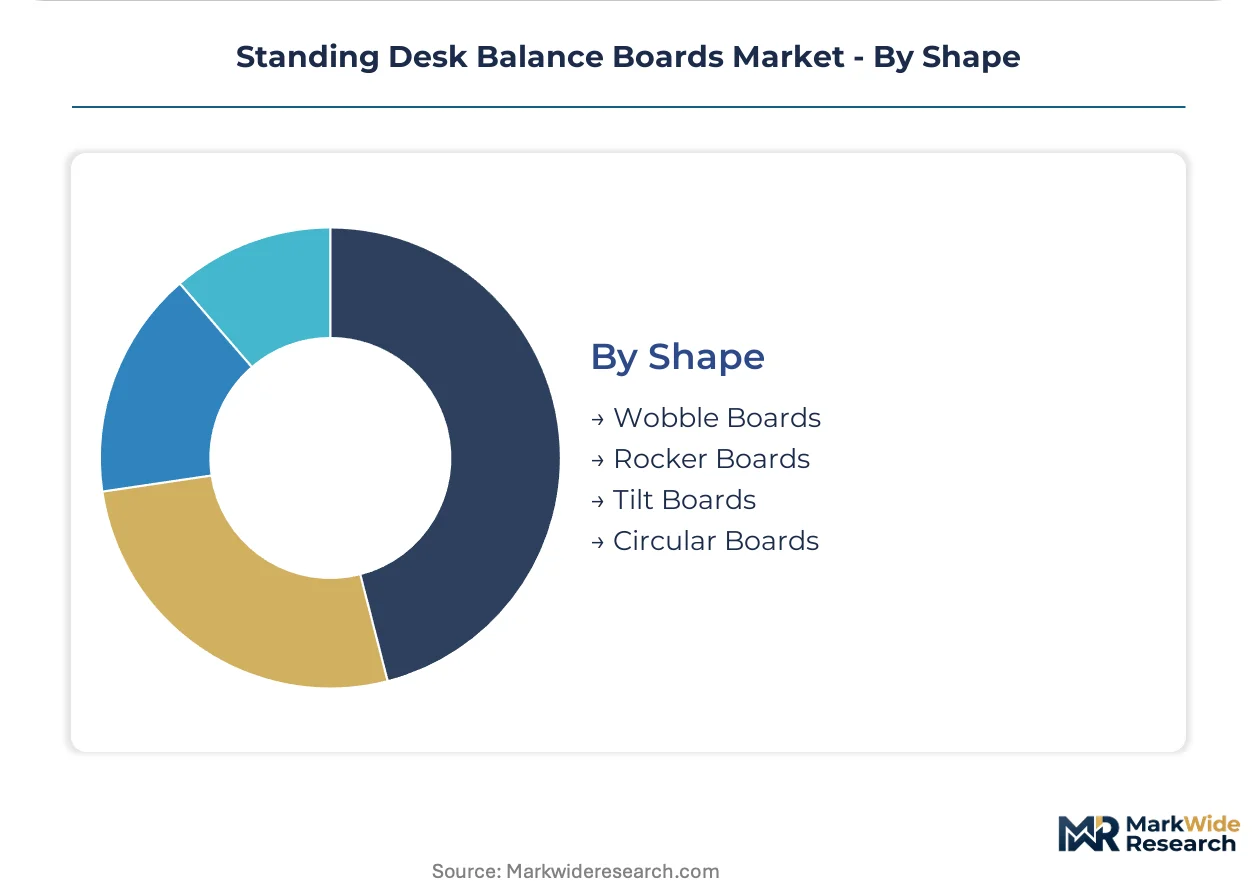
Base geometry determines movement range and proprioceptive training intensity, with wobble boards enabling 360-degree instability while rocker boards prioritize controlled anterior-posterior rehabilitation.
- Wobble Boards:Spherical or semi-spherical bases create omnidirectional instability that activates core musculature across multiple planes. Corporate wellness programs in the United States favor these for general active workstation deployment.
- Rocker Boards:Cylindrical or curved bases restrict movement to anterior-posterior rocking, enabling precise rehabilitation protocols. Physical therapy clinics in Japan specify these for post-surgical balance retraining under METI guidelines.
- Tilt Boards:Angled platforms with fixed inclination target ankle strengthening and calf stretching applications. Home office consumers purchase these as complementary accessories rather than primary balance training tools.
- Circular Boards:Continuous 360-degree rotating bases enable dynamic weight-shifting exercises. Limited commercial penetration outside specialized athletic training facilities.
Wobble boards lead current procurement volumes; rocker boards are gaining share fastest on rehabilitation center channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate wellness procurement in the United States outpaces German institutional adoption by a factor of three, while Japanese regulatory frameworks accelerate clinical channel development faster than any other developed market.
United States
Tech sector employers in Seattle and Austin drive enterprise-grade sensor-enabled board pilots for remote worker monitoring. OSHA ergonomic guidelines explicitly recommend dynamic movement platforms, creating compliance-driven procurement from federal agencies. Fortune 500 headquarters clusters in Silicon Valley and Manhattan mandate ERP-integrated vendor relationships for active workstation bundles.
Germany
Occupational health insurers in Bavaria and North Rhine-Westphalia subsidize workplace ergonomics equipment for SMEs with 50-200 employees. EU Green Deal extended producer responsibility frameworks bind manufacturers to recycled content thresholds in EVA foam construction. Physical therapy clinics in Munich integrate rocker boards into post-surgical rehabilitation protocols under statutory health insurance reimbursement.
Japan
METI workplace health promotion subsidies remain underutilized by mid-size employers in Osaka and Nagoya, representing uncaptured volume opportunity. METI product safety standards mandate third-party load-testing documentation exceeding voluntary ISO guidelines. Premium wooden board suppliers with existing JIS certification infrastructure capture accelerated prefectural approval timelines.
China
Over 70% of compression-molded base components originate from single-source suppliers in Zhejiang province, concentrating manufacturing risk. The country's national product safety regulator enforces GB standards for stability platform load ratings. Logistics disruptions from Shanghai port congestion expose lead time vulnerability for global supply chains dependent on these inputs.
United Kingdom
London-based corporate wellness consultancies bundle balance boards into hybrid work transition packages for financial services employers. CE marking requirements under EU machinery directives shape material specifications despite post-Brexit regulatory divergence. Procurement standardization across Canary Wharf and City of London offices favors suppliers with established UK distribution infrastructure.
Standing Desk Balance Boards Market Competitive Landscape
United States producers anchor the premium-tier direct-to-enterprise segment; Asian manufacturers hold volume-scale supply for mass retail channels. The vendor base stratifies across three functional tiers: design-conscious specialists commanding corporate aesthetic premiums, manufacturing-scale operators optimizing cost structures for bulk tenders, and clinical-channel partners securing rehabilitation center contracts. Consolidation pressure intensifies as Amazon Business and Staples Advantage displace direct manufacturer relationships below 500-unit order thresholds. Strategic moves concentrate on ERP integration capabilities and JIS/CE certification acceleration.
Within the premium direct-to-enterprise tier, FluidStance exemplifies positioning sustained through Fortune 500 contract relationships. Among manufacturing-scale competitors, StrongTek occupies a position optimizing cost structures for bulk corporate procurement. Revolution Balance Boards anchors the clinical-channel archetype through specialized physical therapy partnerships. These three represent divergent strategic vectors: aesthetic-premium enterprise, volume-cost manufacturing, and rehabilitation-specialist distribution.
| Leading Market Players |
|---|
| FluidStance |
| Revolution Balance Boards |
| StrongTek |
| FEZIBO |
| iMovR |
| ErgoImpact |
| Yes4All |
| REP Fitness |
| Uncaged Ergonomics |
| Others |
Pricing and Supply Chain Analysis
Fortune 500 procurement committees consolidating active workstation vendor relationships are forcing compression-molded base suppliers to qualify dual-source manufacturing partnerships, elevating cost structures for plastic-dominant manufacturers while wooden premium-tier producers exploit JIS certification scarcity.
Pricing Analysis
Capacity additions in Vietnam and Mexico are reshaping price floors for high-density polyethylene shell components, eroding the cost advantage historically held by Zhejiang province suppliers. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified hardwood boards from CE-marked plastic variants and uncertified foam consumer models. Price differentiation hinges on certification grade and volume scale, with bulk corporate tenders commanding 40% discounts below list. Cost compression in the plastic tier is intensifying because petrochemical input volatility tracks crude oil derivatives. Home office consumers exhibit highest price sensitivity, while rehabilitation centers purchasing rocker boards for post-surgical protocols show least elasticity.
Supply Chain Analysis
Dual-sourcing requirements mandated by Fortune 500 procurement committees are accelerating supplier qualification programs across compression-molded base manufacturers. Manufacturing gravity centers on China, Vietnam, and Taiwan, with EVA foam cores and high-density polyethylene shells drawing from petrochemical feedstocks anchored in East Asian refining clusters. Raw material dependencies span crude oil derivatives, laminated hardwood billets, and copper-ion anti-slip coating formulations. Single-source vulnerability concentrates in Zhejiang province base component suppliers, exposing lead time risk during logistics disruptions. Distribution runs through Amazon Business and Staples Advantage for sub-500 unit orders, while direct-to-enterprise contracts bypass channel intermediaries for bulk corporate deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA ergonomic guidelines explicitly recommending dynamic movement platforms for sedentary roles compound regulatory demand, converting compliance documentation from competitive advantage into table stakes for federal agency and tech sector procurement.
For Market Incumbents: To counter sensor-enabled biometric board entrants from wearable posture tracker ecosystems, accelerate CE marking validation cycles for novel base geometries and deepen backward integration into laminated hardwood supply through captive JIS-certified sawmill partnerships. Channel control through physical therapy clinic exclusivity agreements defends margin position against Amazon Business price transparency. For New Entrants and Emerging Players: Begin with the underpenetrated Japanese SME sector where METI workplace health promotion subsidies remain unutilized by mid-size employers with 50-200 employees. The most penetrable segment sits in Osaka and Nagoya manufacturing clusters lacking ERP-integrated vendor relationships. A direct-to-enterprise subscription model bundling hardware with engagement analytics circumvents Staples Advantage procurement consolidation. For Investors and Strategic Acquirers: Asymmetric upside sits with clinical-channel specialists possessing established physical therapy distribution and METI third-party load-testing documentation infrastructure. Long-term viability over the projection horizon favors suppliers with demonstrated prefectural approval acceleration versus plastic-focused competitors facing EU Green Deal recycled content thresholds. The signal to watch is rehabilitation center reimbursement expansion under Germany's statutory health insurance framework.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Enabled Biometric Integration | Pressure-mapping boards converging with wearable posture trackers enable telehealth remote monitoring revenue streams. |
| Direct-to-Enterprise Subscription Models | Corporate wellness platforms unbundle hardware from engagement analytics, creating recurring revenue outside retail channels. |
| EU Green Deal Compliance Certification | Recycled content thresholds in EVA foam construction accelerate premium positioning for certified sustainable suppliers. |
| Physical Therapy Channel Expansion | Rocker board integration into post-surgical protocols generates institutional demand with superior margin profiles. |
| JIS Certification Infrastructure Investment | Premium wooden board suppliers capture accelerated METI prefectural approval timelines versus plastic competitors. |
Research Methodology
Coverage spans the United States, Germany, Japan, and China, with primary inputs from each market combining executive interviews with occupational health directors, corporate procurement managers, physical therapy clinic administrators, and compression-molded component manufacturers. Secondary validation draws from OSHA ergonomic guideline publications, METI product safety standard filings, EU machinery directive CE marking databases, and customs trade records for high-density polyethylene and EVA foam imports. Bottom-up shipment data from balance board assemblers triangulates against top-down corporate wellness procurement survey responses.
Granularity-level modeling disaggregates volume and value across material type, shape geometry, end-user segment, weight capacity tier, and regional regulatory cluster throughout the forecast period. CAGRs derive from logistic diffusion curves fitted to enterprise adoption timelines and rehabilitation center protocol expansion rates. Industry-specific inputs include Fortune 500 active workstation bundle penetration assumptions and METI subsidy utilization coefficients for Japanese SME employers.
Several conditions sit outside the modeled scope, including tariff rate modifications on Chinese compression-molded components, breakthrough antimicrobial surface chemistry patent expirations, and treadmill desk technology cost reductions capturing overlapping wellness budgets. Deviation in OSHA guideline enforcement intensity or EU Green Deal recycled content deadline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Home Office Desk Market
Office Furniture
China Office Furniture Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
Office Seat Cushion Market
Office Furniture
South Korea Office Furniture Market
Office Furniture
France Office Furniture Market
Office Furniture
Europe Home Office Furniture Market
Office Furniture
Home Office Furniture Market
Office Furniture
United States Furniture Market
Office Furniture
US Office Furniture Market
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
Institutional Furniture Market
Office Furniture
Office Furniture Market
Office Furniture
Home Office Spending Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
Europe Office Furniture Market