
 Desk Chairs Market | 2026-2036
Desk Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Desk Chairs Market Analysis
Aftermarket service revenue is fragmenting as manufacturers compete to capture recurring margin pools beyond initial equipment sales. Herman Miller leverages its dealer network to sustain premium positioning in ergonomic configurations. Steelcase anchors North American corporate contracts through direct sales teams and specification relationships. Okamura Corporation dominates Asian commercial projects with localized production and JIS-certified engineering.
Desk chairs are seating devices engineered for sustained use at workstations, typically incorporating adjustable seat height, lumbar support mechanisms, and swivel bases constructed from steel, aluminum, or reinforced polymers to distribute user weight across eight-hour duty cycles. Ergonomic and mesh categories lead replacement cycles in corporate offices, where employers prioritize musculoskeletal risk reduction and thermal comfort during extended sitting. Gaming and executive leather segments occupy distinct margin pools, with the former extracting value from aesthetic customization and the latter from premium hide sourcing and hand-finished upholstery.
FDA oversight of medical-grade seating and EPA guidelines on volatile organic compound emissions from foam and adhesives shape material selection and factory certification requirements in the United States. The EU Green Deal and REACH chemical restrictions compel European manufacturers to phase out certain flame retardants and document supply chain chemistry. Stakeholders must monitor evolving ergonomics standards from ISO and national workplace regulators to anticipate specification changes before contract renewal cycles.
Market Dynamics
Hybrid work stabilization is forcing a wholesale replacement of aging corporate seating inventories, with employers now specifying eight-hour ergonomic certification as a baseline procurement threshold rather than a premium upgrade.
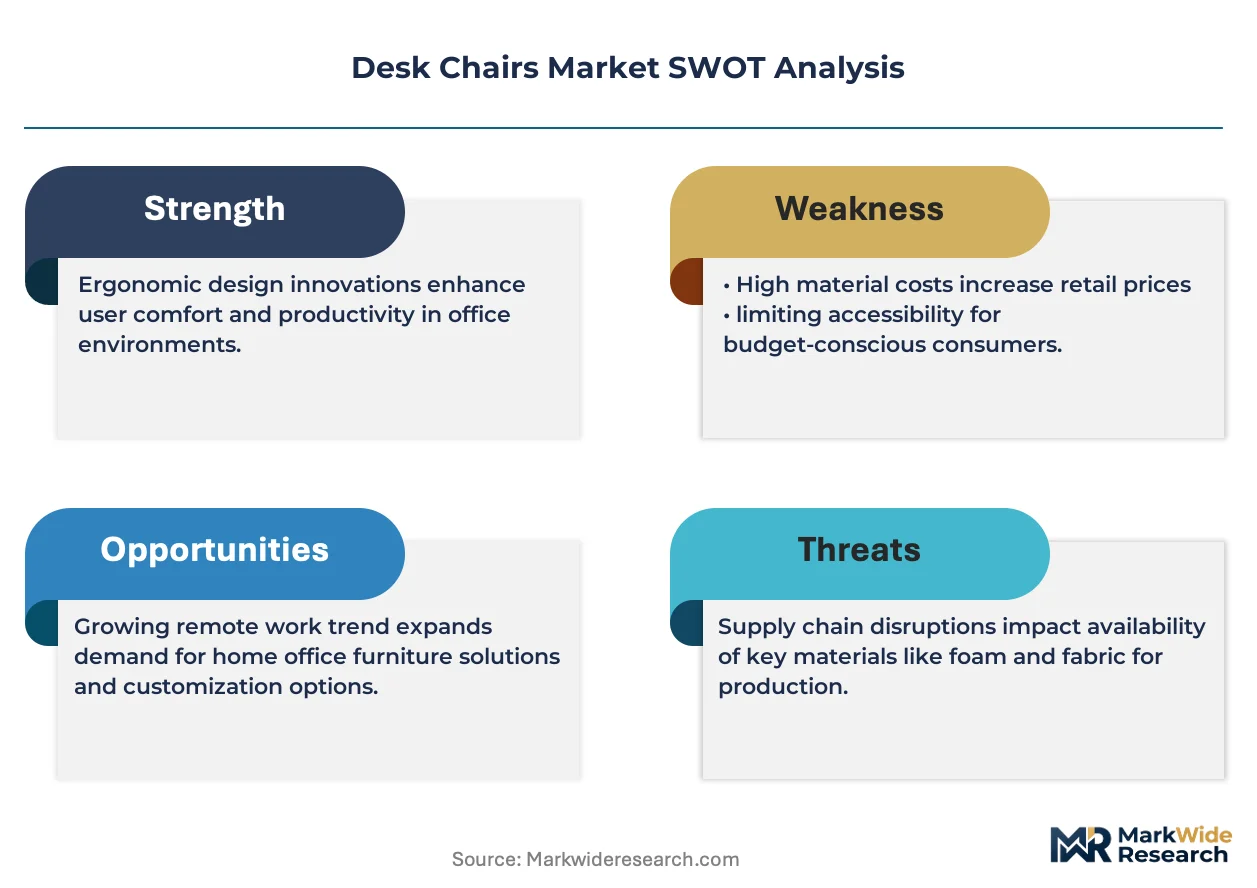
Growth Catalysts
- California Title 24 energy standards:Building codes in the United States now mandate thermal comfort performance in commercial interiors, accelerating specification of mesh-back and breathable foam configurations that reduce HVAC load.
- Corporate musculoskeletal risk programs:Human resources departments in Germany and Japan are deploying ISO 9241-5 certified seating as preventive infrastructure against repetitive strain claims and lost productivity.
- Mesh textile engineering:Advances in tension-mapped polymer weaving enable lumbar support without mechanical complexity, shortening production cycles and reducing component count for mid-market manufacturers.
Market Restraints
- Aluminum and steel price volatility:Base metal cost swings compress margin predictability for frame producers, particularly those without captive foundry operations or long-term commodity hedging.
- Polyurethane foam supply concentration:Three chemical conglomerates dominate global TDI and MDI production, exposing chair manufacturers to input rationing during petrochemical plant maintenance cycles.
- REACH chemical documentation burdens:European manufacturers face escalating compliance costs to trace and disclose flame retardant chemistry through multi-tier supply chains.
Strategic Opportunities
- India commercial real estate buildout:Bangalore and Hyderabad IT corridor expansion creates first-time specification demand for ergonomic task seating in domestic outsourcing operations.
- Refurbishment and remanufacturing channels:Circular economy mandates in the European Union incentivize take-back programs and component-level reuse, opening recurring revenue streams beyond initial equipment sales.
- Sensor-embedded posture monitoring:Integration of pressure mapping and accelerometry into seat pans enables real-time ergonomic coaching, differentiating premium offerings for knowledge-worker employers.
Industry Challenges
- ISO 9241-5 certification timeline:Third-party ergonomic validation requires six to nine months of anthropometric testing, delaying product launches and compressing effective sales windows.
- Legacy fleet incompatibility:New ergonomic specifications often conflict with existing workstation dimensions and cable management infrastructure, complicating large-scale replacement rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desk Chairs Market |
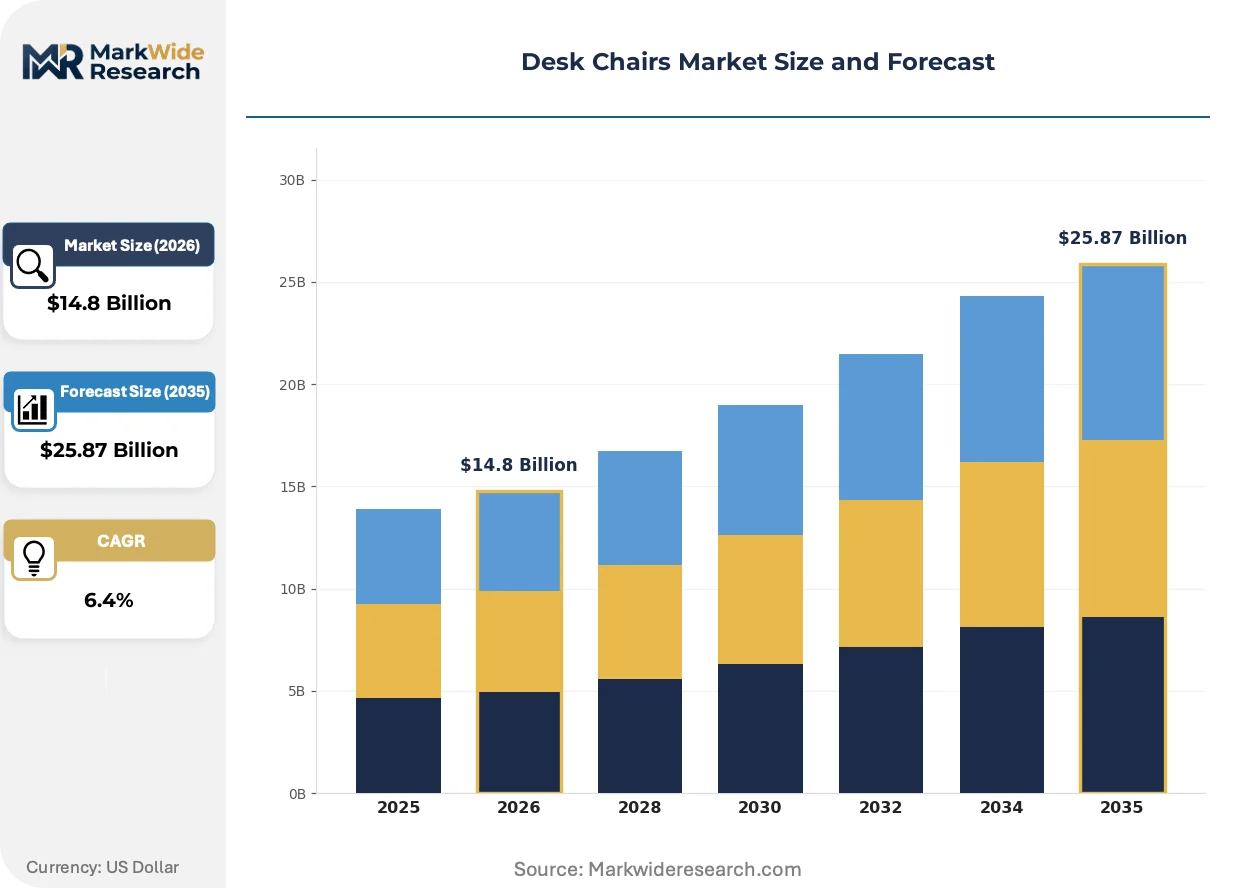
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ergonomic, Executive, Task, Gaming Material: Mesh, Leather, Fabric, Plastic End User: Corporate Offices, Home Offices, Educational Institutions, Co-working Spaces Feature: Adjustable Height, Lumbar Support, Armrests, Swivel |
| Companies Covered | Herman Miller, Steelcase, Humanscale, Haworth, Knoll, IKEA, HNI Corporation, Okamura Corporation, Vitra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desk Chairs Market Emerging Trajectories
Seating design is converging with wellness technology and circular material systems, compressing traditional product lifecycles while elevating certification requirements as competitive differentiators.
Dynamic lumbar mechanisms using elastomer torsion instead of mechanical linkages are collapsing the cost gap between entry-level and ergonomic-mid-tier seating. Regional banking and insurance headquarters in the United States are specifying these configurations for entire floorplates. The technology is collapsing aftermarket service revenue models by eliminating adjustment failure modes.
REACH flame retardant phase-outs are compelling European manufacturers to migrate from halogenated additives to phosphorus-based chemistry. Reformulation costs are being passed through specification contracts with extended lead times. Task seating for public administration tenders in France and Germany faces the steepest compliance burden.
Direct-to-employer configuration tools are displacing traditional dealer specification relationships for standardized office deployments. Facility managers in Japan are using web-based platforms to specify certified seating without intermediary design consultation. This channel compression is most visible in technology sector expansions where procurement cycles have shortened from quarters to weeks.
Desk Chairs Market Segmentation
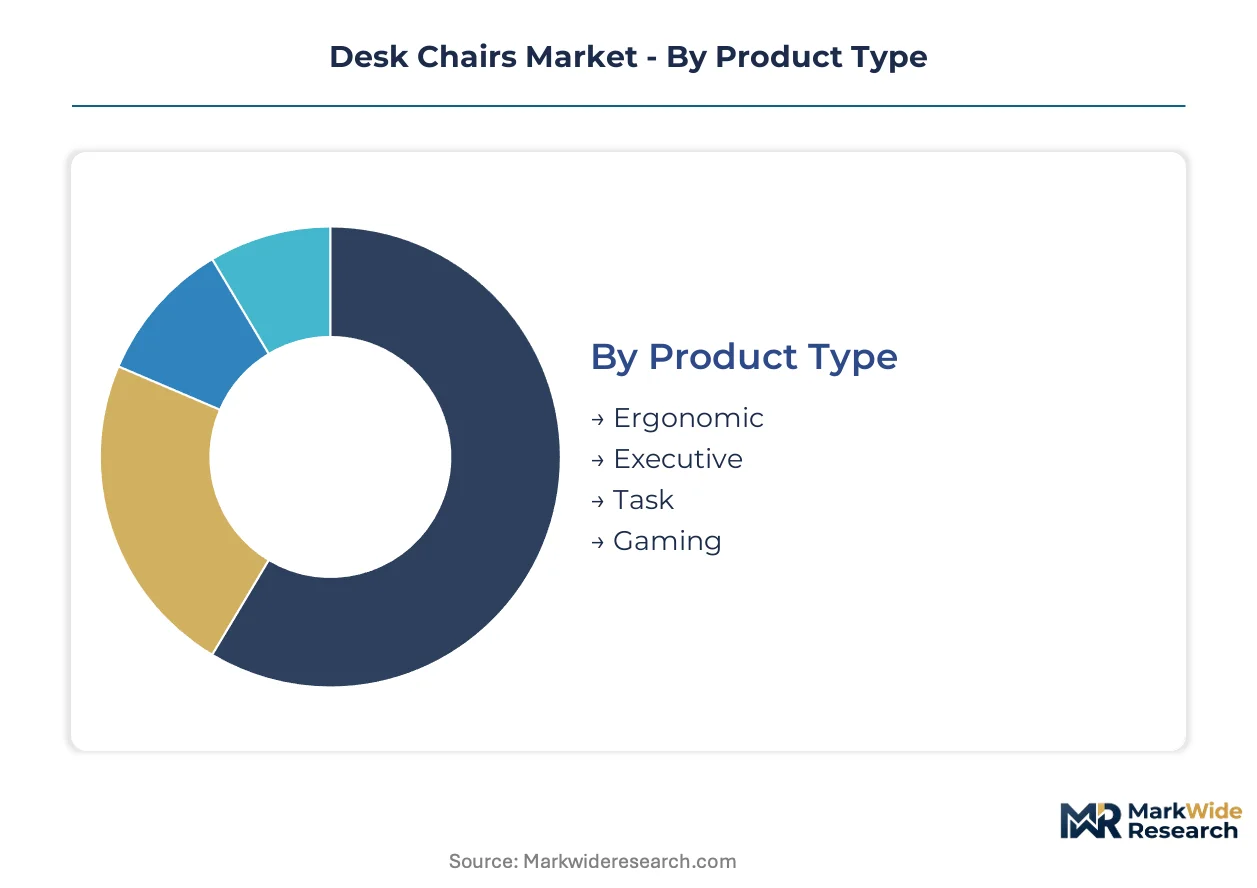
Desk chair procurement decisions split across functional specifications, material durability, and workplace deployment models. Manufacturers configure production lines around these segment boundaries to capture margin pools tied to certification requirements and replacement cycle timing.
Product Type:
Mature ergonomic and task categories dominate commercial procurement volumes, while executive and gaming segments operate on distinct margin architectures shaped by aesthetic customization and performance positioning.
- Ergonomic:Engineered with ISO 9241-5 certified anthropometric adjustability including dynamic lumbar mechanisms and tension-mapped mesh. Corporate offices in the United States and Germany specify these for eight-hour duty cycles to reduce musculoskeletal claims and HVAC load through breathable configurations.
- Task:Standardized seating with fixed or limited adjustability, constructed from reinforced polymers and steel frames for high-density floorplate deployment. Demand concentrates in co-working spaces and educational institutions where procurement prioritizes unit cost over individual customization, though California Title 24 thermal standards are elevating baseline specifications.
- Executive:Premium hide upholstery with hand-finished detailing and high-back silhouettes. Law firms and financial services headquarters in Japan maintain specification demand for leather configurations signaling organizational hierarchy.
- Gaming:Aesthetic-forward designs with integrated RGB compatibility and racing-inspired ergonomics. The segment extracts value from customization ecosystems and streaming-visible branding rather than workplace certification standards.
Ergonomic handles the majority of throughput; gaming is the fastest mover on share.
Material:
Cost tier differentiation separates breathable performance textiles from premium natural materials, with regulatory chemistry constraints reshaping competitive positioning in European supply chains.
- Mesh:Tension-mapped polymer weaving enables lumbar support without mechanical complexity, shortening production cycles. REACH flame retardant phase-outs in the European Union are accelerating phosphorus-based chemistry migration for mesh textiles in public administration tenders.
- Leather:Full-grain and corrected-grain hides with hand-finished upholstery commanding premium positioning. Executive segments in Japan and Germany sustain demand despite extended lead times tied to hide sourcing and finishing capacity constraints.
- Fabric:Woven synthetic and natural fiber blends offering color customization at mid-market price points. Educational institutions specify fabric for durability against staining and abrasion in high-turnover seating inventories.
- Plastic:Injection-molded polypropylene and reinforced polymer shells for entry-level task seating. Home office demand in India concentrates here as first-time ergonomic buyers prioritize cost accessibility over adjustability range.
Mesh captures the steepest expansion trajectory as thermal performance standards tighten; plastic maintains volume leadership in emerging market penetration.
End User:
Application context determines specification rigor, with corporate procurement operating on certified preventive infrastructure logic and home office demand responding to direct-to-employer configuration tools.
- Corporate Offices:Large-scale ergonomic certification deployments with ISO 9241-5 validation and extended warranty structures. Hybrid work stabilization is forcing wholesale replacement of aging inventories across United States banking and insurance headquarters.
- Home Offices:Individual purchasing decisions increasingly channeled through web-based configuration platforms. Japan's technology sector procurement cycles have compressed from quarters to weeks through direct-to-employer tools bypassing traditional dealer relationships.
- Educational Institutions:High-density seating with institutional durability requirements and standardized dimensions. Budget constraints favor task-grade plastic and fabric configurations over ergonomic adjustability.
- Co-working Spaces:Rapid-turnover seating with aesthetic consistency across location networks. Operators prioritize mesh-back standardization for thermal comfort in shared HVAC environments.
Corporate offices command the dominant specification volume; co-working spaces are climbing the fastest as flexible workplace models expand.
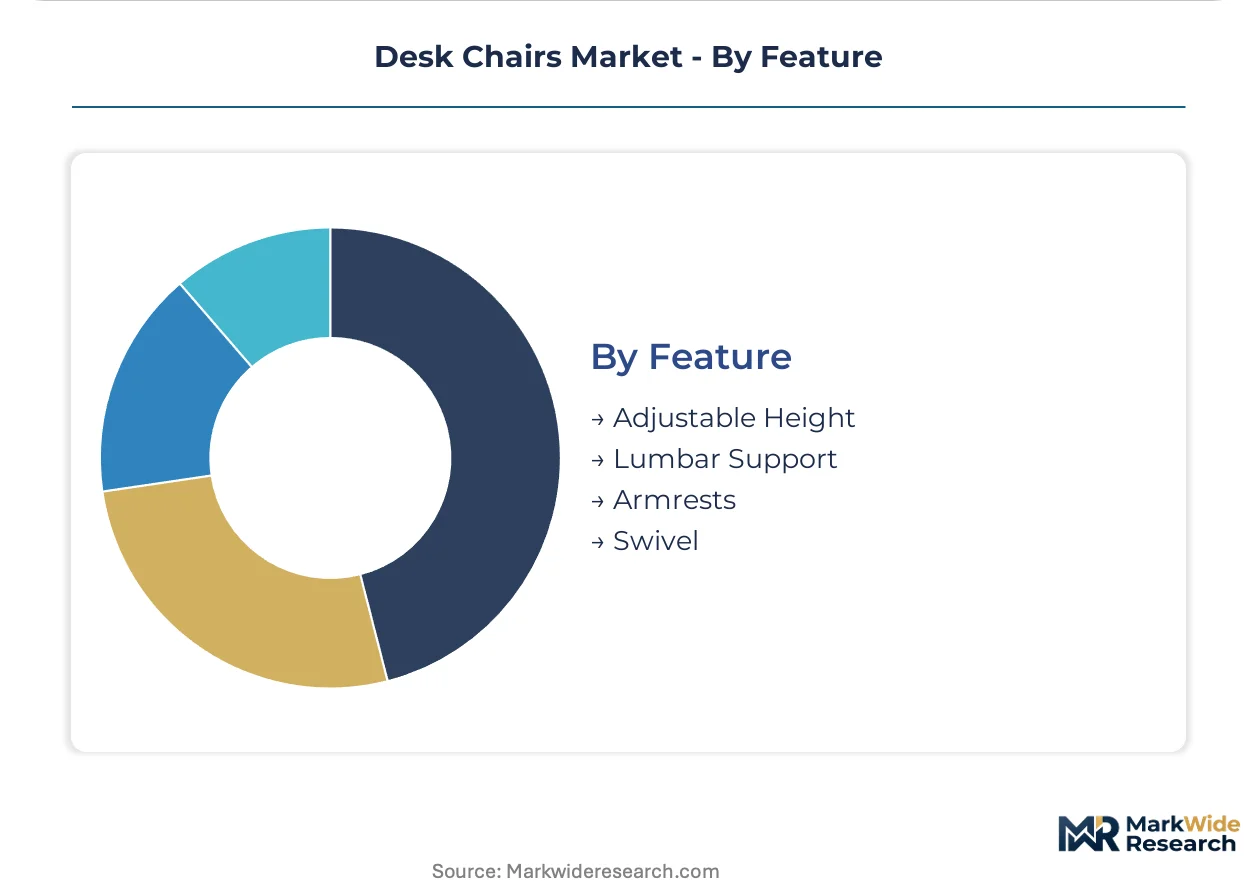
Feature:
Customer type segmentation separates preventive infrastructure buyers seeking certified adjustability from cost-optimized purchasers accepting baseline mobility functions.
- Adjustable Height:Pneumatic cylinder mechanisms enabling seated position range across user percentiles. Universal specification baseline across all end-user categories, with gas lift quality differentiating warranty terms.
- Lumbar Support:Dynamic elastomer torsion and mechanical linkage systems for lower back load distribution. Corporate musculoskeletal risk programs in Germany deploy ISO-certified configurations as preventive infrastructure.
- Armrests:Fixed, height-adjustable, and multi-axis configurations affecting shoulder girdle positioning. Executive and ergonomic segments specify 4D adjustability; task and educational deployments often omit to reduce unit cost.
- Swivel:Steel and aluminum base constructions with caster mobility for workstation reach. Standard across commercial categories with base material selection driven by floor surface compatibility and load rating requirements.
Adjustable height and swivel constitute universal specification; lumbar support is gaining share fastest as eight-hour certification becomes baseline procurement threshold.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate buyers in the United States and Germany absorb premium pricing for certified ergonomic configurations, while procurement in India and co-working operators worldwide prioritize unit cost over adjustability range.
United States
Banking and insurance headquarters in New York and Chicago are replacing aging seating inventories with eight-hour ergonomic certification as baseline procurement. California's Title 24 building energy standards mandate thermal comfort performance, accelerating mesh-back specifications that reduce HVAC load. The Pacific Northwest technology corridor drives demand for sensor-embedded posture monitoring in premium task seating.
Germany
Corporate musculoskeletal risk programs deploy ISO 9241-5 certified seating as preventive infrastructure against repetitive strain claims. REACH chemical documentation requirements compel manufacturers to trace flame retardant chemistry through multi-tier supply chains. The Rhine-Ruhr industrial region concentrates specification demand from regional banking headquarters and public administration tenders.
Japan
Technology sector procurement cycles have compressed from quarters to weeks through direct-to-employer web-based configuration platforms. METI workplace safety guidelines elevate JIS-certified engineering requirements for commercial projects. The Kanto region around Tokyo anchors demand from financial services headquarters maintaining leather executive specifications.
India
Bangalore and Hyderabad IT corridor expansion creates first-time specification demand for ergonomic task seating in domestic outsourcing operations. BIS standards for furniture safety shape import compliance for multinational facility rollouts. Home office demand concentrates in entry-level plastic configurations as first-time ergonomic buyers prioritize cost accessibility.
United Kingdom
London financial services and professional services firms sustain demand for premium executive configurations alongside certified ergonomic deployments. CSRD circular economy disclosure requirements incentivize take-back programs and component-level reuse. The Southeast England corridor concentrates co-working space expansion driving mesh-back standardization for thermal comfort in shared HVAC environments.
Desk Chairs Market Vendor Landscape
Capability concentration sits with ergonomic specialists commanding premium positioning through certification relationships; scale advantage sits with diversified furniture conglomerates serving high-volume contract channels. The vendor base separates into three strategic archetypes: heritage ergonomic specialists with anthropometric research legacies, diversified workplace furniture conglomerates with direct sales infrastructure, and value-oriented retailers with standardized configuration platforms. Competitive moves center on circular economy service expansion and sensor-embedded wellness technology integration.
Among heritage ergonomic specialists, Herman Miller and Humanscale exemplify premium-tier positioning through dealer network relationships and specification consulting. Steelcase anchors the diversified conglomerate archetype with North American corporate contract penetration. Okamura Corporation represents the Asia-Pacific engineering specialist archetype, occupying a position in JIS-certified commercial project delivery.
| Leading Market Players |
|---|
| Herman Miller |
| Steelcase |
| Humanscale |
| Haworth |
| Knoll |
| IKEA |
| HNI Corporation |
| Okamura Corporation |
| Vitra |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container freight corridors linking Chinese component hubs to West Coast distribution centers transmit cost volatility directly into landed pricing for North American contract buyers, amplifying margin compression for manufacturers without captive foam production or long-term steel hedging programs while simultaneously widening spreads between premium ergonomic configurations and entry-level task seating.
Pricing Analysis
Aftermarket service revenue from extended warranty programs and component replacement contracts drives lifetime value capture for established manufacturers, with three-tier pricing structure across premium, standard, and economy levels anchored by ISO 9241-5 certification grade and pneumatic cylinder quality tier. Price differentiation rests on dynamic lumbar mechanism complexity and mesh textile engineering sophistication, with corporate procurement in Germany and Japan absorbing premium positioning for eight-hour certified configurations while Indian home office buyers concentrate in plastic-shell economy tiers. Cost compression in mid-market mesh configurations is intensifying because tension-mapped polymer weaving advances shorten production cycles, though aluminum base casting volatility constrains margin predictability for frame-dependent producers.
Supply Chain Analysis
Polyurethane foam feedstock draws from concentrated TDI and MDI production in China, Germany, and the United States, with three chemical conglomerates controlling global isocyanate supply and exposing chair manufacturers to input rationing during petrochemical maintenance cycles. Steel and aluminum frame sourcing centers on Taiwanese and South Korean mill operations, while mesh textile weaving concentrates in Chinese and Vietnamese polymer facilities. Single-source vulnerability in foam chemistry creates procurement risk for European manufacturers facing REACH documentation deadlines. Distribution runs through dealer specification networks for corporate contract channels and direct-to-employer web platforms for standardized office deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent seating manufacturers face sustained substitution pressure from sensor-embedded wellness technology providers and remanufacturing-as-a-service operators, requiring defensive repositioning around circular economy infrastructure and real-time ergonomic data integration to preserve contract renewal rates.
For Market Incumbents: Entrench specification relationships through JIS and ISO certification investments that extend beyond product sales into posture monitoring data services and component-level refurbishment programs. Steelcase and Herman Miller dealer networks represent defensible control points against direct-to-employer platform disintermediation. Backward integration into mesh textile weaving and aluminum die-casting reduces exposure to commodity volatility while supporting premium pricing for eight-hour certified configurations.
For New Entrants and Emerging Players: Mid-market commercial buildings in India's Bangalore and Hyderabad IT corridors represent the most penetrable entry point, with first-time ergonomic specification demand outpacing established supply infrastructure and BIS compliance creating manageable barriers versus saturated North American contract channels. Sensor-embedded seat pan technology for knowledge-worker employers offers differentiation without requiring heritage anthropometric research capabilities. Web-based configuration platforms bypassing traditional dealer relationships enable rapid procurement cycle compression matching Japan's technology sector velocity.
For Investors and Strategic Acquirers: Regional remanufacturing specialists with established take-back logistics and component refurbishment capabilities present acquisition targets positioned for circular economy mandate acceleration under EU CSRD disclosure requirements. Long-term viability hinges on recurring revenue transition from equipment sales to service and data monetization models. The signal to watch is corporate procurement contract language shifting from capital expenditure line items to per-seat subscription pricing with embedded wellness monitoring.
| Strategic Initiative | Industry Significance |
|---|---|
| Circular Economy Service Expansion | EU CSRD mandates accelerate take-back program revenue streams beyond initial equipment sales. |
| Sensor-Embedded Wellness Integration | Pressure mapping and accelerometry differentiate premium offerings for knowledge-worker employers. |
| Certification Investment Acceleration | ISO 9241-5 and JIS validation defend specification relationships against direct-to-employer platforms. |
| Regional Manufacturing Footprint | Localized production in India and Southeast Asia reduces freight exposure and import compliance burden. |
| Dealer Network Consolidation | Specification consulting relationships protect margin pools from web-based configuration channel compression. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K furniture segment disclosures, and ISO certification registry records, combining structured interviews with facility managers, corporate procurement officers, ergonomic consultants, and dealer network principals alongside bottom-up and top-down triangulation across manufacturer shipment data and end-user specification surveys.
Forecast inputs incorporate product type segmentation across ergonomic, task, executive, and gaming categories; material tier differentiation between mesh, leather, fabric, and plastic; and end-user deployment models spanning corporate offices, home offices, educational institutions, and co-working spaces. CAGRs were derived through regression analysis of replacement cycle timing, certification adoption curves, and regional commercial real estate expansion patterns, with thermal performance standards and musculoskeletal risk program penetration serving as demand-side modifiers.
Macroeconomic conditions sit as an overlay; deviation in commercial construction spending, base metal pricing, and petrochemical feedstock availability would shift the trajectory. Forecasts reflect documented assumptions regarding hybrid work policy stabilization and regulatory compliance timeline adherence. Cross-checking against BIS import filings and EU ECHA chemical registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
United States Home Office Furniture Market
Office Furniture
Office Chairs Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
Luxury Office Furniture Market
Office Furniture
Rental Furniture Market
Office Furniture
Office Seat Cushion Market
Office Furniture
Home Office Spending Market
Office Furniture
Brazil Office Furniture Market
Office Furniture
Germany Office Furniture Market
Office Furniture
France Office Furniture Market
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
United States Furniture Market
Office Furniture
China Office Furniture Market
Office Furniture
Europe Office Furniture Market
Office Furniture
Office Furniture Market