
 Camping Furniture Market | 2026-2036
Camping Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Camping Furniture Market Analysis
Ultralight specification tiers is rotating through the camping furniture category as consumers prioritize packable weights below two pounds for backcountry use. Helinox leverages advanced DAC aluminum pole architecture to dominate premium backpacking chairs. Coleman sustains mass-market penetration through retail channel control and accessible price positioning. Dometic anchors the car camping segment with integrated kitchen and seating systems designed for vehicle-based recreation.
Camping furniture encompasses portable, collapsible seating, sleeping, and surface structures engineered for temporary outdoor habitation, typically employing aluminum alloy frames, ripstop polyester fabrics, and tension-based assembly mechanisms to achieve load ratings of 250–400 pounds at sub-five-pound packed weights. The product category serves recreational mobility by enabling comfortable, durable camp infrastructure without permanent installation. Chairs and cots capture the largest volume share within product type segmentation due to universal trip utility and repeat purchase frequency. Aluminum leads material demand for its strength-to-weight ratio, though steel persists in budget car camping lines where transport weight matters less. Backpacking within use case segmentation commands the highest per-unit margins as technical specifications justify premium pricing.
EPA oversees chemical safety in fabric coatings and flame retardants applied to camping furniture sold in the United States, while REACH governs substance restrictions across European supply chains, and ISO 5912 sets baseline safety and performance benchmarks for camping equipment internationally. These frameworks elevate compliance costs for smaller manufacturers while creating market access barriers for uncertified imports. Stakeholders must monitor evolving state-level fire safety amendments and emerging extended producer responsibility schemes for outdoor gear.
Market Dynamics
The camping furniture market is compressing around two incompatible specifications: sub-two-pound backpacker gear and vehicle-anchored luxury systems for dispersed campers. This tension between portability and comfort is forcing manufacturers to choose specialization over portfolio breadth.
Growth Catalysts
- REACH substance restrictions:European chemical compliance is filtering non-compliant Asian suppliers from Western supply chains, creating shelf space for certified domestic producers.
- Festival infrastructure:Multi-day music and outdoor events in the United States and Australia are normalizing single-trip disposable furniture purchases among non-traditional outdoor consumers.
- DAC aluminum pole architecture:Advanced tent-pole manufacturing techniques originally developed for mountaineering shelters are migrating into premium chair frames, collapsing packed volumes by forty percent.
Market Restraints
- Ripstop nylon price volatility:Petrochemical feedstock fluctuations and textile mill concentration in Vietnam create margin pressure for mid-tier manufacturers without forward contracts.
- ISO 5912 testing backlog:International safety certification queues at accredited laboratories extend product launch timelines by six to nine months for new market entrants.
- Steel frame substitution:Budget car camping lines face demand erosion from aluminum alternatives as transport economics shift toward fuel efficiency.
Strategic Opportunities
- Rooftop tent integration:Vehicle-based camping systems in Australia and the western United States are creating attachable furniture categories that lock into rack-mounted habitat modules.
- EU Green Deal procurement mandates:Public-sector outdoor recreation programs across Germany, France, and the Netherlands are adding recycled-content requirements that favor closed-loop domestic manufacturers.
- Direct-to-consumer refurbishment:Premium aluminum-frame chairs with replaceable fabric panels are enabling subscription-style durability services that extend customer lifetime value.
Industry Challenges
- Flame-retardant chemist scarcity:EPA and state-level fire safety amendments are outpacing available technical expertise for reformulating fabric coatings without restricted substances.
- Extended producer responsibility compliance:Emerging French and German take-back schemes for outdoor gear require reverse logistics infrastructure that most specialty manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camping Furniture Market |
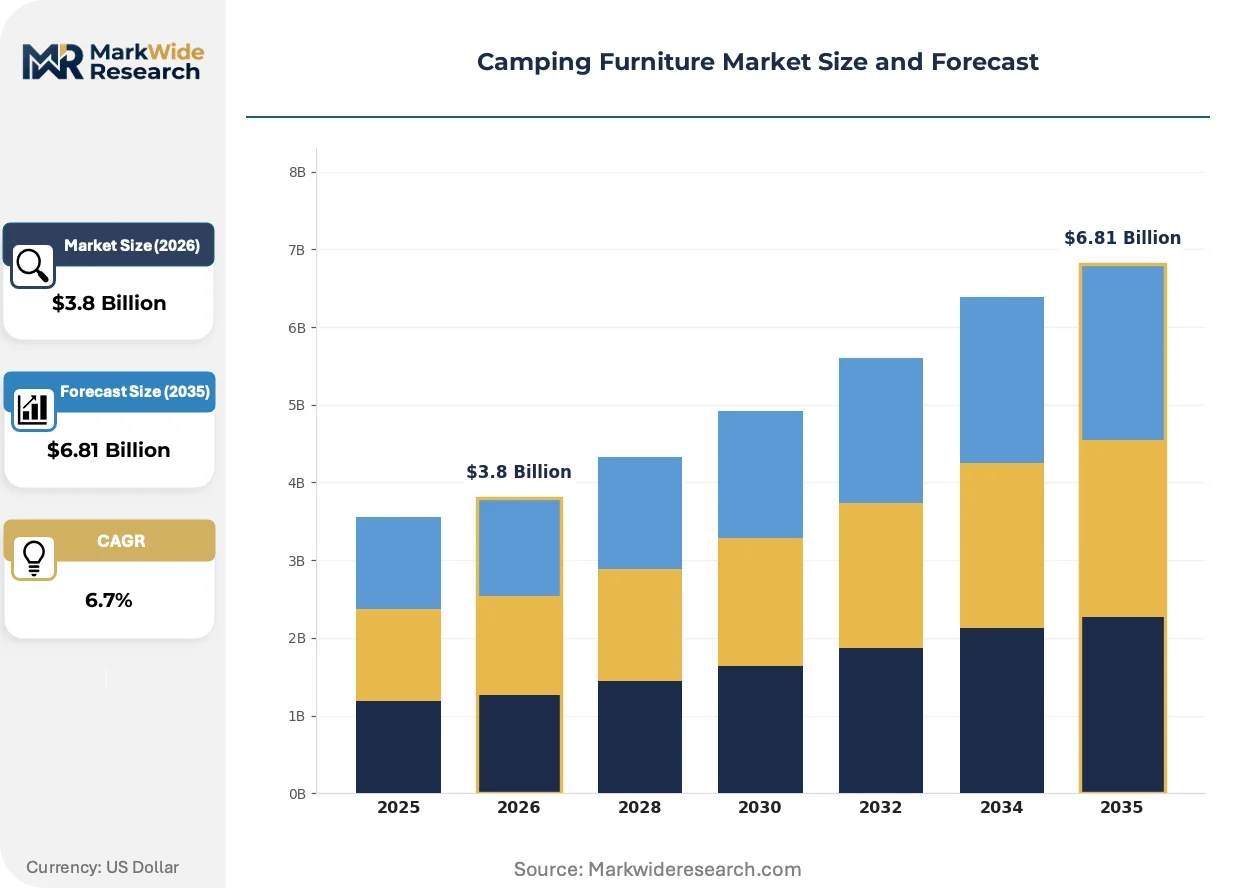
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Cots, Hammocks Material: Aluminum, Steel, Wood, Fabric Use Case: Backpacking, Car Camping, Tailgating, Festivals Customer Type: Outdoor Enthusiasts, Campgrounds, Retailers, Event Planners |
| Companies Covered | ALPS Mountaineering, Thule Group, Coleman Company, Big Agnes, YETI, GCI Outdoor, Dometic, Kamp-Rite, Helinox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camping Furniture Market Emerging Trajectories
Material science and regulatory chemistry are rewriting competitive rules faster than brand equity can accumulate. Manufacturers now compete on supply-chain documentation and gram-scale engineering rather than heritage positioning.
Helium-grade aluminum alloys originally developed for aerospace satellite structures are bifurcating the premium backpacking segment. Ultralight enthusiasts in the Pacific Northwest and Colorado are adopting these frames despite thirty-percent price premiums over standard 7000-series alternatives. The technology is bifurcating retailer assortments into technical specialty channels versus mass outdoor merchants unable to justify inventory depth.
REACH candidate list expansions are accelerating substitution of PFAS-based water repellents in European-bound products. Industrial laundries in Portugal and Romania now reject untreated fabrics that fail spray-test verification. Backpacking shelters and ground cloths face the steepest compliance ramps as moisture protection is non-negotiable for backcountry safety.
Buyers are fragmenting across incompatible use cases that resist cross-selling. Weekend vehicle campers in Utah and Arizona reject specifications that matter to Appalachian Trail through-hikers, forcing brands to maintain parallel product architectures. Specialty retailers in Denver and Portland report inventory duplication costs that mass-channel competitors in the Midwest avoid through single-SKU depth.
Camping Furniture Market Segmentation
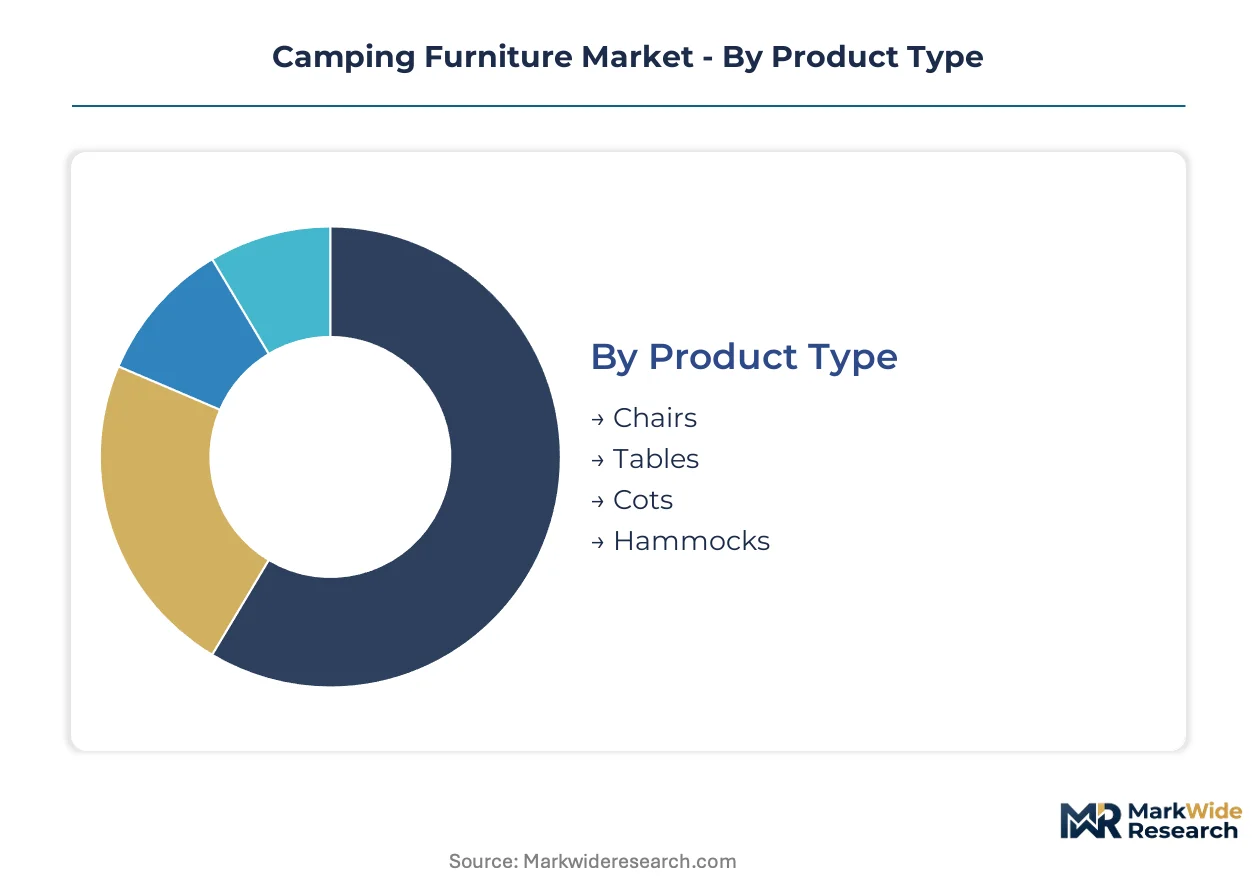
Camping furniture segmentation reflects divergent engineering requirements between ultralight backcountry mobility and vehicle-anchored comfort systems. Regulatory compliance thresholds and transport economics create non-overlapping specification tiers that resist portfolio consolidation.
Product Type:
REACH substance restrictions and ISO 5912 safety certifications create divergent compliance burdens across portable furniture categories, with seating products facing the steepest flame-retardant reformulation costs.
- Chairs:DAC aluminum pole architecture enables sub-two-pound packed weights with 300-pound load ratings. Demand concentrates among Appalachian Trail through-hikers and Pacific Northwest ultralight communities where gram-scale reductions justify forty-percent price premiums over steel alternatives.
- Cots:Tension-based fabric suspension systems using ripstop polyester achieve sleeping elevations that insulate against ground moisture. Campgrounds in Utah and Arizona favor these for rental inventory durability, though backpacking adoption remains limited by packed volume constraints.
- Tables:Roll-top aluminum slat construction balances surface area against collapsibility. Festival infrastructure procurement in Australia drives single-trip disposable purchases with minimal durability requirements.
- Hammocks:Integrated bug netting and rainfly compatibility distinguishes backcountry-specified models from recreational yard variants. Tree-strap suspension systems face emerging leave-no-trace restrictions in national park jurisdictions.
Established volume favors chairs; emerging adoption favors cots.
Material:
Cost tier stratification separates aerospace-grade alloys from commodity steel based on transport mode and trip duration.
- Aluminum:Helium-grade alloys from satellite manufacturing supply chains deliver strength-to-weight ratios that dominate premium backpacking chairs. German and French outdoor retailers now mandate recycled-content verification under EU Green Deal procurement mandates.
- Steel:Budget car camping lines persist where fuel efficiency matters less than upfront acquisition cost. Frame corrosion resistance determines product lifespan in coastal Australian and Florida markets.
- Wood:Collapsible camp stools using hardwood laminates serve glamping aesthetics with minimal technical performance. Scandinavian design retailers position these as lifestyle accessories rather than functional equipment.
- Fabric:Ripstop polyester and nylon variants face PFAS substitution pressure under REACH candidate list expansions. Portuguese industrial laundries now reject untreated fabrics failing spray-test verification.
Margin concentration sits with aluminum; volume accessibility rests with steel.
Use Case:
Customer mobility requirements fragment demand across incompatible portability thresholds.
- Backpacking:Sub-five-pound packed weight mandates with 250-pound minimum load ratings command the highest per-unit margins. Technical specifications around DAC pole architecture and ripstop fabric grades justify premium pricing unavailable to mass-channel competitors.
- Car Camping:Vehicle-anchored systems from Dometic integrate kitchen modules with seating infrastructure. Dispersed camping permit growth in western United States national forests expands addressable market beyond developed campground boundaries.
- Tailgating:Stadium parking lot durability requirements prioritize steel frame stability over weight minimization. Repeat purchase frequency remains low due to seasonal use concentration around autumn sports calendars.
- Festivals:Multi-day music events in the United States and Australia normalize single-trip furniture disposal. Non-traditional outdoor consumers prioritize acquisition convenience over longevity specifications.
Technical premium concentrates in backpacking; volume expansion favors festivals.
Customer Type:
Procurement authority and durability expectations separate institutional buyers from individual enthusiasts.
- Outdoor Enthusiasts:Individual gear acquisition through specialty retailers in Denver and Portland drives specification literacy and brand loyalty. Replaceable fabric panel subscription services extend customer lifetime value for premium aluminum-frame chairs.
- Campgrounds:Rental inventory managers prioritize theft-resistant designs and rapid turnaround cleaning protocols. German and Dutch public-sector recreation programs add recycled-content requirements that filter supplier pools.
- Retailers:Mass-channel competitors in the Midwest avoid inventory duplication costs through single-SKU depth strategies. Specialty retailers absorb higher carrying costs to serve fragmented use case demands.
- Event Planners:Festival infrastructure procurement operates on compressed timelines with minimal quality verification. Australian and United States event logistics firms represent fastest-expanding demand channel for disposable-category furniture.
Margin stability favors outdoor enthusiasts; procurement velocity favors event planners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese textile mills supply ripstop nylon to German and United States furniture assemblers, creating a compliance bottleneck as REACH substance restrictions tighten. This trade corridor concentrates regulatory risk in European-bound shipments while North American buyers face separate EPA flame-retardant thresholds.
United States
National park visitation and dispersed camping permit growth in Utah and Arizona drive demand for vehicle-anchored luxury systems. EPA oversight of chemical safety in fabric coatings elevates compliance costs for imported chairs and cots. Specialty retailers in Denver and Portland absorb inventory duplication costs to serve fragmented use-case demands across incompatible portability tiers.
Germany
EU Green Deal procurement mandates for public-sector outdoor recreation programs filter supplier pools toward recycled-content verification. ECHA REACH candidate list expansions accelerate PFAS substitution in water-repellent fabrics bound for German consumers. Industrial clusters in Bavaria and North Rhine-Westphalia host compliance laboratories processing ISO 5912 safety certifications for European market access.
China
Domestic manufacturers face filtration from Western supply chains as REACH substance restrictions disqualify non-compliant producers. MIIT industrial standards for aluminum alloy processing support helium-grade alloy adoption in premium export frames. Guangdong and Zhejiang production zones concentrate textile mill capacity for ripstop polyester supply to global furniture assemblers.
Australia
Festival infrastructure procurement in New South Wales and Victoria normalizes single-trip disposable furniture purchases among non-traditional outdoor consumers. TGA-equivalent state-level product safety frameworks govern temporary event equipment deployment. Rooftop tent integration trends in Queensland and Western Australia create attachable furniture categories for vehicle-based camping systems.
France
Emerging extended producer responsibility schemes for outdoor gear require reverse logistics infrastructure that specialty manufacturers lack. ANSM and CNIL-aligned environmental compliance layers onto existing REACH obligations for furniture sold through French retail channels. Auvergne-Rhône-Alpes outdoor recreation clusters pilot closed-loop rental programs with recycled-content procurement specifications.
Camping Furniture Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and channel control dimensions. The vendor base stratifies around three tiers: mass-market retailers with retail channel dominance, premium specialists with technical specification leadership, and vehicle-system integrators with habitat module compatibility. Structural consolidation remains limited as incompatible use-case specifications resist portfolio breadth. Competitive moves concentrate on geographic licensing partnerships and direct-to-consumer platform development rather than horizontal acquisition.
Within the premium technical tier, Helinox and Big Agnes exemplify specification-driven positioning through advanced aluminum pole architecture and ultralight fabric systems. Coleman Company anchors mass-market penetration through retail channel density and accessible price positioning. Dometic occupies the vehicle-system integrator position, representing car camping infrastructure convergence with habitat module compatibility. These three archetypes illustrate the market's forced specialization between portability and comfort vectors.
| Leading Market Players |
|---|
| ALPS Mountaineering |
| Thule Group |
| Coleman Company |
| Big Agnes |
| YETI |
| GCI Outdoor |
| Dometic |
| Kamp-Rite |
| Helinox |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for helium-grade aluminum alloys lock in supply access for premium backpacking chair manufacturers while anchoring price visibility against volatile aerospace scrap markets. These agreements bind Vietnamese textile mills to fixed-volume ripstop nylon deliveries, insulating mid-tier assemblers from petrochemical feedstock swings that otherwise compress margins.
Pricing Analysis
Current-generation DAC aluminum pole architecture commands forty-percent premiums over prior-generation 7000-series frames, while next-generation satellite-grade alloys threaten further stratification. Three-tier pricing structure across premium, standard, and economy levels separates ISO 5912-certified technical specialists from mass-channel competitors. Cost compression in the steel-frame economy tier is intensifying because aluminum substitution erodes fuel-efficiency-conscious car campers. Festival procurement teams exhibit highest price sensitivity; Appalachian Trail through-hikers show lowest sensitivity to gram-scale weight premiums.
Supply Chain Analysis
Strait of Malacca transit underwrites ripstop polyester feedstock flows from Guangdong and Zhejiang production zones to German and United States furniture assemblers. Vietnamese textile mill concentration and Chinese aluminum alloy processing create dual-source dependencies for frame and fabric components. REACH substance restrictions pose regulatory restriction risks that filter non-compliant Asian suppliers from European-bound shipments. Distribution runs through mass-market retail channel density for volume tiers and specialty technical dealers for premium specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The camping furniture market is approaching a platform-economics inflection as rooftop tent integration creates attachable furniture categories requiring habitat module interoperability standards. Dometic's vehicle-system convergence demonstrates how ecosystem control captures recurring revenue beyond single-unit sales.
For Market Incumbents: Secure DAC aluminum pole architecture supply through backward integration into aerospace alloy supply chains, insulating against helium-grade material competition. Defend against emerging direct-to-consumer refurbishment services by deploying replaceable fabric panel subscription programs that extend customer lifetime value for premium aluminum-frame chairs. For New Entrants and Emerging Players: Lead with festival infrastructure procurement as the most penetrable demand channel, exploiting compressed timeline requirements and minimal quality verification protocols that disadvantage established technical specialists. Target Australian and United States event logistics firms with single-trip disposable furniture categories optimized for acquisition convenience over longevity specifications. For Investors and Strategic Acquirers: Capital is best deployed toward vehicle-system integrators with habitat module compatibility and closed-loop domestic manufacturers positioned for EU Green Deal recycled-content mandates. Long-term viability favors suppliers with reverse logistics infrastructure for emerging French and German extended producer responsibility schemes. Watch REACH candidate list expansion velocity as the inflection indicator for PFAS substitution cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aerospace Alloy Supply | Helium-grade aluminum access locks in premium backpacking chair margins against satellite manufacturing competition. |
| Direct-to-Consumer Refurbishment Platform | Replaceable fabric panel subscriptions extend customer lifetime value for DAC aluminum-frame chairs. |
| Rooftop Tent Integration Development | Habitat module compatibility captures vehicle-based camping demand in Queensland and Western Australia. |
| EU Green Deal Compliance Certification | Recycled-content verification unlocks German and Dutch public-sector outdoor recreation procurement. |
| Festival Infrastructure Channel Expansion | Australian and United States event logistics firms represent fastest-expanding demand for disposable-category furniture. |
Methodological Framework
The analysis maps backpacking ultralight specifications, car camping vehicle systems, festival disposable categories, and tailgating durability tiers, each validated through product development directors at aluminum frame manufacturers, procurement leads at Vietnamese textile mills, category buyers at mass-market retailers, and compliance officers at REACH certification laboratories. Primary interview findings triangulate against customs trade records for ripstop polyester and aluminum alloy shipments, SEC 10-K filings from listed outdoor equipment manufacturers, ECHA REACH candidate list publications, and national park visitation statistics. Bottom-up unit economics and top-down market sizing converge through iterative stakeholder validation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation across product type, material grade, use case mobility requirements, and customer procurement authority. CAGRs derive from trend extrapolation of national park permit growth, dispersed camping adoption curves, and festival infrastructure spending patterns. Industry-specific inputs include DAC aluminum pole architecture adoption rates and REACH substance restriction implementation timelines.
Forecasts assume regulatory continuity in EPA flame-retardant oversight and ECHA REACH candidate list expansion; material policy shifts would require re-modeling of compliance cost burdens across fabric coating reformulation. Revision becomes warranted when PFAS substitution technical feasibility crosses commercial viability thresholds or when extended producer responsibility scheme adoption accelerates beyond pilot program scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
Retractable Awnings Market
Outdoor Decor
Outdoor Dining Table Market
Outdoor Decor
United States Outdoor Furniture Market
Outdoor Decor
Wooden Decking Market
Outdoor Decor
Brazil Sustainable Home Decor Market
Outdoor Decor
Garden Rooms Market
Outdoor Decor
Brush Rocker Market
Outdoor Decor
Outdoor Kitchen Cabinets Market
Outdoor Decor
Outdoor Cushions Market
Outdoor Decor
Spray Covers Market
Outdoor Decor
Outdoor Furniture Market
Outdoor Decor
Middle East Outdoor and Indoor Furniture Market
Outdoor Decor
Floating Fountains Market
Outdoor Decor
North America Awnings Market
Outdoor Decor
Europe Awnings Market
Outdoor Decor
North America Residential Outdoor Gas Fire Pits Market