
 Europe Upholstered Furniture Market | 2026-2036
Europe Upholstered Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Upholstered Furniture Market Foresight
Hospitality buyers are redrawing procurement patterns across the European upholstered furniture landscape. DFS Furniture Plc leverages its vertically integrated British manufacturing base to serve contract hoteliers with accelerated lead times. Poltrona Frau anchors the luxury segment through its heritage leatherworking expertise in Tolentino. Natuzzi S.p.A. competes on Mediterranean design identity while sustaining extensive retail distribution across Southern Europe.
Europe upholstered furniture comprises seating products built on engineered wood or metal frames, padded with polyurethane foam, polyester fiber, or down blends, and covered with leather, fabric, velvet, or microfiber materials. Primary commercial purpose spans residential living spaces, corporate offices, hospitality venues, and institutional waiting areas where ergonomic support and aesthetic cohesion drive selection. Sofas generate the largest revenue pool across product types, though recliners capture disproportionate margin in aging European demographics. Fabric upholstery leads volume by material, while leather commands premium positioning in executive and luxury hospitality settings. The residential end-user segment remains mature, whereas hospitality procurement accelerates fastest amid post-pandemic hotel renovation cycles.
REACH regulation and the EU Green Deal constrain chemical inputs in foam production and mandate recyclability disclosures across member states. ECHA's evolving restrictions on flame retardants and volatile organic compounds directly reshape supplier qualification criteria and reformulation costs for manufacturers serving Germany, France, and Italy. The EU AI Act introduces emerging compliance dimensions for smart furniture with embedded sensors. Stakeholders must monitor ecodesign standard expansions and carbon border adjustment mechanisms to protect market access and sourcing economics.
Market Dynamics
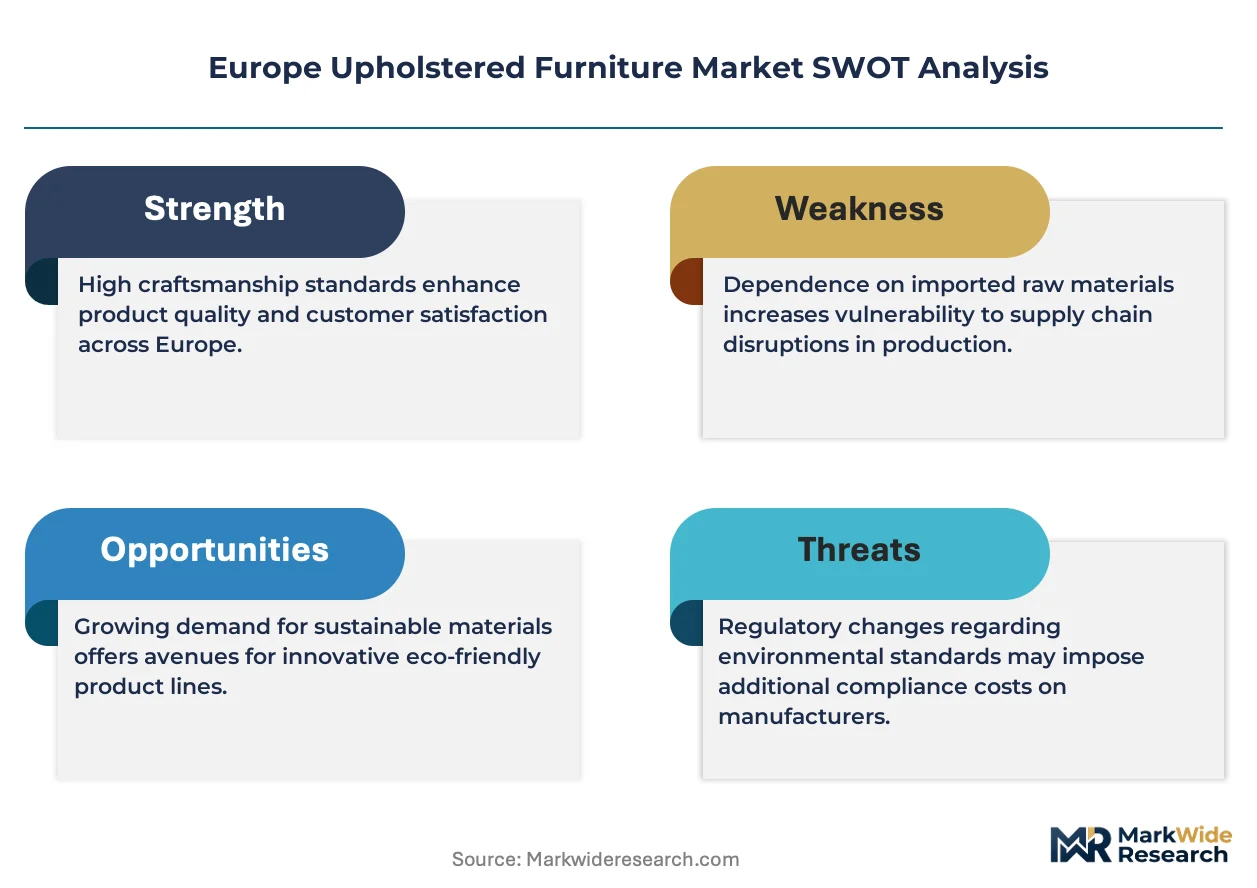
The EU Green Deal's ecodesign requirements are compressing foam chemistry choices across European manufacturing, forcing rapid supplier recertification and raw material substitution before enforcement deadlines tighten.
Growth Catalysts
- REACH chemical reformulation:Manufacturers serving Germany and France are accelerating bio-polyol adoption in foam production to preempt ECHA restrictions on isocyanates and flame retardants.
- Hospitality renovation cycles:Boutique hotel chains across Italy and Spain are replacing pandemic-deferred upholstery stock, creating concentrated demand spikes for fire-rated contract seating.
- Brianza cluster specialization:The concentration of tanning, woodworking, and metal finishing capabilities within 50 kilometers of Milan enables sub-6-week custom lead times unmatched elsewhere in Europe.
Market Restraints
- Polyether polyol price volatility:Feedstock exposure to propylene oxide markets creates margin compression for foam suppliers serving mid-tier residential segments.
- Chinese fabric dominance:Over 60% of European upholstery textile supply routes through Ningbo and Shaoxing mills, exposing buyers to shipping rate spikes and tariff uncertainty.
- Legacy frame joinery limitations:Dowel-and-glue construction cannot meet new EU load-bearing durability standards without capital-intensive CNC routing upgrades.
Strategic Opportunities
- CSRD disclosure mandates:Early movers capturing scope 3 carbon data from Italian tanneries and Portuguese cork suppliers will secure preferred supplier status with ESG-screening hospitality procurement teams.
- Modular sofa platforms:Component-based seating systems allow end-users to replace worn sections rather than full units, opening subscription and refurbishment revenue streams in Nordic markets.
- Smart furniture sensor integration:Embedded occupancy and wear-monitoring hardware creates differentiated positioning for airport lounge and co-working space contracts under the EU AI Act's risk-based compliance framework.
Industry Challenges
- Master upholsterer attrition:The Brianza and Valencia clusters face acute shortages of craftspeople capable of hand-tied spring and eight-way hand-tied construction, forcing automation investments that compromise heritage positioning.
- Dual certification timelines:Simultaneous pursuit of EU CE marking and UKCA conformity assessment post-Brexit doubles testing costs and extends product launch windows for cross-channel suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Upholstered Furniture Market |
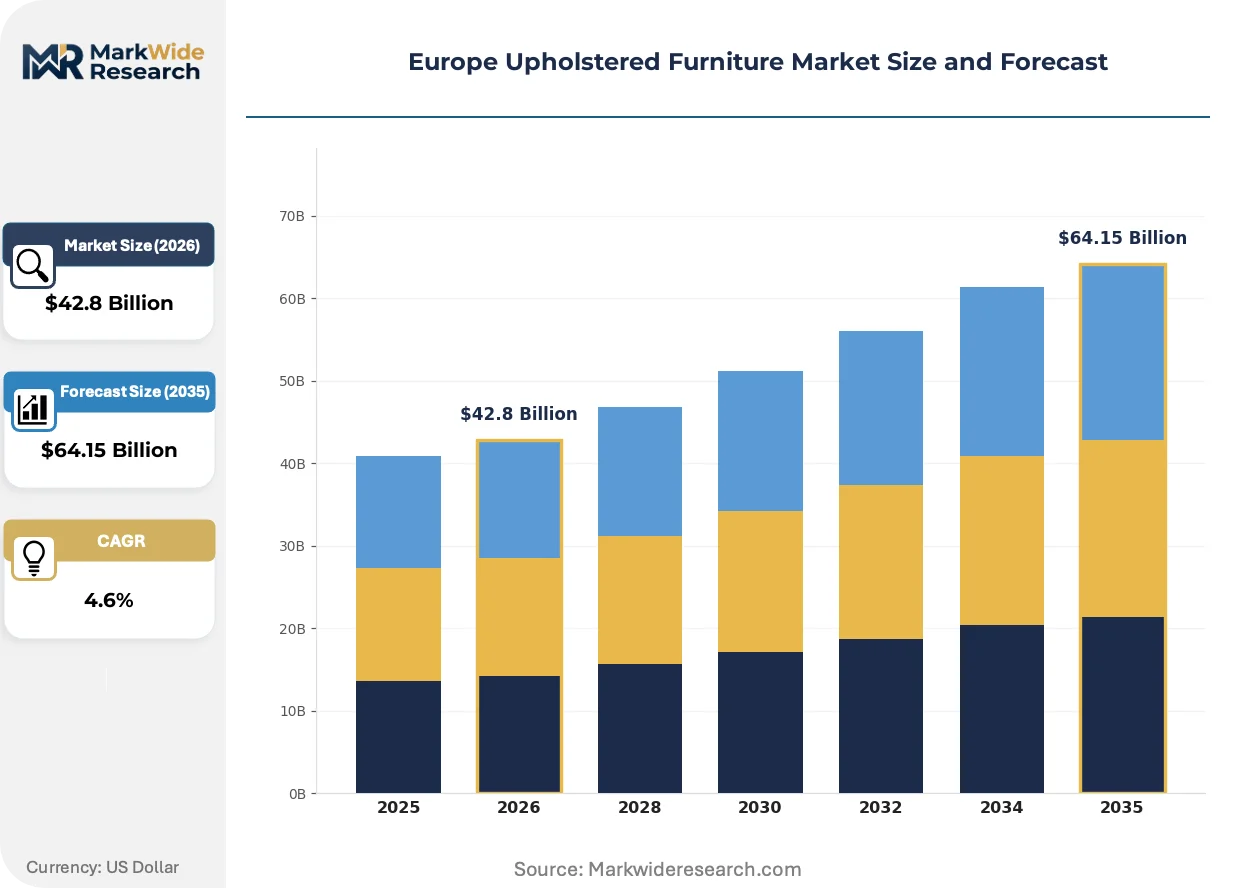
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $64.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Recliners, Ottomans Material: Leather, Fabric, Velvet, Microfiber End User: Residential, Commercial, Hospitality, Institutional Sales Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | DFS Furniture Plc, Poltronesofà, IKEA Group, Polipol, Meble WERSAL, Steinhoff International, Poltrona Frau, Roche Bobois, Natuzzi S.p.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Upholstered Furniture Market Shifts & Advancements
Material chemistry, regulatory disclosure architecture, and hospitality procurement models are converging to redefine competitive positioning across European upholstery manufacturing.
Recycled PET fiber derived from ocean plastic waste is decomposing the traditional virgin polyester supply chain. Scandinavian hospitality groups are mandating marine plastic content minimums in public area seating. This material shift is compressing price premiums for sustainable upholstery textiles toward parity with conventional options.
The EU Green Deal's ecodesign for sustainable products regulation is mandating digital product passports for furniture placed on the single market. Manufacturers must embed QR-linked material provenance data covering foam origin, textile dye chemistry, and frame wood species. Italian luxury producers are responding fastest, leveraging existing supplier audit infrastructure to meet 2027 disclosure deadlines.
Direct-to-hotelier digital platforms are displacing traditional contract furniture dealers in project specification. Procurement teams at Accor and Marriott International properties are using 3D visualization tools to configure custom upholstery without showroom visits. This channel compression is most advanced in German and Dutch markets where facility management groups centralize purchasing decisions across property portfolios.
Europe Upholstered Furniture Market Segmentation
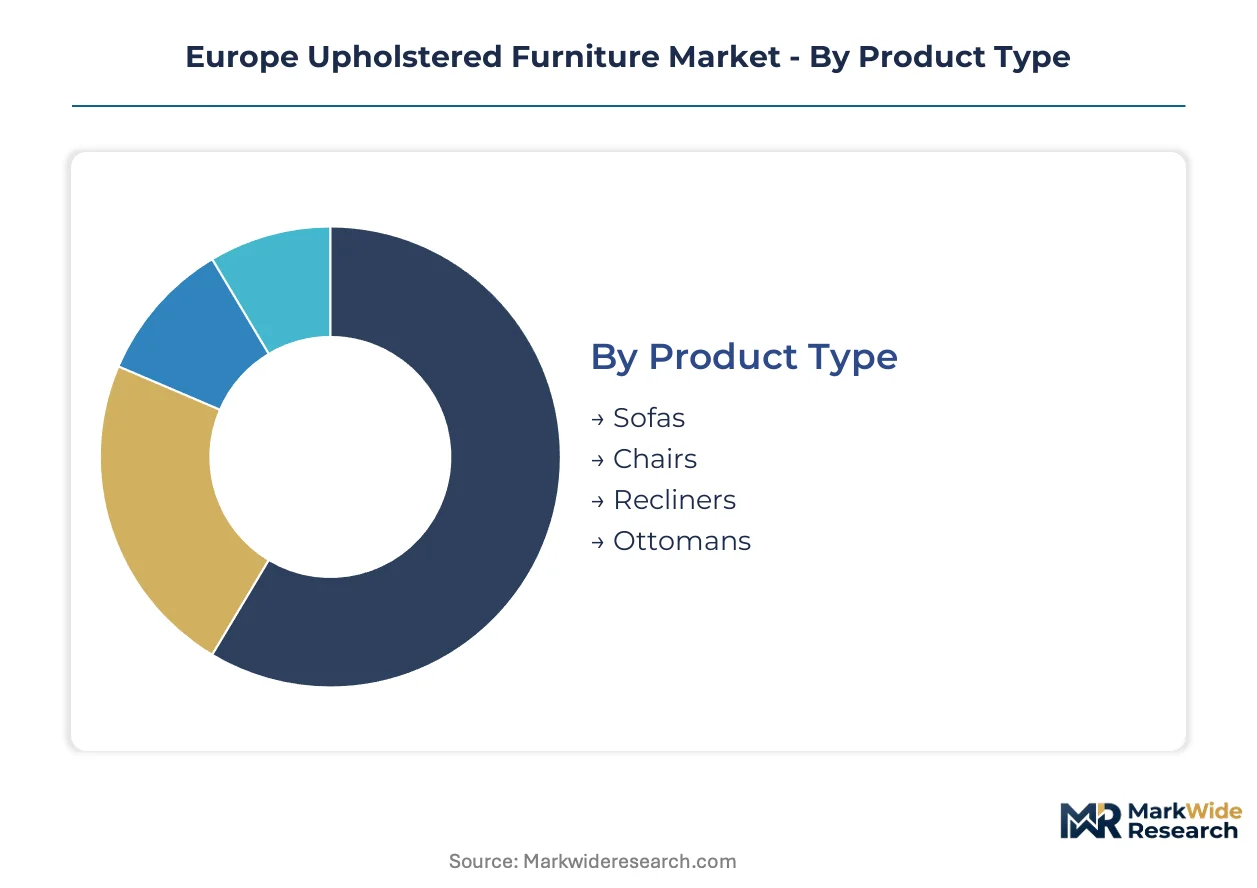
Segmentation in European upholstered furniture reveals divergent supply chain configurations. Product type and material choices map directly to manufacturing location and export intensity. Understanding these splits enables targeted capacity planning and regulatory compliance investment.
Product Type:
Sofas and chairs flow predominantly through domestic Italian and Portuguese manufacturing for European distribution, while recliners and ottomans increasingly source from Eastern European assembly hubs serving export markets.
- Sofas:Engineered wood frames with multi-density polyurethane foam cores and sinuous spring suspension systems dominate construction. German and French residential buyers concentrate demand in the 2.5 to 3.5-meter width category, with Brianza manufacturers capturing the premium custom segment through sub-6-week lead times.
- Chairs:Dining and accent chair categories span molded plywood shells to fully upholstered wingback designs. Spanish contract furniture specialists in Valencia cluster serve hospitality renovation cycles with fire-rated foam configurations meeting ECHA flame retardant standards.
- Recliners:Mechanism-integrated seating with steel reclining hardware and high-resilience foam padding. Aging demographics in Italy and Germany sustain demand for ergonomic positioning features.
- Ottomans:Modular footrest and storage bench configurations using medium-density foam and hardwood legs. Polish and Romanian factories supply volume retail channels across Northern Europe.
Sofas command the established base. The steepest expansion runs through recliners.
Material:
Cost tier stratification separates material categories sharply. Leather and velvet anchor premium positioning with concentrated Italian supply, while fabric and microfiber compete on volume accessibility through distributed sourcing.
- Leather:Full-grain and corrected-grain hides from Italian tanneries in Solofra and Santa Croce sull'Arno supply luxury hospitality and executive office segments. REACH chemical restrictions on chromium tanning drive vegetable-tanning process investments.
- Fabric:Woven polyester, cotton blends, and linen-look synthetics constitute the volume leader. Scandinavian hospitality procurement mandates recycled PET content minimums, compressing sustainable premiums toward parity with virgin fiber pricing.
- Velvet:Dense pile constructions in cotton, silk, or synthetic blends deliver tactile luxury positioning. Belgian and Dutch weaving houses supply high-end residential and boutique hotel specifications.
- Microfiber:Ultra-fine polyester filament constructions offering stain resistance and durability at accessible price points. Portuguese textile mills serve mass-market retail channels across Iberia and France.
Fabric sustains the volume core. Leather captures margin expansion from ESG-screening procurement teams.
End User:
Application-driven demand splits align with regulatory exposure and replacement cycle timing. Residential and institutional segments operate on extended depreciation schedules, while hospitality and commercial refresh stock on accelerated renovation timelines.
- Residential:Living room and bedroom seating for individual consumers. Italian and German markets concentrate premium upholstery expenditure, with online visualization tools displacing traditional showroom visits in Dutch and German purchasing.
- Commercial:Corporate office reception, meeting room, and breakout seating. German facility management groups centralize procurement across property portfolios, favoring modular platforms with component replaceability.
- Hospitality:Hotel lobbies, guest rooms, and restaurant seating for boutique and chain properties. Post-pandemic renovation cycles in Italy and Spain create concentrated demand spikes for fire-rated contract specifications.
- Institutional:Healthcare waiting areas, educational common rooms, and government facility seating. Extended tender processes and durability certification requirements favor established suppliers with CE marking infrastructure.
Residential anchors volume throughput. Hospitality delivers the sharpest demand inflection.
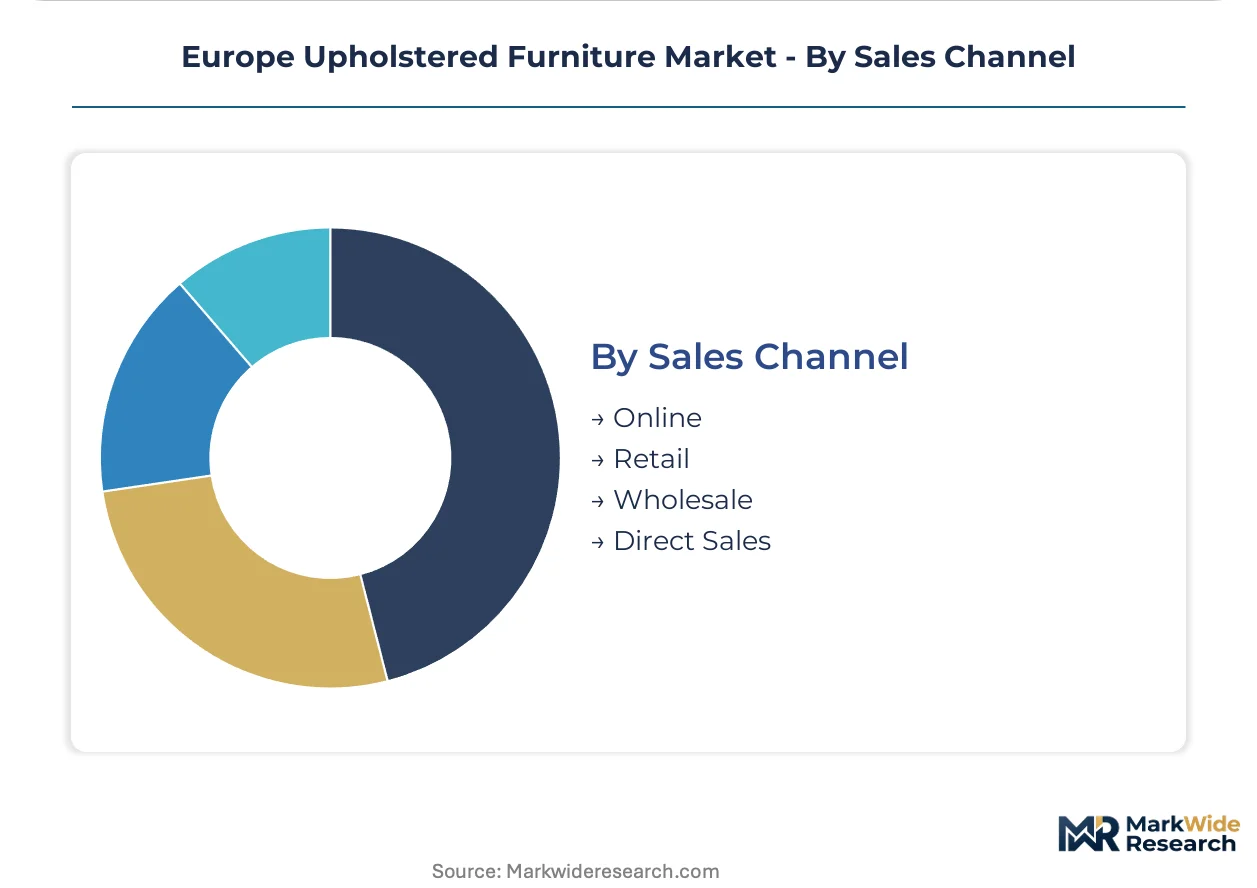
Sales Channel:
Customer type and purchase scale determine channel selection. Direct and wholesale relationships dominate contract volume, while retail and online serve fragmented residential decision-making.
- Online:Configurator-driven platforms with 3D visualization and home delivery logistics. German and Nordic consumers lead adoption of digital-first upholstery purchasing without physical showroom visits.
- Retail:Branded storefronts and multi-brand furniture galleries with in-person material sampling. Southern European markets retain stronger showroom dependency for tactile leather and fabric evaluation.
- Wholesale:Dealer networks and contract furniture distributors serving project specification. Traditional channels face compression from direct-to-hotelier digital platforms at Accor and Marriott International properties.
- Direct Sales:Manufacturer-owned showrooms and specification teams targeting hospitality and commercial procurement. Italian luxury producers leverage heritage positioning to bypass dealer margins on high-value contracts.
Retail maintains the broadest footprint. Online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian upholstery exports flow northward into German and French hospitality procurement channels, while Polish assembly hubs feed volume retail demand across Scandinavia. This trade-flow configuration concentrates premium craft capabilities in Mediterranean manufacturing clusters while Eastern European facilities capture standard-segment scale.
Germany
Facility management groups in Berlin and Hamburg centralize corporate seating procurement across multi-property portfolios, favoring modular platforms with component replaceability. ECHA's evolving REACH restrictions on flame retardants force foam reformulation across domestic suppliers. The North Rhine-Westphalia region hosts upholstery fabricators serving fire-rated contract specifications for hotel renovation cycles.
Italy
Boutique hotel chains in Milan and Rome drive concentrated demand spikes for custom leather seating with sub-6-week lead times. The EU Green Deal's ecodesign requirements mandate digital product passports covering material provenance by 2027. The Brianza cluster north of Milan concentrates tanning, woodworking, and metal finishing capabilities within a 50-kilometer radius unmatched elsewhere in Europe.
France
Paris-based luxury hospitality procurement teams specify heritage leatherworking for executive lounge and suite installations. ANSM and CNIL oversight intersects with CSRD disclosure mandates for scope 3 carbon data from Italian tanneries. The Île-de-France region anchors specification influence that radiates into Belgian and Dutch distribution channels.
Spain
Post-pandemic hotel renovation cycles in Barcelona and Madrid create demand inflection for fire-rated contract seating configurations. ECHA flame retardant standards reshape supplier qualification criteria for Valencia-based foam specialists. The Valencia cluster faces acute craft shortages in hand-tied spring construction, forcing automation investments that alter heritage positioning.
Poland
Mass-market retail channels across Northern Europe source volume ottomans and standard seating from Warsaw and Łódź assembly operations. CE marking infrastructure supports export access to German and Scandinavian buyers. Polish factories compete on lead time compression for mid-tier residential segments where price sensitivity dominates selection criteria.
Europe Upholstered Furniture Market Competitive Landscape
Listed leaders compete with private specialists across capital access and craft heritage dimensions. The vendor base splits between vertically integrated British manufacturers, Italian luxury leatherworkers, and Scandinavian volume retailers. Three archetypes dominate: heritage craft houses with atelier positioning, scale-driven retailers with configurator platforms, and contract specialists with fire-rated certification infrastructure. M&A activity concentrates on regional craft brands, while capacity expansion targets Eastern European assembly for standard-segment volume.
Within the heritage craft tier, Poltrona Frau and Roche Bobois exemplify Mediterranean leatherworking prestige anchored in generational supplier relationships. DFS Furniture Plc occupies a distinct position as a listed British manufacturer with vertically integrated domestic production serving accelerated hospitality lead times. Natuzzi S.p.A. represents the design-export archetype, leveraging Mediterranean aesthetic identity across Southern European retail distribution while competing with Scandinavian volume players.
| Leading Market Players |
|---|
| DFS Furniture Plc |
| Poltronesofà |
| IKEA Group |
| Polipol |
| Meble WERSAL |
| Steinhoff International |
| Poltrona Frau |
| Roche Bobois |
| Natuzzi S.p.A. |
| Others |
Supply & Pricing Matrix
Sub-6-week custom lead times from the Brianza cluster translate directly into pricing power for Italian luxury manufacturers, while Polish assembly operations serving Northern European retail channels compete on compressed margins where inventory turns dictate supplier selection.
Pricing Analysis
Current-generation bio-polyol foam formulations command premium positioning over legacy petroleum-based chemistry, while next-generation digital product passport compliance will further stratify pricing tiers. Three-tier pricing structure across heritage craft, mid-tier contract, and mass-market retail levels dominates the landscape. Price differentiation hinges on REACH certification grade and Brianza cluster provenance. Cost compression in mid-tier residential segments intensifies as Chinese fabric supply routes expose buyers to shipping volatility. Hospitality procurement teams demonstrate least price sensitivity, while mass-market retail channels exhibit acute responsiveness to polyurethane foam feedstock fluctuations.
Supply Chain Analysis
Inventory positioning at Italian tanneries and Portuguese cork suppliers reflects just-in-time coordination with Brianza frame manufacturers, compressing working capital cycles for heritage positioning. Supply concentrates in Italy for premium leather and custom upholstery, Poland for volume assembly, and China for fabric textiles. Raw material flows draw from Solofra tanning districts, German engineered wood suppliers, and Ningbo textile mills. Single-source vulnerability runs through Chinese fabric dominance exceeding sixty percent of European upholstery textile routes. Distribution runs through direct-to-hotelier digital platforms displacing traditional contract dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of master upholsterers capable of eight-way hand-tied construction in the Brianza and Valencia clusters constrains output expansion for heritage-positioned manufacturers, forcing capital allocation toward automation or craft apprenticeship pipelines.
For Market Incumbents: Fortify supplier relationships with Italian tanneries and Portuguese cork producers to preempt CSRD-driven scope 3 disclosure advantages for competitors. Invest in CNC routing upgrades to meet EU load-bearing durability standards before legacy frame joinery becomes non-compliant. Dual certification timelines for CE marking and UKCA conformity assessment threaten launch windows for cross-channel suppliers. For New Entrants and Emerging Players: Anchor in modular sofa platforms for Nordic markets where subscription and refurbishment revenue streams remain underdeveloped. Target hospitality procurement digitization in German and Dutch facility management groups where 3D visualization tools displace showroom-dependent specification. Partner with recycled PET fiber suppliers to capture Scandinavian marine plastic content mandates before sustainable premiums compress to parity. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regional craft brand acquisition targets in Italy and Spain offer heritage positioning at valuations below standalone replication costs. Monitor master upholsterer wage inflation in the Brianza cluster as inflection indicator for automation-driven margin compression across the heritage tier.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Product Passport Integration | Italian luxury producers leverage existing supplier audit infrastructure to meet EU Green Deal disclosure deadlines. |
| Backward Integration into Bio-Polyol Production | Manufacturers serving Germany and France preempt ECHA restrictions on isocyanates and flame retardants. |
| Direct-to-Hotelier Platform Launch | Procurement teams at Accor and Marriott properties bypass traditional contract furniture dealer margins. |
| Modular Component Standardization | End-users replace worn sections rather than full units, opening subscription revenue in Nordic markets. |
| Smart Furniture Sensor Development | Embedded occupancy hardware creates differentiated positioning for airport lounge contracts under EU AI Act compliance. |
Research Methodology
A standing panel of hospitality procurement directors, Brianza cluster production managers, Italian tannery technical leads, and German facility management buyers provided ongoing calibration across primary fieldwork. Secondary validation drew from ECHA regulatory filings, EU customs trade data, CSRD disclosure frameworks, and CE marking certification databases. Bottom-up capacity modeling triangulated against top-down hospitality renovation cycle projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, material category, end-user application, and sales channel configuration. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points. Forecast inputs incorporated REACH chemical reformulation timelines and ecodesign standard enforcement sequences.
Material uncertainties — tariff reconfiguration on Chinese textile imports, ECHA flame retardant restriction expansion, and master upholsterer labor availability — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Russia Home Furniture Market
Furniture
United Arab Emirates Furniture Market
Furniture
RTA Furniture Market
Furniture
Canada Home Furniture Market
Furniture
North America Smart Furniture Market
Furniture
Children's Home Study Desks Market
Furniture
Plastic Furniture Market
Furniture
Global Smart Furniture Market
Furniture
Recliner Chair Market
Furniture
UK Sustainable Home Furniture Market
Furniture
Contract Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Ready-To-Assemble (RTA) Furniture Market
Furniture
US Sustainable Furniture Market
Furniture
Germany Home Furniture Market
Furniture
Children Furniture Market