
 Japan Vegan Cosmetics Market | 2026-2036
Japan Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Vegan Cosmetics Market Insights
Young professional women in metropolitan Japan are collapsing the historical gap between prestige and mass-market vegan beauty, forcing brands to recalibrate positioning. Shiseido Co Ltd anchors its vegan portfolio through advanced biotech fermentation platforms developed at its Yokohama research center. Kao Corporation competes via intensive R&D spending on plant-derived surfactants that replace petroleum-based emulsifiers. Lush Fresh Handmade Cosmetics differentiates through vertically controlled retail channels and transparent ingredient sourcing.
Japan vegan cosmetics encompass beauty and personal care products formulated without animal-derived ingredients, animal testing, or byproducts such as beeswax, lanolin, or carmine, typically substituting plant oils, synthetic peptides, and microbial fermentates to achieve comparable sensorial and functional performance. The primary commercial purpose centers on serving ethically motivated consumers who reject animal exploitation while demanding dermatological efficacy comparable to conventional formulations. Skincare dominates current revenue generation due to higher per-unit pricing and repeat purchase frequency among aging-conscious buyers. Serum formulations within the skincare category are gaining fastest traction as consumers prioritize concentrated active delivery over multi-step routines. Online Retail channels capture expanding margin pools by eliminating department store concession fees and enabling direct consumer education on vegan certification standards.
METI administers quality labeling rules that pressure brands to substantiate vegan claims through documented supply chain audits, while the Consumer Affairs Agency monitors against misleading environmental representations. Japan's alignment with ISO 16128 natural and organic cosmetics standards creates technical benchmarks that vegan products must meet or exceed to secure shelf placement at major retailers. Stakeholders must monitor evolving interpretations of what constitutes adequate vegan verification as domestic certification bodies proliferate and retail buyers tighten due diligence protocols.
Market Dynamics
Fermentation-derived ceramides and biotech surfactants are collapsing the cost-performance gap between plant-based and conventional cosmetic chemistry, forcing incumbent formulators to rebuild R&D pipelines around microbial production platforms.
Growth Catalysts
- Tokyo-Osaka demand corridor:Young professional women in these metropolitan clusters are normalizing vegan beauty as default skincare, creating concentrated volume pull that justifies dedicated supply chain investment.
- METI ethical labeling framework:Documented supply chain audit requirements pressure brands into verifiable vegan claims, which retail buyers at major department stores now mandate for shelf placement.
- Biotech fermentation platforms:Advanced microbial production of ceramides and peptides achieves sensorial parity with animal-derived equivalents at declining unit economics.
Market Restraints
- Plant oil input volatility:Cold-pressed jojoba and squalane prices fluctuate with California and Mediterranean harvest conditions, compressing gross margins on mid-tier formulations.
- Single-source fermentation capacity:Domestic bioreactor infrastructure concentrates in Kanagawa and Osaka prefectures, creating geographic concentration risk for finished goods supply.
- ISO 16128 compliance friction:Natural and organic certification benchmarks impose documentation burdens that smaller domestic brands struggle to satisfy without dedicated regulatory staff.
Strategic Opportunities
- Kansai corridor expansion:Kyoto and Kobe present underpenetrated demand pools where vegan positioning remains novel versus saturated Tokyo retail environments.
- Direct-to-consumer subscription channels:Online retail enables margin recovery from eliminated department store concession fees while building recurring revenue through personalized regimen curation.
- Consumer Affairs Agency enforcement clarity:Tightening scrutiny of misleading environmental claims creates first-mover advantage for brands with pre-established vegan verification protocols.
Industry Challenges
- Formulation chemist scarcity:Cross-training conventional cosmetic scientists in microbial fermentation and plant-derived emulsification requires 18-24 month capability buildout timelines.
- Multi-certification audit burden:Simultaneous pursuit of vegan, cruelty-free, and ISO 16128 credentials demands parallel documentation streams that strain quality assurance bandwidth.
- Legacy retailer integration:Department store concession systems built around seasonal color cosmetics resist the education-intensive, slow-turn skincare model that vegan brands require.
Report Scope
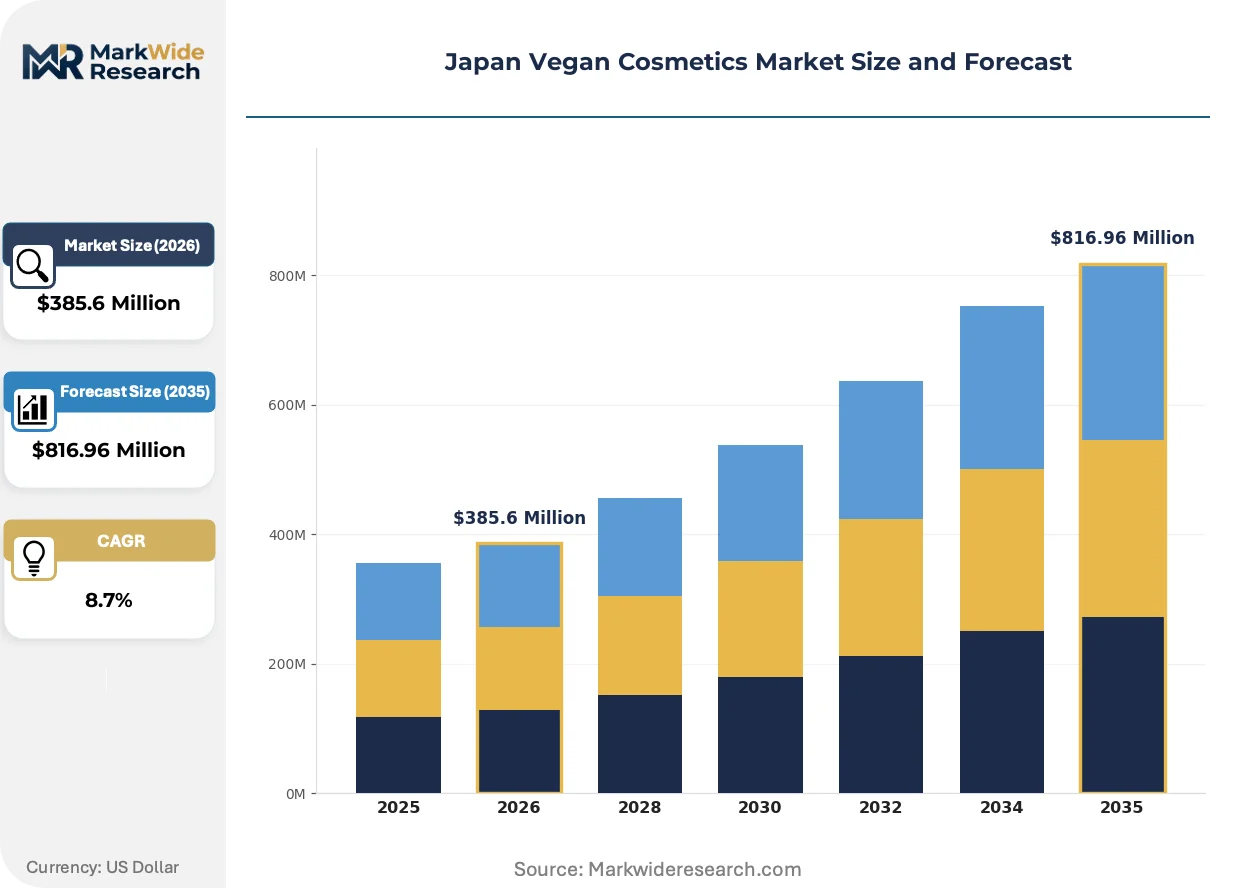
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Vegan Cosmetics Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Hair Care, Fragrance Formulation: Cream, Serum, Gel, Balm Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies Customer Type: Millennials, Gen Z, Health Enthusiasts, Eco-conscious Consumers |
| Companies Covered | L'Oreal S.A., AINOKI, Shiseido Co Ltd, REI COSMETICS JAPAN, KIWABI, Kao Corporation, Pols Orbis Holdings Inc, Lush Fresh Handmade Cosmetics, Kose Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Vegan Cosmetics Market Trends and Innovations
Biotechnology is displacing petroleum and animal chemistry as the primary innovation vector, while regulatory verification requirements and channel disintermediation reshape how value flows between manufacturers and end users.
Precision fermentation of ceramides and peptides is fragmenting the traditional supplier base for functional cosmetic ingredients. Domestic biotech startups and established personal care multinationals now compete directly with agricultural commodity traders for formulation slots. Serum and concentrated treatment categories absorb these inputs fastest, as consumers prioritize single-step efficacy over multi-product rituals.
METI's evolving interpretation of quality labeling rules is tightening documentary requirements for vegan claims. Brands must now maintain batch-level supply chain records that withstand retailer due diligence protocols. Premium skincare segments face the steepest compliance burden, as higher price points attract proportionally greater regulatory scrutiny and consumer litigation risk.
Subscription-based replenishment models are displacing department store discovery as the primary customer acquisition channel for vegan beauty. Young professional women in metropolitan Japan prefer algorithm-curated regimen recommendations over counter-based consultations. Online retail captures expanding margin pools by eliminating intermediary markups while enabling direct education on certification standards and ingredient provenance.
Japan Vegan Cosmetics Market Segmentation
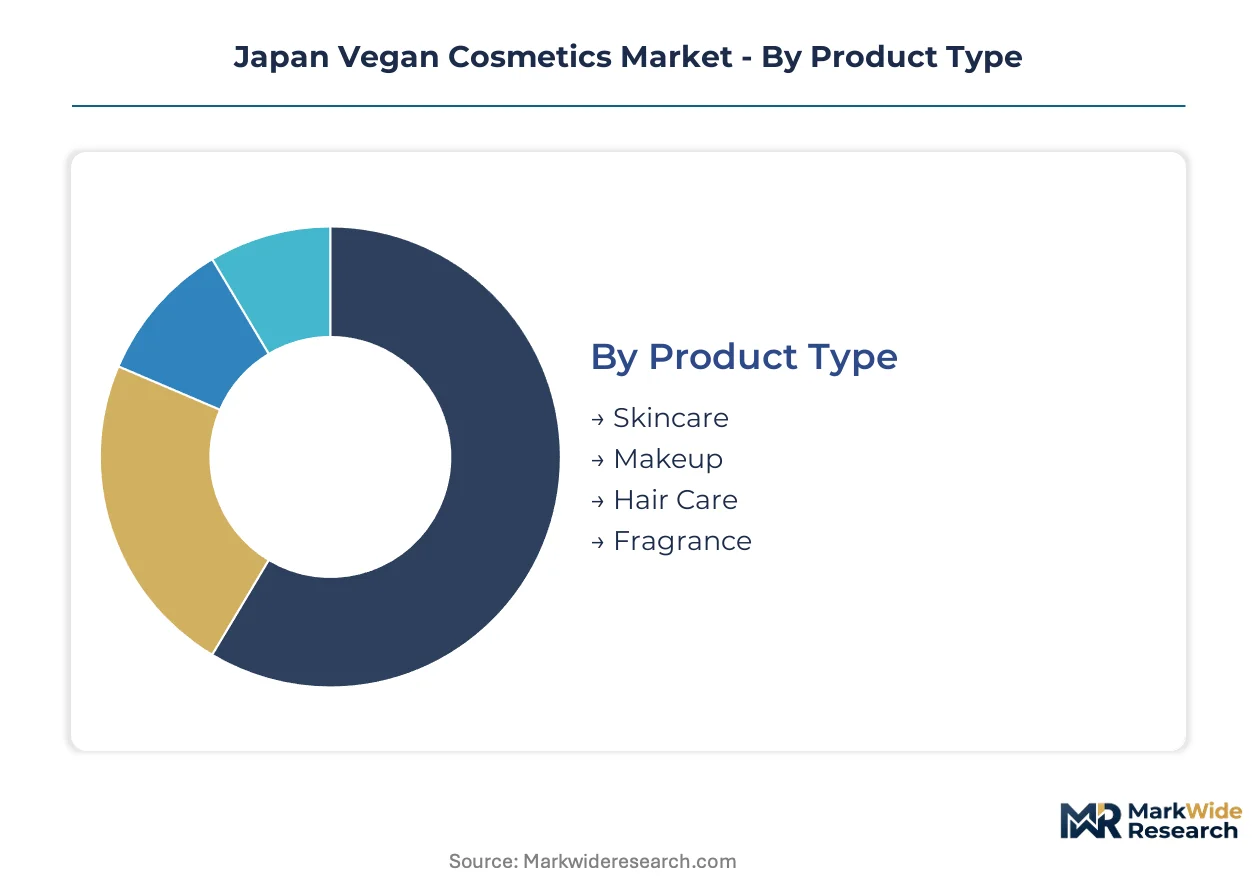
Segmentation in Japan's vegan cosmetics market reveals how ethical positioning intersects with formulation technology and channel economics. Distinct margin profiles emerge across product categories, with biotech-enabled segments commanding premium pricing while conventional plant-based formulations face input cost volatility.
Product Type:
Premium pricing power concentrates in segments where fermentation-derived actives justify per-unit premiums, while mass-market categories compete on supply chain transparency.
- Skincare:Fermentation-derived ceramides and peptides dominate formulations, with serum and concentrated treatment subcategories absorbing the bulk of biotech R&D investment. Tokyo and Osaka professional women drive repeat purchase frequency through subscription replenishment models.
- Makeup:Color cosmetics face steeper vegan reformulation challenges due to carmine and beeswax dependencies. Kanto corridor retailers now mandate batch-level vegan verification for shelf placement, compressing margins on mid-tier brands.
- Hair Care:Plant-derived surfactants replace petroleum-based emulsifiers in shampoo formulations.
- Fragrance:Synthetic musks and fermentation-derived aroma compounds substitute for animal-derived fixatives.
Skincare holds installed capacity. Serum formulations within skincare are rotating up the share rankings.
Formulation:
Volume pull varies sharply by texture category, with concentrated formats capturing disproportionate margin through reduced packaging and shipping intensity.
- Serum:High-actives concentration enables premium positioning while satisfying demand for simplified routines. Young professional women in metropolitan Japan prioritize single-step efficacy, driving fastest volume expansion in this texture category.
- Cream:Traditional moisturizer formats face reformulation pressure to replace lanolin and squalane from shark liver sources. Kansai corridor pharmacies report strongest trial-to-repeat conversion for plant-derived cream alternatives.
- Gel:Lightweight textures suit humid summer conditions in Japanese coastal cities.
- Balm:Occlusive formats concentrate in lip and targeted treatment applications.
Cream maintains broadest household penetration. Serum is climbing the fastest among texture formats.
Distribution Channel:
Channel economics determine which certification investments brands can recover, with direct-to-consumer models capturing margin pools unavailable to concession-dependent retailers.
- Online Retail:Algorithm-curated regimen recommendations displace counter-based consultations, enabling direct education on METI-compliant vegan verification standards. Subscription models eliminate department store concession fees while building recurring revenue.
- Specialty Stores:Vertically controlled retail channels like Lush demonstrate that transparent ingredient sourcing commands price premiums. Staff training costs for vegan certification education constrain expansion beyond major metropolitan corridors.
- Supermarkets:Mass-market placement requires ISO 16128 compliance documentation that strains smaller domestic brand quality assurance bandwidth.
- Pharmacies:Healthcare-adjacent positioning suits dermatological efficacy claims for sensitive-skin vegan formulations.
Online Retail captures expanding margin pools. Specialty Stores are gaining share in the Kansai corridor expansion.
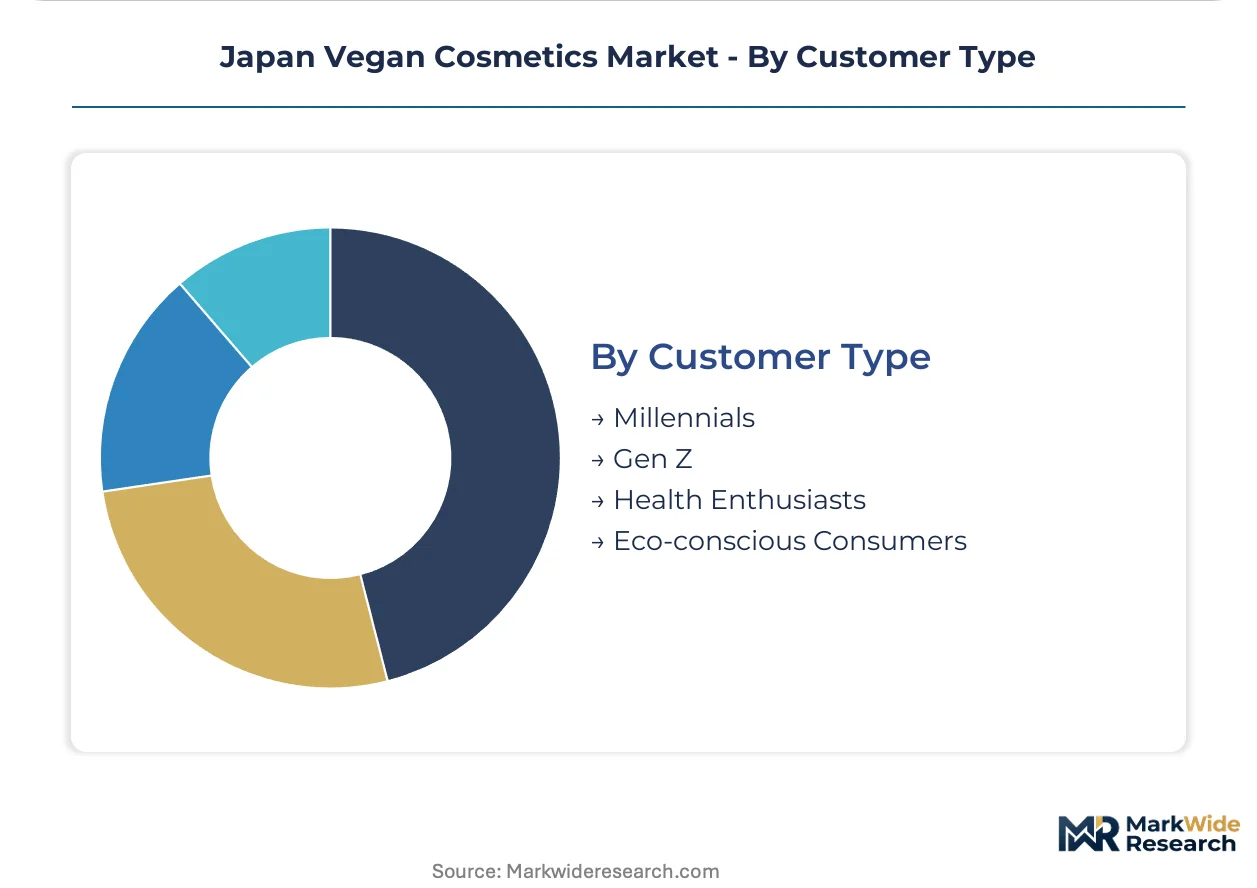
Customer Type:
Generational and psychographic segments exhibit divergent willingness-to-pay for verification depth, with professional cohorts prioritizing supply chain audit documentation over price sensitivity.
- Millennials:Aging-conscious buyers concentrate spending on premium skincare with documented anti-aging efficacy. This cohort shows highest loyalty to brands with pre-established vegan verification protocols ahead of Consumer Affairs Agency enforcement tightening.
- Gen Z:Digital-native discovery patterns favor social media education on ingredient provenance over traditional retail. Tokyo and Osaka clusters normalize vegan beauty as default, creating concentrated volume pull.
- Health Enthusiasts:Cross-category wellness spending extends to cosmetic ingredient scrutiny.
- Eco-conscious Consumers:Environmental motivation overlaps with but distinct from animal ethics positioning.
Millennials hold established spending capacity. Gen Z is expanding most quickly as a share of vegan beauty purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese vegan cosmetics manufacturers export primarily to South Korea and Taiwan, where K-beauty consumers demand fermentation-derived actives that domestic suppliers cannot yet produce at scale. This trade corridor shapes capacity allocation across Kanto and Kansai production clusters.
Kanto/Tokyo
Young professional women in Shibuya and Ginza normalize vegan beauty as default skincare, creating concentrated volume pull for premium serum formulations. METI's ethical labeling guidelines pressure brands headquartered here to maintain batch-level supply chain documentation. Biotech fermentation platforms cluster in Yokohama and Kawasaki, where Shiseido operates advanced microbial production facilities.
Kansai/Osaka
Aging-conscious buyers in Kyoto and Kobe drive repeat purchase frequency for plant-derived cream alternatives through pharmacy channels. The Consumer Affairs Agency monitors Osaka-based brands against misleading environmental representations with particular intensity. Kao Corporation anchors R&D spending on plant-derived surfactants at its Osaka research center.
Chubu/Nagoya
Industrial automation suppliers in Aichi Prefecture serve bioreactor equipment needs for fermentation-derived ceramide producers. Regional pharmaceutical manufacturers explore cosmetic ingredient diversification under PMDA-adjacent quality frameworks. Nagoya's logistics infrastructure connects domestic production to Taiwan export markets.
Kyushu
Agricultural cooperatives in Fukuoka and Kumamoto experiment with cold-pressed botanical oil supply for mid-tier vegan formulations. Prefectural economic development agencies subsidize cosmetic ingredient processing facilities to diversify from traditional crop exports. Limited fermentation capacity forces reliance on Kanto bioreactor networks.
Hokkaido
Pristine water sources and cool climate conditions attract premium skincare brands seeking "clean" manufacturing narratives for domestic and export positioning. Dairy cooperative infrastructure repurposes fermentation expertise toward microbial cosmetic ingredient trials. Sapporo serves as a test market for vegan positioning among health-enthusiast consumer segments.
Japan Vegan Cosmetics Market Competitive Landscape
Player mix skews toward diversified personal care conglomerates with captive biotech fermentation capacity. Market structure concentrates around three to four integrated manufacturers controlling premium distribution channels through department store concessions. Strategic archetypes include: fermentation-platform specialists leveraging Yokohama and Osaka bioreactor infrastructure; vertically controlled retail operators eliminating intermediary markups through direct channels; and mid-tier domestic brands competing on ISO 16128 compliance documentation. Dominant competitive moves center on R&D pipeline rebuilding around microbial production platforms and subscription-based direct-to-consumer channel expansion.
Among diversified Japanese personal care conglomerates, Shiseido Co Ltd and Kao Corporation exemplify the fermentation-platform archetype through captive research infrastructure. Lush Fresh Handmade Cosmetics occupies a distinct position as a vertically controlled retail operator with transparent ingredient sourcing protocols. These three entities represent the primary competitive vectors shaping formulation standards, channel economics, and verification protocols across the market.
| Leading Market Players |
|---|
| L'Oreal S.A. |
| AINOKI |
| Shiseido Co Ltd |
| REI COSMETICS JAPAN |
| KIWABI |
| Kao Corporation |
| Pols Orbis Holdings Inc |
| Lush Fresh Handmade Cosmetics |
| Kose Corporation |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day fermentation batch cycles in Kanagawa and Osaka bioreactor facilities concentrate supply-side pricing power among three integrated manufacturers, while department store concession fees absorb 35-45 percent of wholesale value across premium skincare tiers.
Pricing Analysis
Prior-generation plant-oil formulations face accelerating price erosion against next-generation fermentation-derived ceramides and peptides. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and biotech input intensity, with METI-compliant batch documentation commanding 15-25 percent premiums. Cost compression in mid-tier cream formulations intensifies because jojoba and squalane input volatility squeezes gross margins. Mass-market supermarket buyers exhibit highest price sensitivity, while subscription-channel millennials accept premium positioning for serum formats with documented supply chain audits.
Supply Chain Analysis
Japan and South Korea anchor fermentation-derived active production, with Taiwan absorbing export volumes for K-beauty brands lacking domestic bioreactor scale. Cold-pressed botanical oils draw from California and Mediterranean agricultural cooperatives, while synthetic peptides rest on Kanagawa microbial production platforms. Single-source bioreactor concentration in Yokohama and Osaka creates geographic vulnerability to prefectural logistics disruptions. Distribution runs through vertically controlled specialty retail and algorithm-curated direct-to-consumer subscription channels, bypassing traditional department store concession markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from biotech-enabled entrants collapsing the efficacy gap between plant-derived and conventional cosmetic chemistry, forcing defensive repositioning around captive fermentation infrastructure.
For Market Incumbents: Shield premium positioning by deepening backward integration into Yokohama and Osaka bioreactor networks, locking in fermentation capacity ahead of formulation chemist scarcity. Accelerate ISO 16128 certification investment to preempt Consumer Affairs Agency enforcement tightening on misleading vegan claims. Defensive patent filings around microbial ceramide production processes deter new entrant replication. For New Entrants and Emerging Players: Subscription-based regimen curation represents the most penetrable service-layer gap, as incumbents under-serve algorithm-personalized replenishment demand from Tokyo and Osaka professional women. Target Kansai corridor pharmacy channels in Kyoto and Kobe where vegan positioning remains novel versus saturated Kanto retail environments. Launch with direct-to-consumer education on METI-compliant verification standards to bypass department store concession barriers. For Investors and Strategic Acquirers: Long-term, this sits as a fermentation-platform consolidation play because biotech-enabled manufacturing advantages compound over conventional formulation expertise. Acquisition targets include domestic brands with pre-established vegan verification protocols and distressed mid-tier players facing ISO 16128 compliance friction. Monitor Consumer Affairs Agency enforcement actions as the signal indicating regulatory clarity premium capture windows.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Platform Expansion | Captive bioreactor capacity in Kanagawa secures supply chain control against input volatility. |
| Direct-to-Consumer Subscription Launch | Eliminates department store concession fees while building recurring revenue through algorithm-curated regimens. |
| ISO 16128 Certification Investment | Preempts retail buyer due diligence requirements and Consumer Affairs Agency enforcement risk. |
| Kansai Corridor Distribution Buildout | Exploits underpenetrated Kyoto and Kobe demand pools before incumbent saturation. |
| Formulation Chemist Capability Buildout | Addresses 18-24 month cross-training timelines for microbial fermentation expertise. |
Research Methodology
Desk research of METI regulatory filings, Consumer Affairs Agency enforcement records, and ISO 16128 certification databases preceded structured interviews with brand managers at personal care conglomerates, pharmacy category buyers in Kanto and Kansai corridors, fermentation platform R&D directors, and subscription channel operations leads. Secondary validation drew from customs trade data on cosmetic ingredient imports, retail audit databases tracking channel shift patterns, and SEC 10-K disclosures from listed personal care manufacturers. Bottom-up volume modeling across product type, formulation texture, and distribution channel segments triangulated against top-down market sizing from production capacity and export flow analysis.
Variance decomposition across product type, formulation technology, distribution channel, and customer generational cohort segments structured the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by pricing tier concentration, with biotech fermentation adoption curves and METI regulatory interpretation timelines as primary forecast inputs. Cross-segment elasticity modeling captured substitution effects between serum and cream formats, as well as online retail channel share capture from department store concessions.
Underlying assumptions cover sustained biotech fermentation cost decline curves, stable METI ethical labeling enforcement intensity, and continued K-beauty export demand pull, with deviation risk concentrated in plant oil commodity price spikes and Consumer Affairs Agency interpretation shifts on vegan claim substantiation. Recalibration cycles align with material shifts in bioreactor capacity utilization, regulatory enforcement patterns, and generational cohort spending transition milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Vegan Beauty Products Market
Vegan Cosmetics
India Vegan Cosmetics Market
Vegan Cosmetics
Mexico Vegan Cosmetics Market
Vegan Cosmetics
France Vegan Cosmetics Market
Vegan Cosmetics
Canada Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
Vegan Face Cream Market
Vegan Cosmetics
Organic Cosmetics Market
Vegan Cosmetics
South Korea Vegan Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market
Vegan Cosmetics
Europe Vegan Cosmetics Market
Vegan Cosmetics
Italy Vegan Cosmetics Market
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
Chile Vegan Cosmetics Market
Vegan Cosmetics
Asia-Pacific Vegan Cosmetics Market
Vegan Cosmetics
Brazil Vegan Cosmetics Market