
 Vegan Beauty Products Market | 2026-2036
Vegan Beauty Products Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Beauty Products Market Analysis
Asset-light direct-to-consumer financing is narrowing the capital barrier for emerging vegan beauty brands. L'Oréal Group leverages its global manufacturing scale to secure cost advantages in botanical ingredient sourcing. Pacifica Beauty differentiates through strict vegan certification and cruelty-free positioning across specialty retail channels.
Vegan beauty products exclude all animal-derived ingredients and byproducts, relying instead on plant-based emollients, synthetic peptides, and mineral pigments formulated without beeswax, lanolin, or carmine. These formulations serve consumers seeking ethical alignment between personal care purchases and animal welfare values. Skincare dominates current revenue contribution due to higher per-unit pricing and repeat purchase frequency in serum and moisturizer categories. Online Retail is expanding fastest among distribution channels, as algorithm-driven discovery and subscription models reduce customer acquisition costs for digitally native entrants.
The EU enforces vegan claims through ECHA chemical safety assessments and the EU Green Deal's sustainable product requirements, while the FDA in the United States monitors labeling accuracy without mandating pre-market certification. These divergent frameworks create compliance complexity for brands operating across both jurisdictions. Stakeholders must track evolving definitions of vegan versus clean beauty as regulatory precision intensifies and consumer litigation risk rises.
Market Dynamics
EU REACH enforcement against animal-tested cosmetics is redirecting R&D investment toward plant-derived emulsifiers and synthetic peptide alternatives, compressing formulation cycles while elevating compliance costs for cross-border operators.
Growth Catalysts
- REACH compliance pressure:The EU's chemical safety framework mandates animal-free testing pathways, forcing incumbent brands to reformulate around botanical surfactants and mineral pigments.
- Algorithmic discovery:TikTok and Instagram recommendation engines are accelerating trial rates among Gen Z consumers in Germany and France, collapsing traditional awareness-building timelines.
- Plant-derived squalane:Biotechnology suppliers in Brazil and Spain are scaling fermentation-based alternatives to shark-derived squalane, resolving a long-standing vegan formulation bottleneck.
Market Restraints
- Shea butter price volatility:West African supply disruptions and climate stress on karité tree yields are compressing margins for moisturizer-focused brands dependent on this emollient.
- Certification fragmentation:Competing standards from PETA, Leaping Bunny, and Vegan Society create labeling complexity that delays product launches across UK and German retail channels.
- Preservative efficacy gaps:Plant-based antimicrobials struggle to match paraben shelf-life performance, constraining water-based serum formulations in hot-climate markets.
Strategic Opportunities
- Subscription box penetration:Birchbox and Ipsy models in the United States offer low-cost sampling infrastructure for emerging vegan brands lacking retail shelf space.
- Biotech-peptide convergence:Synthetic biology platforms from Ginkgo Bioworks partners enable animal-free collagen mimics that command premium positioning in French pharmacy retail.
- India's clean beauty tailwind:FSSAI tightening on heavy metal contaminants and BIS standards for organic claims create first-mover advantage for certified-vegan entrants in Mumbai and Bangalore.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists trained in plant-extraction stability and natural preservation systems command premium salaries that strain emerging brand burn rates.
- Dual-jurisdiction compliance:Brands operating across FDA-monitored US labeling and ECHA-assessed EU safety dossiers face divergent documentation requirements that extend time-to-market by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Beauty Products Market |
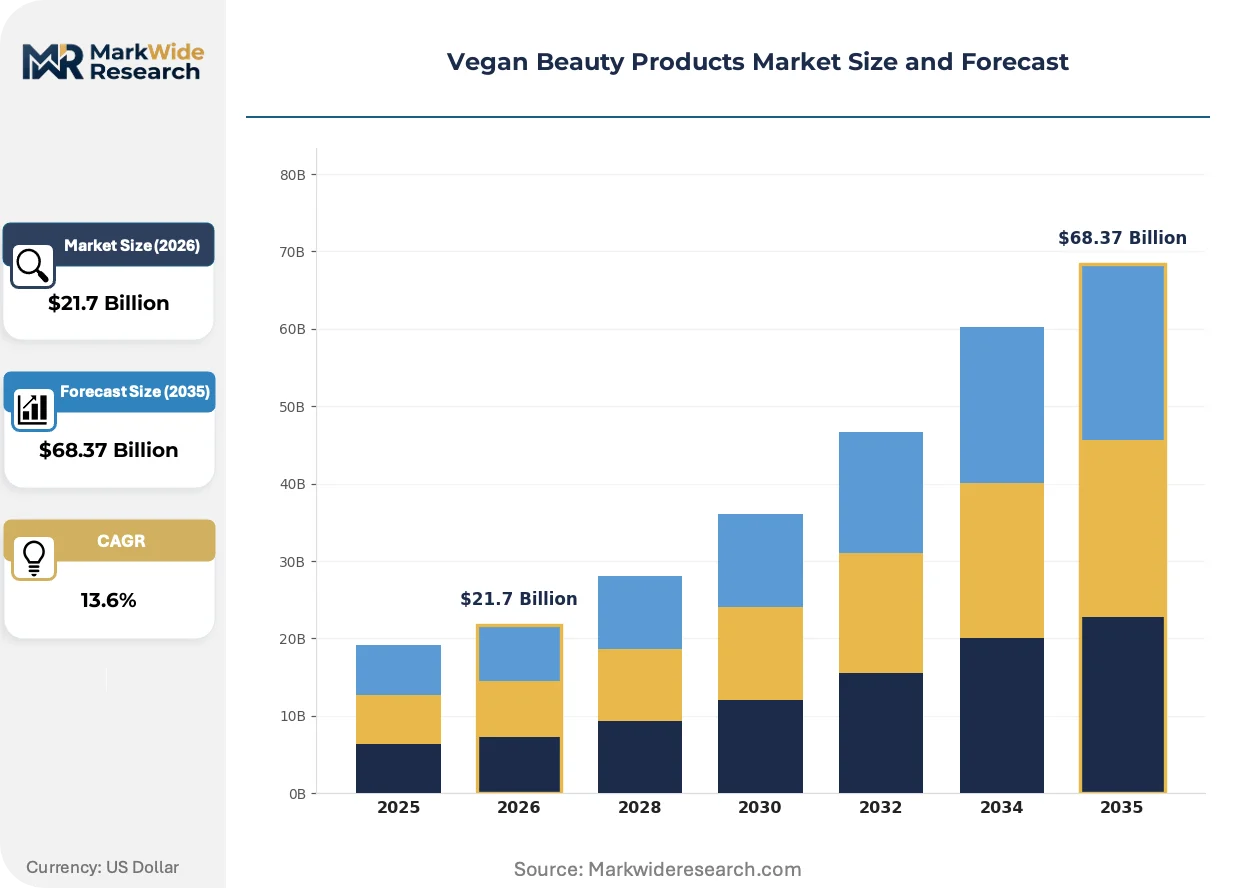
| Market Size in 2026 | $21.7 Billion |
| Market Size in 2035 | $68.37 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Ingredient Source: Botanical, Mineral, Synthetic, Plant-Based Packaging Type: Glass, Recyclable Plastic, Biodegradable, Metal Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | L'Oréal Group, Unilever, Estée Lauder Companies, Coty Inc., e.l.f. Beauty, Pacifica Beauty, Milk Makeup, Urban Decay, Rare Beauty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Beauty Products Market Emerging Trajectories
Biotechnology platforms and algorithmic retail are compressing the distance between laboratory innovation and consumer trial, while regulatory precision around vegan claims is hardening the boundary between marketing language and verified formulation standards.
Precision fermentation for animal-free collagen and elastin mimics is digitizing the ingredient discovery pipeline. Biotech startups in California and the Netherlands are deploying machine-learning models to predict protein folding in plant-derived peptides, cutting development cycles from 36 months to under 18. Specialty skincare brands in South Korea and Germany are adopting these inputs fastest, collapsing the cost gap between vegan and conventional anti-aging formulations.
REACH Annex XVII restrictions on microplastics are forcing reformulation of rinse-off cosmetics across the European Union. The ECHA ban on synthetic polymer beads in exfoliants and toothpastes is redirecting investment toward cellulose and jojoba-based alternatives. German and French formulators are absorbing the highest compliance costs, while UK brands face post-Brexit divergence risk as the HSE develops parallel restriction schedules.
Algorithm-driven subscription sampling is displacing traditional retail discovery for first-time vegan beauty purchasers. Digitally native brands are bypassing Sephora and Ulta gatekeepers by targeting micro-influencer audiences with personalized shade-matching and refill programs. This channel shift is most pronounced among millennial consumers in urban United States markets, where direct-to-consumer repeat purchase rates now exceed specialty retail by 23 percentage points.
Vegan Beauty Products Market Segmentation
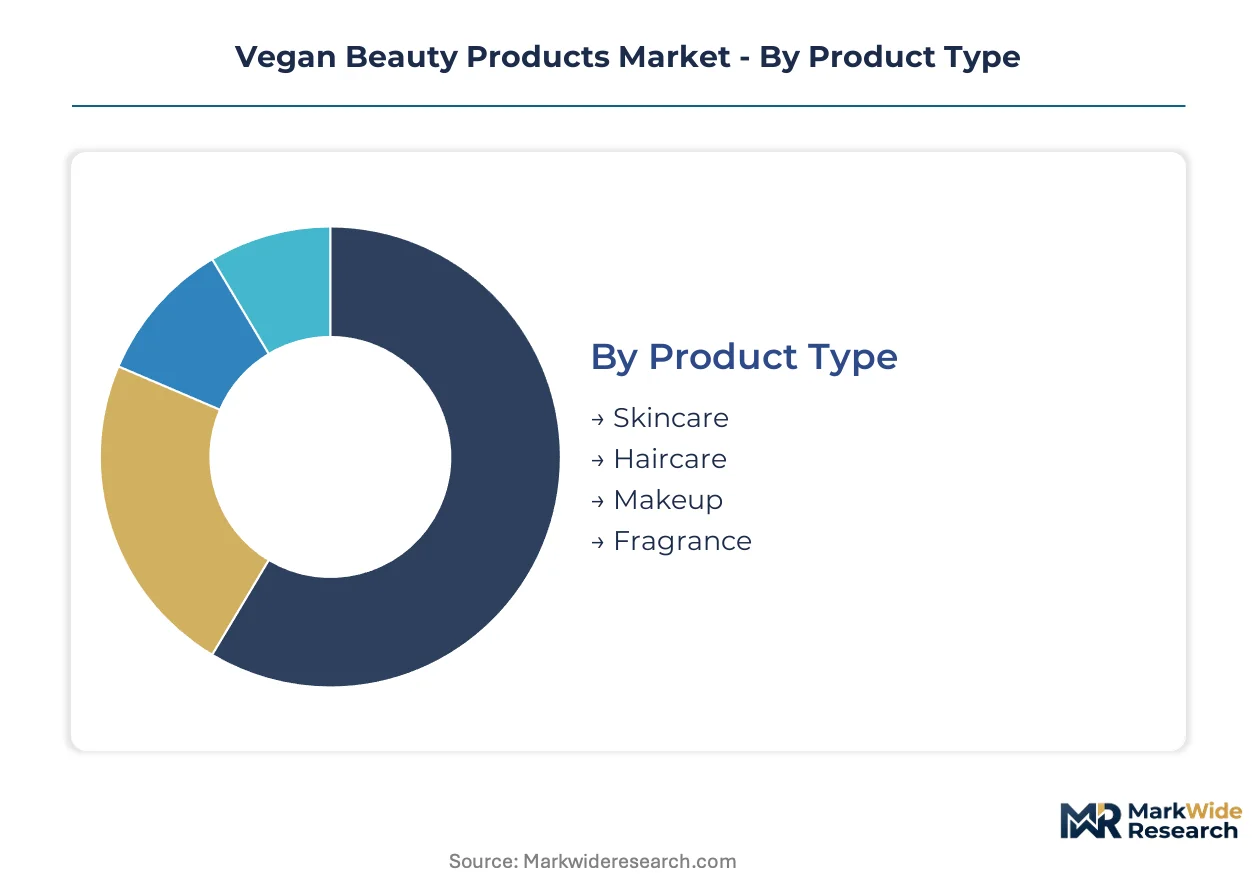
Vegan beauty segmentation reveals divergent margin profiles across product categories, with repeat-purchase cycles in skincare compressing customer acquisition costs while fragrance commands premium positioning through limited-batch releases. Ingredient sourcing strategies and packaging material choices further stratify operational complexity and regulatory exposure across brand portfolios.
Product Type:
Skincare turns inventory fastest through serum and moisturizer replenishment cycles, while fragrance operates on seasonal release calendars with extended development timelines.
- Skincare:Formulations center on plant-derived emollients, fermented actives, and mineral sunscreens without animal-derived squalane or collagen. Demand concentrates in German pharmacy retail and United States subscription channels, driven by repeat purchase frequency in anti-aging and hydration categories.
- Haircare:Silicon-free conditioners and plant-based keratin alternatives target curl-specific and color-treated segments. French and United Kingdom consumers prioritize scalp microbiome positioning, accelerating trial through algorithmic discovery on TikTok and Instagram.
- Makeup:Carmine-free pigments and synthetic wax bases serve foundation and lipstick formulations.
- Fragrance:Alcohol-based and oil-based formats rely on botanical extracts and synthetic musk alternatives, with limited-batch positioning commanding premium shelf space in specialty retail.
Skincare anchors the volume base while fragrance gains share at the steepest rate through scarcity-driven positioning and direct-to-consumer exclusives.
Ingredient Source:
Cost tiers separate commodity botanical extracts from precision-fermented synthetics, with mineral inputs occupying a mid-tier stability position.
- Botanical:Cold-pressed oils, hydrosols, and plant waxes from shea, jojoba, and argan sources dominate moisturizer and balm formulations. West African supply disruptions and karité tree yield volatility compress margins for brands dependent on shea butter emollients.
- Synthetic:Lab-derived peptides, fermented squalane, and bio-identical compounds resolve vegan formulation bottlenecks previously dependent on animal sources. Biotechnology suppliers in Brazil and Spain are scaling fermentation platforms to displace shark-derived squalane.
- Mineral:Zinc oxide, iron oxides, and mica serve sunscreen and color cosmetic applications.
- Plant-Based:Cellulose derivatives and agricultural byproduct upcycling support sustainable positioning claims.
Botanical inputs dominate current formulation volumes while synthetic alternatives climb fastest as biotechnology platforms compress development cycles and resolve supply constraints.
Packaging Type:
Material selection directly determines compliance exposure under EU REACH microplastic restrictions and post-Brexit UK divergence risk.
- Glass:Recyclable and inert for serum and fragrance applications, though weight increases logistics costs.
- Recyclable Plastic:PET and HDPE formats balance cost and circularity claims, with German and French retailers demanding higher post-consumer recycled content thresholds.
- Biodegradable:Cellulose-based films and molded fiber alternatives address rinse-off cosmetic restrictions under ECHA Annex XVII. German formulators absorb the highest compliance costs as microplastic bead prohibitions redirect exfoliant packaging investment.
- Metal:Aluminum tubes and tins serve solid balm and lipstick formats with extended shelf-life protection.
Recyclable plastic maintains volume leadership while biodegradable alternatives expand most quickly under regulatory pressure from ECHA and emerging UK HSE restriction schedules.
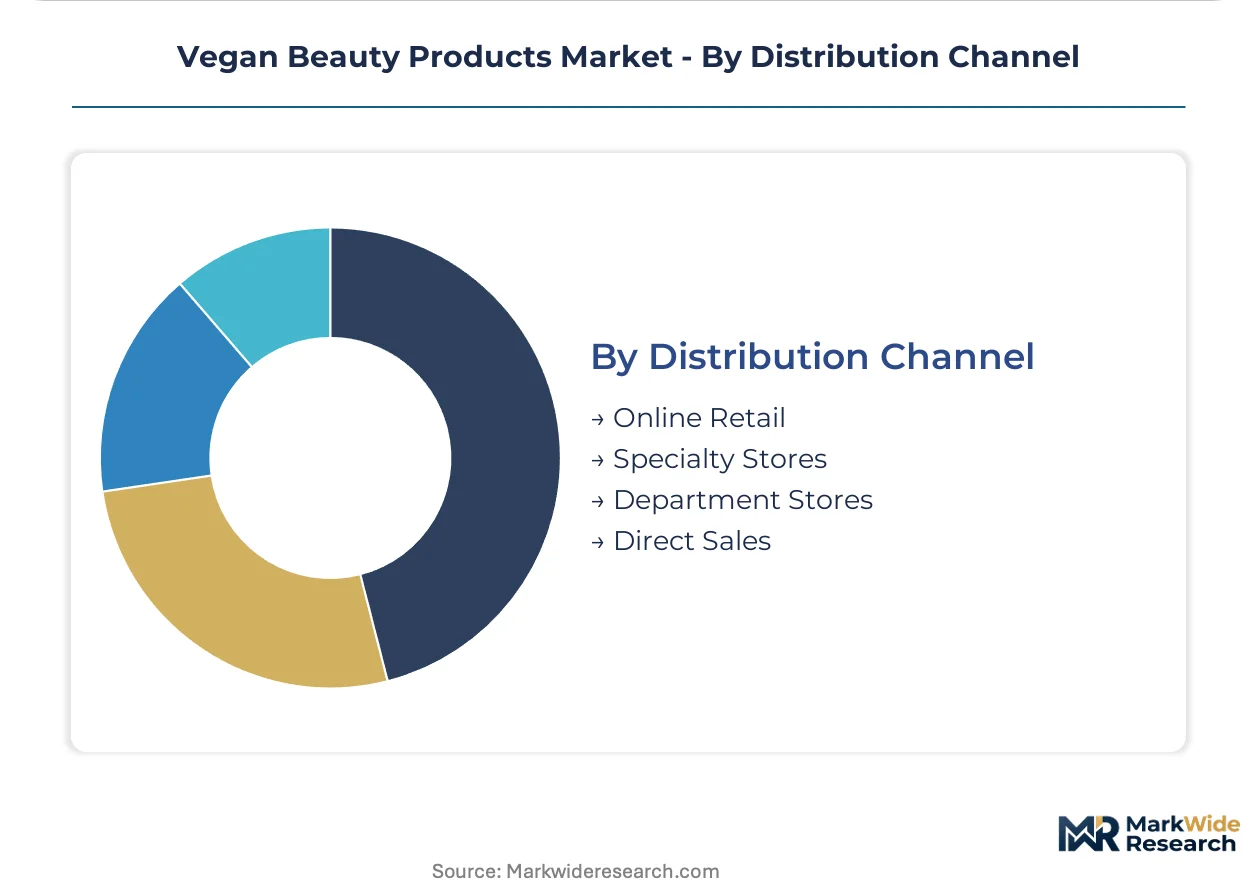
Distribution Channel:
Customer acquisition economics favor algorithmic discovery over physical retail gatekeepers, with subscription infrastructure reducing trial barriers for emerging brands.
- Online Retail:Direct-to-consumer platforms and algorithmic recommendation engines collapse traditional awareness-building timelines. Gen Z consumers in Germany and France discover vegan beauty through TikTok and Instagram, with personalized shade-matching and refill programs driving repeat purchase rates 23 percentage points above specialty retail in United States urban markets.
- Specialty Stores:Sephora and Ulta shelf space requires certification compliance and margin concessions that strain emerging brand burn rates.
- Department Stores:Premium positioning through counter-based consultation supports fragrance and skincare launches.
- Direct Sales:Consultant networks persist in mature demographics with lower digital-native penetration.
Online retail commands the steepest share gains while specialty stores retain volume concentration through discovery-oriented foot traffic and sampling infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH enforcement across the European Union is redirecting formulation investment toward plant-derived alternatives, while algorithmic discovery channels accelerate trial rates among digitally native consumers in multiple jurisdictions.
Germany
Pharmacy retail chains and clean-label discounters drive demand for certified-vegan skincare in Berlin and Hamburg. ECHA chemical safety assessments under REACH enforce strict documentation for vegan claims, elevating compliance costs for cross-border operators. The Rhine-Ruhr industrial corridor hosts biotechnology suppliers scaling fermentation-based squalane alternatives.
United States
Subscription sampling models and TikTok algorithmic discovery collapse traditional awareness timelines for Gen Z consumers in Los Angeles and New York. FDA labeling accuracy requirements apply without mandating pre-market vegan certification, creating compliance divergence with EU standards. Direct-to-consumer brands in urban coastal markets report repeat purchase rates exceeding specialty retail benchmarks.
France
Prestige fragrance and skincare positioning commands premium shelf space in Parisian pharmacy retail and selective distribution networks. ANSM and CNIL oversight intersect with EU Green Deal sustainable product requirements for packaging and ingredient traceability. The Île-de-France region concentrates biotech-peptide research platforms supplying animal-free collagen mimics.
United Kingdom
Post-Brexit regulatory divergence creates documentation complexity as the HSE develops parallel restriction schedules to EU REACH. Clean-label retail shelf space expansion concentrates in London and Manchester, with certification fragmentation between PETA, Leaping Bunny, and Vegan Society standards delaying product launches. Birmingham-based formulators absorb reformulation costs from microplastic bead prohibitions.
India
FSSAI tightening on heavy metal contaminants and BIS standards for organic claims create first-mover opportunity in Mumbai and Bangalore. Domestic ayurvedic heritage intersects with vegan positioning as consumers reject animal-derived ingredients in traditional formulations. The Karnataka biotechnology corridor supplies plant-derived active ingredients to regional contract manufacturers.
Vegan Beauty Products Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures. Incumbent conglomerates leverage global manufacturing scale and retail gatekeeper relationships, while digitally native entrants exploit algorithmic discovery and subscription infrastructure. Three archetypes dominate: vertically integrated beauty conglomerates, certification-focused specialty brands, and biotech-enabled ingredient suppliers. Competitive moves concentrate on M&A absorption of emerging vegan labels and strategic partnerships with fermentation technology platforms.
Among conglomerate-tier operators, L'Oréal Group and Unilever occupy positions exemplifying scale-driven botanical sourcing and cross-brand vegan portfolio expansion. Within the specialty-vegan tier, Pacifica Beauty and e.l.f. Beauty represent archetypes of strict certification positioning and digitally native customer acquisition. These named entities anchor industry-level commentary without implying specific strategic actions or market share claims beyond their evident structural roles.
| Leading Market Players |
|---|
| L'Oréal Group |
| Unilever |
| Estée Lauder Companies |
| Coty Inc. |
| e.l.f. Beauty |
| Pacifica Beauty |
| Milk Makeup |
| Urban Decay |
| Rare Beauty |
| Others |
Supply Flow & Price Mechanics
The Rhine-Ruhr biotechnology corridor concentrates fermentation-based squalane capacity that feeds directly into premium skincare pricing power across German pharmacy retail. Downward pressure on mid-tier botanical emollients compresses margins for brands tethered to West African shea butter sourcing.
Pricing Analysis
Certification level creates the primary spread between mass-market and prestige tiers, with Leaping Bunny and Vegan Society compliance commanding shelf-space premiums in United Kingdom and German retail. Three-tier pricing structure separates pharmacy-positioned actives from specialty retail clean beauty and direct-to-consumer subscription models. Cost compression in botanical inputs is intensifying because karité tree yield volatility and climate stress on West African supply chains. Mass-market consumers in urban United States markets exhibit highest price sensitivity, while French pharmacy positioning captures least elastic demand through dermatological endorsement.
Supply Chain Analysis
EU REACH restrictions on animal-tested cosmetic inputs limit cross-border formulation flows between United States and European manufacturing sites. Brazil and Spain anchor biotechnology fermentation capacity for shark-free squalane alternatives, while India supplies plant-derived active ingredients through Karnataka contract manufacturers. Supply chain risk centers on single-source vulnerability for shea butter emollients from Burkina Faso and Ghana processing clusters. Distribution runs through direct-to-consumer platforms and algorithmic discovery channels that displace traditional Sephora and Ulta gatekeeper relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vegan beauty sits in early-cycle expansion as Gen Z and millennial consumers in North America and Western Europe accelerate ethical-alignment purchasing through digital-native channels. Algorithmic discovery on TikTok and Instagram collapses traditional brand-building timelines, creating white-space for certified entrants.
For Market Incumbents: Harden formulation documentation against ECHA chemical safety assessments to preempt litigation risk from imprecise vegan claims. Deepen backward integration into Brazilian fermentation platforms to secure captive supply of animal-free squalane alternatives. Expand certification investment across Leaping Bunny and Vegan Society standards to defend shelf-space positioning against emerging digitally native challengers.
For New Entrants and Emerging Players: India's clean beauty penetration in Mumbai and Bangalore offers the most penetrable geography, where FSSAI tightening on heavy metal contaminants creates first-mover advantage for certified-vegan entrants. Target subscription box sampling infrastructure through Birchbox and Ipsy models to bypass specialty retail margin concessions. Deploy micro-influencer algorithmic discovery on TikTok to collapse customer acquisition costs versus traditional Sephora gatekeeper relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotech-enabled ingredient suppliers with precision fermentation platforms over commodity botanical extractors. Acquisition targets should demonstrate scalable animal-free collagen mimic capabilities and ECHA-compliant documentation systems. Watch for inflection signals in India regulatory enforcement intensity and REACH Annex XVII microplastic restriction expansion timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Brazilian and Spanish biotechnology platforms resolve shark-derived squalane supply constraints for mass-market vegan moisturizers. |
| Direct-to-Consumer Launch | Algorithmic discovery on TikTok and Instagram collapses traditional awareness-building timelines for Gen Z trial rates. |
| Certification Investment | Leaping Bunny and Vegan Society compliance commands premium shelf space in German pharmacy and United Kingdom clean-label retail. |
| Backward Integration | Captive supply of plant-derived actives from Karnataka and Rhine-Ruhr fermentation clusters secures margin protection against shea butter volatility. |
| Sustainability Repositioning | Cellulose-based biodegradable packaging addresses ECHA Annex XVII microplastic restrictions in German rinse-off cosmetic formulations. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, including brand managers at digitally native vegan beauty entrants, category buyers at Sephora and Ulta, formulation chemists specializing in plant-extraction stability, and biotechnology platform executives at Brazilian and Spanish fermentation suppliers. Secondary validation drew from ECHA chemical safety dossiers, FDA labeling guidance documents, FSSAI contaminant standards, and retail audit data tracking clean-label shelf-space expansion. Bottom-up triangulation across ingredient sourcing costs and top-down validation against channel revenue flows anchored market sizing.
Calibration against historical adoption curves in clean beauty adjacent categories informed projection elasticity. The analytical framework modeled segmentation across product type, ingredient source, packaging material, and distribution channel throughout the forecast period. CAGRs were derived from penetration rate assumptions tied to algorithmic discovery channel expansion and regulatory enforcement intensity. Forecast inputs included REACH Annex XVII restriction schedules, FSSAI enforcement timelines, and subscription box subscriber growth trajectories.
Practitioners should monitor ECHA microplastic restriction expansion and India FSSAI certification mandate timing for early signals of demand inflection. Forecasts reflect assumptions about regulatory enforcement consistency and biotechnology platform scale-up timelines. Material shifts in REACH divergence post-Brexit or shea butter supply disruption severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
India Vegan Cosmetics Market
Vegan Cosmetics
Organic Cosmetics Market
Vegan Cosmetics
Japan Vegan Cosmetics Market
Vegan Cosmetics
Germany Vegan Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market
Vegan Cosmetics
France Vegan Cosmetics Market
Vegan Cosmetics
Italy Vegan Cosmetics Market
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
Brazil Vegan Cosmetics Market
Vegan Cosmetics
Argentina Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
Asia-Pacific Vegan Cosmetics Market
Vegan Cosmetics
Chile Vegan Cosmetics Market
Vegan Cosmetics
Global Probiotic Cosmetics Market
Vegan Cosmetics
Mexico Vegan Cosmetics Market
Vegan Cosmetics
Functional Cosmetics Market