
 Saudi Arabia Furniture Market | 2026-2036
Saudi Arabia Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Furniture Market Outlook
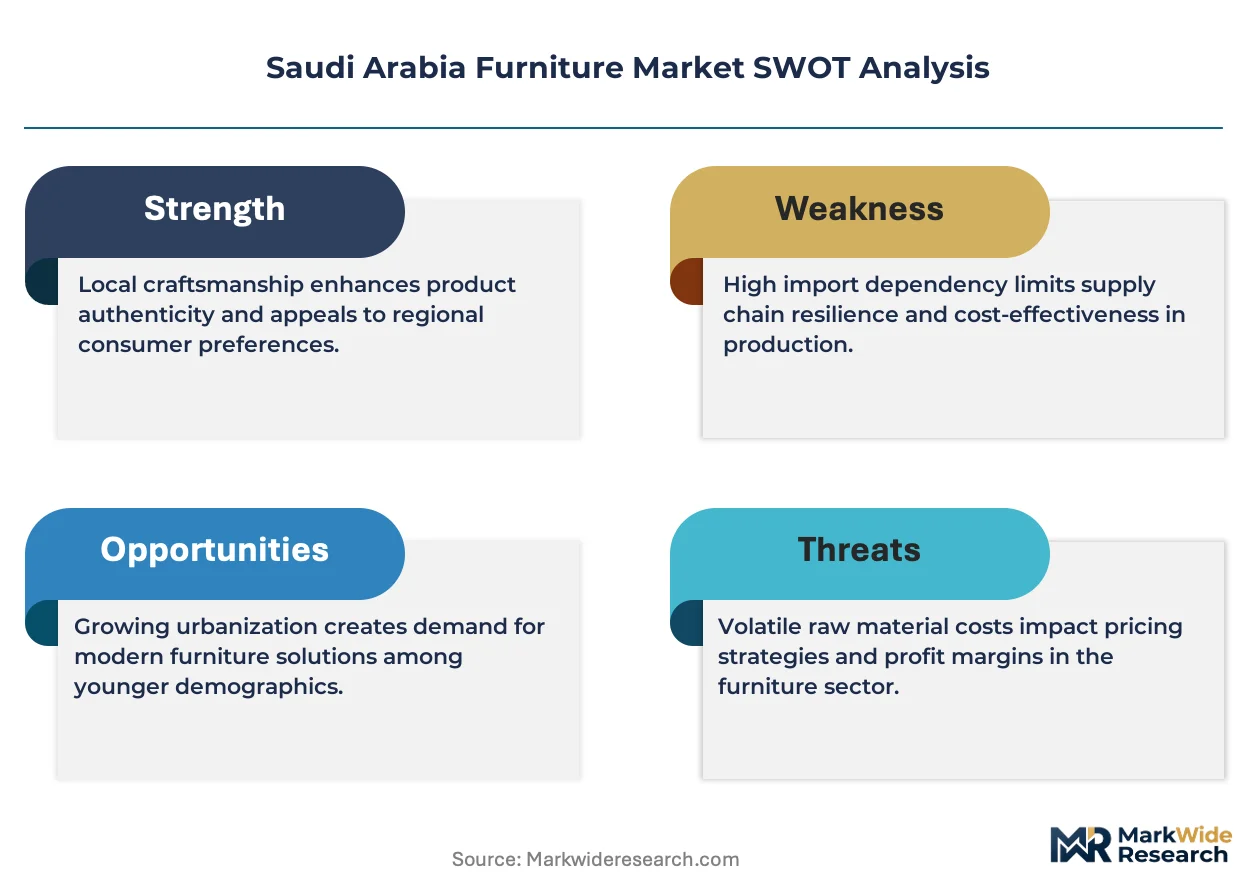
SASO's updated furniture safety and flammability standards is repositioning the cost-of-entry calculus for both domestic manufacturers and importers entering the kingdom. Royal Furniture leverages its established Saudi manufacturing footprint to navigate compliance requirements without freight cost penalties. IKEA anchors its competitive stance through global supply chain scale that absorbs certification overhead across high-volume product lines.
Furniture encompasses movable objects engineered for human support, storage, and spatial organization, typically constructed from wood, metal, plastic, or fabric composites with load-bearing frames and finished surfaces. The category serves residential dwellings, commercial offices, hospitality venues, and institutional facilities through functional and aesthetic spatial solutions. Wood material segments dominate premium residential procurement due to perceived durability and cultural preference for solid construction. Online distribution channels represent the fastest-growing structural avenue as digital payment infrastructure matures and last-mile logistics penetrate secondary Saudi cities.
SASO technical regulations, the Saudi Building Code, and Gulf Standardization Organization (GSO) harmonized requirements collectively govern product safety, chemical emissions, and structural integrity for furniture sold in the kingdom. These frameworks elevate compliance costs for imported goods while creating protected runway for domestic producers meeting certification thresholds. Stakeholders must monitor evolving eco-labeling mandates and circular economy directives that could reshape material sourcing decisions and manufacturing investments.
Market Dynamics
SASO's tightening flammability and safety certification requirements are compressing import windows while Neom and Red Sea Project construction schedules pull specialized hospitality furnishing demand forward. Domestic manufacturers with in-house testing capabilities capture protected runway as compliance timelines extend.
Growth Catalysts
- Vision 2030 hospitality pipeline:Giga-project construction across Riyadh, Jeddah, and western coastal zones generates concentrated procurement for contract-grade seating, modular systems, and outdoor furnishings. Project timelines compress delivery windows.
- SASO technical regulations:Mandatory furniture safety and chemical emission standards create compliance moats for domestic producers with certified laboratory partnerships. Importers face extended pre-shipment verification cycles.
- Digital payment infrastructure:Mada network penetration and buy-now-pay-later integration enable online furniture transactions in secondary cities previously constrained by cash-on-delivery logistics.
Market Restraints
- Import dependency for engineered wood:Saudi Arabia lacks sufficient particleboard and MDF manufacturing capacity, exposing producers to Baltic and Southeast Asian supply volatility and freight rate swings.
- SASO certification bottlenecks:Limited accredited testing laboratory capacity in Riyadh and Jeddah extends product approval timelines, delaying market entry for new import suppliers.
- Skilled upholstery labor scarcity:Manual furniture finishing and textile application expertise concentrates with aging craft workers, constraining domestic production scale-up for premium residential segments.
Strategic Opportunities
- Eastern Province secondary cities:Dammam, Khobar, and Jubail exhibit underpenetrated organized retail presence relative to Riyadh and Jeddah, with rising expatriate housing demand driving furniture procurement.
- Circular economy material mandates:Anticipated SASO eco-labeling extensions would reward domestic manufacturers with recycled content capabilities and localized supply chain footprints.
- Modular flat-pack systems:CNC routing and parametric design software convergence enables mass-customized furniture production at assembly-line economics, compressing last-mile delivery costs.
Industry Challenges
- Certification timeline compression:Giga-project procurement schedules demand SASO compliance documentation within 90-day windows, straining quality assurance workflows and third-party laboratory scheduling.
- Legacy ERP integration:Established Saudi furniture distributors operate on fragmented inventory management systems that resist real-time integration with e-commerce front-ends and logistics platforms.
- Technical textile sourcing complexity:Hospitality-grade fire-retardant upholstery fabrics require specialized supplier relationships in Belgium and Italy, with minimum order quantities misaligned with project-based demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Furniture Market |
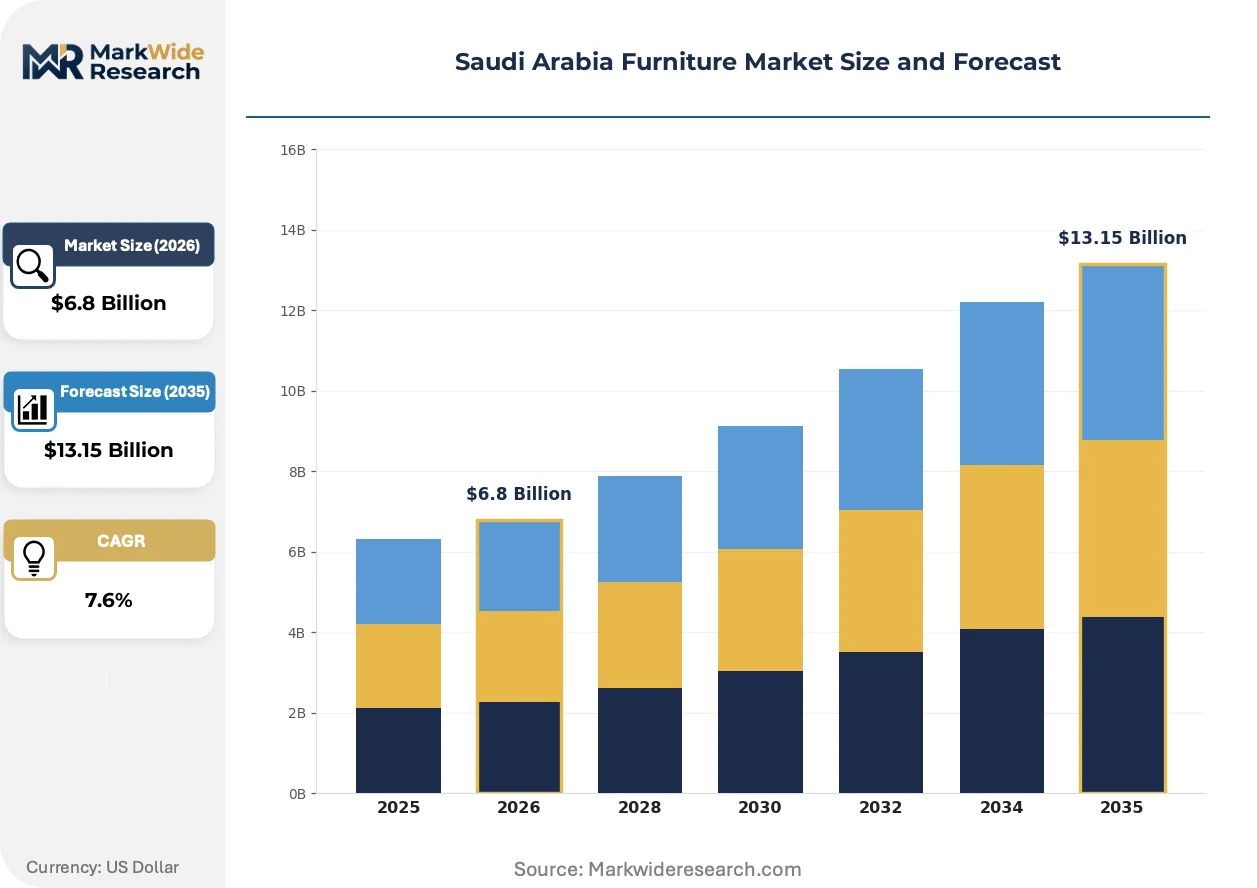
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Cabinets Material: Wood, Metal, Plastic, Fabric End User: Residential, Commercial, Hospitality, Schools Distribution Channel: Online, Retail Stores, Showrooms, Wholesalers |
| Companies Covered | Royal Furniture, Marina Home, IKEA, Pottery Barn, Al-Abdulkader Furniture Co. Ltd, Home Centre, Danube Home, IDdesign, PAN Emirates, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Furniture Market Strategic Shifts
Production technology and procurement behavior are restructuring how Saudi furniture moves from factory floor to installed interior. Three forces are compressing traditional value chain segments.
CNC nesting and robotic edge-banding systems are automating panel processing workflows in Riyadh-based manufacturing facilities. Hospitality contractors and giga-project developers specify these precision-cut components for standardized guest room installations. The technology is automating quality consistency while reducing material waste rates and skilled labor dependency.
SASO's updated furniture flammability standards and the Saudi Building Code's interior finish requirements are tightening chemical emission thresholds for imported products. Domestic manufacturers with in-house testing capabilities compress compliance cycles. Residential developers and hospital operators now prioritize pre-certified local suppliers to avoid project delays.
Direct-to-consumer digital platforms are disintermediating traditional showroom-based distribution in secondary Saudi cities. Younger household formation segments in Tabuk, Hail, and Abha purchase modular systems through mobile-optimized interfaces with augmented reality placement tools. Riyadh-based logistics providers now operate dedicated furniture fulfillment centers to serve this channel expansion.
Saudi Arabia Furniture Market Segmentation
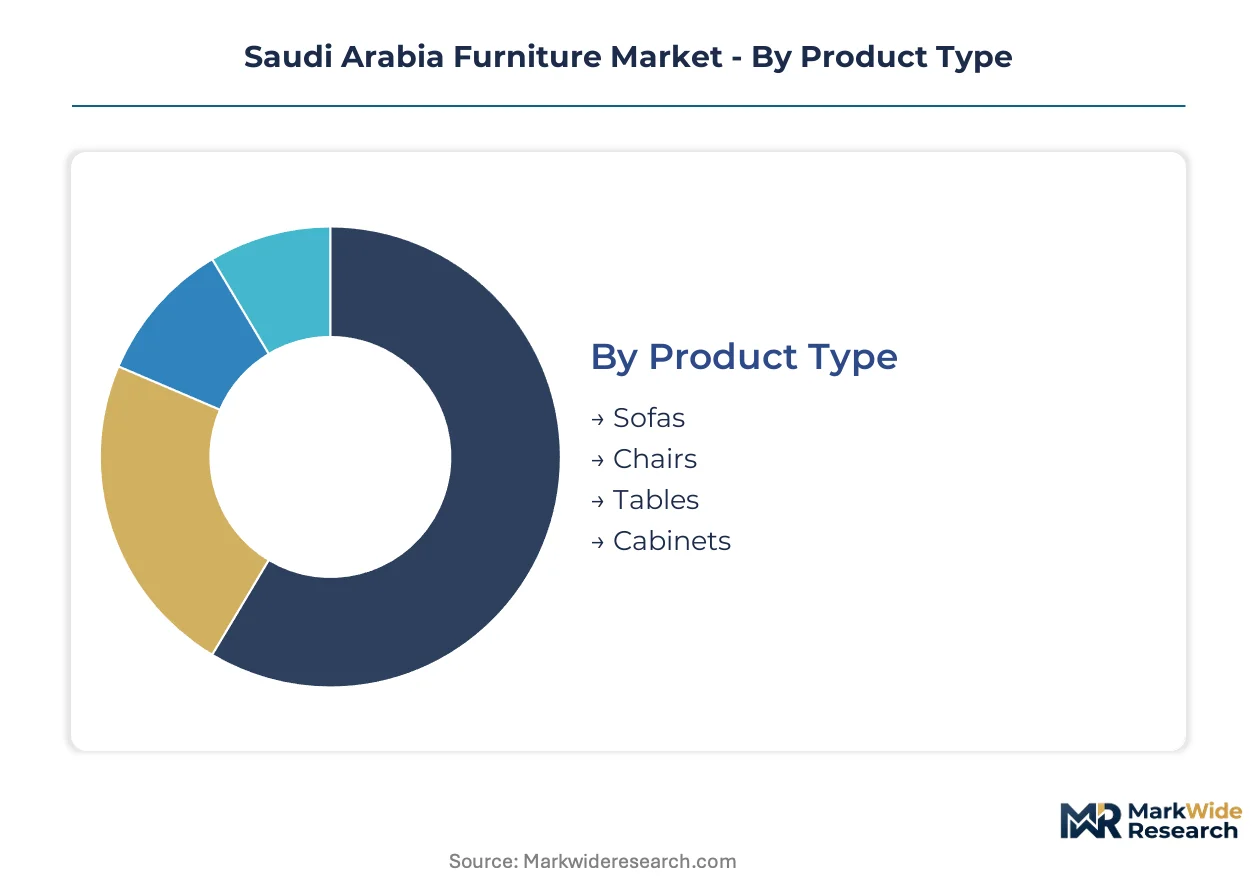
Segmentation reveals where capital deployment and compliance investments concentrate across Saudi Arabia's furniture value chain. Procurement patterns diverge sharply between giga-project hospitality contracts and residential e-commerce transactions.
Product Type:
Sofas and chairs demand the heaviest upfront tooling investment for frame engineering and upholstery automation. Tables and cabinets require less specialized equipment but compete on material finishing precision.
- Sofas:Multi-component assemblies combining engineered wood frames, suspension systems, and textile upholstery. Hospitality procurement in Riyadh and Jeddah concentrates demand for fire-retardant contract-grade specifications as Vision 2030 projects advance.
- Chairs:Ranging from molded plastic seating to hand-finished hardwood frames with leather or fabric coverings. Office fit-outs across King Abdullah Financial District and secondary city commercial zones drive volume for ergonomic task seating with SASO structural certification.
- Tables:Surface-bearing furniture spanning dining, conference, and occasional use categories. Demand clusters around Neom and Red Sea Project hospitality specifications requiring moisture-resistant outdoor materials.
- Cabinets:Storage systems with hinged, sliding, or open-access configurations. Residential kitchen and wardrobe installations in Riyadh's northern expansion corridors dominate procurement.
Most installed capacity flows through Sofas. Expansion is steepest in Chairs.
Material:
Wood commands premium positioning through cultural preference for solid construction, while metal and plastic segments compete on cost-engineered hospitality specifications. Fabric selection determines final product margin structure through textile sourcing complexity.
- Wood:Solid hardwoods, veneers, and engineered panels including particleboard and MDF. Premium residential procurement in Riyadh favors Saudi-sourced tamarisk and imported oak, though domestic MDF capacity gaps expose manufacturers to Baltic supply volatility.
- Metal:Steel tubing, aluminum extrusions, and powder-coated frames for commercial and outdoor applications. Giga-project outdoor furnishing contracts specify marine-grade aluminum for Red Sea coastal installations.
- Plastic:Injection-molded polypropylene and polycarbonate for mass-market seating and storage. Price-sensitive residential segments in Eastern Province secondary cities absorb high-volume production.
- Fabric:Natural fibers, synthetics, and technical textiles for upholstery applications. Hospitality-grade fire-retardant fabrics from Belgian and Italian suppliers face SASO flammability testing bottlenecks.
Wood retains the dominant revenue share. Fabric is climbing the fastest as upholstery specifications tighten.
End User:
Residential buyers purchase through fragmented retail channels while hospitality and commercial procurement consolidates around contract manufacturers with SASO certification. Schools represent a price-constrained institutional segment with standardized specifications.
- Residential:Individual household procurement spanning first-time buyers in Riyadh's developing suburbs and replacement purchases in established Jeddah neighborhoods. Digital payment maturity enables online transactions previously constrained by cash-on-delivery logistics.
- Commercial:Office, retail, and healthcare facility furnishings with durability specifications and bulk procurement terms. King Abdullah Financial District and Jeddah Economic City developments concentrate demand for modular workstation systems.
- Hospitality:Hotels, resorts, and food-service venues requiring contract-grade durability and standardized guest room configurations. Neom, Red Sea Project, and Qiddiya construction schedules compress delivery windows.
- Schools:Educational institution procurement through centralized government tendering with stringent cost ceilings and local content preferences. Classroom and administrative furniture specifications prioritize longevity over design differentiation.
Hospitality captures the highest contract values. Residential delivers the steepest expansion trajectory through e-commerce penetration.
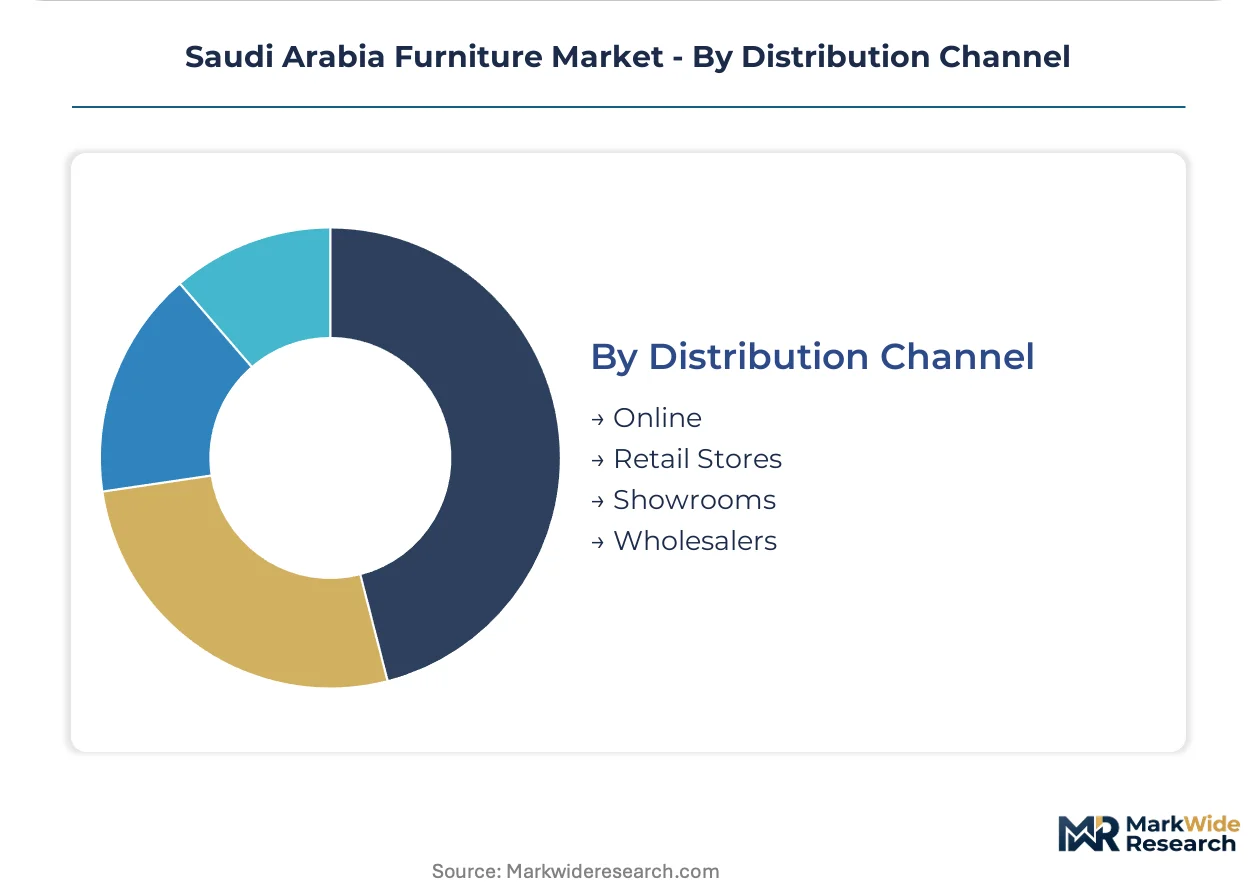
Distribution Channel:
Online platforms disintermediate traditional showroom networks in secondary cities while wholesalers retain leverage over project-based hospitality procurement. Retail stores face margin compression from rent escalation in prime Riyadh and Jeddah locations.
- Online:Direct-to-consumer digital platforms with mobile-optimized interfaces and augmented reality placement tools. Tabuk, Hail, and Abha household formation segments drive growth as dedicated furniture fulfillment centers expand last-mile coverage.
- Retail Stores:Organized multi-brand and single-brand outlets with physical product examination and immediate delivery. Eastern Province cities including Dammam and Khobar exhibit underpenetrated organized retail presence relative to Riyadh and Jeddah saturation.
- Showrooms:High-ambience display environments for premium and custom furniture with design consultation services. Luxury residential procurement in Riyadh's Diplomatic Quarter and Jeddah's waterfront districts sustains this channel.
- Wholesalers:B2B distributors serving contractors, developers, and institutional buyers with volume pricing and project logistics coordination. Giga-project procurement teams source through established relationships with SASO-certified wholesale networks.
Wholesalers handle the largest transaction volumes. Online channels are gaining share fastest through payment infrastructure maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's furniture industry traces its commercial origins to Jeddah's Red Sea port infrastructure, where timber imports from Southeast Asia and East Africa first established woodworking clusters serving pilgrimage-driven hospitality demand. Riyadh's subsequent emergence as the administrative capital redirected manufacturing investment inland, creating today's bifurcated geographic structure.
Riyadh
Vision 2030 giga-projects concentrate procurement for contract-grade seating and modular systems across Diriyah Gate and King Abdullah Financial District developments. SASO technical regulations mandate in-country testing for all hospitality furnishings, compressing approval timelines for domestic producers with Riyadh-based laboratory partnerships. Northern expansion corridors including KAFD and Qiddiya access road zones host CNC-equipped panel processing facilities automating guest room component production.
Eastern Province
Dammam and Khobar absorb rising expatriate housing demand from Aramco expansion and petrochemical sector recruitment, driving residential furniture procurement through underpenetrated organized retail channels. The Saudi Building Code's interior finish requirements apply uniformly across the province, elevating compliance costs for imported goods relative to locally certified alternatives. Jubail's industrial city hosts emerging flat-pack assembly operations serving contractor bulk orders with reduced last-mile logistics.
Western Region
Jeddah's historical woodworking heritage persists in custom ateleries serving luxury residential developments along the Corniche and Diplomatic Quarter satellite zones. Red Sea Project construction schedules pull demand forward for marine-grade aluminum outdoor furnishings and moisture-resistant engineered wood. Makkah and Madinah pilgrimage infrastructure renewal sustains specialized contract seating procurement with accelerated replacement cycles.
NEOM Northwest
The linear city's construction timeline generates specialized furnishing requirements for hospitality, residential, and workplace typologies without precedent in Saudi procurement history. NEOM's own sustainability frameworks exceed baseline SASO requirements, creating dual certification burdens for suppliers. Oxagon's planned manufacturing zone targets captive furniture production to reduce import dependency for giga-project fit-outs.
Saudi Arabia Furniture Market Competitive Environment
The competitive structure tilts toward diversified retail conglomerates with multi-brand portfolios and manufacturing-anchored domestic specialists. Market concentration remains moderate, with no single operator commanding dominant share across all product categories and distribution channels. Two strategic archetypes define positioning: vertically integrated Saudi fabricators leveraging SASO compliance proximity, and global retailers deploying scale economics to absorb certification overhead. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as operators seek to secure giga-project procurement relationships ahead of construction peak demand.
Among Saudi-anchored manufacturers, Royal Furniture exemplifies the compliance-integrated archetype through its established domestic production footprint and laboratory partnerships. IKEA anchors the scale-driven global retail tier, absorbing SASO certification costs across high-volume product lines. Al-Abdulkader Furniture Co. Ltd occupies a position within the mid-market fabrication segment, representing traditional Saudi woodworking heritage adapted to contemporary production methods.
| Leading Market Players |
|---|
| Royal Furniture |
| Marina Home |
| IKEA |
| Pottery Barn |
| Al-Abdulkader Furniture Co. Ltd |
| Home Centre |
| Danube Home |
| IDdesign |
| PAN Emirates |
| Others |
Value Chain & Pricing Dynamics
CNC nesting automation and robotic edge-banding deployment across Riyadh manufacturing facilities simultaneously compresses unit production costs and concentrates supply capacity among capital-equipped domestic producers. This technology transition elevates fixed-cost thresholds for market entry while rewarding operators with in-house SASO certification capabilities.
Pricing Analysis
The bundled-versus-unbundled service split separates project-based hospitality procurement from direct-to-consumer residential transactions. Three-tier pricing structure across premium, standard, and economy levels reflects SASO certification grade and volume scale, with premium tiers commanding substantial markups for fire-retardant contract-grade specifications. Price differentiation stems from certification overhead absorption and after-sales installation bundling. Cost compression in the economy tier is intensifying because Baltic MDF supply volatility feeds raw material uncertainty. Residential e-commerce buyers exhibit highest price sensitivity, while giga-project hospitality procurement teams prioritize compliance assurance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Baltic and Southeast Asian engineered wood suppliers, where particleboard and MDF manufacturing concentration exposes Saudi fabricators to freight rate swings and customs clearance delays. Geographic supply concentration centers on Estonia, Latvia, and Malaysia for core panel inputs, with Italian and Belgian mills dominating technical textile upholstery. Raw material dependencies encompass fire-retardant fabric composites, marine-grade aluminum extrusions, and moisture-resistant engineered wood. Regulatory restriction risk manifests through SASO flammability testing bottlenecks that extend pre-shipment verification cycles. Distribution runs through project-based wholesale networks for hospitality contracts and dedicated furniture fulfillment centers for online residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's furniture market functions as a stable compounder, with Vision 2030 giga-project construction schedules generating sustained procurement visibility across hospitality and residential segments.
For Market Incumbents: To counter import certification timeline compression, domestic manufacturers should deepen laboratory partnerships with Riyadh-based SASO-accredited facilities and expand CNC-equipped panel processing capacity in northern Riyadh corridors. Backward integration into Saudi-sourced tamarisk hardwood procurement reduces Baltic supply dependency. For New Entrants and Emerging Players: E-commerce logistics providers represent the critical channel partner type for penetrating secondary cities including Tabuk, Hail, and Abha, where organized retail presence remains underdeveloped relative to Riyadh saturation. Modular flat-pack systems with augmented reality placement tools offer the most penetrable residential entry angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market fabricators with established SASO compliance workflows and aging ownership structures. Long-term viability over a five-to-ten year window hinges on captive giga-project procurement relationships. Monitor NEOM construction milestone announcements as the primary inflection indicator for specialized furnishing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Investment | Compresses approval timelines for domestic producers supplying Vision 2030 hospitality projects. |
| CNC Automation Deployment | Riyadh-based panel processing facilities reduce skilled labor dependency and material waste rates. |
| E-commerce Fulfillment Expansion | Dedicated furniture distribution centers in secondary cities enable digital payment penetration. |
| Backward Integration into Hardwood | Saudi-sourced tamarisk procurement mitigates Baltic MDF supply volatility exposure. |
| Modular Flat-pack Systems | Parametric design software enables mass-customized production at assembly-line economics. |
Study Parameters
Coverage spans Saudi Arabia's primary economic zones, with primary inputs from each region's manufacturing and distribution clusters. The analysis combines structured interviews with furniture manufacturing executives, hospitality procurement directors, SASO certification specialists, and e-commerce logistics operators with secondary validation from Saudi customs records, SASO technical regulation filings, and Vision 2030 project development databases. Bottom-up production capacity assessments triangulate against top-down expenditure projections across the analysis window.
Segmentation-level modeling disaggregates revenue and volume trajectories across product type, material composition, end-user category, and distribution channel dimensions throughout the forecast period. CAGRs derive from regression analysis against construction permit flows, hospitality pipeline announcements, and digital payment penetration metrics. Industry-specific forecast inputs incorporate giga-project construction schedules and SASO laboratory capacity expansion timelines.
Revisions become necessary when Baltic supply disruptions intensify, SASO testing bottlenecks extend beyond current cycle times, or NEOM construction milestones accelerate beyond baseline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
India Furniture Market
Furniture
Armchair on Casters Market
Furniture
Germany Home Furniture Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
Italy Furniture Retail Market
Furniture
Lecterns Market
Furniture
Canada Secondary Wood Products Market
Furniture
Global Organic Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
China Furniture Market
Furniture
Mexico Home Furniture Market
Furniture
Kids Furniture Market
Furniture
Recliner Chair Market
Furniture
Salon Chairs Market
Furniture
Bar Stools Market
Furniture
Europe Home Furniture Market