
 Screening Equipment Market | 2026-2036
Screening Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Screening Equipment Market Outlook
Mining is consolidating its position as the dominant demand vertical for screening equipment, while construction and recycling applications broaden the buyer base. Sandvik AB leverages its rock-processing technology heritage to sustain engineering-intensive contracts in Nordic and Australian mining belts. Metso Outotec anchors its competitive stance through aftermarket service networks that extend equipment life cycles. Terex Corporation differentiates via mobile screening platforms that serve demolition recyclers across North American urban corridors.
Screening equipment comprises engineered machinery that separates bulk materials by particle size through controlled vibration, rotation, or gyratory motion, typically operating with mesh apertures ranging from micrometers to hundreds of millimeters depending on the separation duty. The primary purpose is to classify raw or processed feed streams into specified size fractions for downstream processing, quality control, or regulatory compliance. Vibrating screens occupy the largest installed base across mining and aggregates applications, while automated systems represent the fastest-expanding technology category as operators reduce labor exposure to dust and noise hazards. Trommel screens serve mature demand in municipal waste management, where margin pools depend on throughput reliability and screen panel replacement economics.
OSHA silica exposure limits in the United States and EU Industrial Emissions Directive enforcement are tightening permissible dust levels around dry screening operations, compelling manufacturers to integrate dust suppression and enclosed housings. EPA particulate standards for non-metallic mineral processing plants further shape equipment specifications in American quarrying and cement feed preparation. Stakeholders must monitor how MEE air quality enforcement in China and evolving state-level mining codes in Brazil and Australia redirect procurement toward enclosed automated systems versus open mechanical configurations.
Market Dynamics
Automated screening systems are displacing manual operations as mining operators confront lower ore grades requiring finer separation tolerances and stricter dust exposure limits. This structural shift compresses equipment replacement cycles while elevating capital intensity across extraction value chains.
Growth Catalysts
- EU Industrial Emissions Directive:Quarry operators across Germany, France, and Italy must retrofit open screening lines with enclosed housings and dust suppression, creating immediate replacement demand for compliant equipment.
- India's highway construction programs:National infrastructure corridors drive sustained procurement of high-capacity vibrating screens for aggregates processing in Rajasthan, Gujarat, and Tamil Nadu.
- Lower-grade ore processing:Australian and Brazilian iron ore miners expand installed screening capacity to maintain metal output from declining head grades, extending equipment runs and panel replacement frequency.
Market Restraints
- Steel price volatility:Screen deck fabrication depends on alloy steel plate and wire mesh inputs subject to commodity swings, compressing manufacturer margins on fixed-price contracts.
- Electronics supply concentration:Variable frequency drives and vibration monitoring sensors concentrate in East Asian component suppliers, exposing equipment builders to lead time uncertainty.
- Technical limitation in wet fines:Blinding of fine aperture meshes below 75 micrometers limits dry separation efficiency for certain mineral concentrates, constraining application scope.
Strategic Opportunities
- Urban demolition recycling:North American contractors processing concrete and asphalt debris seek mobile screening platforms with rapid site-to-site deployment capability.
- Indonesia's nickel expansion:Laterite ore processing for battery-grade nickel requires specialized trommel and vibrating screen configurations for clay-rich feedstocks.
- Sensor-based sorting convergence:X-ray transmission and near-infrared detection technologies integrate with mechanical screening to upgrade marginal ore streams before comminution.
Industry Challenges
- Vibration analysis expertise:Predictive maintenance of high-G force screens demands specialized technicians familiar with frequency spectrum interpretation and bearing diagnostics, creating hiring bottlenecks.
- Legacy control system integration:Automated screening lines must interface with existing SCADA architectures in brownfield plants, extending commissioning timelines and customization costs.
- ISO 10816 machinery vibration certification:Compliance documentation for international project tenders requires third-party testing protocols that delay shipment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screening Equipment Market |
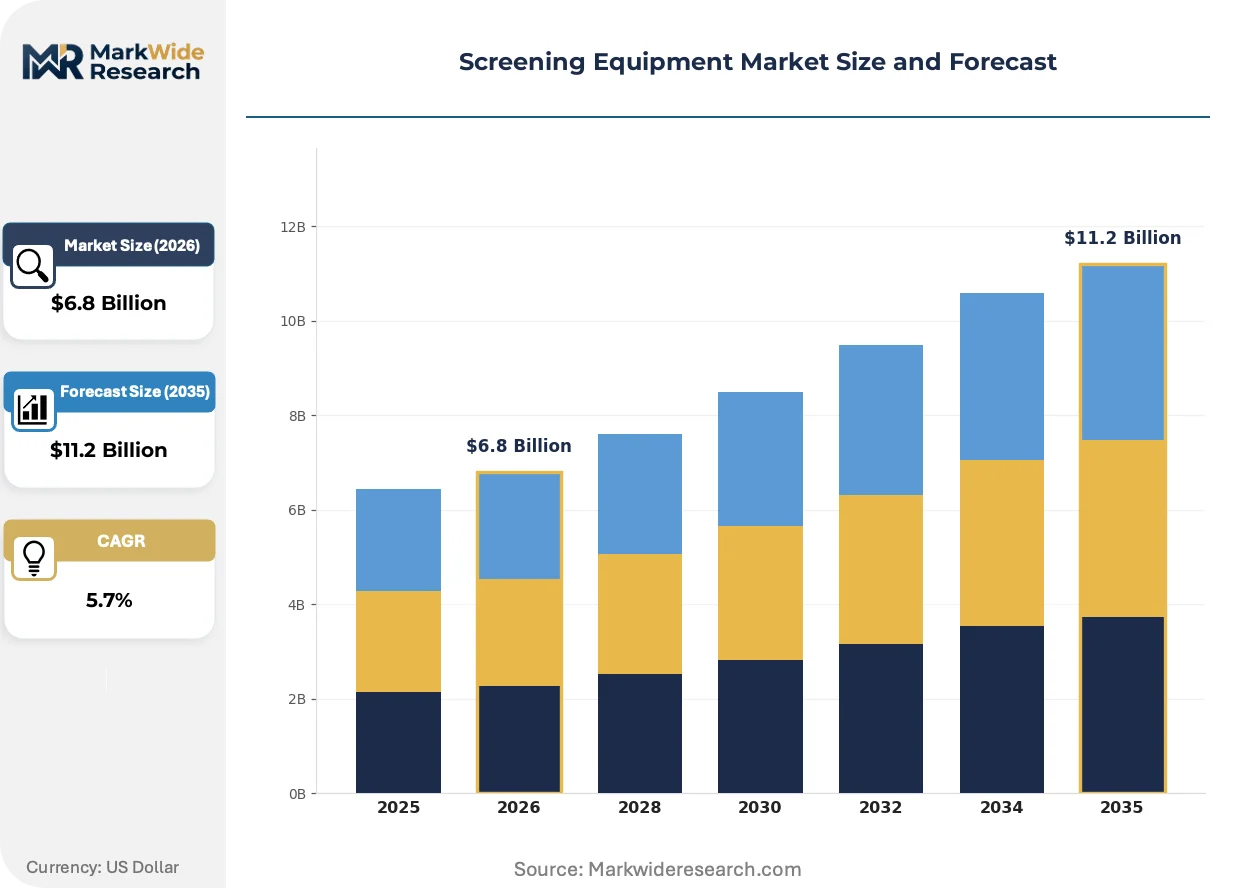
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibrating Screens, Gyratory Equipment, Trommel Screens, Disc Screens Application: Mining, Recycling, Agriculture, Construction End User: Aggregates, Waste Management, Food Processing, Energy Technology: Mechanical Screening, Automated Systems, Hydraulic Solutions, Electrical Screening |
| Companies Covered | Terex Corporation, Sandvik AB, Metso Outotec, Astec Industries, Inc., Weir Group PLC, McCloskey International, Kleemann GmbH, FLSmidth A/S, Derrick Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screening Equipment Market Strategic Shifts
Digitalization of screening operations is compressing maintenance intervals while enabling real-time process optimization. Equipment manufacturers embed condition monitoring and remote diagnostics to differentiate service offerings and lock in aftermarket revenue streams.
Artificial intelligence-driven particle size analysis is converging with mechanical screening circuits. Mining operators in Western Australia deploy camera-based systems that adjust screen amplitude and feed rate automatically based on real-time oversize detection. This convergence reduces labor exposure to dust hazards while stabilizing downstream grinding efficiency.
OSHA's respirable crystalline silica standard is compelling quarry operators to enclose previously open screening stations. American limestone and granite processors invest in negative-pressure housings and baghouse dust collection to meet the permissible exposure limit. This regulatory pressure elevates capital requirements for new installations and accelerates replacement of legacy equipment in Texas, Georgia, and Missouri aggregate operations.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-tier aggregates producers. Rental and lease-to-own arrangements spread through North American and European markets as contractors seek to preserve balance sheet capacity for core fleet investments. This financing shift concentrates in demolition recycling and short-term infrastructure projects where equipment utilization cycles remain uncertain.
Screening Equipment Market Segmentation
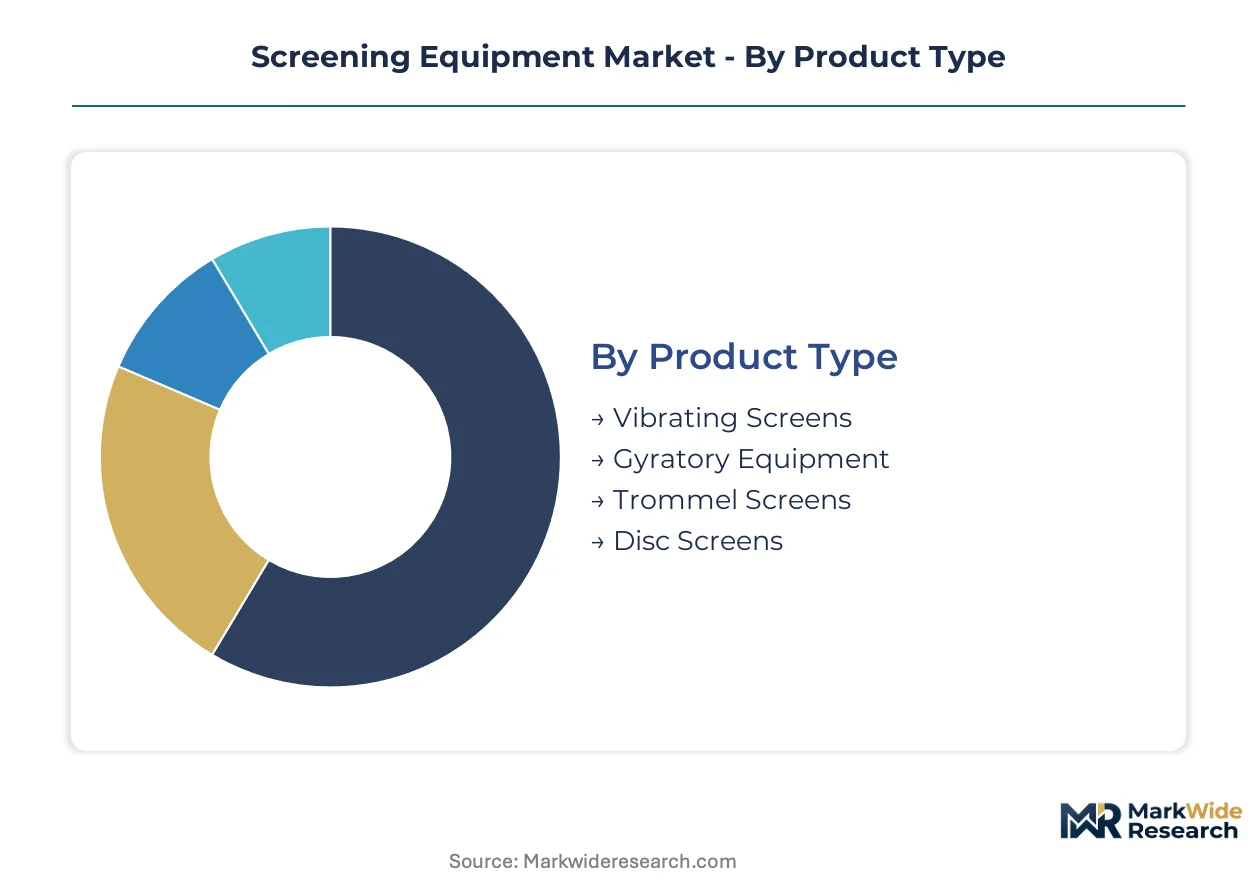
Screening equipment procurement patterns diverge sharply across duty cycles and automation intensity. Product architecture determines capital outlay and operating cost structures, while application context shapes regulatory exposure and replacement frequency.
Product Type:
Vibrating screens dominate installed tonnage capacity, yet premium margins concentrate in specialized configurations that handle difficult separations.
- Vibrating Screens:Elliptical and linear motion configurations process high-volume bulk feeds through modular wire mesh or polyurethane panels. Australian iron ore operators in the Pilbara region deploy these for fines recovery from declining head grades, driving panel replacement demand.
- Gyratory Equipment:Multi-plane gyratory sifters achieve precision separations below 75 micrometers for food-grade and chemical applications. European pharmaceutical compounders specify these for active ingredient classification where mesh integrity directly affects batch compliance.
- Trommel Screens:Rotating cylindrical drums with perforated plate or wire mesh handle high-moisture, sticky feeds in municipal waste and composting operations.
- Disc Screens:Interlocking star discs separate dimensional materials without blinding, serving construction debris and wood chip applications where long, stringy particles predominate.
Today's leader: Vibrating Screens. Tomorrow's challenger: Automated Systems.
Application:
Mining commands the heaviest unit specifications and longest service intervals, while recycling applications favor mobility and rapid reconfiguration.
- Mining:Hard rock and alluvial operations require abrasion-resistant screen decks rated for 10-hour continuous cycles. Brazilian Carajás iron ore complexes specify high-G force horizontal screens for dense medium recovery circuits.
- Recycling:Concrete, asphalt, and mixed C&D debris processors prioritize tracked mobile platforms with hydraulic folding conveyors. North American urban corridor contractors demand rapid site-to-site deployment for demolition projects.
- Agriculture:Grain cleaning and seed grading operations utilize gentler gyratory or rotary configurations to minimize kernel damage.
- Construction:Quarry-owned static plants and contractor mobile fleets serve aggregates production for infrastructure concrete and road base.
Volume concentrates in Mining. Steepest expansion trajectory emerges in Recycling.
End User:
Aggregates producers prioritize throughput reliability over separation precision, whereas food and energy applications impose strict contamination controls.
- Aggregates:Crushed stone, sand, and gravel operations run high-capacity inclined screens with heavy-duty deck frames. India's National Highway Development Program sustains procurement across Rajasthan, Gujarat, and Tamil Nadu crushing circuits.
- Waste Management:Material recovery facilities and composting sites balance throughput against manual sorting labor reduction. EU landfill diversion targets accelerate trommel and star screen adoption for organics separation.
- Food Processing:Flour mills and snack food plants specify stainless steel contact surfaces with FDA-compliant mesh certifications.
- Energy:Biomass pellet producers and coal preparation plants screen feedstocks for combustion efficiency and emissions compliance.
Aggregates anchors current demand. Waste Management gains share fastest as circular economy mandates spread.
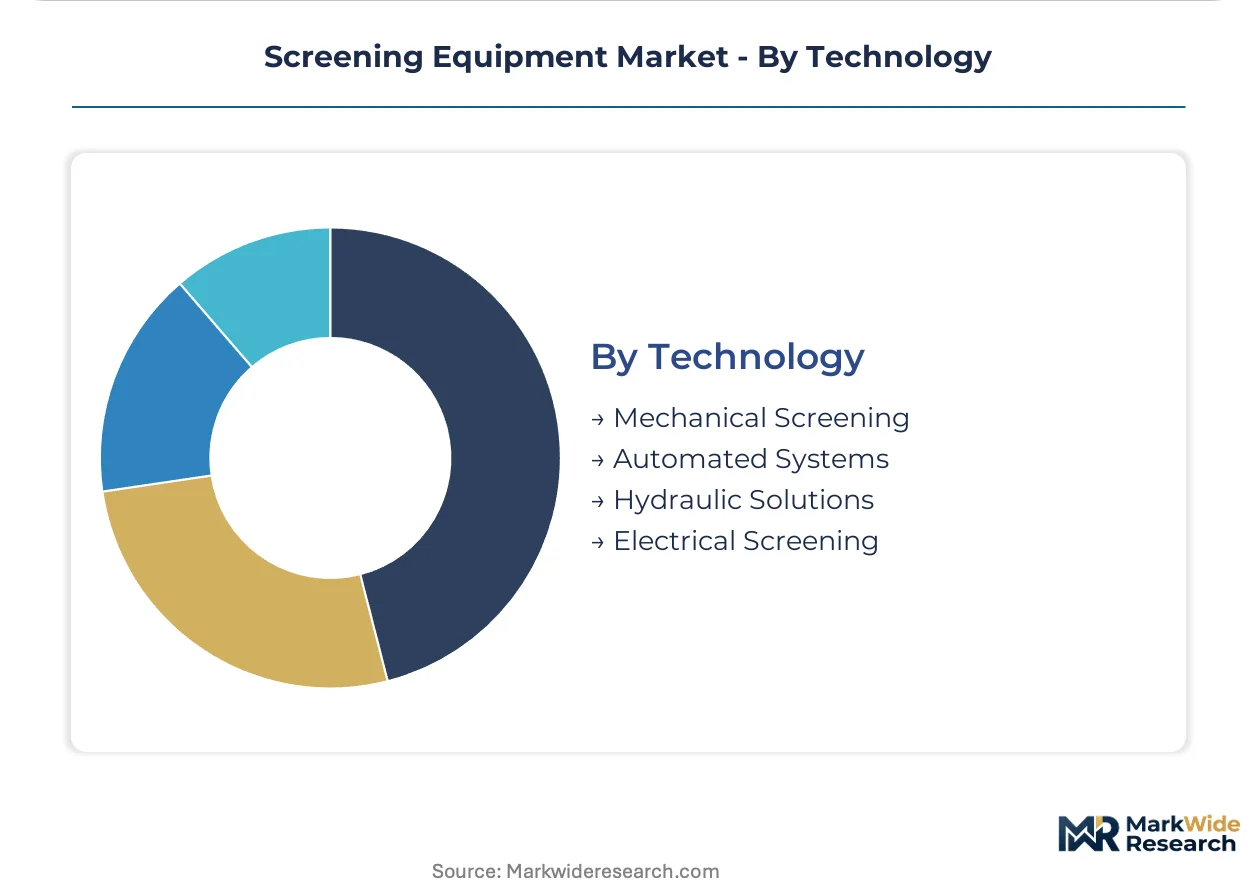
Technology:
Mechanical systems retain cost advantage for standard separations, while automated platforms capture premium positioning through labor reduction and dust containment.
- Mechanical Screening:Direct-drive and brute-force vibration mechanisms dominate baseline mining and aggregates applications where operator exposure to dust and noise remains acceptable.
- Automated Systems:Enclosed housings with variable frequency drives, remote amplitude adjustment, and integrated dust suppression command capital premiums. German quarry operators retrofit open lines to meet EU Industrial Emissions Directive limits.
- Hydraulic Solutions:Track-mounted mobile screens utilize hydraulic power for positioning and conveyor folding in demolition recycling.
- Electrical Screening:High-frequency electromagnetic drives enable fine aperture separations below 100 micrometers for industrial minerals and chemical processing.
Mechanical Screening holds volume leadership. Automated Systems represent the premium growth vector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement flows toward jurisdictions where compliance costs remain manageable relative to ore quality. Australian and Brazilian miners expand screening capacity to process declining head grades, while European quarry operators absorb retrofit costs for dust containment. Indian contractors capitalize on infrastructure spending without comparable environmental overhead.
Australia
Pilbara iron ore operators deploy high-tonnage vibrating screens for fines recovery circuits. EPA Western Australia enforces dust management plans for dry processing facilities. Perth-based engineering clusters supply modular screen housings to Newman and Port Hedland mine sites.
Brazil
Carajás mining complexes specify abrasion-resistant deck configurations for dense medium separation. ANVISA coordinates with state environmental agencies on occupational silica limits. Belo Horizonte fabricators manufacture replacement screen panels for southeastern iron ore belts.
India
National Highway Development Program contractors procure inclined screens for Rajasthan and Gujarat aggregate crushing. Ministry of Road Transport and Highways mandates quality control testing for road base materials. Tamil Nadu quarry clusters near Chennai sustain heavy equipment replacement cycles.
Germany
Quarry operators retrofit open screening lines with enclosed automated systems. EU Industrial Emissions Directive enforcement through Länder environmental agencies accelerates capital replacement. Bavarian limestone processors near Munich invest in negative-pressure housings and baghouse integration.
United States
Texas and Missouri aggregate producers replace legacy equipment to meet OSHA respirable crystalline silica standards. EPA particulate regulations for non-metallic mineral processing shape equipment specifications. Georgia granite quarries deploy mobile screening platforms for rapid site reconfiguration.
Screening Equipment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with mining procurement favoring established engineering houses while recycling applications attract regional fabricators. The vendor base organizes into three tiers: integrated rock-processing technology providers, aftermarket service networks, and mobile equipment specialists. Consolidation pressure runs highest among mid-scale screen panel suppliers facing steel input volatility. Dominant competitive moves include geographic expansion into nickel laterite processing corridors and portfolio diversification toward sensor-integrated sorting systems.
Among Nordic and North American engineering houses, Sandvik AB, Metso Outotec, and Terex Corporation exemplify contrasting strategic positions. Sandvik anchors the rock-processing heritage tier with deep integration into Australian and Brazilian mining belts. Metso Outotec occupies the aftermarket-intensive archetype, extending equipment life cycles through service network density. Terex represents the mobile-first specialization, with tracked platform configurations serving demolition recyclers across urban North American corridors.
| Leading Market Players |
|---|
| Terex Corporation |
| Sandvik AB |
| Metso Outotec |
| Astec Industries, Inc. |
| Weir Group PLC |
| McCloskey International |
| Kleemann GmbH |
| FLSmidth A/S |
| Derrick Corporation |
| Others |
Value Chain & Pricing Dynamics
Backward integration into alloy steel fabrication anchors pricing power for Nordic and Australian engineering houses serving mining procurement. Captive control over screen deck production insulates these manufacturers from commodity swings while compressing procurement cycles for Brazilian and Indian contractors facing volatile wire mesh inputs.
Pricing Analysis
Distributor margins on replacement screen panels run 15-25 points above direct-to-mine contracts for original equipment. Three-tier pricing structure across premium automated systems, standard mechanical configurations, and economy mobile units separates Australian iron ore operators from Indian highway contractors and North American demolition recyclers. Pricing pressure stems from steel input volatility compressing fabricator margins on fixed-price tenders. Aggregates producers in India exhibit highest price sensitivity due to thin project margins, while EU quarry operators absorb capital premiums for dust-compliant enclosed systems.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mining demand in Australia and Brazil, while regional distributors serve fragmented aggregates contractors across India and North America. Component concentration in China and South Korea for variable frequency drives and vibration sensors creates single-source vulnerability for European and American equipment builders. Steel plate from German and Japanese mills feeds high-abrasion deck fabrication, with logistics chokepoints at Rotterdam and Singapore elevating delivery costs for Brazilian customers. Distribution runs through manufacturer-direct teams for major mining accounts and specialized industrial distributors for mid-tier recycling operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The screening equipment market reads as a late-cycle quality story as mining operators replace open mechanical lines with dust-contained automated systems that command capital premiums and lock in aftermarket service contracts.
For Market Incumbents: Deepen aftermarket service network density in Australian Pilbara and Brazilian Carajás corridors to capture panel replacement demand from declining ore grades. Incumbents must defend against sensor-integrated sorting convergence by acquiring AI-driven particle analysis capabilities and embedding predictive maintenance modules that extend equipment life cycles. For New Entrants and Emerging Players: AI-driven remote diagnostics capabilities offer entry leverage into mid-tier North American demolition recycling where mobile platform utilization cycles remain uncertain. New entrants should target urban corridor contractors in Texas and Georgia seeking rapid-deployment screening for concrete and asphalt debris processing, positioning through equipment-as-a-service financing to bypass capital purchase barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional screen panel fabricators because steel input volatility is driving consolidation among sub-scale suppliers unable to hedge commodity exposure. Investors should monitor MEE air quality enforcement intensity in China as the inflection signal indicating accelerated procurement shift toward enclosed automated configurations across Asian mining belts.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Sorting Convergence | X-ray transmission and near-infrared detection technologies upgrade marginal ore streams before comminution, reducing downstream energy intensity. |
| Equipment-as-a-Service Expansion | Rental and lease-to-own arrangements preserve balance sheet capacity for North American demolition contractors facing uncertain project pipelines. |
| Aftermarket Service Network Densification | Perth and Belo Horizonte engineering clusters capture recurring revenue from high-G force screen maintenance in Pilbara and Carajás mining belts. |
| Dust Containment Retrofit Programs | German and Bavarian quarry operators invest in negative-pressure housings to meet EU Industrial Emissions Directive enforcement timelines. |
| Mobile Platform Rapid Deployment | Tracked screening systems with hydraulic folding conveyors serve Georgia granite quarries and Texas limestone operations requiring site-to-site flexibility. |
Study Parameters
Bottom-up mining and aggregates modeling reconciled against top-down component supplier tracking forms the analytical core of this study. Primary interviews with maintenance directors at Australian iron ore operations, plant engineers at Indian highway construction firms, aftermarket service heads at Nordic engineering houses, and procurement teams at Brazilian mining complexes combined with secondary validation from customs trade data, SEC equipment manufacturer filings, and EU emissions compliance databases. Triangulation between demand-side utilization patterns and supply-side production capacity ensures segmentation integrity across vibrating screen, trommel, and automated system categories.
Historical trendline analysis of replacement cycles and capital expenditure patterns across the projection horizon established baseline growth trajectories. Segmentation modeling incorporated product type, application duty cycle, automation intensity, and regional regulatory cluster dimensions. CAGRs derived from equipment shipment tracking and installed base depreciation schedules, with forecast inputs including ore grade decline curves in Australian and Brazilian iron ore belts and EU Industrial Emissions Directive compliance timelines for quarry retrofit demand.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel price volatility and Chinese environmental enforcement intensity. Outputs reflect documented assumptions regarding mining capital commitment cycles and infrastructure program continuity in India. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Adulteration Tester Market
Food Safety Testing
Global Inline Metal Detector Market
Food Safety Testing
Xylose Absorption Tests Market
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Amylase Testing Market
Food Safety Testing
Fruit & Vegetable Wash Market
Food Safety Testing
Water Activity Meter Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
Food Authentication Testing Market
Food Safety Testing
Meat Speciation Testing Service Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
Water Activity Instrumentation Market
Food Safety Testing
UK Food Testing Market
Food Safety Testing
Middle East and Africa Food Safety Testing Market