
 Global Cellular Networks Market | 2026-2036
Global Cellular Networks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cellular Networks Market Foresight
The EU AI Act is expanding compliance burdens for network equipment vendors selling into European smart city and public safety deployments. Deutsche Telekom AG leverages its integrated tower and fiber assets to sustain pricing power across German and Eastern European markets. China Mobile Communications Corporation anchors its position through captive R&D into Open RAN architectures, while Verizon Communications Inc. differentiates via millimeter-wave spectrum depth in dense US urban corridors.
Cellular networks constitute radio access infrastructure operating across licensed spectrum bands from 600 MHz to 100 GHz, employing base transceiver stations, core packet gateways, and backhaul links to deliver packet-switched voice and data services to mobile terminals. 5G NR deployments now dominate capital allocation as operators sunset 3G and refarm mid-band spectrum, while small cell infrastructure represents the fastest-growing deployment type because macro site densification cannot alone satisfy capacity demands in urban hotspots. IoT connectivity applications command expanding margin pools as NB-IoT and LTE-M modems penetrate utility metering, asset tracking, and agricultural sensor networks.
The FCC in the United States, the EU's Radio Spectrum Policy Group, and India's TRAI collectively shape market access through auction design, equipment authorization rules, and local content mandates. EMA and CE marking requirements in Europe plus FCC OET certification in the United States create divergent testing regimes that fragment vendor product portfolios. Stakeholders must monitor spectrum reallocation timelines and open interface mandates, as regulatory choices between licensed and shared spectrum models will determine which equipment architectures achieve scale.
Market Dynamics
Capital allocation across the cellular infrastructure sector pivots on spectrum refarming velocity and Open RAN interoperability mandates, forcing vendors to rebuild product portfolios around disaggregated architectures while maintaining backward compatibility with installed base stations.
Growth Catalysts
- Smart city infrastructure mandates:Municipal governments in India, Germany, and Brazil are embedding 5G small cells into street furniture and traffic management systems to support real-time video analytics and autonomous vehicle corridors.
- EU AI Act compliance frameworks:Equipment vendors must now certify network elements for algorithmic transparency in public safety deployments, creating replacement cycles for legacy base stations lacking embedded audit capabilities.
- NB-IoT module cost compression:Semiconductor process advances have driven modem prices below three dollars, unlocking utility metering and agricultural sensor networks previously served by unlicensed LPWAN technologies.
Market Restraints
- Gallium nitride substrate shortages:Power amplifier manufacturers face twelve-month lead times for high-purity GaN wafers, constraining macro base station output and inflaming equipment delivery backlogs.
- Single-source dependency for mmWave beamforming ASICs:Three foundries control ninety percent of sub-6nm RF silicon capacity, concentrating supply risk for dense urban small cell rollouts.
- Electromagnetic field exposure thresholds:Italy's stricter SAR limits compared to EU baseline standards force site-specific power reductions that degrade coverage economics in suburban deployments.
Strategic Opportunities
- BharatNet fiber convergence:India's rural broadband backbone creates backhaul-ready anchor points for 4G/5G radio access network extension into previously uneconomical districts.
- Private 5G network slicing:Manufacturing campuses in Vietnam and Indonesia are procuring dedicated spectrum licenses for industrial automation, bypassing public operator intermediaries.
- CSRD sustainability disclosure:European operators must now report Scope 3 network equipment emissions, favoring vendors with modular, repairable hardware designs and circular supply chains.
Industry Challenges
- Multi-vendor Open RAN integration:Disaggregated radio units from different suppliers frequently fail interoperability testing at O-RAN ALLIANCE plugfests, delaying commercial launches and inflating system integration costs.
- Legacy 2G/3G sunsetting complexity:Decommissioning obsolete core network elements while maintaining circuit-switched voice fallback for rural subscribers requires parallel infrastructure operation that strains operational budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cellular Networks Market |
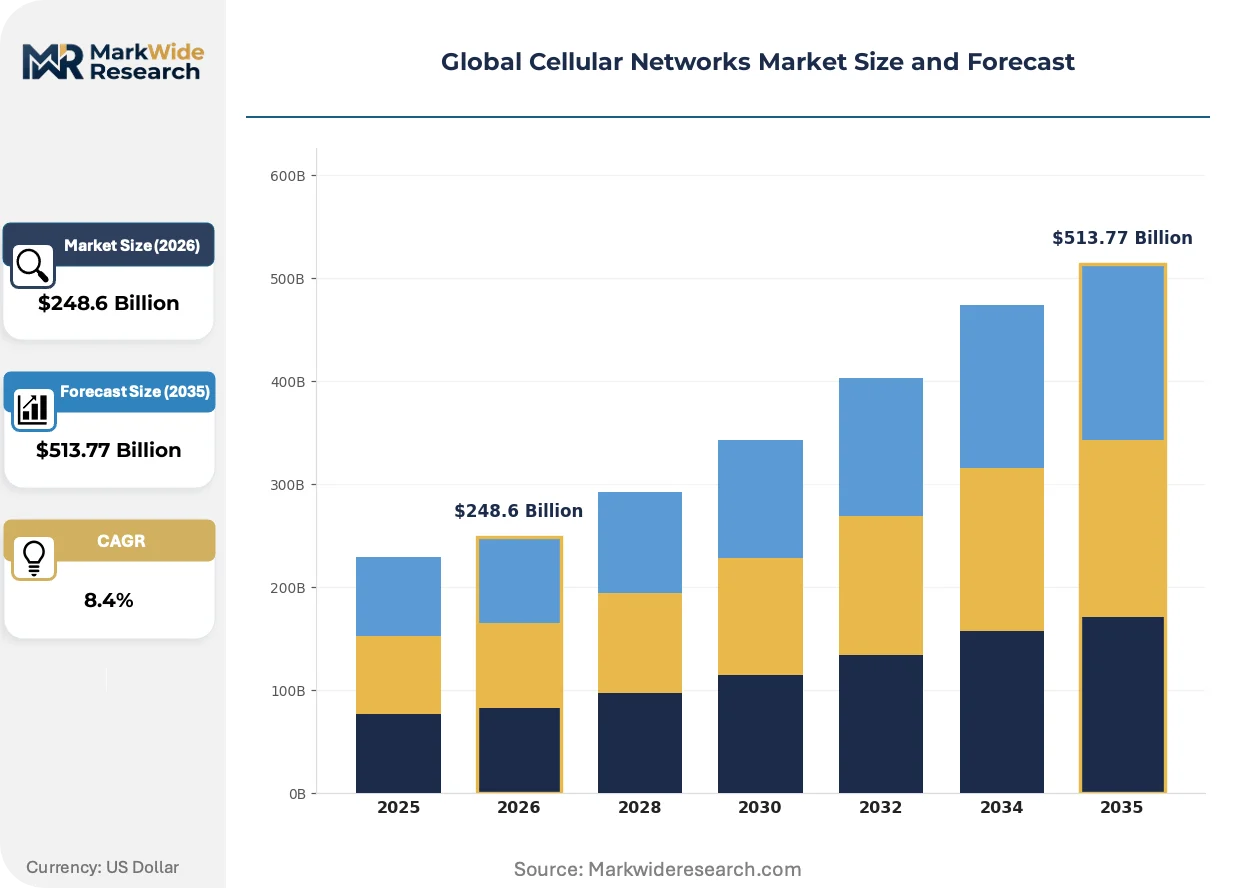
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $513.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 2G, 3G, 4G LTE, 5G NR, NB-IoT, LTE-M Deployment Type: Macro Cell, Small Cell, Distributed Antenna System, Pico Cell, Femto Cell Application: Mobile Broadband, IoT Connectivity, M2M Communication, Public Safety Networks, Fixed Wireless Access End User: Telecom Operators, Enterprises, Government, Smart Cities, Transportation Providers |
| Companies Covered | Deutsche Telekom AG, China Telecommunications Corporation, China Mobile Communications Corporation, Vodafone Group Plc, T-Mobile US Inc., Verizon Communications Inc., Nippon Telegraph and Telephone Corporation, SoftBank Group Corp., AT&T Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cellular Networks Market Shifts & Advancements
Radio access network architecture is undergoing forced disaggregation as regulatory pressure and cost imperatives dismantle the integrated base station model that dominated prior cellular generations.
Cloud-native baseband processing is unifying distributed unit functions onto commodity server hardware, allowing mobile operators in South Korea and Finland to consolidate cell site compute into regional edge data centers. This architecture compresses hardware diversity at the tower while introducing new latency constraints that fiber backhaul must satisfy.
The EU's Radio Spectrum Policy Group has mandated 3.4-3.8 GHz band harmonization across member states by 2027, compelling equipment manufacturers to retune filter and amplifier designs for contiguous rather than fragmented national allocations. German and Polish operators are accelerating procurement timelines to lock in hardware before retooling costs escalate.
Enterprise buyers now demand network-as-a-service contracts with performance-based SLAs rather than capital-intensive ownership models, particularly in mining and port automation verticals across Australia and Chile. System integrators are displacing traditional equipment vendors in direct customer relationships, capturing recurring revenue streams that hardware suppliers struggle to access.
Global Cellular Networks Market Segmentation
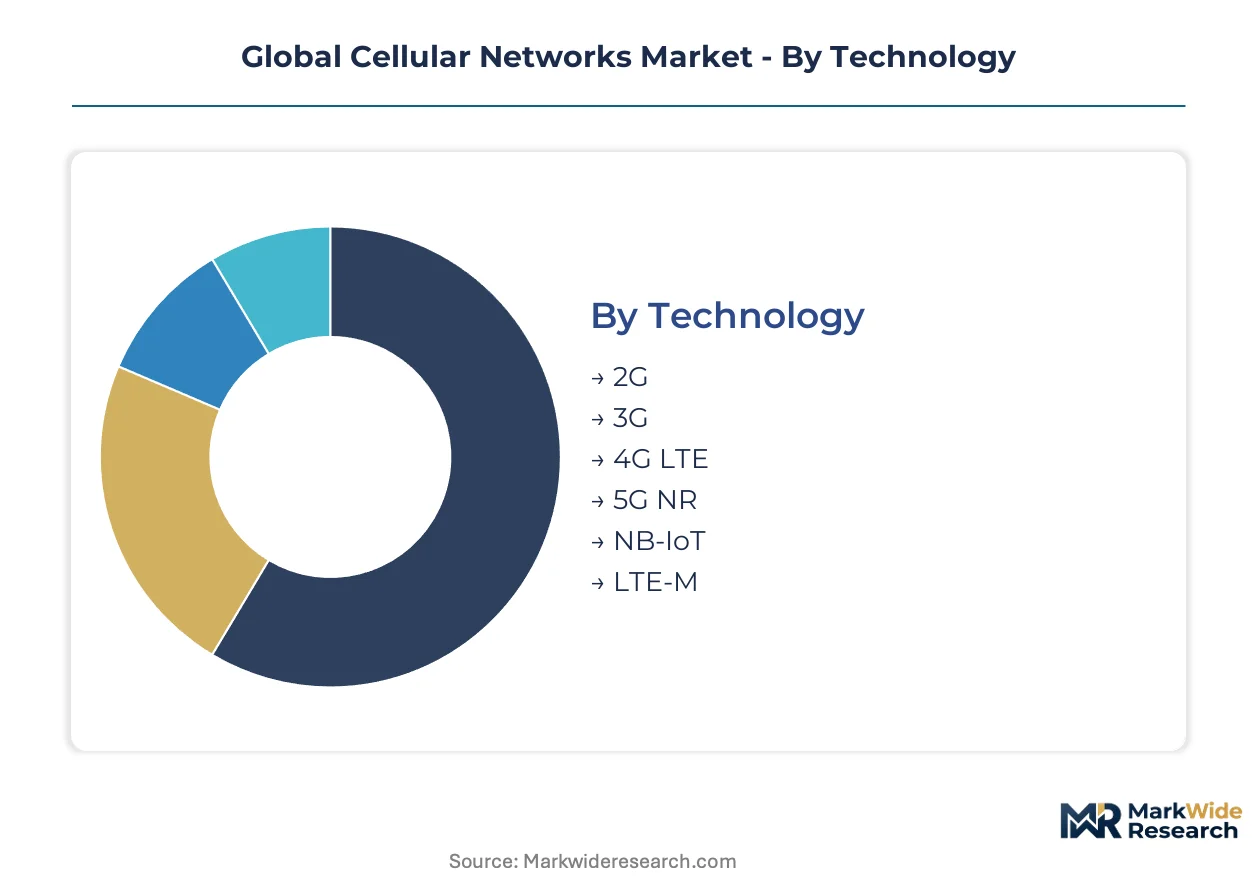
Cellular network procurement patterns diverge sharply across technology generations and deployment scales, with capital allocation priorities shifting from coverage-centric macro builds toward capacity-driven small cell densification. Understanding segment boundaries clarifies where equipment vendors must rebuild portfolios for disaggregated architectures versus defending integrated legacy positions.
Technology:
Capital intensity varies enormously across technology generations, with 5G NR demanding massive MIMO antenna arrays and millimeter-wave spectrum investments that dwarf prior deployment economics.
- 5G NR:New radio interfaces operating in sub-6 GHz and mmWave bands enable network slicing and ultra-reliable low-latency communication. Indian operators are procuring equipment at unprecedented scale for nationwide coverage, driven by Reliance Jio's aggressive rollout timelines and TRAI-mandated coverage obligations.
- 4G LTE:Mature orthogonal frequency-division multiple access technology now serves as capacity fallback and rural coverage anchor. German operators maintain LTE as primary revenue layer while 5G builds progress, reflecting Deutsche Telekom's spectrum refarming discipline.
- NB-IoT:Narrowband cellular protocol optimized for low-power wide-area sensor networks with extended battery life.
- LTE-M:Machine-type communication variant supporting voice and mobility for asset tracking applications.
- 3G:Legacy wideband code-division multiple access technology undergoing accelerated sunsetting across European markets.
- 2G:Circuit-switched GSM infrastructure retained primarily for rural voice fallback and machine-to-machine legacy modules.
4G LTE absorbs the bulk of installed capacity; 5G NR is expanding most quickly.
Deployment Type:
Site economics fragment sharply between rural macro coverage and urban hotspot densification, with each deployment type demanding distinct power, backhaul, and zoning compliance profiles.
- Macro Cell:High-power base stations covering 1-30 kilometer radii with tower-mounted antenna systems. Gallium nitride substrate shortages are constraining power amplifier output, forcing Brazilian operators to extend delivery timelines for Amazon basin coverage extensions.
- Small Cell:Low-power nodes deployed on street furniture and building facades for urban capacity infill. Municipal governments in Germany are embedding these into traffic management systems to support autonomous vehicle corridors and real-time video analytics.
- Distributed Antenna System:Network of spatially separated antenna nodes connected to common source via fiber or coaxial transport.
- Pico Cell:Compact indoor coverage solution for enterprise campuses and shopping complexes.
- Femto Cell:Residential-grade access point providing localized coverage for consumer premises.
Macro Cell infrastructure dominates cumulative capital deployed; Small Cell installations are climbing the fastest.
Application:
Revenue per bit varies by three orders of magnitude across applications, from bulk IoT connectivity to premium public safety network slicing.
- Mobile Broadband:Consumer and enterprise data services comprising the core revenue base for telecom operators. South Korean operators have consolidated baseband processing into regional edge data centers, introducing fiber backhaul latency constraints that equipment vendors must engineer around.
- IoT Connectivity:Massive machine-type communication for utility metering, agricultural sensors, and asset tracking. Semiconductor process advances have compressed NB-IoT modem prices below three dollars, unlocking utility networks previously served by unlicensed LPWAN alternatives.
- M2M Communication:Machine-to-machine telemetry for industrial automation and fleet management.
- Public Safety Networks:Mission-critical voice and data for emergency services requiring hardened reliability.
- Fixed Wireless Access:Last-mile broadband delivery competing with fiber-to-the-home in suburban and rural markets.
Mobile Broadband commands the largest share of operator capital budgets; IoT Connectivity is gaining share fastest.
End User:
Procurement sophistication diverges between regulated telecom incumbents and emerging enterprise buyers demanding network-as-a-service consumption models.
- Telecom Operators:Licensed spectrum holders building nationwide coverage with regulated wholesale obligations. Verizon Communications differentiates via millimeter-wave spectrum depth in dense US urban corridors, while China Mobile anchors position through captive Open R&D into Open RAN architectures.
- Smart Cities:Municipal governments procuring integrated infrastructure for traffic management, environmental monitoring, and public safety. EU AI Act compliance mandates are forcing replacement cycles for legacy base stations lacking embedded algorithmic audit capabilities.
- Enterprises:Manufacturing campuses and logistics hubs deploying private 5G networks for industrial automation.
- Government:Defense and civilian agencies requiring sovereign-controlled secure communications.
- Transportation Providers:Rail, port, and aviation operators demanding continuous mobility coverage.
Telecom Operators account for the dominant share of equipment procurement; Smart Cities are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones for electronics manufacturing concentrate base station assembly capacity near Chennai and Sriperumbudur, attracting component suppliers seeking tariff advantages under the government's production-linked incentive schemes.
United States
Verizon Communications and T-Mobile US compete for millimeter-wave spectrum depth in dense urban corridors. FCC auction design and OET certification requirements shape vendor market access. The San Francisco Bay Area and Boston metro anchor Open RAN software development clusters.
Germany
Deutsche Telekom AG leverages integrated tower and fiber assets across German and Eastern European markets. The EU AI Act and Radio Spectrum Policy Group harmonization mandates force equipment retooling for 3.4-3.8 GHz contiguous allocations. Berlin and Munich host smart city pilot programs embedding 5G small cells into traffic infrastructure.
India
Reliance Jio's nationwide 5G rollout and BharatNet fiber convergence drive unprecedented base station procurement volumes. TRAI coverage obligations and spectrum auction terms accelerate rural network extension. Tamil Nadu's Sriperumbudur electronics cluster hosts manufacturing for radio access equipment.
China
China Mobile Communications Corporation anchors position through captive R&D into Open RAN architectures. MIIT spectrum allocation policies and GB standards for electromagnetic compatibility shape vendor compliance. Shenzhen and Beijing concentrate baseband processing and antenna design capabilities.
South Korea
SK Telecom and KT Corporation consolidate distributed unit functions into regional edge data centers. METI-aligned spectrum policies and national 5G coverage mandates sustain equipment refresh cycles. Seoul Capital Area and Busan-Ulsan anchor cloud-native network function deployment.
Global Cellular Networks Market Competitive Landscape
North American operators anchor one tier through spectrum depth and enterprise vertical integration; East Asian equipment vendors hold manufacturing scale advantages through captive semiconductor supply chains. Market structure concentrates around national champions with regulatory capture in home markets. Three archetypes dominate: integrated telecom operators owning tower and fiber assets; state-backed champions with R&D subsidies; and equipment vendors pivoting toward Open RAN disaggregation. Competitive moves center on spectrum auction positioning and strategic fiber backhaul acquisitions.
Among integrated telecom operators, Deutsche Telekom AG, Verizon Communications Inc., and China Mobile Communications Corporation exemplify the asset-heavy archetype that sustains pricing power through vertical control over passive infrastructure. These entities occupy positions where spectrum licenses, tower portfolios, and fiber depth create defensive moats against pure-play equipment vendors. Their procurement decisions collectively shape vendor R&D priorities across sub-6 GHz massive MIMO and millimeter-wave small cell roadmaps.
| Leading Market Players |
|---|
| Deutsche Telekom AG |
| China Telecommunications Corporation |
| China Mobile Communications Corporation |
| Vodafone Group Plc |
| T-Mobile US Inc. |
| Verizon Communications Inc. |
| Nippon Telegraph and Telephone Corporation |
| SoftBank Group Corp. |
| AT&T Inc. |
| Others |
Supply & Pricing Matrix
Hyperscale telecom operators in India and Germany command volume-driven contract structures that compress equipment margins while extending payment terms to eighteen months. This buyer concentration forces vendors to absorb gallium nitride substrate premiums and foundry slot scarcity through internal cost buffers rather than price pass-through.
Pricing Analysis
Short lead-time premiums of twenty to thirty percent apply to macro base station orders requiring gallium nitride power amplifiers within six-month windows, while spot inventory of legacy 4G radio units trades at distressed clearance levels. Three-tier pricing structure across premium, standard, and economy levels separates Open RAN-compliant massive MIMO arrays from integrated legacy base stations and refurbished rural coverage units. Cost compression in the standard tier is intensifying because semiconductor foundries are prioritizing automotive and AI chip allocations over RF silicon. Municipal smart city procurement teams exhibit highest price sensitivity due to fixed budget cycles, whereas defense and public safety buyers accept premium positioning for hardened reliability certifications.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale operator demand for 5G massive MIMO arrays, while systems integrators and distribution partners manage enterprise private network and smart city deployments requiring localized installation support. Taiwan, South Korea, and the United States concentrate sub-6nm RF ASIC fabrication and millimeter-wave beamforming silicon design. High-purity gallium nitride wafers, ceramic filter substrates, and precision antenna elements constitute critical input dependencies. Single-source vulnerability concentrates in three foundries controlling ninety percent of advanced RF silicon capacity. Distribution runs through authorized vendor-direct programs for tier-one operators and regional value-added resellers for mid-market enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated national champions as Open RAN interoperability failures and gallium nitride supply shortages force smaller equipment vendors into distressed asset sales or exit.
For Market Incumbents: To counter multi-vendor integration failures at O-RAN ALLIANCE plugfests, Deutsche Telekom and Verizon must deepen captive R&D into radio unit software stacks and secure long-term gallium nitride wafer offtake agreements with substrate suppliers. Backward integration into tower and fiber assets sustains pricing power against pure-play equipment vendors while creating exclusive deployment channels for proprietary hardware architectures. For New Entrants and Emerging Players: Capture private 5G network slicing opportunities in Vietnamese and Indonesian manufacturing campuses where public operator intermediaries are bypassed and procurement cycles run shorter than national infrastructure tenders. Enterprise verticals in mining automation and port logistics present the most penetrable segments due to performance-based SLA demand and limited incumbent relationships. A systems integrator-led go-to-market angle displaces traditional vendor-direct models and captures recurring service revenue. For Investors and Strategic Acquirers: The window for entry favors distressed equipment vendors with Open RAN software stacks and established carrier lab relationships but strained working capital from gallium nitride procurement delays. Long-term viability hinges on consolidation into platforms with sufficient scale to negotiate foundry priority allocation and absorb CSRD compliance costs. Monitor O-RAN ALLIANCE plugfest certification timelines as the critical inflection signal for which disaggregated architectures achieve commercial scale.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Software Stack Development | Deutsche Telekom's captive R&D investments determine which radio unit architectures achieve interoperability certification first. |
| Gallium Nitride Supply Agreement | Long-term wafer offtake contracts with substrate manufacturers insulate power amplifier output against twelve-month lead time constraints. |
| Smart City Infrastructure Partnership | Municipal procurement programs in Berlin and Munich embed 5G small cells into traffic management systems with algorithmic audit requirements. |
| Private 5G Network Deployment | Manufacturing campuses in Vietnam and Indonesia procure dedicated spectrum licenses for industrial automation bypassing public operators. |
| CSRD Compliance Certification | European operators must report Scope 3 network equipment emissions favoring vendors with modular repairable hardware designs. |
Research Methodology
SEC filings, O-RAN ALLIANCE technical specifications, and TRAI spectrum auction records formed the secondary backbone, cross-referenced against primary interviews with radio access network procurement directors, tower infrastructure planners, and semiconductor supply chain managers. Bottom-up and top-down triangulation validated equipment shipment volumes against operator capex disclosures and foundry capacity allocation reports.
Bottom-up modeling aggregated country-level spectrum auction timelines, coverage obligation mandates, and base station deployment densities across technology generation and deployment type segments. Top-down constraints applied macroeconomic variables, regulatory harmonization schedules, and raw material availability indices. CAGRs were derived from fitted growth curves across the projection horizon, with 5G NR penetration rates and gallium nitride substrate supply elasticity as primary forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Open RAN interoperability certification delays, spectrum reallocation decisions by the EU Radio Spectrum Policy Group and India's TRAI, and foundry capacity shifts toward AI chip demand. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Japan Telecom Market
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market
Telecommunications Infrastructure
Iraq Telecom Market
Telecommunications Infrastructure
5G Infrastructure Market
Telecommunications Infrastructure
Kenya Telecom Tower Market
Telecommunications Infrastructure
Brazil Telecom Tower Market
Telecommunications Infrastructure
Fixed-Line Communications Market
Telecommunications Infrastructure
France Telecom Towers Market
Telecommunications Infrastructure
Global Telecom System Integration Market
Telecommunications Infrastructure
Carrier Infrastructure in Telecom Applications Market
Telecommunications Infrastructure
OTN Equipment Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Germany Telecom Towers Market
Telecommunications Infrastructure
Nigeria Telecom Tower Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market