
 Costa Rica Telecom Market | 2026-2036
Costa Rica Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Costa Rica Telecom Market Insights
The premium fiber-to-the-home tier is repositioning away from prepaid mobile bundles as ICE Group (Kolbi) leverages its state-backed infrastructure dominance to anchor high-ARPU households, while Liberty Communications of Costa Rica LLC competes through cable-TV bundling and Tigo Costa Rica differentiates via aggressive 4G expansion in secondary cities.
Costa Rica telecom encompasses the transmission of voice, data, and video services across wired and wireless networks operating on licensed spectrum bands typically ranging from 700 MHz to 3.5 GHz, with fiber optic backhaul achieving latency below 10 milliseconds to support real-time enterprise applications. Mobile Services generates the largest revenue pool as smartphone penetration saturates urban centers, yet Broadband Internet represents the fastest-expanding segment as remote work institutionalizes fiber demand; the Pricing Model dimension shows Bundled Services capturing disproportionate margin as operators combat churn through fixed-mobile convergence.
SUTEL enforces asymmetric interconnection rates and universal service obligations that shape carrier investment priorities, while the Ministry of Science and Technology's National Telecommunications Plan mandates rural broadband targets that redirect subsidy flows toward underserved cantons. Stakeholders must monitor spectrum auction timelines and tower-sharing regulations as these decisions will determine which technologies achieve commercial scale first.
Market Dynamics
SUTEL's spectrum reallocation mandates are compressing carrier investment timelines and forcing accelerated 5G infrastructure deployment across the Central Valley corridor, fundamentally restructuring capital allocation priorities for fixed-mobile convergence.
Growth Catalysts
- Cloud-based unified communications:Financial services firms in San José are institutionalizing remote work protocols, driving enterprise fiber demand with sub-10 millisecond latency requirements.
- SUTEL asymmetric interconnection rates:The regulator's pricing framework incentivizes infrastructure sharing, reducing redundant tower builds and accelerating rural coverage expansion.
- Secondary city 4G densification:Provincial cantons outside the Greater Metropolitan Area are experiencing smartphone saturation, creating addressable mobile data markets previously served by 3G.
Market Restraints
- Geographic deployment cost asymmetry:Mountainous terrain and dispersed rural settlements impose fiber trenching costs that exceed urban benchmarks by substantial multiples.
- Spectrum scarcity in mid-band:Limited 3.5 GHz availability constrains carrier capacity planning for fixed wireless access in suburban zones.
- State-backed infrastructure concentration:ICE Group's historical dominance in backbone fiber creates asymmetric wholesale access terms for competing retail operators.
Strategic Opportunities
- Underserved Caribbean coastal cantons:Limón province exhibits broadband penetration gaps that subsidy flows from the Ministry of Science and Technology's National Telecommunications Plan specifically target.
- Fixed-mobile convergence bundles:Cable-TV operators possess latent fiber assets that support quadruple-play packaging for high-ARPU household capture.
- Edge computing co-location:Low-latency fiber backhaul enables distributed data center partnerships with logistics and agricultural technology firms.
Industry Challenges
- 5G radio access network integration:Legacy 4G core infrastructure requires non-standalone architecture upgrades that complicate vendor interoperability.
- Rural tower permitting timelines:Municipal environmental review processes for macro-site construction extend deployment schedules beyond carrier financial planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Costa Rica Telecom Market |
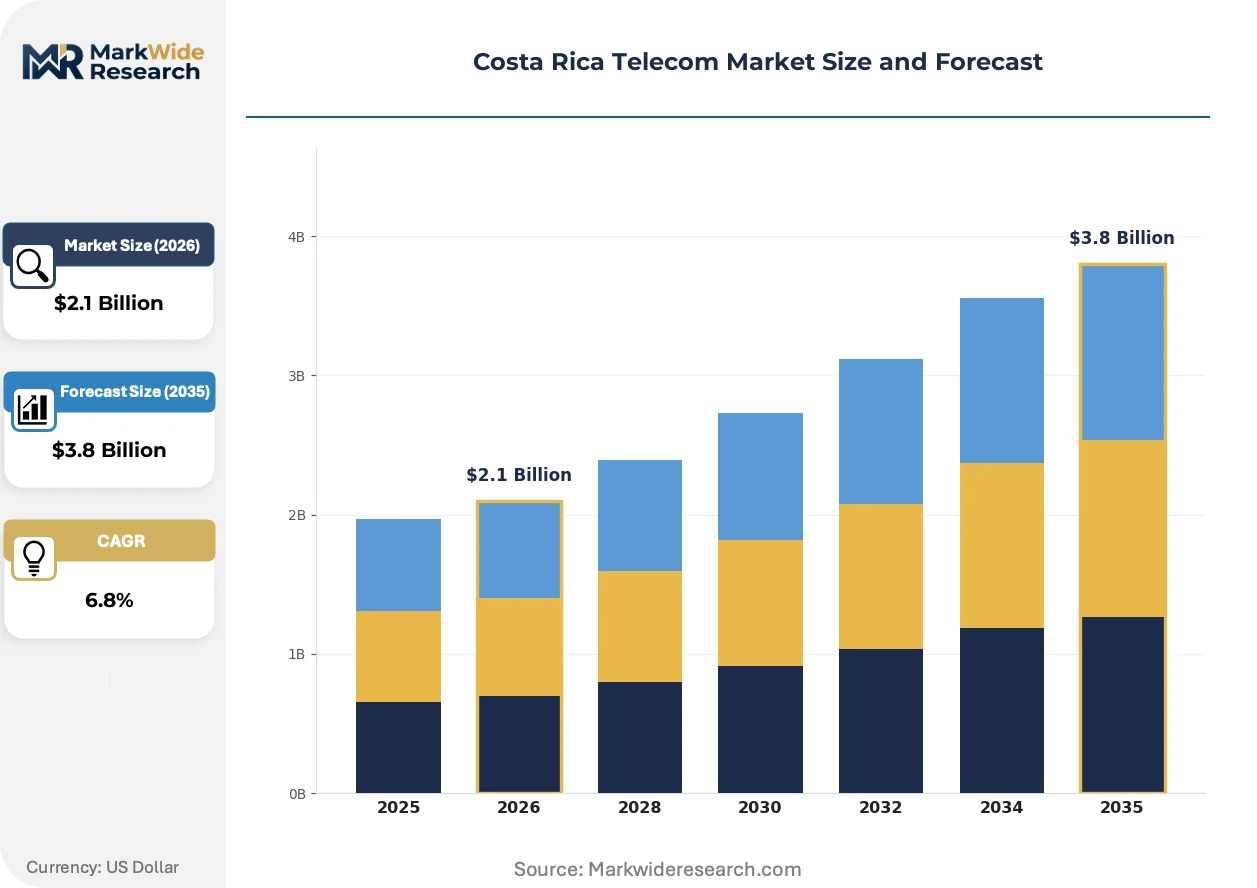
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed-line Services, Broadband Internet, VoIP Services Customer Type: Residential Users, Small Businesses, Large Enterprises, Government Agencies Technology: 4G, 5G, Fiber Optics, DSL Pricing Model: Prepaid Plans, Postpaid Plans, Bundled Services, Pay-as-you-go |
| Companies Covered | Sky Costa Rica, Telecable, ICE Group (Kolbi), Movistar, Cabletica, Liberty Communications of Costa Rica LLC, Tigo Costa Rica, RACSA, Claro Costa Rica, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Costa Rica Telecom Market Trends and Innovations
Network function virtualization is compressing carrier operational models while SUTEL's regulatory calendar and enterprise consumption pattern shifts create simultaneous pressure points across infrastructure and service layers.
Open RAN architecture is automating radio access network deployment for Costa Rican carriers seeking vendor diversification beyond traditional equipment suppliers. Mid-tier operators are piloting disaggregated baseband and radio unit configurations to reduce capital intensity in secondary city rollouts. This modular approach is automating site commissioning timelines and enabling multi-vendor interoperability that legacy integrated systems cannot match.
SUTEL's tower-sharing regulations are mandating passive infrastructure co-location for all licensed spectrum holders above defined coverage thresholds. The policy eliminates redundant steel and power investments while accelerating time-to-market for 5G service launches. Rural cantons with limited tower density are experiencing the most pronounced deployment acceleration as carriers pool rather than duplicate vertical assets.
Enterprise procurement of communications services is consolidating around outcome-based connectivity contracts rather than discrete bandwidth purchases. Manufacturing and logistics verticals in the Central Valley are demanding guaranteed application performance tiers with penalty clauses for latency or packet loss violations. This contractual evolution is most visible among export-oriented firms requiring seamless integration with international cloud regions.
Costa Rica Telecom Market Segmentation
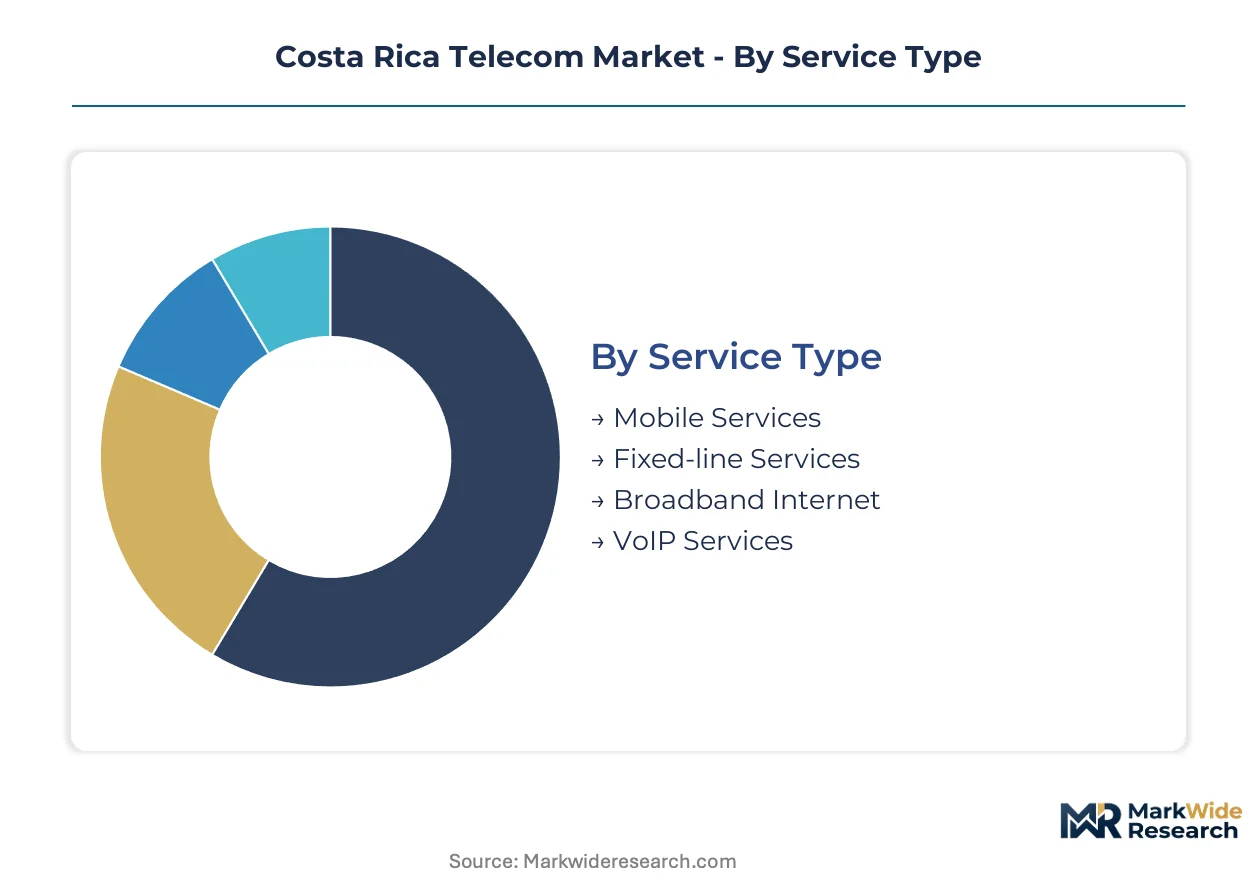
Carrier investment priorities across Costa Rica diverge sharply by segment maturity, with legacy infrastructure defending cash flows while fiber and 5G absorb disproportionate capital deployment. Understanding these segment boundaries clarifies where SUTEL's regulatory pressure translates into actual service differentiation versus commodity pricing.
Service Type:
Standardized subscription mechanics dominate mobile and fixed-line offerings, whereas broadband and VoIP allow greater customization around latency tiers and integration depth.
- Mobile Services:Voice and data transmission over licensed cellular spectrum supports smartphone penetration across urban centers and secondary cities. San José financial services firms drive enterprise mobile data consumption as remote work protocols institutionalize secure application access.
- Broadband Internet:High-capacity fiber and fixed wireless connections achieve sub-10 millisecond latency to the Central Valley's enterprise clusters. ICE Group's state-backed backbone infrastructure creates wholesale access asymmetries that constrain competing retail operators' margin structures.
- Fixed-line Services:Traditional copper-based voice connections persist in legacy residential installations and specific government agency contracts.
- VoIP Services:Packet-switched voice over IP networks enables cost arbitrage for small businesses and international call-intensive operations.
Most installed capacity flows through Mobile Services. Expansion is steepest in Broadband Internet.
Customer Type:
Volume concentration sits with residential subscriptions, while margin extraction concentrates in enterprise and government verticals requiring service-level guarantees.
- Large Enterprises:Dedicated fiber circuits with guaranteed bandwidth and latency specifications support cloud-based unified communications in San José's financial district. Outcome-based connectivity contracts with penalty clauses for performance violations are displacing discrete bandwidth purchases among export-oriented manufacturers.
- Residential Users:Mass-market subscriptions span prepaid mobile, fixed broadband, and bundled entertainment packages across the Greater Metropolitan Area. Liberty Communications competes through cable-TV bundling while Tigo Costa Rica targets secondary city 4G densification.
- Small Businesses:SOHO-grade connectivity combines basic broadband with mobile voice services, often procured through retail channels without customized service terms.
- Government Agencies:Universal service obligation mandates and public procurement frameworks shape contract structures, with Ministry of Science and Technology subsidy flows redirecting investment toward rural canton coverage targets.
Residential Users anchor volume throughput. Large Enterprises command the steepest expansion trajectory for premium connectivity tiers.
Technology:
Maturity gradients separate legacy DSL infrastructure from fiber's performance premium and cellular generations' upgrade cycles.
- Fiber Optics:Glass-core transmission infrastructure delivers sub-10 millisecond latency across ICE Group's state-dominated backbone network. Enterprise adoption accelerates as remote work institutionalizes real-time application performance requirements in San José.
- 5G:Next-generation cellular architecture operates on SUTEL-reallocated mid-band spectrum, with non-standalone deployments requiring 4G core integration. SUTEL's tower-sharing regulations compress redundant steel investments and accelerate time-to-market for service launches.
- 4G:Mature cellular standard saturates urban centers while Tigo Costa Rica pursues aggressive densification in provincial cantons previously served by 3G.
- DSL:Copper-based digital subscriber line technology retains residual presence in legacy residential installations not yet reached by fiber trenching programs.
4G infrastructure carries most installed capacity. Fiber Optics is gaining share fastest among new deployment decisions.
Pricing Model:
Commitment depth varies from zero-contract prepaid flexibility to multi-year bundled convergence arrangements.
- Bundled Services:Fixed-mobile convergence packages combine broadband, mobile voice, video entertainment, and fixed-line into single-contract household relationships. Cable-TV operators leverage latent fiber assets for quadruple-play capture of high-ARPU subscribers in the Greater Metropolitan Area.
- Postpaid Plans:Monthly subscription contracts with device financing components dominate smartphone-centric mobile consumption among credit-qualified residential and enterprise accounts.
- Prepaid Plans:Pay-in-advance mobile subscriptions without contractual commitment serve price-sensitive segments and informal economy participants.
- Pay-as-you-go:Usage-metered pricing without baseline subscription applies to occasional-use scenarios and backup connectivity requirements.
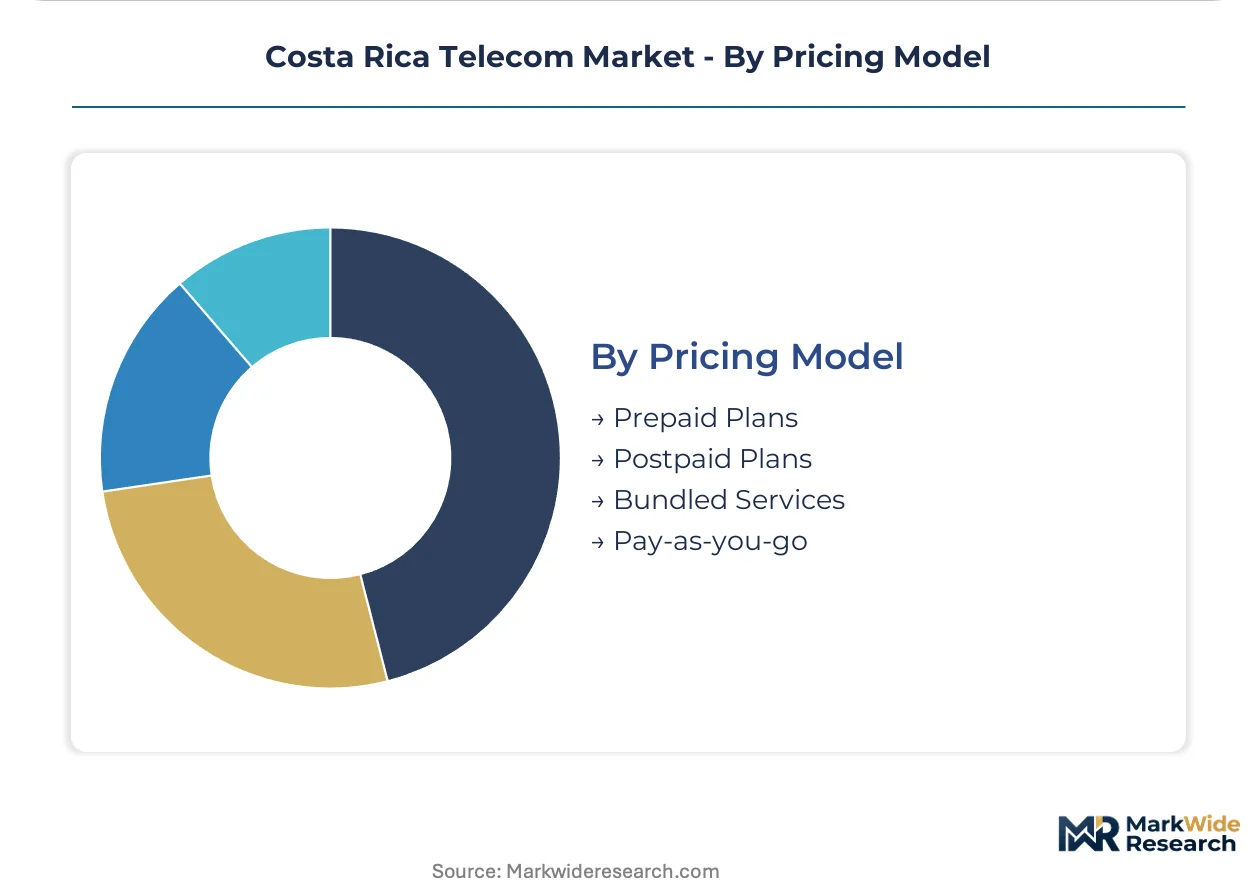
Postpaid Plans process most subscriber-billing volume. Bundled Services shows the steepest margin expansion as operators combat churn through convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Costa Rica's telecom infrastructure density contrasts sharply with Nicaragua's sparser fiber deployment, yet both Central American markets face similar mountainous terrain challenges that inflate rural connectivity costs beyond urban benchmarks.
San José Province
Financial services firms in the capital district drive enterprise fiber demand with sub-10 millisecond latency requirements for cloud-based unified communications. SUTEL's asymmetric interconnection rate framework shapes carrier investment priorities across the metropolitan core. The Central Valley corridor anchors national backbone capacity as ICE Group leverages state-backed infrastructure dominance.
Alajuela Province
Secondary city smartphone saturation creates addressable mobile data markets previously served by 3G networks. The Ministry of Science and Technology's National Telecommunications Plan redirects subsidy flows toward underserved cantons in this northwestern zone. Tigo Costa Rica pursues aggressive 4G densification in provincial centers outside the Greater Metropolitan Area.
Cartago Province
Remote work institutionalization accelerates residential broadband adoption among households historically dependent on mobile connectivity. Municipal environmental review processes for macro-site construction extend rural tower permitting timelines beyond carrier planning horizons. The provincial capital exhibits growing demand for fixed-mobile convergence bundles.
Limón Province
Caribbean coastal cantons exhibit broadband penetration gaps that national subsidy programs specifically target for closure. Tower-sharing regulations mandated by SUTEL accelerate deployment through passive infrastructure co-location. Logistics and agricultural technology firms explore edge computing partnerships enabled by low-latency fiber backhaul expansion.
Guanacaste Province
Tourism-dependent coastal municipalities require redundant connectivity for hospitality and service sector operations. Geographic deployment cost asymmetry imposes fiber trenching expenses substantially above Central Valley benchmarks. Liberty Communications competes through cable-TV bundling in concentrated coastal population centers.
Costa Rica Telecom Market Competitive Landscape
Top-tier vendors anchor infrastructure ownership, while retail service providers compete through bundling and segmentation strategies. The market exhibits tiered concentration around state-backed backbone operators, cable-TV converged players, and mobile-centric challengers. Three archetypes dominate: integrated infrastructure incumbents, converged entertainment-communications platforms, and mobile-first expansionists. Carriers defend position through fixed-mobile convergence packaging and secondary city coverage densification.
Among state-affiliated operators, ICE Group (Kolbi) represents the integrated infrastructure archetype through backbone fiber dominance. Liberty Communications of Costa Rica LLC and Tigo Costa Rica occupy converged platform and mobile expansionist positions respectively, each exemplifying distinct competitive vectors in household and provincial market capture.
| Leading Market Players |
|---|
| Sky Costa Rica |
| Telecable |
| ICE Group (Kolbi) |
| Movistar |
| Cabletica |
| Liberty Communications of Costa Rica LLC |
| Tigo Costa Rica |
| RACSA |
| Claro Costa Rica |
| Others |
Pricing and Supply Chain Analysis
Enterprise procurement of outcome-based connectivity contracts with penalty clauses for latency violations is compressing carrier margin structures and forcing infrastructure operators to prioritize fiber densification over legacy copper maintenance, which in turn elevates capital intensity and reshapes wholesale access pricing across the Central Valley corridor.
Pricing Analysis
Capacity additions in fiber backbone infrastructure are reshaping price floors for broadband services as ICE Group's state-backed deployment programs expand wholesale access availability. Three-tier pricing structure across premium, standard, and economy levels segments residential and enterprise demand, with quality grade and geographic delivery cost as primary differentiation drivers. Cost compression in prepaid mobile tiers is intensifying because Tigo Costa Rica's aggressive 4G densification in secondary cities expands addressable markets. Residential users in the Greater Metropolitan Area exhibit highest price sensitivity, while large enterprises in San José's financial district demonstrate lowest sensitivity due to guaranteed latency requirements.
Supply Chain Analysis
Certification requirements for SUTEL spectrum licensing and tower-sharing compliance create gating barriers for equipment vendors seeking carrier contracts. Supply concentrates in China, South Korea, and the USA for radio access network hardware, optical transmission equipment, and core network software. Raw material dependencies span fiber optic cable, semiconductor components, and steel for tower construction. Single-source vulnerability in 5G baseband chip supply creates structural exposure for non-standalone deployment timelines. Distribution runs through authorized distributor networks serving carrier procurement departments with direct manufacturer relationships for large-scale infrastructure awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Costa Rica's telecom market functions as a regulatory compounder where SUTEL's spectrum reallocation mandates and asymmetric interconnection rate frameworks continuously reshape carrier investment priorities and service differentiation capabilities.
For Market Incumbents: Cement backbone fiber dominance through accelerated trenching programs in the Central Valley corridor before subsidy flows redirect toward rural canton coverage targets. Defend against Liberty Communications' cable-TV bundling and Tigo Costa Rica's 4G densification by deepening fixed-mobile convergence packaging with guaranteed latency tiers for enterprise accounts. Prioritize tower-sharing agreements to reduce redundant steel investments and compress rural deployment timelines. For New Entrants and Emerging Players: Edge computing co-location partnerships with logistics and agricultural technology firms in Limón province offer white-space penetration with lower incumbent density. Caribbean coastal cantons exhibit broadband penetration gaps specifically targeted by Ministry of Science and Technology subsidy flows, creating addressable infrastructure demand. Municipal environmental review process expertise accelerates macro-site permitting timelines beyond carrier planning horizons. For Investors and Strategic Acquirers: Asymmetric upside sits with converged entertainment-communications platforms possessing latent fiber assets for quadruple-play bundling. Long-term viability over the next decade hinges on fixed-mobile convergence execution and secondary city coverage densification. Acquisition target archetypes include cable-TV operators with underutilized fiber plant and regional tower companies with SUTEL-compliant co-location infrastructure. Watch for spectrum auction timeline announcements as inflection indicators for 5G capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Backbone Expansion | ICE Group's state-backed trenching programs anchor wholesale access pricing power across the Central Valley corridor. |
| Fixed-Mobile Convergence Bundling | Cable-TV operators leverage latent fiber assets for quadruple-play capture of high-ARPU households in metropolitan zones. |
| Tower-Sharing Compliance | SUTEL's passive infrastructure co-location mandates eliminate redundant steel investments and accelerate rural 5G deployment. |
| Open RAN Architecture Adoption | Disaggregated baseband configurations reduce capital intensity for secondary city rollouts beyond traditional vendor lock-in. |
| Edge Computing Partnership | Low-latency fiber backhaul enables distributed data center co-location with logistics firms in Limón province. |
Research Methodology
Bottom-up enterprise connectivity modeling reconciled against top-down carrier infrastructure tracking forms the analytical core of this study. Primary interviews with network planning executives at mobile operators, regulatory affairs specialists at SUTEL, enterprise IT procurement officers in San José's financial district, and wholesale access managers at backbone operators combine with secondary validation from SUTEL spectrum auction filings, Ministry of Science and Technology subsidy disbursement records, carrier capex disclosures, and municipal permitting databases. This dual-layer approach triangulates demand-side consumption patterns against supply-side deployment capacity.
Historical trendline analysis of segment revenue trajectories and technology adoption curves establishes baseline growth parameters across the projection horizon. Segmentation dimensions modeled include service type, customer archetype, technology generation, and pricing commitment depth, with additional granularity around geographic deployment zones spanning the Greater Metropolitan Area versus provincial cantons. CAGRs derive from fitted growth curves applied to validated base-year estimates, incorporating SUTEL regulatory calendar milestones and enterprise remote work institutionalization patterns as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to spectrum auction timing, tower-sharing enforcement intensity, and rural subsidy allocation shifts. Forecasts reflect documented assumptions regarding SUTEL regulatory continuity and carrier capital commitment sustainability. A model refresh is warranted upon material change in SUTEL's asymmetric interconnection rate framework or Ministry of Science and Technology National Telecommunications Plan subsidy redirection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Mftpaas Market
Telecommunications
A2P SMS Market
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
Cloud Radio Access Network (C-RAN) Market
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
Telecom Services Market
Telecommunications
Cambodia Telecom Tower Market
Telecommunications
Global Hosted PBX Market
Telecommunications
Utility Communications Market
Telecommunications
5G in Defense Market
Telecommunications
Russia ICT Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Luxembourg Telecom Market
Telecommunications
Australia Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Russia Telecom Market
Telecommunications
LTE Base Station System Market