
 Intimate Hygiene Products Market | 2026-2036
Intimate Hygiene Products Market Size, Share, and Industry Trends Forecast 2026-2036
Intimate Hygiene Products Market Intelligence
A shift from outsourced fragrance and preservative supply toward captive botanical extraction is recalibrating how formulators secure ingredient traceability. Procter & Gamble Company leverages its internal dermatological testing infrastructure to validate pH-specific claims across regional markets. Essity AB anchors its European manufacturing base with integrated absorbent materials research that feeds adjacent personal care categories. Kimberly-Clark Corporation competes through controlled distribution relationships with pharmacy and club retail channels in North America.
Intimate hygiene products encompass cleansers, wipes, gels, sprays, and washes engineered with acidic pH buffers between 3.8 and 4.5 to maintain mucosal compatibility without disrupting native flora. Manufacturers employ cold-process emulsification to preserve heat-sensitive botanical actives such as lactic acid and chamomile extract, yielding solutions for daily perineal and external genital cleansing. Wipes and washes occupy the largest volume positions due to established consumer habits and portable convenience, while gels and sprays capture higher per-unit margins through concentrated dispensing formats and premium positioning. The unisex and teens end-user categories are expanding fastest as brands destigmatize male intimate care and puberty-focused education campaigns broaden early-age product familiarity.
FDA oversight of cosmetic versus drug claims, EU REACH restrictions on sensitizing preservatives, and ECHA classification of certain quaternary ammonium compounds are elevating reformulation costs while rewarding compliant first movers. Brands navigating this framework must document full supply chain ingredient provenance to satisfy retailer audit requirements in both jurisdictions. Stakeholders should monitor pending FDA rulemaking on premarket safety substantiation and prepare scenario plans for potential mandatory adverse-event reporting expansion.
Market Dynamics
EU REACH restrictions on quaternary ammonium compounds and FDA monograph updates are forcing simultaneous reformulation across multiple product lines, compressing development cycles while elevating compliance documentation burdens for intimate hygiene manufacturers serving transatlantic markets.
Growth Catalysts
- pH-balanced formulation science:Advances in cold-process emulsification preserve heat-sensitive botanical actives including lactic acid and chamomile extract, enabling mucosal-compatible daily cleansing solutions.
- REACH chemical disclosure mandates:Tightened ingredient provenance requirements reward first movers with documented supply chain transparency, creating competitive separation from lagging competitors.
- Teen and unisex category expansion:Puberty-focused education campaigns and male intimate care destigmatization are broadening early-age product familiarity and household penetration rates.
Market Restraints
- Plant-derived surfactant cost premiums:Captive botanical extraction infrastructure requires significant capital deployment, squeezing margin structures for mid-tier brands without backward integration.
- German-French-UK demand concentration:Retailer shelf space expansion concentrates in three mature markets, limiting volume growth diversification and amplifying competitive intensity.
- Quaternary ammonium compound reclassification:ECHA restrictions on sensitizing preservatives eliminate established antimicrobial chemistries, necessitating expensive efficacy revalidation.
Strategic Opportunities
- Pharmacy and club retail channel deepening:Controlled distribution relationships in North American pharmacy networks offer margin protection and professional endorsement leverage.
- Integrated absorbent materials research:Adjacent personal care category synergies enable cross-pollination of moisture-management technologies into intimate wipe substrates.
- Pre-teen preventive care positioning:Early intervention messaging creates lifetime value capture through habit formation before competitive brand loyalty solidifies.
Industry Challenges
- Dermatological testing capacity constraints:pH-specific claim validation requires specialized laboratory infrastructure that outstrips available certified testing facility supply.
- Dual-jurisdiction compliance synchronization:Simultaneous FDA premarket safety substantiation and EU supply chain audit documentation creates timeline misalignment and launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intimate Hygiene Products Market |
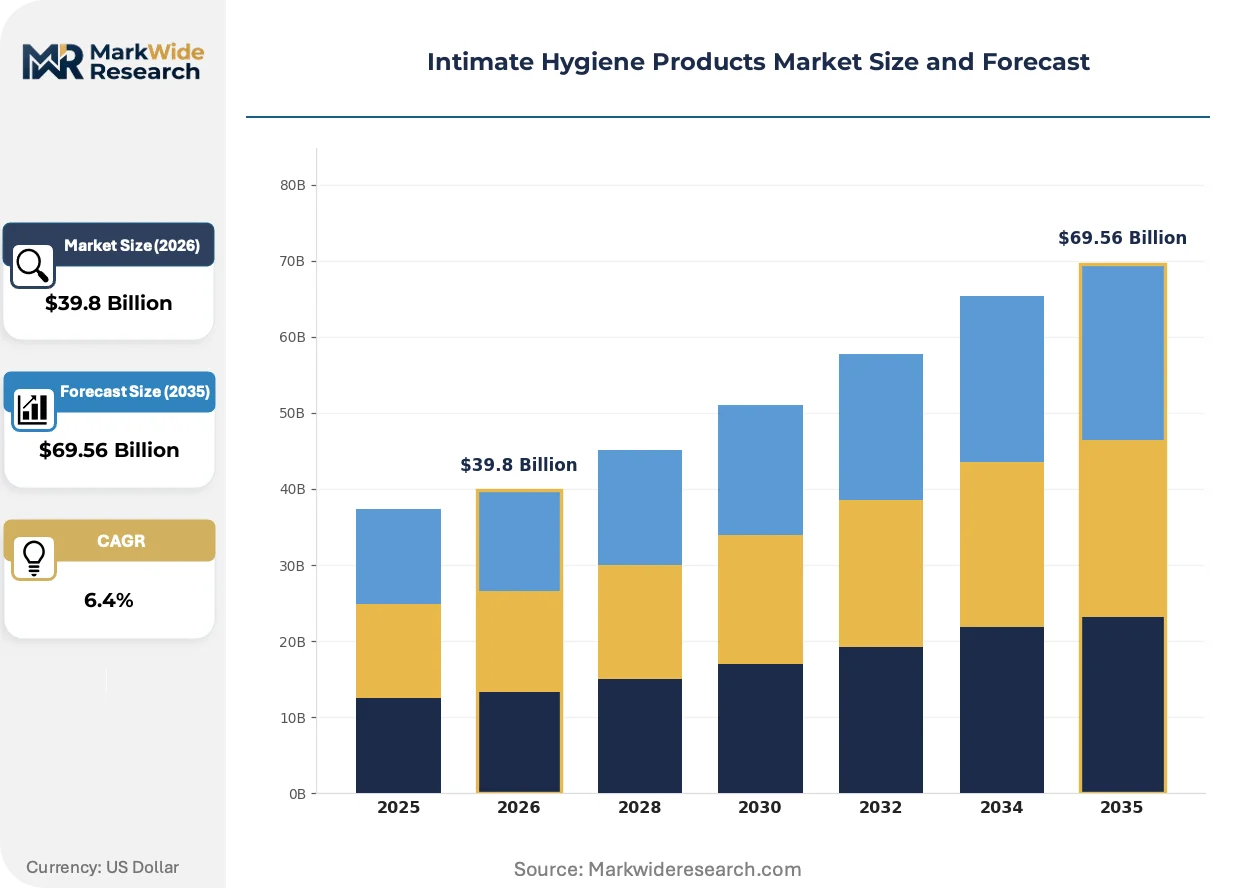
| Market Size in 2026 | $39.8 Billion |
| Market Size in 2035 | $69.56 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wipes, Gels, Sprays, Washes End User: Women, Men, Unisex, Teens Formulation: Natural, Organic, Synthetic, Antibacterial Packaging Type: Bottles, Tubes, Sachets, Jars |
| Companies Covered | Unicharm Corporation, Edgewell Personal Care Company, Procter & Gamble Company, Ontex Group NV, Kao Corporation, Kimberly-Clark Corporation, Johnson & Johnson, Hengan International Group Company Limited, Essity AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intimate Hygiene Products Market Strategic Shifts & Innovations
Cold-process manufacturing and botanical extraction integration are compressing traditional fragrance house intermediation, while regulatory disclosure mandates accelerate transparency investments across formulation development pipelines.
Microbiome-friendly preservation systems are modularizing how formulators approach shelf-life extension without disrupting native genital flora. Premium and professional-grade product lines adopt these systems fastest, compressing the competitive window for conventional preservative-dependent portfolios. This shift is enabling smaller brands to compete on ingredient narrative rather than manufacturing scale.
EU REACH framework updates on endocrine-disrupting chemical screening are elevating reformulation costs for legacy preservative systems. Manufacturers must now document full supply chain ingredient provenance to satisfy retailer audit requirements. Wipes and washes face the steepest compliance burden given their higher preservative loads and skin-contact frequency.
Millennial and Gen Z purchasing patterns favor natural-formulation washes with portable convenience formats. Direct-to-subscription models displace conventional grocery-aisle discovery in North America and Western Europe. Germany and France exhibit the strongest channel migration toward pharmacy-endorsed digital storefronts.
Intimate Hygiene Products Market Segmentation
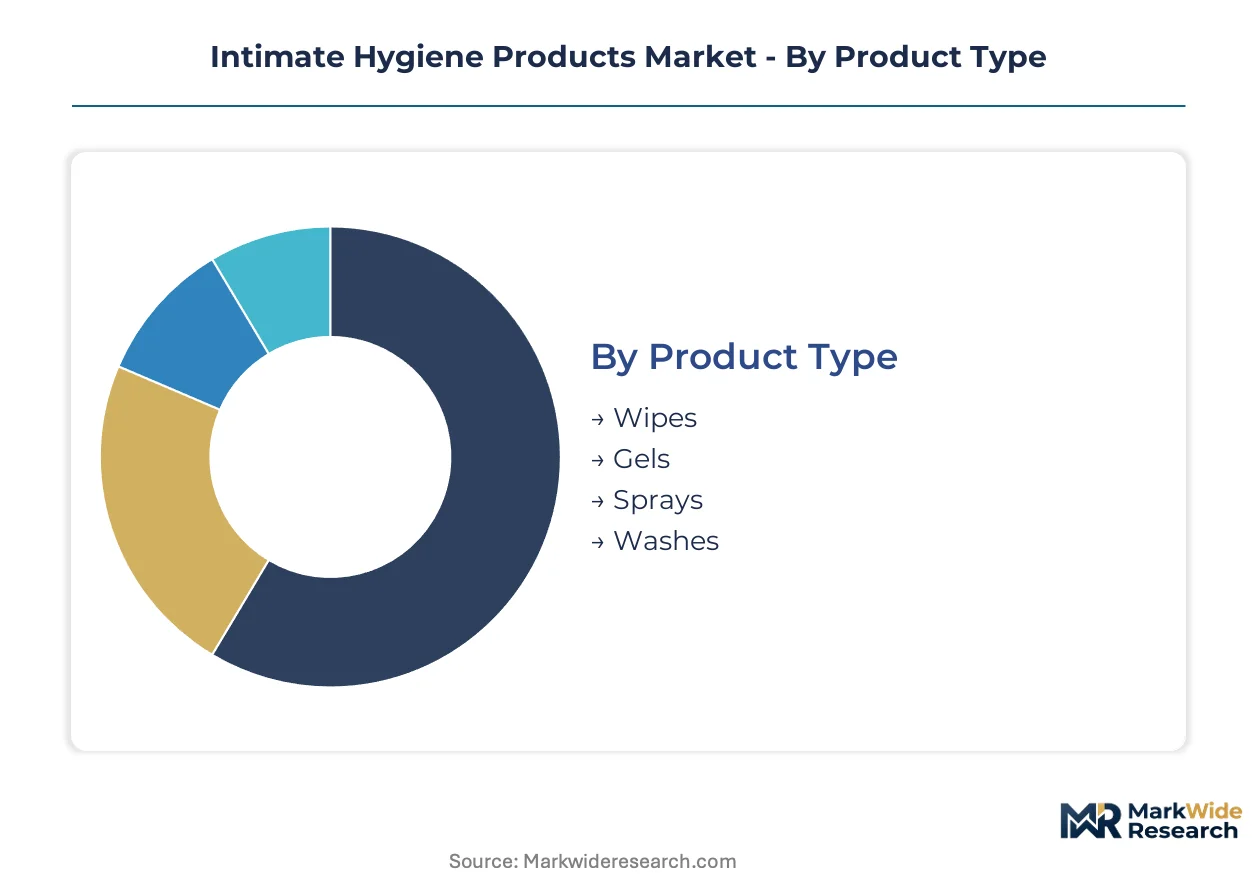
Segmentation in intimate hygiene products reveals distinct capital requirements across manufacturing configurations. Cold-process emulsification equipment for botanical formulations demands specialized infrastructure, while commodity wipes production scales through absorbent materials integration.
Product Type:
Wipes and washes absorb the heaviest capital deployment through integrated substrate manufacturing and pH-buffering production lines.
- Wipes:Nonwoven substrate production requires captive spunlace or airlaid lines costing substantially more than formulation-only facilities. Demand concentrates in Germany and France where pharmacy channel endorsement validates premium positioning. ECHA quaternary ammonium restrictions force preservative system reinvestment.
- Washes:Liquid filling lines with acidic pH stabilization between 3.8 and 4.5 need stainless steel corrosion-resistant tanks and in-line monitoring systems. Millennial and Gen Z women in the United States and United Kingdom drive volume through subscription replenishment models.
- Gels:Concentrated dispensing formats command higher per-unit margins through viscosity-controlled rheology modifiers and precision pump packaging.
- Sprays:Aerosol or finger-spray mechanisms require propellant-safe filling infrastructure with pressure-testing protocols.
Most installed capacity flows through Wipes. Expansion is steepest in Washes.
End User:
Women's products dominate current manufacturing footprint, while unisex and teen positioning requires reformulation investment for pH-neutral and educational packaging adaptations.
- Women:Established pH-specific formulations between 3.8 and 4.5 anchor production scheduling and dermatological testing queues. Germany, France, and the United Kingdom concentrate retailer shelf space expansion for this core demographic.
- Unisex:Marketing repositioning without full reformulation allows margin capture from male intimate care destigmatization campaigns. The United States shows strongest channel migration toward pharmacy-endorsed digital storefronts for this emerging category.
- Men:Dedicated formulations with masculine-coded fragrance profiles require separate production runs but leverage existing filling infrastructure.
- Teens:Puberty-focused education campaigns create lifetime value capture through habit formation before competitive brand loyalty solidifies.
Women's segments retain the largest installed base. Unisex and Teens are climbing the fastest.
Formulation:
Natural and organic segments demand captive botanical extraction infrastructure, while synthetic and antibacterial formulations face regulatory reclassification costs.
- Natural:Cold-process emulsification preserves heat-sensitive actives including lactic acid and chamomile extract. EU REACH disclosure mandates reward documented supply chain transparency with competitive separation from lagging competitors.
- Organic:Certification requirements for ingredient provenance add audit documentation burdens but command shelf space premiums in pharmacy networks.
- Synthetic:Established surfactant chemistries face margin compression from plant-derived alternatives.
- Antibacterial:ECHA quaternary ammonium compound restrictions eliminate established antimicrobial chemistries, necessitating expensive efficacy revalidation.
Natural formulations command the most capital-intensive extraction infrastructure. Organic certification is gaining share fastest.
Packaging Type:
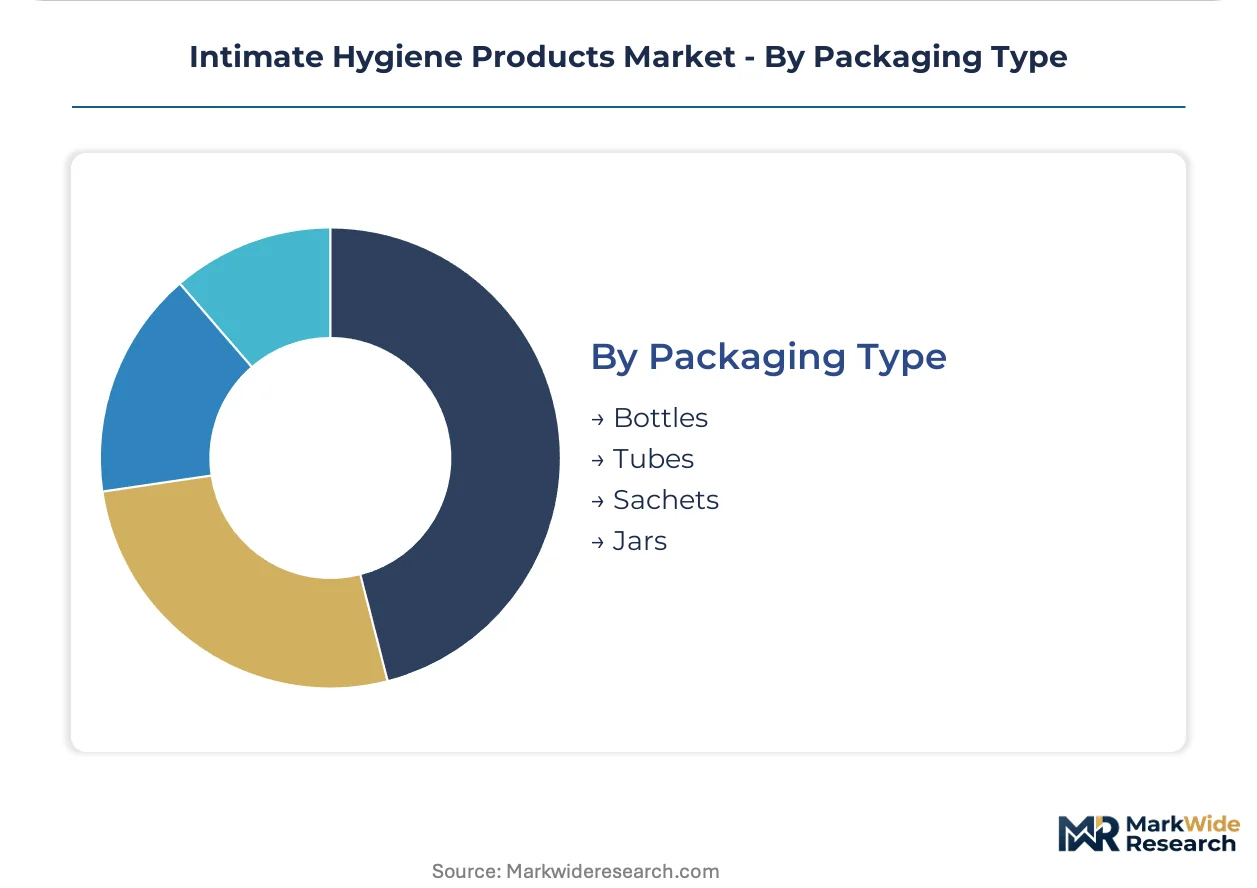
Bottles and tubes require blow-molding or extrusion equipment with acidic pH-compatible resin selection, while sachets minimize unit cost for trial and travel formats.
- Bottles:HDPE or PET containers with flip-top or pump closures dominate wash and gel dispensing. United States pharmacy and club retail channels favor larger volume formats with professional endorsement leverage.
- Tubes:Laminated or extruded plastic tubes suit gel and cream viscosities with precise dosing control.
- Sachets:Single-use foil or film packets minimize per-unit material cost for wipes and wash samples. Portable convenience formats align with Millennial and Gen Z purchasing patterns in North America and Western Europe.
- Jars:Wide-mouth containers serve thicker balm or cream formulations with finger-access application.
Bottles carry the majority of filling line investment. Sachets show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procter & Gamble's Cincinnati headquarters anchors North American formulation science, while Essity's Stockholm base drives European absorbent materials integration across intimate hygiene supply chains.
United States
Pharmacy and club retail channels concentrate demand in the Midwest and Southeast, with subscription replenishment models displacing conventional grocery-aisle discovery. FDA over-the-counter monograph updates tighten ingredient disclosure requirements for pH-specific claims. Greater Boston hosts dermatological testing infrastructure that validates mucosal-compatible formulations for regional market entry.
Germany
Retailer shelf space expansion in the Rhine-Ruhr metropolitan region concentrates volume for natural-formulation washes and wipes. EU REACH chemicals framework mandates full supply chain provenance documentation for plant-derived surfactants. Bavaria's chemical manufacturing corridor supplies cold-process emulsification equipment to domestic and export markets.
France
Parisian pharmacy-endorsed digital storefronts channel Millennial and Gen Z purchasing toward premium positioning formats. ECHA classification of quaternary ammonium compounds forces preservative system reinvestment across wipes production. The Auvergne-Rhône-Alpes region anchors botanical extraction infrastructure for captive ingredient supply.
United Kingdom
Subscription models and portable convenience formats drive wash volume through London and Southeast distribution hubs. UK retailer audit requirements align with EU REACH disclosure mandates despite regulatory divergence. The Midlands manufacturing belt integrates pH-buffering production lines with absorbent materials research facilities.
Japan
Kao Corporation's Tokyo-centered operations exemplify integrated formulation and substrate manufacturing for wipes and washes. METI guidelines on cosmetic safety substantiation elevate documentation burdens for antimicrobial product lines. The Kansai region around Osaka hosts precision pump packaging suppliers serving concentrated gel and spray formats.
Intimate Hygiene Products Market Key Industry Players
Global majors compete with regional champions across distribution channel access and dermatological testing infrastructure, producing a tiered structure where scale-driven portfolios coexist with specialized natural-formulation brands. Consolidation pressure concentrates among mid-tier players lacking captive botanical extraction or backward integration into substrate manufacturing. Three archetypes dominate: integrated personal care conglomerates with internal testing facilities, absorbent materials specialists leveraging adjacent category synergies, and regional hygiene players with pharmacy channel relationships. Capacity expansion and strategic partnerships represent the dominant competitive moves, with M&A activity targeting botanical extraction capabilities and pH-specific formulation expertise.
Among integrated personal care conglomerates, Procter & Gamble Company and Kimberly-Clark Corporation occupy positions defined by controlled distribution relationships and dermatological validation infrastructure. Essity AB anchors the European manufacturing base archetype with integrated absorbent materials research feeding adjacent personal care categories. Johnson & Johnson exemplifies the pharmacy-endorsed positioning tier through professional channel leverage in North American and Western European markets. These three entities represent distinct strategic postures without implying specific market share or operational metrics.
| Leading Market Players |
|---|
| Unicharm Corporation |
| Edgewell Personal Care Company |
| Procter & Gamble Company |
| Ontex Group NV |
| Kao Corporation |
| Kimberly-Clark Corporation |
| Johnson & Johnson |
| Hengan International Group Company Limited |
| Essity AB |
| Others |
Cost & Logistics Intelligence
EU REACH disclosure mandates for botanical ingredient provenance gate both qualified supply and premium-tier pricing access, compressing margins for brands lacking captive extraction infrastructure while rewarding documented transparency with pharmacy channel premiums. German and French retailers now audit full supply chain documentation as a condition of shelf space allocation, effectively bifurcating the market between compliant and non-compliant supply bases.
Pricing Analysis
Input-cost pass-through from cold-process emulsification equipment and stainless steel pH-buffering tanks runs through formulation pricing, with plant-derived surfactant premiums widening spreads between natural and synthetic tiers. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-endorsed botanical lines from club retail value packs and grocery-channel generics. Cost compression in mid-tier wipes is intensifying because ECHA quaternary ammonium restrictions force preservative system reinvestment. Mass-market buyers exhibit highest price sensitivity, while pharmacy-channel purchasers accept formulation premiums for dermatological validation.
Supply Chain Analysis
Freight cost volatility from Bavaria's chemical manufacturing corridor to Rhine-Ruhr distribution hubs elevates landed costs for pH-stabilization equipment and botanical extracts. Supply concentrates in Germany, France, and the United Kingdom for finished goods, with raw material dependencies spanning chamomile cultivation in Auvergne-Rhône-Alpes, lactic acid fermentation in the Netherlands, and nonwoven substrate production in Sweden. Single-source vulnerability in dermatological testing infrastructure creates bottlenecks for pH-specific claim validation. Distribution runs through pharmacy networks and club retail channels in North America, with subscription models displacing conventional grocery-aisle discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Millennial and Gen Z demand shifts toward natural-formulation washes with documented supply chain transparency justify premium positioning investments.
For Market Incumbents: Lock in captive botanical extraction capacity before EU REACH disclosure mandates harden into non-negotiable retailer audit requirements. Essity AB's integrated absorbent materials model demonstrates how backward integration into substrate manufacturing defends margin structures against mid-tier competitors lacking cold-process emulsification infrastructure. Priority levers include dermatological testing queue control and pharmacy channel relationship deepening. For New Entrants and Emerging Players: Enter via male intimate care destigmatization campaigns targeting United States pharmacy-endorsed digital storefronts, where unisex positioning requires minimal reformulation investment. The teen preventive care segment offers penetrable white space through puberty-focused education partnerships with school health programs. Direct-to-subscription models bypass incumbent shelf space dominance. For Investors and Strategic Acquirers: Roll-up economics work for regional hygiene players with pharmacy channel relationships because consolidation pressure concentrates among mid-tier brands lacking captive botanical extraction or pH-specific formulation expertise. Long-term viability hinges on 5-10 year regulatory compliance trajectory rather than volume scale alone. Watch FDA premarket safety substantiation rulemaking as inflection indicator for compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Botanical Extraction | EU REACH disclosure mandates reward documented supply chain transparency with competitive separation. |
| Pharmacy Channel Deepening | Controlled distribution relationships in North America offer margin protection and professional endorsement leverage. |
| pH-Specific Formulation R&D | Cold-process emulsification preserves heat-sensitive actives for mucosal-compatible daily cleansing solutions. |
| Subscription Model Launch | Direct-to-consumer replenishment displaces conventional grocery-aisle discovery among Millennial and Gen Z purchasers. |
| Teen Preventive Care Positioning | Early intervention messaging creates lifetime value capture before competitive brand loyalty solidifies. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at pharmacy and club retail channels, supply planners, and dermatological testing facility directors with secondary validation from FDA over-the-counter monograph filings, ECHA REACH substance registrations, Nielsen retail audit data, and customs records. Bottom-up demand modeling and top-down supply capacity assessments triangulated volume and value outputs.
Segment-weighting across product type, end user, formulation, and packaging dimensions anchored the analytical framework over the projection horizon. CAGRs derived from installed capacity expansion schedules, retailer shelf space allocation trends, and subscription model adoption curves. Industry-specific inputs included dermatological testing queue lengths, cold-process emulsification equipment lead times, and botanical extract spot pricing volatility.
Inputs from primary interviews and regulatory filings were available through the study window; gaps in real-time subscription churn data and teen segment household penetration rates introduce uncertainty bands around volume assumptions. Forecasts reflect documented assumptions subject to revision from FDA rulemaking timing, ECHA reclassification decisions, and raw material cost movements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Body Firming Creams Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
Pre-Shave Care Market
Beauty & Personal Care
Salon Service Market
Beauty & Personal Care
Global Organic Hair Color Market
Beauty & Personal Care
Cosmetics Face Serum Market
Beauty & Personal Care
Deodorant and Antiperspirants Market
Beauty & Personal Care
Post-Shave Care Market
Beauty & Personal Care
Europe Lip Care Products Market
Beauty & Personal Care
Facial Cleansers and Toners Market
Beauty & Personal Care
Spas and Beauty Salons Market
Beauty & Personal Care
Body Balm Market
Beauty & Personal Care
Hair Removal Epilator Market
Beauty & Personal Care
South America Deodorants Market
Beauty & Personal Care
Argentina Beauty and Personal Care Products Market