
 Facial Cleansers and Toners Market | 2026-2036
Facial Cleansers and Toners Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Cleansers and Toners Market Analysis
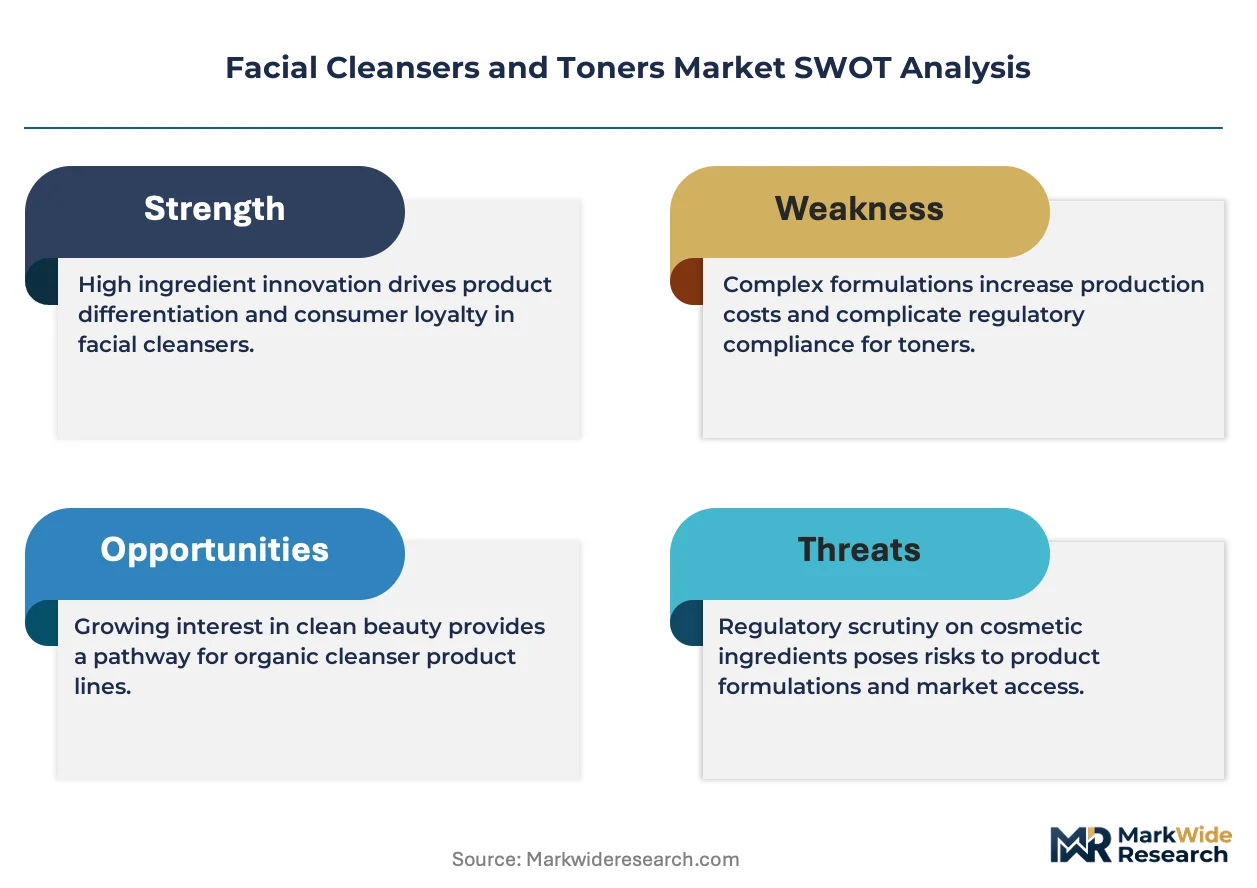
EU Green Deal chemical footprint disclosure rules is consolidating demand around biodegradable surfactant formulations. L'Oréal S.A. leverages its integrated raw-materials research to preempt compliance costs. Unilever anchors its portfolio through mass-market gel cleansers with certified biodegradable bases. Beiersdorf AG differentiates via alcohol-free toners engineered for barrier-sensitive skin profiles.
Facial cleansers and toners comprise liquid or semi-liquid topical preparations designed to remove sebum, particulate matter, and residual cosmetics from skin surfaces, typically employing surfactant systems at pH 4.5–6.5 matched to acid mantle chemistry; toners follow with astringent or hydrating aqueous solutions to restore post-cleansing moisture balance and prepare skin for subsequent treatment steps. Gel cleansers dominate volume through universal compatibility across oily and combination skin types, while micellar water captures margin concentration in travel-format and sensitive-skin niches. Specialty beauty stores retain the highest per-unit price realization, though online retail channels are capturing frequency-driven replenishment purchases.
EMA cosmetic ingredient safety assessments, REACH chemical registration thresholds, and FDA cosmetic labeling requirements collectively elevate compliance costs for synthetic preservative systems and fragrance allergens. These frameworks push manufacturers toward natural extracts and alcohol-free formulations that satisfy multi-jurisdiction dossier standards. Stakeholders must monitor pending FDA fragrance allergen disclosure mandates and EU microplastic restriction timelines to calibrate reformulation pipelines and inventory transition schedules.
Market Dynamics
The Facial Cleansers and Toners Market is compressing around biodegradable surfactant compliance as the EU Green Deal's chemical footprint disclosure rules force wholesale formulation redesign across major manufacturing bases.
Growth Catalysts
- REACH chemical registration thresholds:ECHA mandates are accelerating industry consolidation toward pre-registered surfactant portfolios, advantaging incumbents with established dossiers.
- Seoul dermatology-linked consumption patterns:South Korean clinic-channel toner prescriptions normalize multi-step regimens among male demographics.
- Biodegradable base certification:ISO 16128-compliant raw materials are capturing premium shelf placement in specialty beauty retail.
Market Restraints
- Palm kernel oil supply concentration:Southeast Asian oleochemical feedstock volatility compresses margin stability for sulfate-free formulations.
- Synthetic preservative technical limitations:Phenoxyethanol alternatives exhibit shorter shelf stability, forcing cold-chain distribution investments.
- FDA fragrance allergen disclosure friction:Pending labeling mandates create inventory transition risk for legacy stock-keeping units.
Strategic Opportunities
- India tier-two urban penetration:BIS cosmetic safety standards harmonization opens organized retail access beyond metro pharmacy chains.
- Micellar water travel-format expansion:Aviation-compliant sub-100ml packaging captures airport duty-free and gym-channel replenishment.
- Alcohol-free barrier repair convergence:Ceramide-infused toner technology intersects with post-procedure skincare protocols.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise in natural extract stabilization commands premium compensation, constraining mid-tier R&D scaling.
- Multi-jurisdiction dossier capex intensity:Parallel EMA, FDA, and MFDS filing requirements demand dedicated regulatory affairs infrastructure.
- Microplastic restriction timeline uncertainty:EU restriction proposals for polyethylene exfoliants force speculative reformulation pipeline bets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Cleansers and Toners Market |
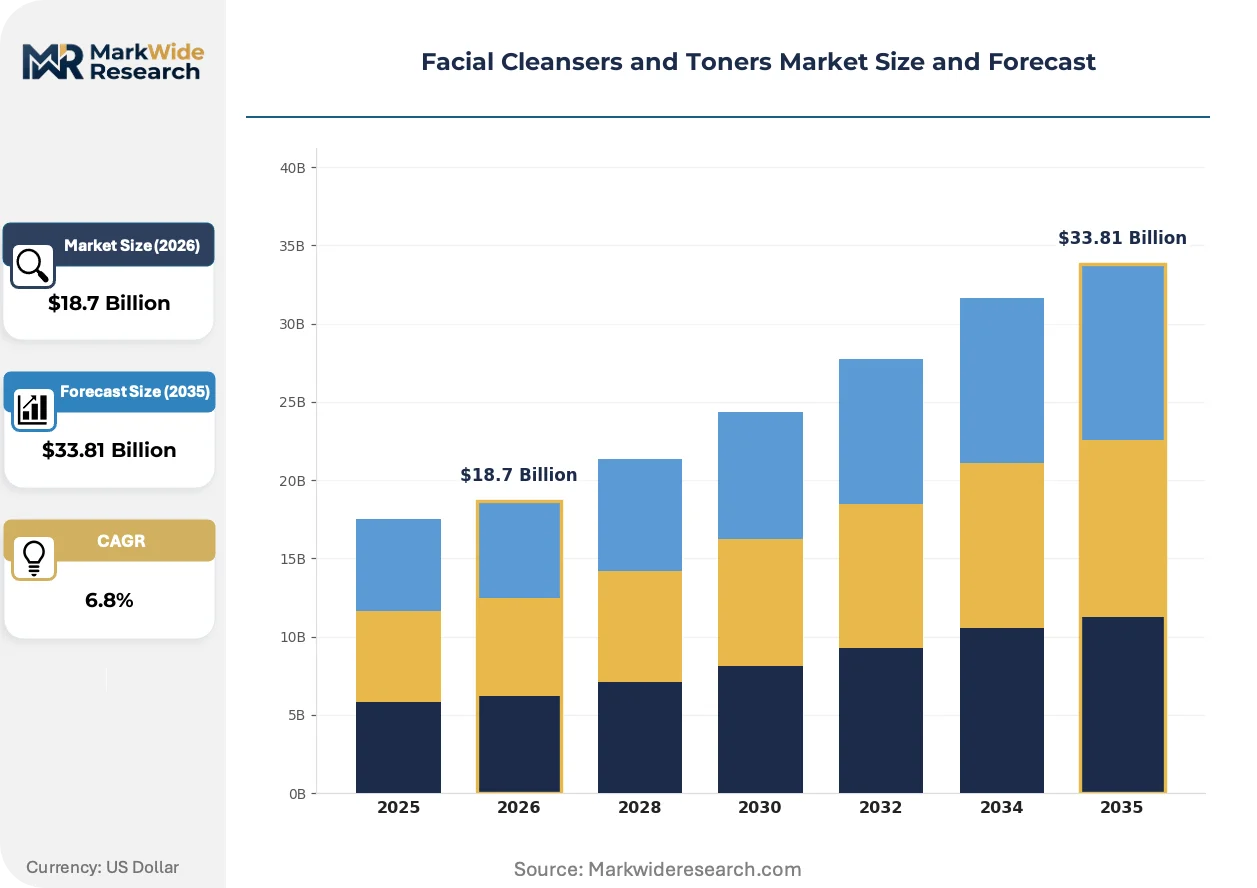
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel Cleanser, Foam Cleanser, Micellar Water, Exfoliating Toner Skin Type: Oily, Dry, Sensitive, Combination Ingredient Type: Natural Extracts, Synthetic Ingredients, Alcohol-Free, Antibacterial Distribution Channel: Online Retail, Drugstores, Supermarkets, Specialty Beauty Stores |
| Companies Covered | L'Oréal S.A., Unilever, Procter & Gamble, Johnson & Johnson, Estée Lauder Companies, Beiersdorf AG, Shiseido Company, Kao Corporation, LVMH Moët Hennessy Louis Vuitton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Cleansers and Toners Market Emerging Trajectories
Formulation chemistry and channel economics are diverging sharply as regulatory pressure and consumption-pattern shifts rewrite competitive rules across preparation types and retail formats.
Biodegradable alkyl polyglucoside surfactant systems are overtaking traditional sodium lauryl sulfate in mass-market gel cleanser production. Male grooming adopters in Seoul and Tokyo are switching to APG-based products at twice the rate of female cohorts. This chemistry transition is compressing commodity surfactant margins while rewarding integrated oleochemical producers with captive biobased feedstock.
REACH Annex XVII microplastic restriction proposals are forcing exfoliant particle redesign across EU-manufactured scrubs and cleansers. The industrial consequence is a scramble toward cellulose bead and jojoba ester alternatives with equivalent sensory profiles. Rinse-off products containing polyethylene microspheres face the steepest compliance timeline, with German and French formulators already completing inventory transitions.
Subscription-based replenishment purchasing is fragmenting traditional supermarket and pharmacy channel dominance. Direct-to-consumer platforms with AI skin-diagnostic onboarding are displacing in-person consultation for toner selection in South Korea and urban China. This behavioral shift is most visible among 25-34 year-old consumers in Seoul, where monthly auto-replenish rates for pH-balancing toners now exceed single-unit purchase frequency.
Facial Cleansers and Toners Market Segmentation
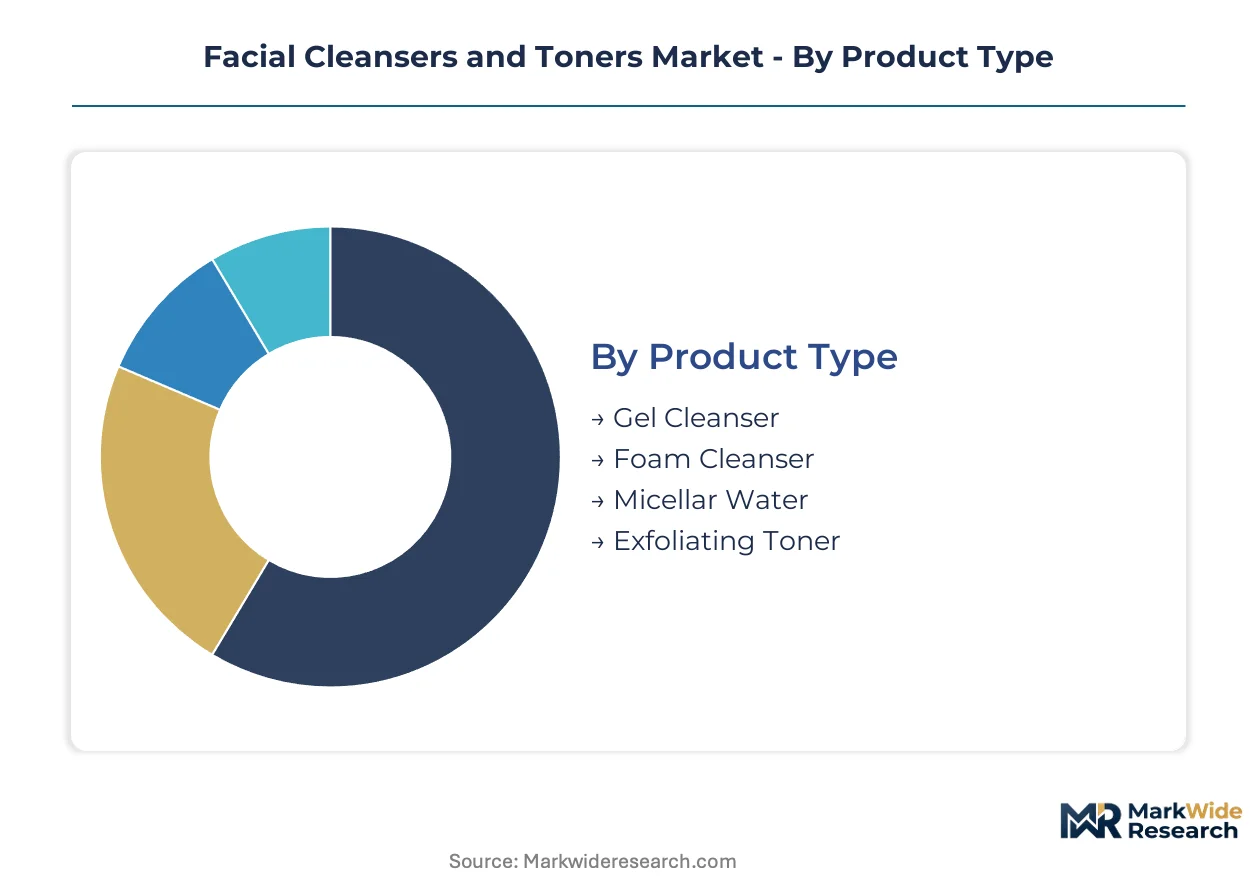
Facial cleansers and toners fragment across four distinct axes that determine formulation chemistry, retail economics, and regulatory exposure. Product type governs manufacturing complexity and margin structure. Skin type and ingredient type dictate R&D priority and compliance burden. Distribution channel shapes pricing power and customer acquisition cost.
Product Type:
Buyers select formats based on skin tolerance thresholds, travel convenience needs, and step-complexity preferences in their regimens.
- Gel Cleanser:Surfactant-based aqueous gels employing mild anionic or amphoteric systems at pH 5.0–6.0 dominate mass-market production for oily and combination skin. Demand concentrates in drugstore and supermarket channels across Germany and France, where ISO 16128-compliant biodegradable bases now command shelf priority under EU Green Deal disclosure rules.
- Micellar Water:Micelle-suspension aqueous solutions using non-ionic surfactant clusters enable no-rinse cleansing for sensitive skin and travel contexts. South Korean and Japanese consumers drive premium positioning, with sub-100ml aviation-compliant formats capturing airport duty-free and gym-channel replenishment frequency.
- Foam Cleanser:Aerosol-dispensed or pump-activated surfactant foams deliver airy texture preferred in humid climates.
- Exfoliating Toner:Acid-based or physical-particle aqueous solutions for cell turnover, now reformulating around cellulose bead alternatives pending REACH microplastic restrictions.
Gel cleansers lead volumes today; micellar water is gaining share fastest.
Skin Type:
Formulation investment intensity escalates toward barrier-compromised and reactive skin profiles where clinical validation commands price premiums.
- Sensitive:Fragrance-free, pH-buffered, and preservative-minimized preparations requiring dermatological testing documentation. Demand clusters in Seoul clinic-channel prescriptions and German pharmacy distribution, where alcohol-free and ceramide-infused specifications intersect with post-procedure skincare protocols.
- Oily:Sebum-regulating cleansers with salicylic acid or niacinamide actives for pore management. Urban male demographics in Tokyo and Mumbai drive frequency-driven replenishment through subscription platforms.
- Dry:Lipid-replenishing cream or oil-based cleansers with occlusive emollients.
- Combination:Zone-targeted formulations balancing T-zone oil control with cheek hydration.
Oily skin formulations lead volumes today; sensitive skin products are expanding most quickly.
Ingredient Type:
Raw material sourcing strategy separates compliance-ready integrated producers from exposed commodity-dependent competitors.
- Natural Extracts:Plant-derived surfactants, botanical antioxidants, and fermented actives requiring stabilization expertise and supply chain traceability. South Korean manufacturers leverage domestic ginseng and green tea extract portfolios, while EU formulators face ECHA botanical allergen dossier requirements.
- Alcohol-Free:Glycol and polyol-based preservation and texture systems replacing ethanol for barrier-sensitive applications. German and French pharmacy channels mandate this specification for rosacea and eczema-prone demographics.
- Synthetic Ingredients:Petrochemical-derived surfactants and preservatives facing REACH registration cost pressure and consumer perception headwinds.
- Antibacterial:Triclosan-replacement formulations using benzalkonium chloride or natural alternatives, constrained by FDA OTC monograph and EU biocidal product regulation.
Synthetic ingredients lead volumes today; natural extracts are climbing the fastest.
Distribution Channel:
Channel selection determines margin capture, customer data access, and inventory risk exposure across replenishment versus discovery purchase occasions.
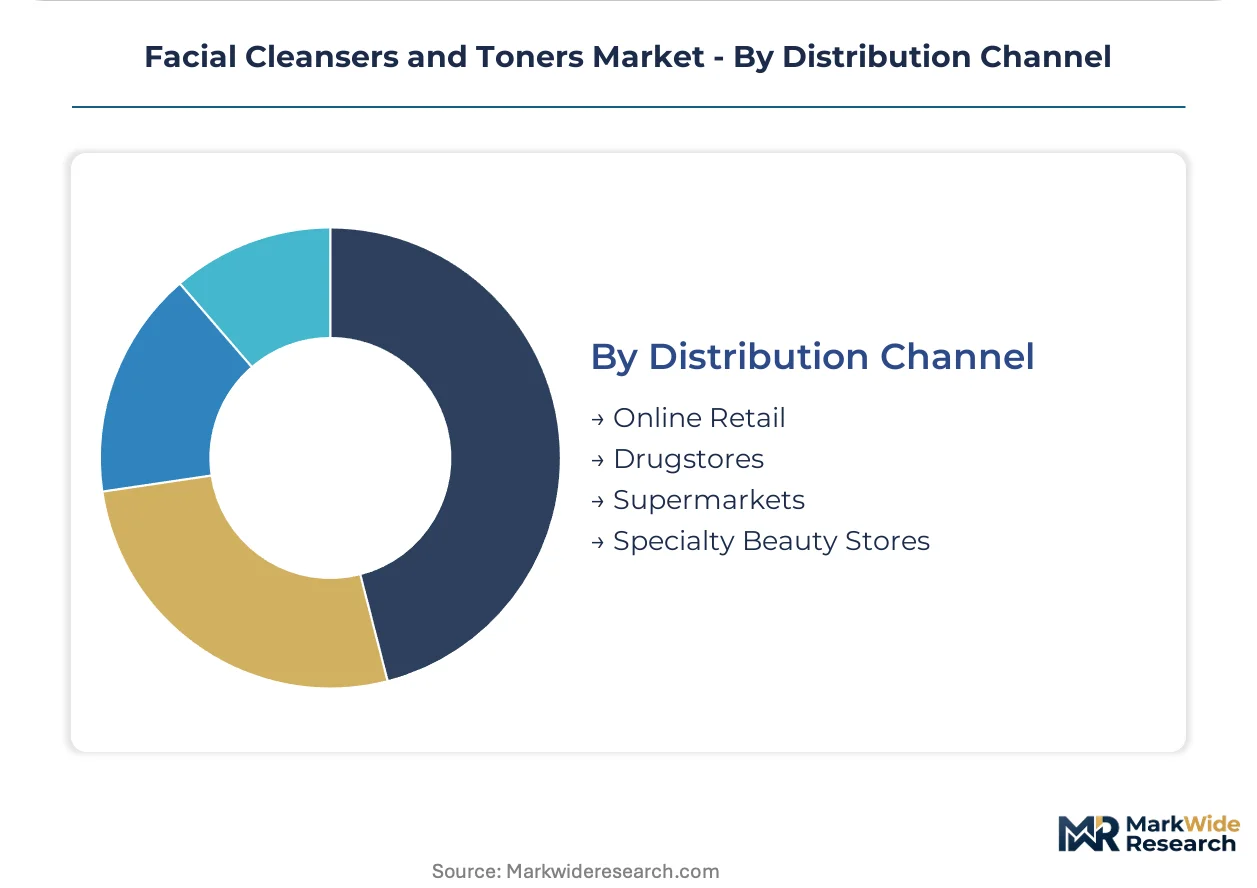
- Online Retail:Direct-to-consumer platforms with AI skin-diagnostic onboarding and subscription auto-replenishment. Seoul and Shanghai urban consumers aged 25–34 exhibit monthly auto-replenish rates for pH-balancing toners exceeding single-unit purchase frequency.
- Specialty Beauty Stores:Sephora, Douglas, and regional prestige retailers delivering highest per-unit price realization through consultation-assisted selection and exclusive SKU distribution.
- Drugstores:Pharmacy-regulated channels in Germany, France, and Japan with pharmacist consultation requirements and reimbursement-adjacent positioning for sensitive skin ranges.
- Supermarkets:Mass-volume, low-margin distribution for basic gel cleansers and familiar brand formats.
Specialty beauty stores lead per-unit margins today; online retail is capturing frequency fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The facial cleansers and toners industry traces its modern formulation lineage to post-war European pharmacy channels, where German and French dermatological traditions established the acid-mantle pH protocols that now govern global standards.
United States
FDA cosmetic labeling requirements and pending fragrance allergen disclosure mandates are compressing inventory timelines for legacy synthetic preservative systems. Male grooming adopters in Brooklyn and Austin are driving subscription-based replenishment for pH-balancing toners through direct-to-consumer platforms. California-based formulators are accelerating reformulation pipelines toward biodegradable surfactant bases ahead of anticipated state-level chemical disclosure expansion.
Germany
ECHA REACH registration thresholds and EU Green Deal chemical footprint rules are consolidating demand around pre-registered surfactant portfolios. Pharmacy-regulated distribution in Berlin and Munich maintains strict alcohol-free specifications for rosacea-prone demographics. Bavarian oleochemical producers are capturing margin premiums through captive biobased feedstock integration for sulfate-free gel cleanser manufacturing.
South Korea
MFDS cosmetic safety dossiers and clinic-channel prescription patterns normalize multi-step regimens among male demographics in Seoul. Dermatology-linked toner consumption concentrates in Gangnam and Seongnam beauty districts, where post-procedure ceramide-infused specifications command price premiums. Domestic ginseng and green tea extract portfolios anchor natural extract stabilization expertise for export-oriented manufacturers.
Japan
METI chemical substance management and PMDA quasi-drug classifications constrain antimicrobial cleanser claims while privileging barrier-repair positioning. Tokyo and Osaka consumers exhibit twice the adoption rate of APG-based products versus female cohorts. Kansai-region formulators specialize in aerosol-dispensed foam cleanser texture engineering for humid-climate distribution.
India
BIS cosmetic safety standards harmonization is opening organized retail access beyond Mumbai and Delhi metro pharmacy chains. Tier-two urban penetration in Pune and Hyderabad is driving frequency-driven replenishment for sebum-regulating oily skin formulations. Domestic manufacturers are navigating palm kernel oil feedstock volatility through Southeast Asian oleochemical supply contracts.
Facial Cleansers and Toners Market Vendor Landscape
Capital-heavy integrated producers with captive raw-materials research compete with asset-light brand marketers licensing formulation technology from third-party laboratories. The market structure concentrates around three strategic tiers: conglomerate beauty divisions with global regulatory affairs infrastructure, regional pharmacy-channel specialists with dermatologist endorsement networks, and direct-to-consumer platforms with AI skin-diagnostic onboarding capabilities. Dominant competitive moves include backward integration into biobased surfactant feedstock and subscription-based customer acquisition replacing traditional retail slotting fees.
Within the conglomerate tier, L'Oréal S.A., Unilever, and Beiersdorf AG exemplify divergent strategic postures. The French S.A. structure anchors integrated raw-materials research capabilities that preempt multi-jurisdiction compliance costs. The Anglo-Dutch multinational occupies mass-market gel cleanser positioning through certified biodegradable base certification. The German AG differentiates via alcohol-free toner engineering for barrier-sensitive skin profiles in pharmacy-regulated channels.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Unilever |
| Procter & Gamble |
| Johnson & Johnson |
| Estée Lauder Companies |
| Beiersdorf AG |
| Shiseido Company |
| Kao Corporation |
| LVMH Moët Hennessy Louis Vuitton |
| Others |
Supply Flow & Price Mechanics
Palm kernel oil feedstock volatility from Southeast Asian oleochemical producers cascades through sulfate-free formulation costs into premium-mid-economy pricing stratification across German and French pharmacy channels.
Pricing Analysis
Subscription-based replenishment models anchored in Seoul and Shanghai direct-to-consumer platforms are displacing per-unit transactional pricing in toner categories. Price differentiation separates ISO 16128-certified biodegradable bases from commodity surfactant formulations, with certification tier and volume scale as primary drivers. Cost compression in mass-market gel cleansers is intensifying due to REACH registration dossier amortization. Subscription adopters in the 25-34 demographic exhibit lowest price sensitivity; supermarket mass-market buyers face highest elasticity.
Supply Chain Analysis
Return flows for unsold inventory and expired preservative systems create reverse-logistics complexity for phenoxyethanol-alternative formulations with shortened shelf stability. Manufacturing concentrates in Germany, France, and South Korea, with Bavarian oleochemical producers and Seoul-based ginseng extract specialists anchoring upstream capacity. Feedstock draws from Malaysian and Indonesian palm kernel estates, South Korean green tea cooperatives, and German biobased surfactant pilot plants. Single-source vulnerability concentrates in Southeast Asian oleochemical supply contracts. Distribution runs through pharmacy-regulated channels in Berlin and Munich, specialty beauty retail in Gangnam, and AI-diagnostic direct-to-consumer platforms in Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facial cleansers and toners function as a stable compounder anchored by regulatory-driven reformulation cycles that perpetually refresh replacement demand across biodegradable surfactant transitions.
For Market Incumbents: Anticipate REACH microplastic restriction timelines by accelerating cellulose bead and jojoba ester alternative validation in exfoliating toner pipelines. Preempt FDA fragrance allergen disclosure mandates through natural extract stabilization R&D investment. Consolidate backward integration into captive biobased feedstock to defend margin position against oleochemical price volatility. For New Entrants and Emerging Players: Direct-to-consumer platforms with AI skin-diagnostic capabilities offer the most penetrable entry vector for pH-balancing toner categories in tier-two Indian cities beyond Mumbai and Delhi pharmacy chains. White-space targets include aviation-compliant sub-100ml micellar water formats for airport duty-free and gym-channel replenishment. Go-to-market execution should anchor in BIS cosmetic safety standards harmonization for organized retail access. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction dossier capex demands exceed mid-tier R&D scaling capacity, fragmenting formulation expertise across natural extract stabilization. Long-term viability favors integrated producers with captive raw-materials research and established EMA-FDA-MFDS regulatory affairs infrastructure. Acquisition target archetype: regional pharmacy-channel specialists with dermatologist endorsement networks in Seoul or Berlin. Monitor EU microplastic restriction implementation timelines as inflection indicator for exfoliant category inventory transition risk.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Surfactant Transition | REACH Annex XVII compliance secures EU Green Deal shelf priority in German pharmacy channels. |
| AI Skin-Diagnostic Platform Launch | Direct-to-consumer onboarding captures subscription auto-replenishment frequency in Seoul urban demographics. |
| Ceramide-Infused Toner Development | Post-procedure specifications command price premiums in Gangnam clinic-channel prescriptions. |
| Aviation-Compliant Format Expansion | Sub-100ml packaging unlocks airport duty-free and gym-channel replenishment velocity. |
| Backward Integration into Biobased Feedstock | Captive oleochemical supply insulates margin stability from Malaysian palm kernel volatility. |
Methodological Framework
Direct dialogue with cosmetic formulation chemists, regulatory affairs directors at conglomerate beauty divisions, pharmacy channel buyers in Berlin and Munich, and Seoul-based dermatology clinic procurement managers grounded qualitative insights. Secondary validation drew from ECHA REACH registration databases, MFDS cosmetic safety dossiers, FDA cosmetic labeling guidance documents, and ISO 16128 standard certification records. Bottom-up segment sizing triangulated against top-down market consolidation estimates.
Segmentation-level outputs across product type, skin type, ingredient sourcing strategy, and distribution channel fed into analytical framework spanning the projection horizon. CAGRs derived from surfactant chemistry transition curves, male grooming adoption velocity in Tokyo and Seoul, and subscription platform penetration rates in urban China and India. Industry-specific inputs included biodegradable base certification adoption timelines and clinic-channel prescription normalization patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU microplastic restriction implementation timing and Southeast Asian oleochemical feedstock disruption. Forecasts reflect assumptions around regulatory compliance cost trajectories and channel shift velocity. Practitioners should monitor REACH restriction finalization dates and palm kernel oil price volatility indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
Beard Straightener Market
Beauty & Personal Care
South America Bath and Shower Products Market
Beauty & Personal Care
Facial Wipes Market
Beauty & Personal Care
Middle East and Africa Beauty and Personal Care Products Market
Beauty & Personal Care
Personal Care Contract Manufacturing Market
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
United Kingdom Hair Care Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
Australia Beauty and Personal Care Products Market
Beauty & Personal Care
Facial Makeup Setting Spray Market
Beauty & Personal Care
At Home Hair Dye Market
Beauty & Personal Care
Sustainable Personal Care Market
Beauty & Personal Care
US Color Cosmetics Market