
 Body Balm Market | 2026-2036
Body Balm Market Size, Share, and Industry Trends Forecast 2026-2036
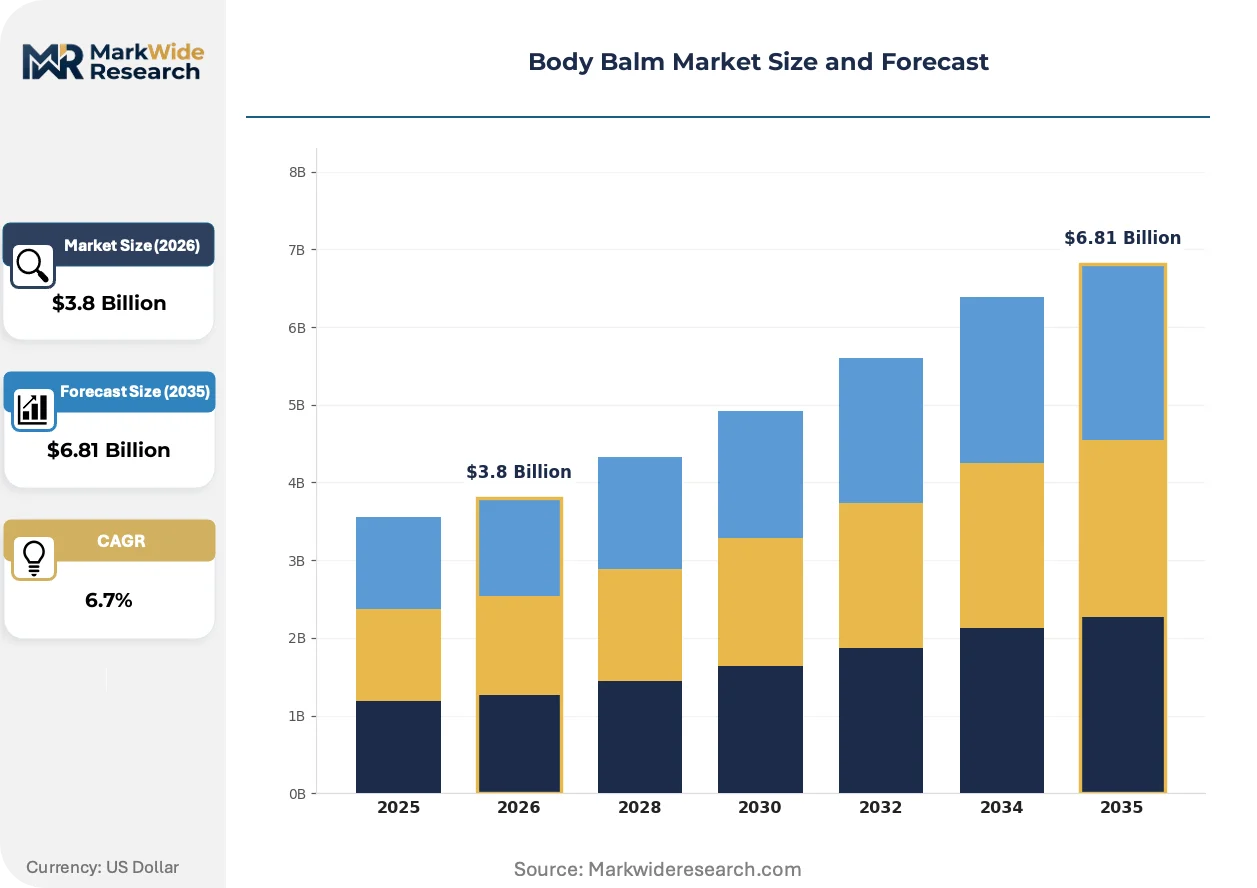
Body Balm Market Outlook
The EU Green Deal is expanding ingredient transparency requirements across cosmetic supply chains, compelling balm manufacturers to reformulate with traceable botanical bases. Kolmar Korea leverages integrated R&D facilities to accelerate clean-label prototyping for European export markets. Cosmax anchors its competitive position through dedicated natural-ingredient manufacturing lines that serve private-label wellness brands. Intercos differentiates via specialized therapeutic balm portfolios targeting dermatological channel partners.
Body balm denotes a semi-occlusive anhydrous or low-water emulsion, typically comprising 40-60% wax-to-oil ratios with petrolatum, shea butter, or plant-based esters as primary occlusives, designed to restore barrier function and reduce transepidermal water loss in compromised skin. Moisturizing balm remains the volume-leading category, though therapeutic balm commands the strongest margin pool due to clinical positioning and practitioner endorsement. Natural ingredients represent the fastest-expanding ingredient source segment, while synthetic formulations retain cost advantages in mass-market jar and tube formats across emerging retail channels.
FDA cosmetic labeling rules and ECHA REACH substance restrictions collectively shape permissible preservative systems and fragrance allergen disclosures, raising compliance costs for cross-border formulations. BIS certification requirements in India and China's GB standards for cosmetics safety further fragment regulatory pathways for multinational balm portfolios. Stakeholders must monitor evolving state-level chemical disclosure laws in the US and pending EU microplastic restrictions that could redefine exfoliating balm formulations.
Market Dynamics
Clean-label mandates from the EU Green Deal are forcing reformulation of occlusive bases across the body balm supply chain, compressing synthetic petrolatum demand while accelerating botanical ester sourcing from integrated oleochemical processors.
Growth Catalysts
- EU Green Deal chemical safety mandates:REACH substance restrictions are compelling manufacturers to replace synthetic emollients with traceable plant-derived alternatives certified under mass-balance accounting.
- Professional spa channel expansion:Therapeutic balm adoption in wellness centers is driving premium positioning and practitioner-endorsed clinical claims for barrier-restoration formulations.
- Shea butter cooperative networks:Vertically integrated sourcing from West African processing clusters is securing supply chain transparency for clean-beauty export markets.
Market Restraints
- Petrolatum feedstock volatility:Refined petroleum derivative pricing fluctuates with crude oil markets, squeezing margin stability for mass-market jar manufacturers dependent on synthetic occlusives.
- Shea butter supply concentration:Over 80 percent of global shea nut processing originates in Burkina Faso and Ghana, creating geographic concentration risk for natural-formulation brands.
- Preservative system limitations:ECHA REACH restrictions on isothiazolinones and formaldehyde-releasing agents eliminate cost-effective preservation options for water-containing balm variants.
Strategic Opportunities
- India BIS certification pathway:Early compliance with Bureau of Indian Standards cosmetic safety requirements opens access to a rapidly formalizing retail pharmacy channel.
- Upcycled fruit-seed oil convergence:Cold-pressed byproduct oils from food processing are automating cost reduction in natural emollient portfolios while supporting circular-economy marketing claims.
- Dermatological e-commerce platforms:Direct-to-practitioner digital distribution is bypassing traditional wholesale beauty supply intermediaries for clinical-grade therapeutic balms.
Industry Challenges
- Reformulation timeline compression:Accelerated EU microplastic restriction deadlines are forcing simultaneous reformulation of exfoliating balm textures and packaging compatibility testing.
- Fragrance allergen disclosure complexity:Cross-border compliance with FDA labeling rules, EU fragrance allergen lists, and China's GB standards requires redundant safety testing documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Balm Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizing Balm, Therapeutic Balm, Soothing Balm, Nourishing Balm End User: Men, Women, Children, Seniors Ingredient Source: Natural Ingredients, Organic Ingredients, Synthetic Ingredients, Herbal Extracts Packaging Type: Tubes, Jars, Tins, Pumps |
| Companies Covered | Kolmar Korea, SBLC Cosmetics, Cosmax, Made By Nature Labs, Cosmetique SA, Rysun, Skinlys, COSMECO, Intercos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Balm Market Strategic Shifts
Biotechnology-derived emollients and precision fermentation are displacing conventional crop-based botanicals, while regulatory disclosure mandates are redefining supply chain transparency as a competitive differentiator rather than compliance cost.
Precision fermentation of squalane is automating the production of molecularly identical emollients without olive-derived agricultural constraints. Clean-beauty formulators in North America and Western Europe are integrating these bioidentical lipids at commercial scale. This biotechnology is automating the decoupling of natural-claim positioning from weather-dependent crop yields.
ECHA REACH substance restrictions on persistent organic pollutants are eliminating certain petrolatum refining byproducts from cosmetic-grade specifications. Balm manufacturers serving European export markets are accelerating third-party certification of botanical wax supply chains. Professional spa and dermatological channels face the steepest compliance cost escalation due to clinical-grade purity requirements.
Subscription-based replenishment models are displacing traditional retail replenishment cycles for therapeutic balm users with chronic skin conditions. Direct-to-consumer brands are capturing recurring revenue through personalized regimen algorithms. This behavioral shift concentrates in the United States where telehealth-integrated skincare consultations normalize digital-first purchasing.
Body Balm Market Segmentation
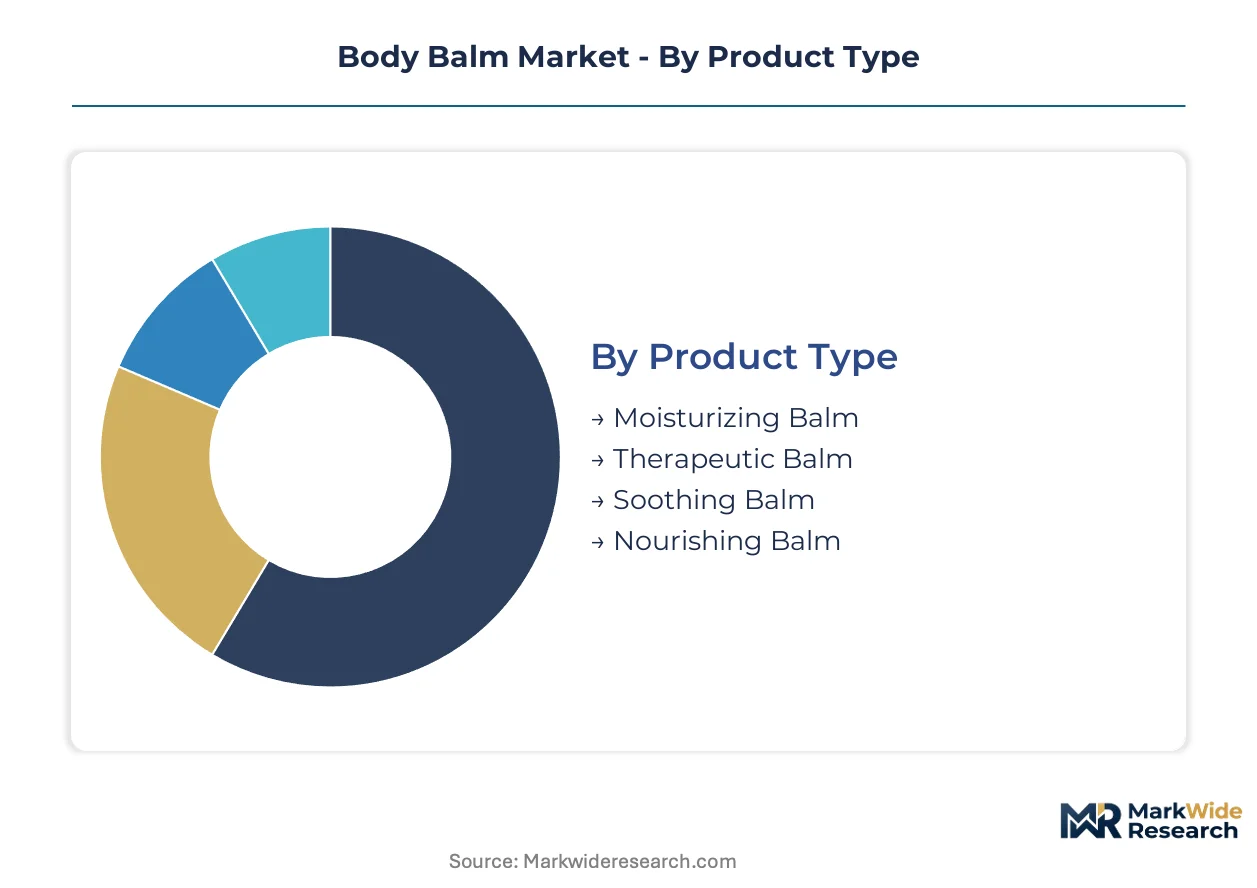
Body balm manufacturers configure production lines around wax-to-oil ratios and occlusive intensity tiers. Segmentation choices determine raw material sourcing strategies, preservative system investments, and channel access requirements across professional spa, retail pharmacy, and direct-to-consumer outlets.
Product Type:
Supply concentration in anhydrous formulation capacity favors high-margin therapeutic variants over commodity moisturizing formats.
- Moisturizing Balm:Standard semi-occlusive emulsions with 40-50% petrolatum or shea butter bases serve daily hydration regimens. Mass-market jar manufacturers in the United States deploy this format for supermarket and drugstore shelf placement, though margin compression from synthetic feedstock volatility limits reinvestment.
- Therapeutic Balm:Clinical-grade barrier-restoration formulations with elevated ceramide or colloidal oatmeal content target compromised skin conditions. Professional spa and wellness centers in Germany and France drive practitioner-endorsed adoption, supported by EU Green Deal transparency mandates for traceable botanical bases.
- Soothing Balm:Calming variants with bisabolol or allantoin address post-procedure irritation.
- Nourishing Balm:Nutrient-dense formats with vitamin complexes target aging skin concerns.
Moisturizing balm absorbs the bulk of installed capacity; therapeutic balm is expanding most quickly.
End User:
Customer lifetime value differentiates sharply across demographic segments, with chronic-condition users generating recurring replenishment revenue.
- Women:Primary purchasers across all retail channels, with concentrated demand for facial-grade body formulations and fragrance-layering compatibility. Clean-beauty direct-to-consumer brands in California and New York capture premium positioning through subscription algorithms.
- Seniors:Age-related barrier dysfunction drives clinical-grade therapeutic adoption. Dermatological e-commerce platforms serving Japan and South Korea bypass wholesale intermediaries for this cohort's regimen complexity.
- Men:Simplified positioning with matte-finish textures targets grooming-integrated routines.
- Children:Fragrance-free, hypoallergenic specifications dominate pediatric channel requirements.
Women account for the majority of current volume; seniors are gaining share fastest due to telehealth-integrated skincare consultation normalization.
Ingredient Source:
Regulatory disclosure intensity varies dramatically by source category, with synthetic formats facing REACH restriction pressure.
- Natural Ingredients:Plant-derived emollients from West African shea cooperative networks and Southeast Asian coconut processing clusters. ECHA mass-balance certification requirements raise documentation costs but unlock European export access for compliant suppliers.
- Synthetic Ingredients:Petrolatum and mineral oil bases retain cost advantages in emerging-market tube formats. Crude oil price volatility squeezes margin stability for manufacturers dependent on refined petroleum derivatives.
- Organic Ingredients:Certified botanicals command shelf-space premiums in French and German pharmacy channels.
- Herbal Extracts:Traditional medicine positioning targets Ayurvedic and TCM-integrated wellness markets.
Synthetic ingredients still dominate unit volume; natural ingredients are climbing the fastest as clean-label mandates accelerate reformulation timelines.
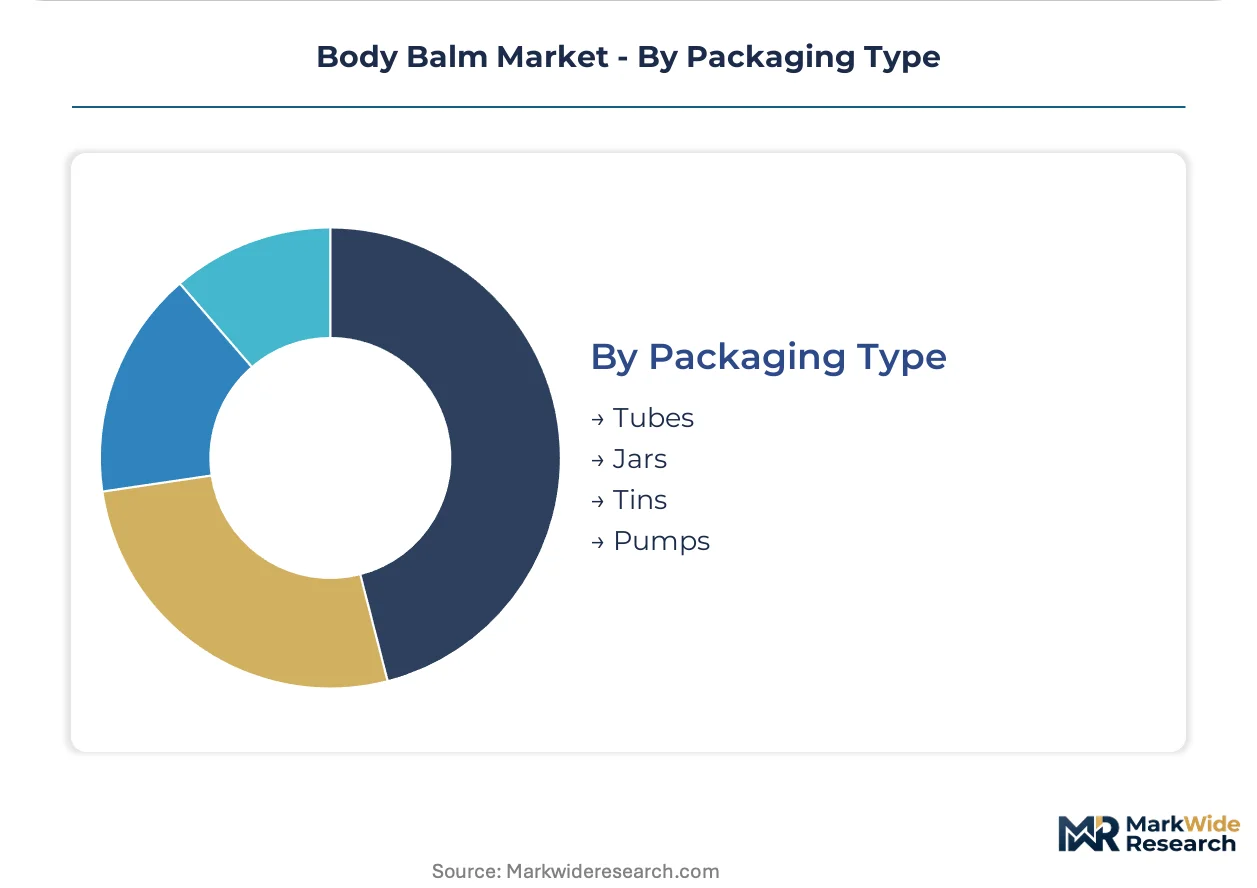
Packaging Type:
Primary packaging selection determines preservation architecture, shipping economics, and retail merchandising flexibility.
- Jars:Wide-mouth containers accommodate thick anhydrous textures and support premium visual presentation. US direct-to-consumer clean-beauty brands favor glass jar formats for shelf differentiation, though airless pump alternatives are encroaching on hygiene-sensitive positioning.
- Tubes:Collapsible aluminum and laminate structures enable precise dosing and travel-format portability. Mass-market manufacturers serving Indian and Brazilian retail pharmacy channels optimize around tube cost efficiency.
- Tins:Metal containers support zero-plastic sustainability claims for solid balm formats.
- Pumps:Airless dispensing systems protect sensitive natural formulations from oxidation.
Jars retain the largest share of premium positioning; tubes are expanding most quickly through emerging-market pharmacy formalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors clean-beauty brand headquarters for direct-to-consumer body balm distribution, while contract manufacturing clusters in Seoul and Milan serve export formulation demand.
United States
Telehealth-integrated skincare consultations normalize subscription-based therapeutic balm replenishment in California and New York. FDA cosmetic labeling rules enforce fragrance allergen disclosures for cross-border formulations. Los Angeles-based direct-to-consumer brands command premium shelf positioning through personalized regimen algorithms.
Germany
Professional spa and wellness centers in Munich and Hamburg drive practitioner-endorsed therapeutic balm adoption. ECHA REACH substance restrictions compel reformulation of synthetic emollient bases. The Baden-Württemberg processing corridor specializes in certified botanical wax supply chains for European export markets.
South Korea
Integrated R&D facilities in Seoul accelerate clean-label prototyping for global wellness brands. MFDS cosmetic safety standards align with ECHA transparency mandates for ingredient traceability. The Incheon-Free Economic Zone concentrates contract manufacturing capacity for private-label natural formulations.
India
Rapidly formalizing retail pharmacy channels in Maharashtra and Gujarat create distribution access for therapeutic balm portfolios. BIS certification requirements raise compliance barriers for imported formulations. The Mumbai-Pune industrial corridor develops domestic manufacturing capacity for Ayurvedic-integrated herbal balm variants.
France
Pharmacy channel premium positioning in Paris and Lyon supports certified organic botanical balm shelf space. ANSM enforces EU Green Deal chemical safety mandates through accelerated substance restriction timelines. The Provence-Alpes-Côte d'Azur region anchors lavender and botanical extract sourcing clusters for fragrance-integrated formulations.
Body Balm Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation certification tiers, with clinical-grade therapeutic portfolios commanding practitioner endorsement premiums. The vendor base stratifies between integrated contract manufacturers with captive R&D facilities and specialized natural-ingredient formulators serving private-label wellness brands. Three archetypes dominate: biotechnology-enabled clean-label specialists, vertically integrated oleochemical processors, and dermatological channel-focused therapeutic developers. Competitive moves concentrate on strategic partnerships with West African shea cooperative networks and capacity expansion in precision fermentation-derived emollient production.
Among Asia-Pacific-based contract manufacturers, Kolmar Korea, Cosmax, and Intercos occupy distinct positioning within the formulation services landscape. Kolmar Korea exemplifies integrated R&D-to-manufacturing capability for accelerated clean-label prototyping. Cosmax anchors the natural-ingredient manufacturing segment through dedicated production lines serving private-label wellness brands. Intercos represents the therapeutic specialization archetype with portfolio concentration targeting dermatological channel partners.
| Leading Market Players |
|---|
| Kolmar Korea |
| SBLC Cosmetics |
| Cosmax |
| Made By Nature Labs |
| Cosmetique SA |
| Rysun |
| Skinlys |
| COSMECO |
| Intercos |
| Others |
Value Chain & Pricing Dynamics
Therapeutic-to-moisturizing certification divergence separates premium practitioner-endorsed formulations from commodity jar formats, with that bifurcation driving both three-tier pricing stratification across premium, standard, and economy levels and concentrated sourcing from West African shea cooperative networks versus dispersed petroleum derivative procurement. ECHA REACH compliance costs for traceable botanical bases compound that structural separation, as clinical-grade purity requirements force premium manufacturers toward captive supply arrangements while mass-market players absorb crude oil volatility in synthetic occlusive portfolios.
Pricing Analysis
Clinical-outcome anchoring dominates therapeutic balm positioning, with barrier-restoration efficacy claims justifying subscription-based replenishment premiums for chronic-condition users in United States telehealth-integrated channels. Price differentiation rests on certification tier—EU Green Deal mass-balance botanical tracing commands shelf-space premiums in German and French pharmacy networks—while cost compression intensifies in mass-market moisturizing segments due to petrolatum feedstock volatility. Seniors with regimen complexity exhibit lowest price sensitivity; emerging-market tube buyers in India and Brazil face acute budget constraints.
Supply Chain Analysis
Domestic-content mandates in India's BIS certification pathway and China's GB standards are reshaping sourcing toward local manufacturing footprints in the Mumbai-Pune and Guangzhou-Shenzhen corridors. Raw material dependencies center on Burkina Faso and Ghana for shea nut processing, South Korea for precision fermentation-derived squalane, and regional petroleum refining clusters for synthetic occlusives. Single-source vulnerability concentrates in West African shea cooperative networks, where geographic concentration risk exceeds eighty percent of global supply. Distribution runs through direct-to-consumer digital platforms for premium therapeutic variants and formalizing retail pharmacy channels for mass-market formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races are accelerating across the body balm supply chain, with players pursuing backward control over West African shea processing clusters to secure traceable botanical supply for EU Green Deal compliance.
For Market Incumbents: Extend certification investments into ECHA mass-balance accounting and captive shea cooperative partnerships to defend margin position against biotechnology-derived emollient substitutes. Kolmar Korea and Cosmax demonstrate integrated R&D-to-manufacturing templates worth emulating. Capacity expansion in Baden-Württemberg botanical wax corridors reinforces European export access. For New Entrants and Emerging Players: Direct-to-practitioner digital distribution routes offer the most penetrable white-space for clinical-grade therapeutic balms, bypassing wholesale beauty supply intermediaries that incumbents dominate. Target subscription-based replenishment algorithms for chronic-condition seniors in United States telehealth-integrated channels. Precision fermentation partnerships with Seoul-based contract manufacturers provide rapid clean-label prototyping without captive oleochemical infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with biotechnology-enabled clean-label specialists given precision fermentation's displacement of weather-dependent crop yields across the analysis window. Acquisition targets should display integrated R&D facilities and existing EU Green Deal compliance documentation. Watch for FDA cosmetic labeling rule harmonization with state-level chemical disclosure laws as inflection signal for cross-border formulation consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Shea Cooperative Vertical Integration | Captive supply from Burkina Faso-Ghana clusters secures ECHA mass-balance certification for European export access. |
| Precision Fermentation Capacity Buildout | Seoul-based R&D facilities automate squalane production without olive-derived agricultural constraints. |
| Direct-to-Consumer Platform Launch | Los Angeles and New York brands capture recurring revenue through personalized regimen algorithms for chronic users. |
| BIS Certification Compliance Investment | Mumbai-Pune manufacturing corridors unlock India's formalizing retail pharmacy channel for therapeutic portfolios. |
| Therapeutic Balm Line Extension | Munich and Hamburg wellness center partnerships drive practitioner-endorsed clinical claims with premium positioning. |
Study Parameters
Multi-period observation of shea butter pricing volatility, EU regulatory timeline acceleration, and subscription replenishment adoption rates anchored the trend analysis, supplemented by interviews with formulation chemists at contract manufacturers, procurement leads at West African processing cooperatives, regulatory affairs specialists navigating ECHA REACH compliance, and category buyers at German pharmacy chains. Secondary validation drew from ECHA substance restriction databases, FDA cosmetic labeling guidance documents, BIS certification requirement publications, and customs trade data on oleochemical imports. Bottom-up segment sizing triangulated against top-down market envelope checks.
Segment-weighting across product type, ingredient source, end user demographic, and packaging format determined value allocation throughout the forecast period. CAGRs derived from regression analysis against historical premiumization trends and regulatory compliance cost trajectories. Forecast inputs included shea nut harvest yield variability, crude oil price band assumptions, and telehealth consultation penetration curves for chronic skin condition management.
The model holds under stable EU Green Deal implementation timelines and continued Baden-Württemberg botanical processing cluster investment; deviation in REACH substance restriction acceleration or West African supply chain disruption would shift therapeutic balm availability assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
North America Lip Care Products Market
Beauty & Personal Care
Global Organic Hair Color Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Deodorant Roll-Ons Market
Beauty & Personal Care
India Herbal Shampoo Market
Beauty & Personal Care
Electric Facial Cleansing Brush Market
Beauty & Personal Care
Lip Care Products Market
Beauty & Personal Care
Europe Hair Conditioner Market
Beauty & Personal Care
US Sustainable Personal Care Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Personal Care Contract Manufacturing Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
Skin Care Luxury Cosmetic Market
Beauty & Personal Care
Colombia Beauty and Personal Care Products Market
Beauty & Personal Care
United Kingdom Dermocosmetics Market