
 Deodorant and Antiperspirants Market | 2026-2036
Deodorant and Antiperspirants Market Size, Share, and Industry Trends Forecast 2026-2036
Deodorant and Antiperspirants Market Outlook
Mass-market retail consolidation among pharmacy chains and big-box retailers is rebalancing procurement leverage across the deodorant and antiperspirants category. Unilever PLC leverages its dual-brand architecture to sustain shelf presence across premium and value tiers in mature Western markets. Procter & Gamble anchors its position through scale manufacturing of clinical-strength antiperspirant formulations. Beiersdorf AG differentiates via dermatological credibility and specialized skin-sensitive product lines.
Deodorants and antiperspirants comprise topical personal care formulations designed to reduce body odor through antimicrobial action, moisture absorption, or pore-blocking mechanisms, typically containing aluminum salts, alcohol carriers, or plant-derived active compounds in stick, spray, roll-on, or gel delivery systems. Spray formats dominate volume in Latin American and European markets due to cultural application preferences and higher per-capita usage frequency, while stick formats command stronger margins in North American retail. The unisex end-user segment is expanding fastest as gender-neutral branding dissolves traditional aisle segmentation, though women-targeted SKUs still occupy the largest revenue share. Natural and aluminum-free formulations are capturing disproportionate growth in specialty and online channels despite commanding price premiums over conventional alternatives.
The FDA regulates antiperspirants as over-the-counter drugs in the United States, mandating specific active ingredient concentrations and labeling claims that constrain formulation innovation timelines. The EU REACH regulation and the EU Green Deal chemical sustainability frameworks are progressively restricting certain aluminum chlorohydrate compounds and synthetic fragrance components, forcing reformulation investments across multinational portfolios. India's BIS standards and CDSCO guidelines for cosmetic safety are tightening import requirements and local manufacturing compliance burdens. Stakeholders must monitor evolving regulatory divergence between jurisdictions to determine whether to standardize global formulations or fragment production regionally.
Market Dynamics
The deodorant and antiperspirants market is undergoing a structural pivot as aluminum-free formulations and microbiome-targeting technologies displace conventional pore-blocking chemistries, forcing incumbent manufacturers to rebuild their active ingredient supply chains and clinical validation pipelines.
Growth Catalysts
- EU Green Deal chemical sustainability frameworks:These regulations are accelerating reformulation investment toward plant-derived antimicrobials and biodegradable carriers, opening premium positioning for compliant portfolios.
- Urban young adult consumers:This demographic in São Paulo, Mumbai, and Los Angeles is expanding daily application frequency and adopting multi-product layering routines that expand category spend per capita.
- Enzymatic odor-neutralization biotechnology:Novel catalytic proteins that metabolize sweat compounds are enabling aluminum-free clinical efficacy claims previously unattainable without metal salts.
Market Restraints
- Aluminum chlorohydrate supply concentration:Three specialty chemical producers in Germany and the United States control pharmaceutical-grade supply, creating input vulnerability for mass-market antiperspirant lines.
- FDA OTC monograph rigidity:The fixed active ingredient concentration ceilings and permitted claim language constrain clinical-strength innovation timelines to 18-36 month approval cycles.
- Propellant cost volatility:Hydrocarbon and compressed gas propellants for aerosol formats face petrochemical feedstock price swings that compress margin on high-volume Latin American spray products.
Strategic Opportunities
- Subscription direct-to-consumer channels:Refillable stick systems and personalized scent profiling are capturing recurring revenue models that bypass retail slotting fee structures.
- India's BIS import standard harmonization:Convergence with ASEAN cosmetic safety protocols is reducing compliance fragmentation for regional manufacturing scale.
- Microbiome skin health convergence:Prebiotic formulations that preserve commensal bacteria while suppressing odor-causing strains are opening dermatology clinic and pharmacy recommendation channels.
Industry Challenges
- Clinical efficacy substantiation timelines:Sweat reduction and 24-48 hour odor protection claims require extensive human panel testing that extends new product development cycles.
- Cross-regional formula fragmentation:Diverging aluminum salt restrictions between EU REACH, US FDA, and India CDSCO guidelines are forcing SKU proliferation and manufacturing complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deodorant and Antiperspirants Market |
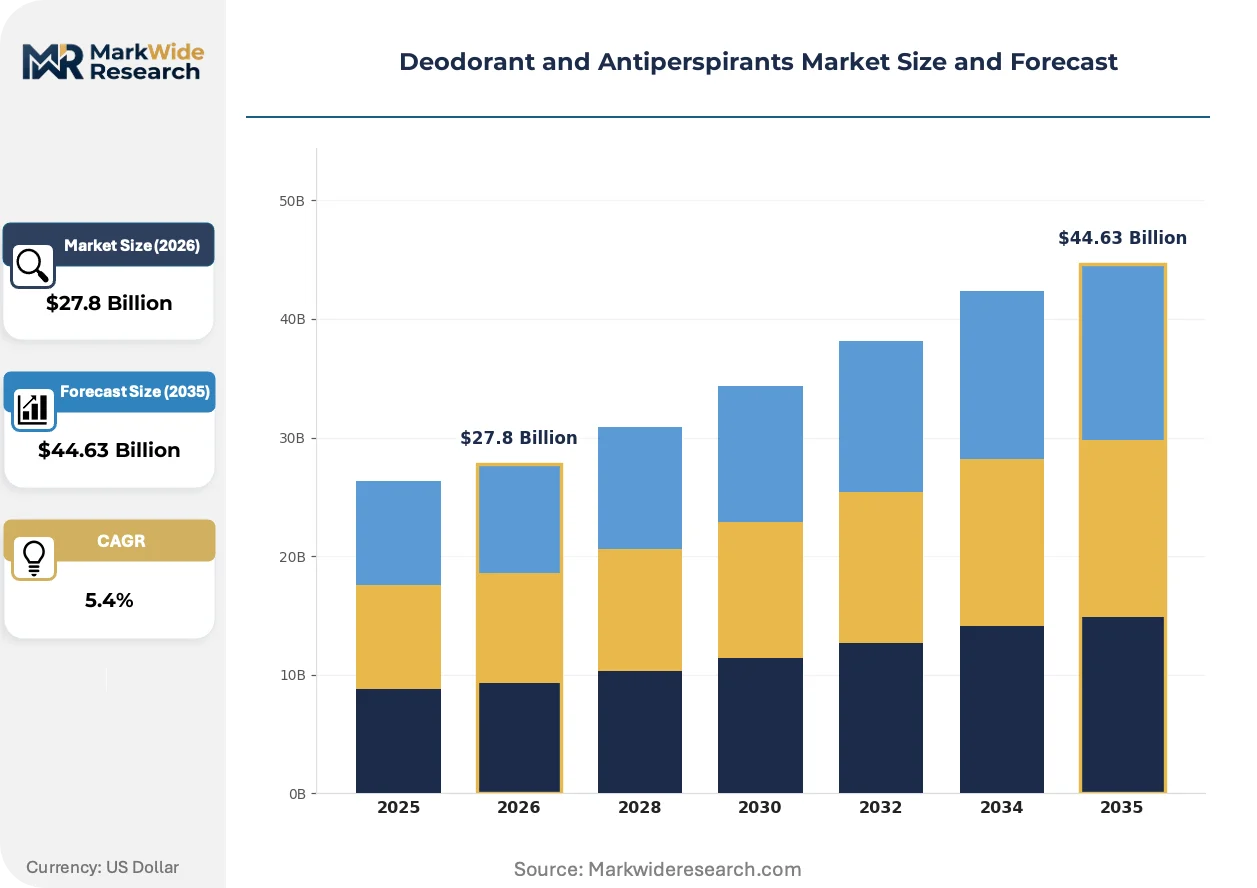
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $44.63 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
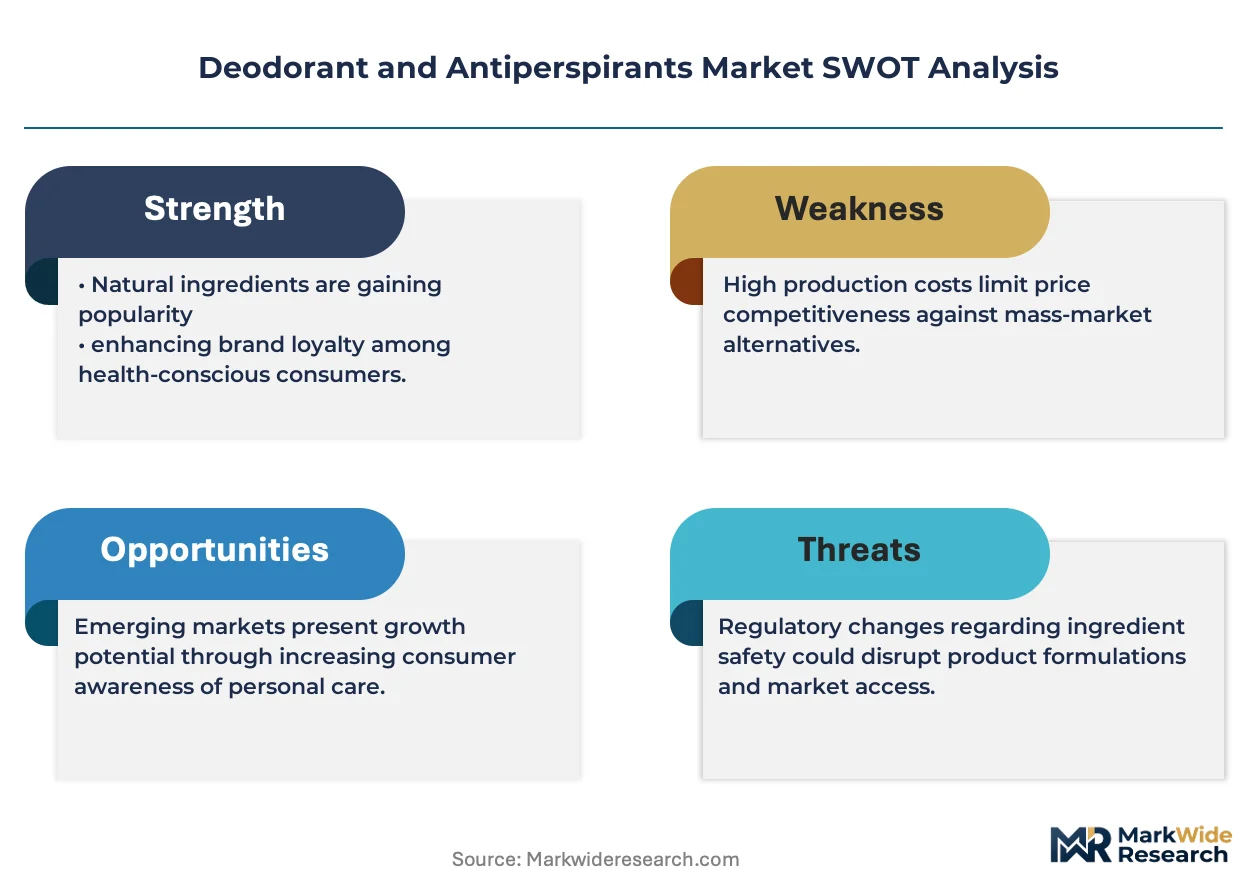
| Segmentation | Product Type: Spray, Stick, Roll-On, Gel End User: Men, Women, Teens, Unisex Formulation: Natural, Antibacterial, Aluminum-Free, Fragrance-Free Distribution Channel: Online, Supermarkets, Drugstores, Specialty Stores |
| Companies Covered | Unilever PLC, Procter & Gamble, Beiersdorf AG, L'Oréal S.A., Colgate-Palmolive Company, Henkel AG & Co. KGaA, Church & Dwight Co., Inc., Coty Inc., Reckitt Benckiser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deodorant and Antiperspirants Market Strategic Shifts
Formulation science and distribution architecture are simultaneously transforming as biotechnology-enabled actives and channel disintermediation rewrite competitive rules for incumbents and challengers alike.
Prebiotic and postbiotic skin microbiome technologies are rewriting efficacy benchmarks for aluminum-free segments. These formulations selectively nourish beneficial bacteria while inhibiting Corynebacterium species that metabolize sweat into odorous compounds. Premium skincare-cosmetic hybrid brands in France and South Korea are accelerating adoption, compressing the traditional separation between dermatological and mass-market positioning.
REACH authorization requirements for synthetic fragrance allergens are forcing systematic replacement of lilial, lyral, and certain musk compounds with natural isolates and biotechnology-derived alternatives. Fragrance houses in Grasse and Geneva are restructuring supply chains to secure compliant raw material streams. Fine fragrance and personal care divisions are consolidating purchasing to absorb reformulation cost premiums.
Young male consumers are displacing traditional gender-segmented retail aisles with unisex and male-specific premium positioning that borrows skincare ritual language. Specialty retailers in Berlin, Brooklyn, and Shibuya are reallocating floor space from legacy pharmacy formats to experiential discovery zones. This behavioral shift is compressing legacy brand loyalty and elevating challenger brand trial rates in urban core demographics.
Deodorant and Antiperspirants Market Segmentation
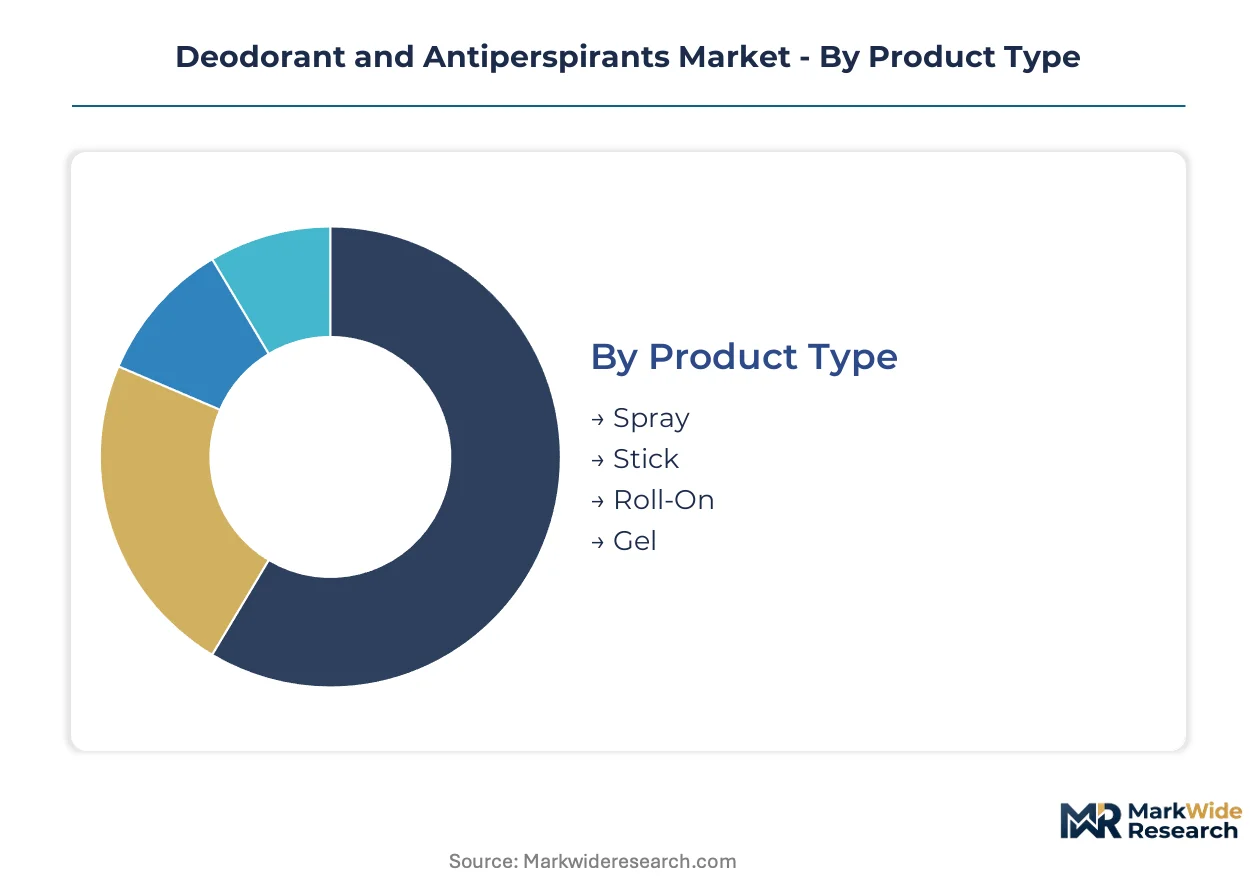
Deodorant and antiperspirant manufacturers fragment their portfolios across formulation chemistry, delivery mechanics, and channel access to capture divergent consumer willingness-to-pay and regulatory compliance requirements. Each segmentation axis carries distinct margin profiles and reformulation cost burdens that reshape competitive positioning.
Product Type:
Spray formats dominate volume throughput in Latin American and European retail, while stick configurations command premium shelf positioning in North American pharmacy chains.
- Spray:Aerosol and pump-dispensed formulations rely on hydrocarbon or compressed gas propellants to distribute aluminum chlorohydrate or fragrance compounds across large skin surface areas. Brazilian and Mexican consumers apply sprays multiple times daily, driving per-capita consumption rates that exceed stick users by significant margins. Propellant cost volatility from petrochemical feedstock swings compresses margin on these high-volume products.
- Stick:Solid anhydrous or soft-solid formulations suspend active ingredients in waxy bases that deposit through direct dermal contact, enabling precise dosage control and travel-friendly portability. United States consumers demonstrate strong preference for invisible solid variants that minimize residue on dark clothing, with clinical-strength SKUs concentrated in this format. Reformulation investments to meet FDA OTC monograph requirements concentrate stick development timelines.
- Roll-On:Liquid or gel suspensions delivered via ball applicator provide even coverage with lower propellant dependency.
- Gel:Clear-drying aqueous formulations target consumers seeking residue-free application with quick-drying properties.
Mature deployment sits with Spray. Newer deployment is concentrated in Gel.
End User:
Gender-segmented aisle configurations are dissolving as unisex branding and male-specific premium positioning capture urban young adult consumers.
- Unisex:Gender-neutral fragrance profiles and minimalist packaging architectures appeal to consumers rejecting traditional binary marketing, with strongest traction in Berlin, Brooklyn, and Shibuya specialty retail. This segment is expanding most quickly as challenger brands bypass legacy pharmacy slotting structures through direct-to-consumer subscription models.
- Women:Historically dominant revenue segment encompassing floral and fresh fragrance families with specialized formulations for sensitive skin and clothing protection. Indian and Brazilian markets sustain robust demand for women-targeted SKUs with extended hour protection claims and skincare-adjacent positioning.
- Men:Masculine-coded woody and aquatic fragrance profiles with higher alcohol content and cooling sensory cues, increasingly borrowing skincare ritual language from premium grooming categories.
- Teens:Entry-price positioning with playful fragrance variants and educational packaging addressing first-time category users.
Established volume concentrates in Women. Steepest expansion trajectory belongs to Unisex.
Formulation:
Regulatory pressure on aluminum salts and synthetic fragrance allergens is fragmenting R&D investment across compliance pathways.
- Natural:Plant-derived antimicrobial actives such as tea tree oil, sage extract, and mineral salts replace synthetic compounds, commanding significant price premiums in specialty and online channels. EU REACH authorization requirements for synthetic allergens accelerate consumer migration toward natural isolates and biotechnology-derived alternatives sourced from Grasse and Geneva fragrance houses.
- Aluminum-Free:Formulations omitting aluminum chlorohydrate and related salts rely on enzymatic odor-neutralization or prebiotic microbiome technologies to achieve clinical efficacy claims previously unattainable without metal salts. Young adult consumers in São Paulo and Los Angeles drive disproportionate growth despite higher unit economics.
- Antibacterial:Conventional formulations deploying triclosan-replacement compounds or alcohol carriers to suppress Corynebacterium species.
- Fragrance-Free:Hypoallergenic positioning for sensitive skin and dermatology clinic recommendation channels.
Conventional penetration peaks with Antibacterial. Regulatory-forced transition is accelerating Aluminum-Free.
Distribution Channel:
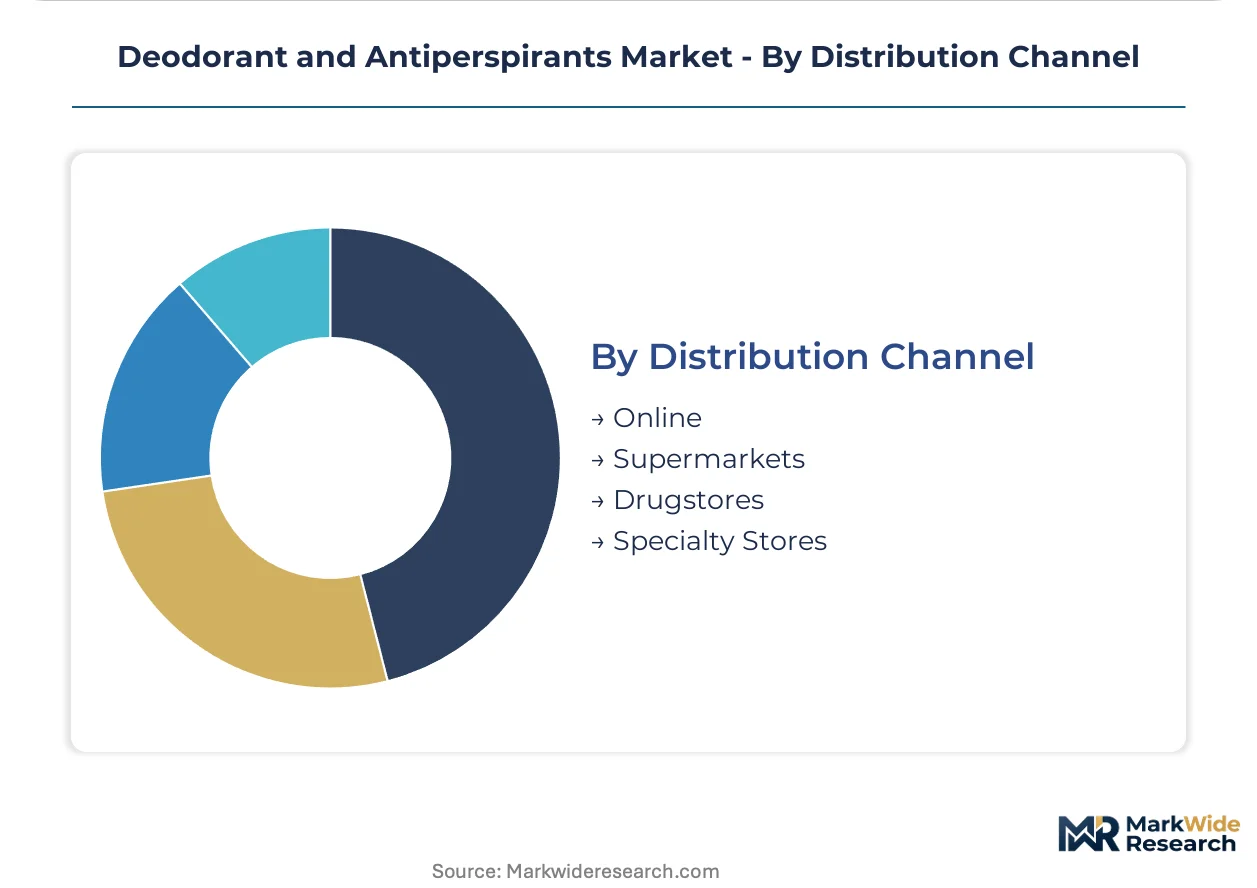
Channel economics determine margin capture, with direct-to-consumer models bypassing retail slotting fees that consume 15-25% of wholesale value in mass-market pharmacy and supermarket placements.
- Online:E-commerce platforms and brand-owned direct-to-consumer sites enable personalized scent profiling, subscription replenishment, and refillable stick systems that lock in recurring revenue. Specialty and aluminum-free brands leverage this channel to circumvent consolidated retail procurement leverage among pharmacy chains and big-box retailers.
- Supermarkets:High-frequency traffic drives impulse purchase and multi-pack volume, though shelf space allocation favors established manufacturers with trade marketing budgets.
- Drugstores:Pharmacy chains anchor clinical-strength and dermatologist-recommended positioning with trained staff consultation.
- Specialty Stores:Curated discovery environments in urban cores elevate challenger brand trial rates through experiential merchandising.
Volume concentration remains with Supermarkets. Margin expansion concentrates in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum chlorohydrate production clusters in Germany and the United States anchor raw material supply for antiperspirant formulations worldwide. These specialty chemical hubs feed manufacturing networks across four demand centers where regulatory divergence and consumer preferences reshape competitive positioning.
United States
FDA OTC monograph requirements govern antiperspirant active concentrations and labeling claims, constraining clinical-strength innovation timelines. Young adult consumers in Los Angeles and Brooklyn drive unisex and aluminum-free adoption through direct-to-consumer subscription models. Pharmacy chains and big-box retailers maintain consolidated procurement leverage over mass-market shelf placement.
Brazil
ANVISA cosmetic safety guidelines align with Mercosur harmonization efforts while preserving distinct import documentation requirements. São Paulo consumers apply spray formats multiple times daily, sustaining per-capita consumption rates that exceed global averages. Local manufacturing scales serve Latin American export demand from industrial corridors in São Paulo state.
Germany
EU REACH authorization and the EU Green Deal chemical sustainability frameworks restrict aluminum chlorohydrate compounds and synthetic fragrance allergens. Specialty chemical producers in the Rhine-Ruhr and Bavarian clusters supply pharmaceutical-grade actives to multinational formulators. Berlin specialty retail reallocates floor space toward experiential discovery zones for challenger brands.
India
BIS standards and CDSCO cosmetic safety guidelines tighten import requirements and local manufacturing compliance burdens. Mumbai young adults expand daily application frequency and adopt multi-product layering routines. Domestic production scales in Maharashtra and Gujarat to serve Southeast Asian export markets as ASEAN protocol convergence reduces regulatory fragmentation.
France
ANSM and ECHA REACH implementation target lilial, lyral, and certain musk compounds for systematic replacement with natural isolates. Fragrance houses in Grasse restructure supply chains to secure compliant raw material streams. Premium skincare-cosmetic hybrid brands accelerate microbiome technology adoption from Paris and Lyon innovation clusters.
Deodorant and Antiperspirants Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue aluminum-free and microbiome-targeting positioning through direct-to-consumer channels. The market structure concentrates procurement leverage among consolidated pharmacy chains and big-box retailers in mature Western markets while fragmenting across specialty retail and online channels in urban core demographics. Three strategic archetypes dominate: multinational CPG conglomerates with dual-brand architectures, dermatological-credibility specialists, and biotechnology-enabled challengers. Competitive moves center on reformulation investment to meet diverging regulatory requirements and subscription-based recurring revenue models that bypass traditional slotting fees.
Within the multinational conglomerate tier, Unilever PLC and Procter & Gamble exemplify scale-driven positioning across premium and value segments, while Beiersdorf AG occupies a dermatological-specialist position. These three anchors represent divergent strategic responses to aluminum-free transition pressures: dual-brand portfolio architecture, clinical-strength manufacturing scale, and skin-sensitive formulation credibility respectively.
| Leading Market Players |
|---|
| Unilever PLC |
| Procter & Gamble |
| Beiersdorf AG |
| L'Oréal S.A. |
| Colgate-Palmolive Company |
| Henkel AG & Co. KGaA |
| Church & Dwight Co., Inc. |
| Coty Inc. |
| Reckitt Benckiser |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock indices for hydrocarbon propellants cascade directly into Latin American spray product margins, compressing value-tier economics while premium aluminum-free formulations absorb cost premiums through subscription pricing architectures.
Pricing Analysis
Extended-hour protection warranties bundled with clinical-strength SKUs differentiate premium positioning from unbundled economy-tier supermarket offerings. Three-tier pricing structure across premium, standard, and economy levels segments by aluminum salt concentration and dermatological certification grade. Price differentiation stems from EU REACH compliance costs and FDA OTC monograph validation timelines. Value-tier buyers in Brazilian supermarkets exhibit highest price sensitivity, while subscription direct-to-consumer subscribers in Los Angeles and Brooklyn accept recurring premiums for microbiome-targeting formulations.
Supply Chain Analysis
Regional distribution centers in São Paulo state and Rhine-Ruhr industrial corridors anchor hub-and-spoke patterns serving Latin American and European retail networks. Pharmaceutical-grade aluminum chlorohydrate production concentrates in Germany and the United States, with enzymatic active biotechnology emerging from South Korean and French innovation clusters. Raw material dependencies span propellant gases, waxy stick bases, and fragrance isolates from Grasse. Single-source vulnerability in German specialty chemical producers creates input risk for mass-market antiperspirant lines. Distribution runs through consolidated pharmacy chains in North America and fragmented specialty retail in Berlin and Shibuya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum chlorohydrate supply concentration in three German and American producers props pricing power across clinical-strength segments, constraining value-tier margin recovery.
For Market Incumbents: Deploy dual-brand architecture to segment aluminum-free portfolios from conventional formulations without cannibalizing core revenue. Incumbents must accelerate microbiome technology licensing from French and South Korean biotech suppliers to preempt challenger brand efficacy claims. Channel control through pharmacy chain exclusivity agreements defends shelf presence against direct-to-consumer subscription erosion. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest customer acquisition cost route for unisex aluminum-free positioning in Brooklyn, Berlin, and Shibuya urban cores. New entrants should target fragrance-free dermatology clinic recommendation channels where incumbent trade marketing budgets carry limited influence. Prebiotic formulation white space in Indian and Brazilian markets offers penetrable expansion geography with converging ASEAN regulatory protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor biotechnology-enabled challengers with validated enzymatic odor-neutralization pipelines in European regulatory jurisdictions. Long-term viability across the analysis window hinges on reformulation agility under diverging FDA, REACH, and CDSCO compliance frameworks. Watch for BIS-ASEAN harmonization completion as inflection signal for Indian manufacturing scale plays.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Investment | EU REACH and FDA compliance timelines force aluminum salt replacement with enzymatic actives. |
| Direct-to-Consumer Launch | Subscription models bypass pharmacy chain slotting fees that consume wholesale value. |
| Supply Chain Regionalization | Maharashtra and Gujarat production scales serve ASEAN convergence with reduced import documentation. |
| Microbiome Technology Licensing | Prebiotic formulations open dermatology clinic recommendation channels beyond mass retail. |
| Fragrance Supply Restructuring | Grasse and Geneva houses secure REACH-compliant natural isolates replacing lilial and lyral compounds. |
Study Parameters
Independent corroboration across regulatory filing databases, customs trade records, and retail audit data underwrites the qualitative findings in this study. Primary interviews with brand managers, category buyers at pharmacy chains, supply planners, and fragrance house technical directors combined with secondary validation from FDA OTC monograph archives, ECHA REACH authorization registers, and ANVISA cosmetic safety guidelines. Bottom-up formulation chemistry trend analysis and top-down retail channel revenue triangulation anchored segmentation sizing.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects in spray, stick, roll-on, and gel formats. Segmentation dimensions modeled include product type, end-user gender positioning, formulation chemistry tier, and distribution channel access. CAGRs derived from historical trajectory analysis adjusted for regulatory intervention timelines and biotechnology adoption S-curves. Forecast inputs incorporate EU Green Deal chemical sustainability framework implementation pace and enzymatic active clinical validation completion rates.
The model holds under stable regulatory divergence between FDA, REACH, and CDSCO frameworks; deviation in aluminum salt authorization reversals or propellant feedstock shock magnitude would shift volume trajectories. Forecasts reflect documented assumptions regarding microbiome technology efficacy substantiation timelines and subscription channel penetration rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
Nail Buffers Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Hair Serums Ingredient Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Color Protection Shampoo Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
North America Bath and Shower Products Market
Beauty & Personal Care
Frizz Control Shampoo Market
Beauty & Personal Care
Online Cosmetics Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
Facial Massager Market
Beauty & Personal Care
UV Nail Gel Lamp Market
Beauty & Personal Care
Sustainable Personal Care Market
Beauty & Personal Care
Body Firming Creams Market
Beauty & Personal Care
Global Massage Oil Market