
 Electric Motor Sales Market | 2026-2036
Electric Motor Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Motor Sales Market Intelligence
The European Union's Ecodesign Directive is expanding the market for high-efficiency motors by setting stringent minimum performance standards. This regulatory pressure creates opportunities for manufacturers that can deliver compliant, energy-saving solutions. Siemens AG leverages its extensive portfolio to serve complex industrial automation needs. In parallel, Nidec Corporation specializes in compact, high-precision motors for consumer electronics and automotive components, while WEG S.A. competes on a global scale with a broad range of industrial motors.
An electric motor is an electromechanical machine that converts electrical energy into mechanical motion. Its operation relies on the interaction between the motor's magnetic field and electric current in a wire winding to generate force in the form of torque. These devices are fundamental for powering countless industrial, commercial, and residential applications. While AC motors, particularly induction types, continue to dominate the industrial machinery end-user segment, brushless DC motors are experiencing rapid adoption in automotive and robotics applications due to their high efficiency and control precision.
The regulatory landscape is primarily shaped by energy efficiency mandates. Frameworks such as the EU's Ecodesign requirements, enforced via CE marking, and standards set by the US Department of Energy define minimum efficiency performance levels. These regulations directly influence motor design, material selection, and market access for manufacturers. The key decision for stakeholders centers on balancing investment in next-generation permanent magnet and brushless technologies against the established infrastructure for traditional AC induction motors.
Market Dynamics
The global regulatory push for decarbonization, codified in frameworks like the EU's Ecodesign Directive, is the central force shaping the market. This pressure mandates higher energy efficiency, compelling a technological shift away from legacy induction motors toward advanced designs across all end-user segments.
Growth Catalysts
- Automotive Electrification:The shift to electric vehicles creates high-volume demand for advanced brushless DC and permanent magnet motors in vehicle powertrains.
- Regulatory Mandates:The EU's Ecodesign Directive and US Department of Energy standards accelerate the replacement of legacy industrial motors by enforcing minimum efficiency levels.
- Industrial Modernization in China:China's manufacturing sector is upgrading to high-efficiency motors for robotics and automation to meet national energy targets.
Market Restraints
- Input Cost Volatility:Price fluctuations for rare-earth elements like neodymium, essential for permanent magnet motors, create significant cost uncertainty for manufacturers.
- Supply Chain Concentration:The concentration of rare-earth mineral processing in China introduces geopolitical and logistical risks for motor producers globally.
- Legacy System Inertia:The large installed base of AC induction motors and a workforce trained on them slows the transition to newer motor technologies.
Strategic Opportunities
- Service-Based Models:Offering motor performance monitoring and energy management as a service provides recurring revenue streams beyond one-time hardware sales.
- Robotics and Automation:Growth in warehouse automation and collaborative robots creates a market for compact, high-precision servo and brushless DC motors.
- Emerging Market Upgrades:Industrializing economies in Southeast Asia and Latin America present opportunities as they replace aging infrastructure and build new manufacturing capacity.
Industry Challenges
- Talent Scarcity:A shortage of engineers and technicians with expertise in modern power electronics, embedded software, and advanced motor control systems hinders product development and support.
- System Integration Complexity:Integrating new high-efficiency motors and their associated variable frequency drives with legacy factory automation systems is a significant technical hurdle for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Motor Sales Market |
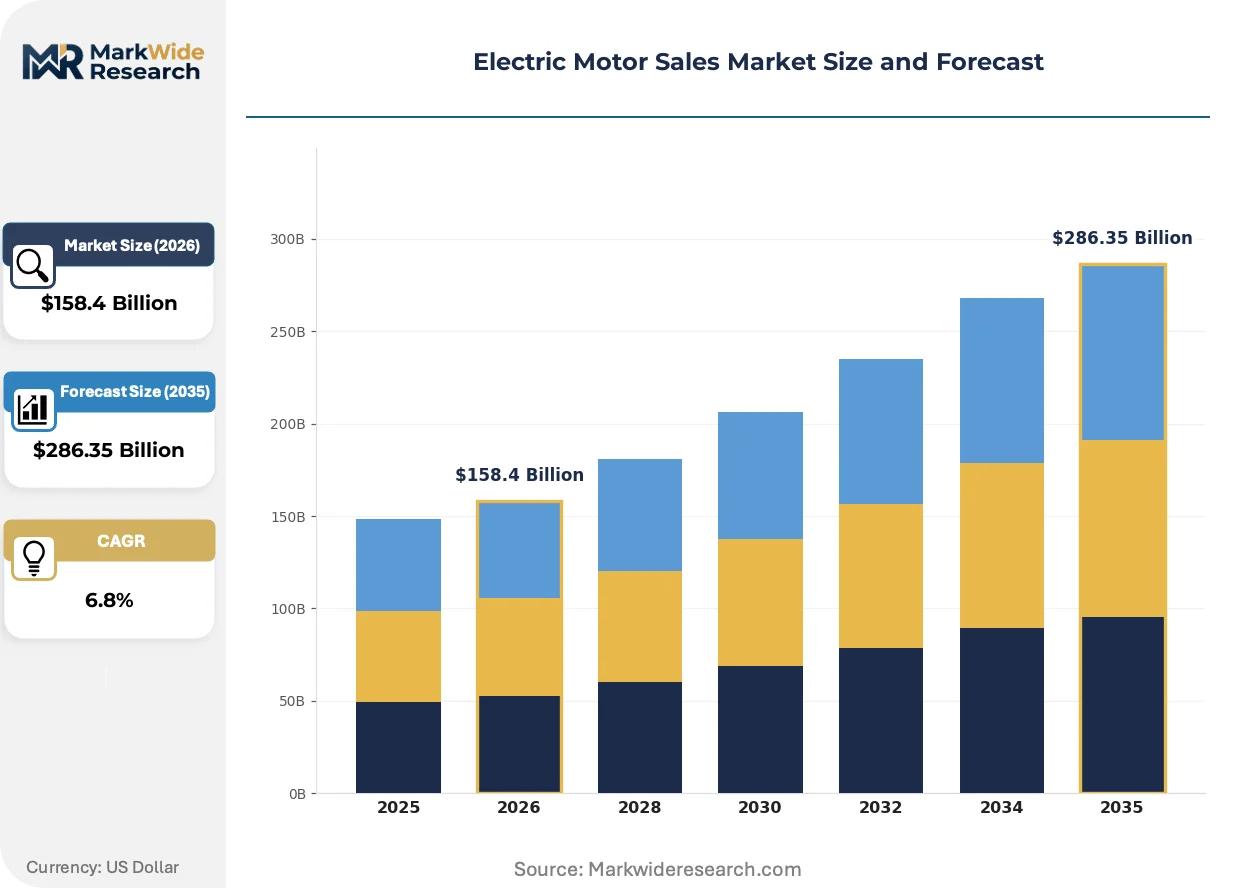
| Market Size in 2026 | $158.4 Billion |
| Market Size in 2035 | $286.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Stepper Motors, Servo Motors End User: Industrial Machinery, Automotive OEMs, HVAC Systems, Home Appliances Technology: Brushless, Induction, Synchronous, Permanent Magnet Application: Robotics, Transportation, Energy Generation, Consumer Electronics |
| Companies Covered | Denso Corporation, WEG S.A., Nidec Corporation, Toshiba Corporation, Mitsubishi Electric Corporation, Siemens AG, General Electric Company, Yaskawa Electric Corporation, ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Motor Sales Market Strategic Shifts & Innovations
The convergence of material science, digital controls, and stringent efficiency mandates is fundamentally altering electric motor design. This evolution is pushing development beyond simple energy savings toward integrated, intelligent motion systems that are self-monitoring and network-aware.
Wide-bandgap semiconductors like Silicon Carbide (SiC) are enabling more efficient and compact motor drives. Automotive and high-performance industrial sectors are rapidly adopting these advanced power electronics. This technological shift is absorbing functions previously handled by separate mechanical components into the drive itself, creating more intelligent and integrated motor systems.
China's Ministry of Industry and Information Technology (MIIT) enforces stringent GB standards for motor energy efficiency, compelling design changes for market access. This mandate forces both domestic and foreign manufacturers to phase out less efficient products. The industrial machinery sector is most affected, accelerating the transition to IE3 and higher efficiency class motors across the country.
End-users in heavy industries are increasingly evaluating motors based on total cost of ownership rather than initial purchase price. This change elevates the role of system integrators and energy service companies (ESCOs) that guarantee long-term performance and savings. This procurement behavior is most visible in Europe, driven by high energy costs and policies like the Energy Efficiency Directive.
Electric Motor Sales Market Segmentation
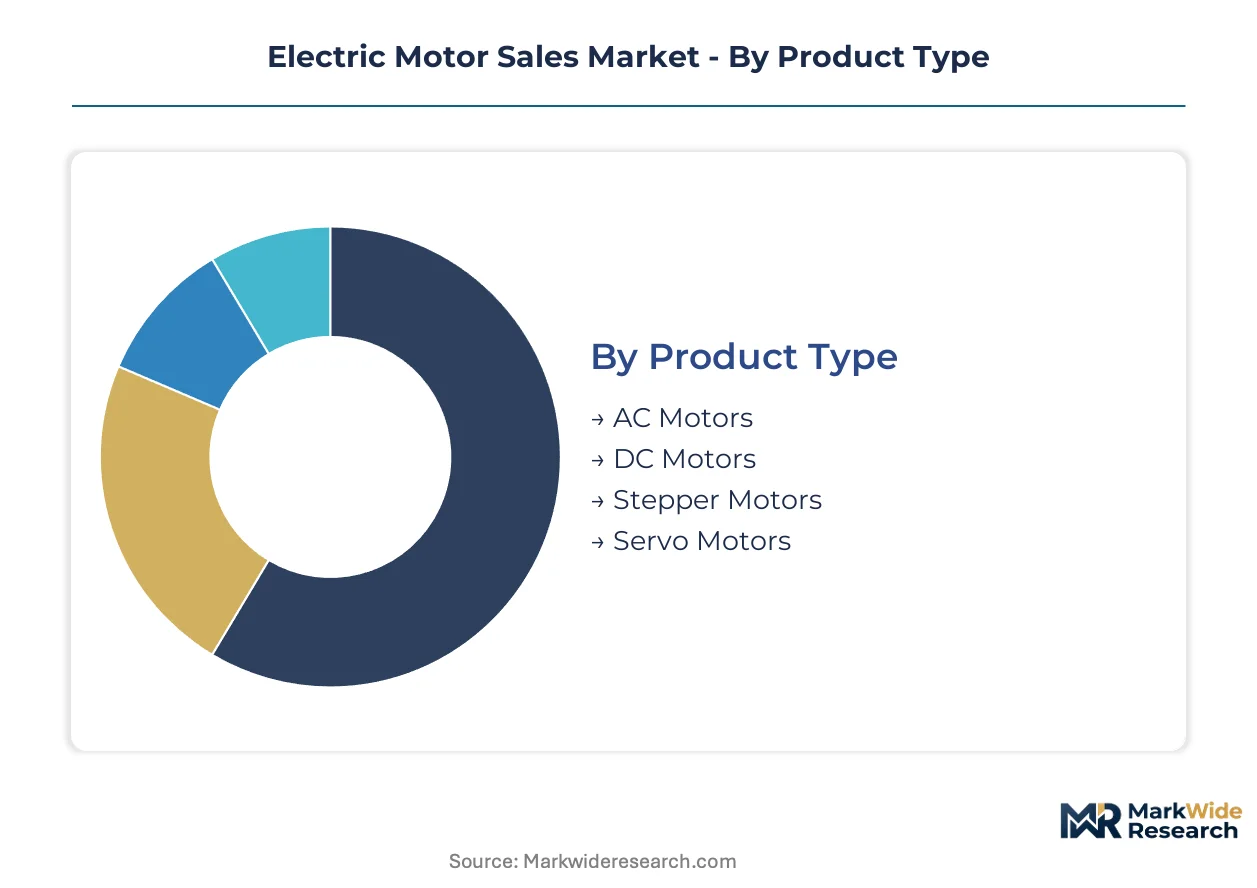
Segmenting the electric motor sales market reveals distinct technological preferences and demand drivers across various industries. This analysis highlights how regulatory pressures, application-specific needs, and material science advancements influence market dynamics and product adoption rates.
Product Type:
The integration depth of electric motors varies, from standalone units to highly embedded components within larger systems.
- AC Motors:These motors operate on alternating current, typically induction or synchronous types, known for their robustness. Industrial machinery in China extensively utilizes AC induction motors for their reliability and cost-effectiveness in manufacturing processes.
- DC Motors:Converting direct current into mechanical energy, DC motors often provide variable speed capabilities. Automotive OEMs in Germany integrate DC motors for precise control in various auxiliary systems, aligning with stringent performance requirements.
- Stepper Motors:These devices utilize pulsed DC current for precise angular positioning, commonly found in applications requiring accurate indexing.
- Servo Motors:High-performance motors with closed-loop feedback systems enable precise motion control, essential for advanced automation and robotics.
Volume placements concentrate in AC Motors; the faster expansion belongs to Servo Motors.
End User:
The end-user segments reflect distinct operational environments and performance requirements, influencing motor design and efficiency standards.
- Automotive OEMs:These manufacturers integrate motors into electric vehicle powertrains and numerous auxiliary systems. The EU Green Deal mandates higher efficiency, driving demand for advanced motors in European automotive production.
- Industrial Machinery:This segment powers manufacturing equipment, pumps, and compressors across diverse industries. China's industrial modernization initiatives are accelerating the replacement of legacy industrial motors with high-efficiency models to meet national energy targets.
- HVAC Systems:Motors are employed in fans, blowers, and compressors within climate control units for commercial and residential buildings.
- Home Appliances:This segment incorporates compact motors for various functions in washing machines, refrigerators, and vacuum cleaners, prioritizing energy efficiency.
Industrial Machinery holds the largest installed base, while Automotive OEMs are experiencing the steepest expansion trajectory.
Technology:
Technology segmentation highlights the varying maturity levels and performance characteristics available across the market.
- Brushless:Featuring electronic commutation, these motors offer high efficiency and a long lifespan without physical brushes. Robotics applications in Japan favor brushless motors for their precision and compact size in automated systems.
- Permanent Magnet:These motors utilize permanent magnets in the rotor, resulting in high power density and efficiency. Electric vehicle powertrains globally are adopting permanent magnet motors for their superior energy conversion and compact design.
- Induction:Relying on electromagnetic induction to produce torque, induction motors are widely used in industrial settings due to their simplicity and durability.
- Synchronous:Operating at a constant speed synchronized with the supply frequency, synchronous motors are suitable for fixed-speed applications requiring precise timing.
Induction technology maintains a significant market share, yet Permanent Magnet motors are gaining share fastest.
Application:
Application segments underscore the strategic importance of electric motors in driving innovation and efficiency across critical sectors.
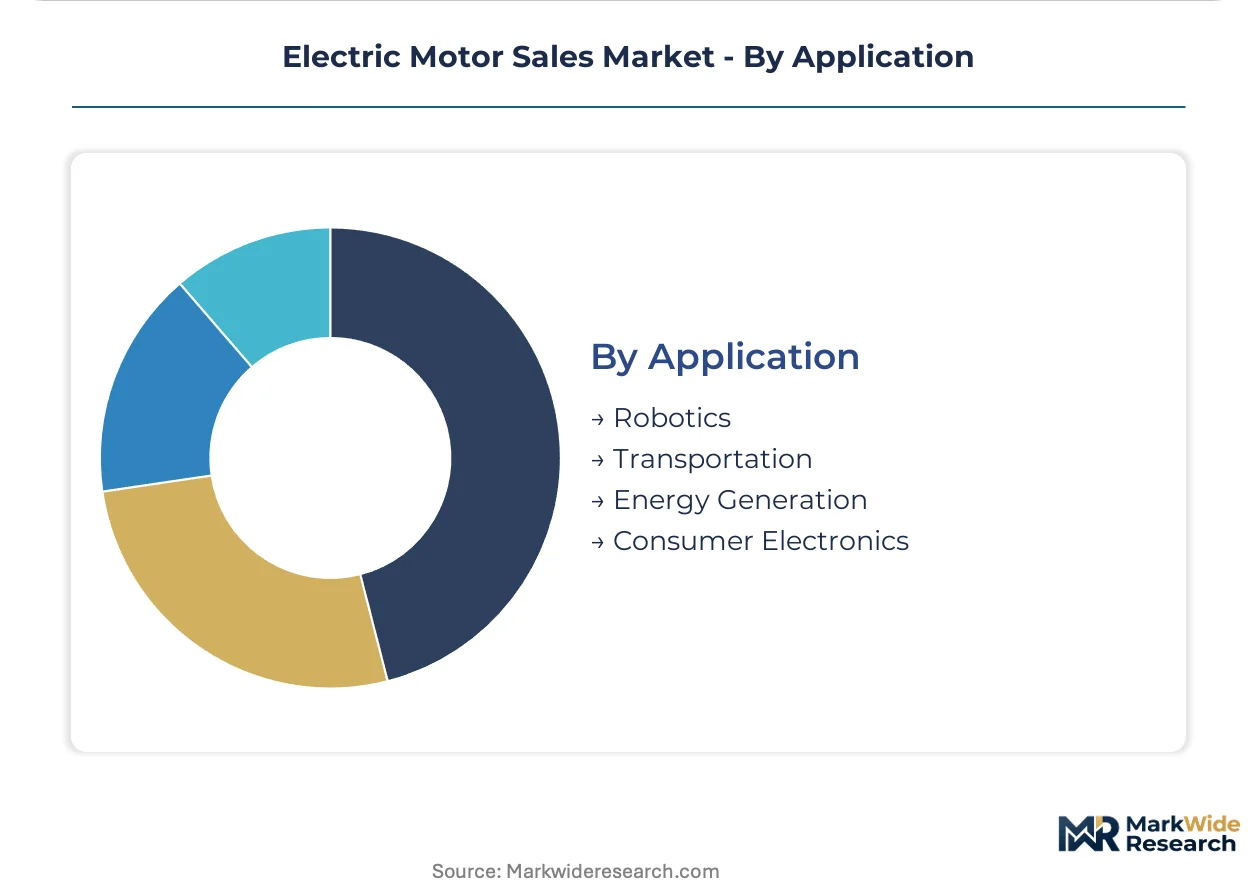
- Transportation:This segment encompasses motors for electric vehicles, rail systems, and aerospace applications. Government policies in the US promoting EV adoption are fueling demand for high-performance motors in the transportation sector.
- Robotics:Precise motors are utilized for articulation, movement, and manipulation in automated systems. Warehouse automation initiatives in North America require compact, high-precision servo and brushless DC motors for efficient operation.
- Energy Generation:This includes motors used in wind turbines, hydro-generators, and other power production systems, contributing to renewable energy efforts.
- Consumer Electronics:Small motors are integrated for various functions within smartphones, cameras, and personal gadgets, emphasizing miniaturization and low power consumption.
Transportation applications represent the fastest-growing segment by volume, with Robotics expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's numerous industrial zones, particularly those focused on advanced manufacturing, are central to global electric motor demand. These regions benefit from national policies like the "Made in China 2025" initiative, which prioritizes high-efficiency industrial equipment. This strategic focus attracts significant investment in motor production and technology upgrades.
China
China's industrial modernization drives demand for high-efficiency motors in robotics and automation. The Ministry of Industry and Information Technology (MIIT) enforces stringent GB standards for motor energy efficiency, compelling design changes. The Yangtze River Delta region, a hub for EV manufacturing and industrial automation, shows high concentration of motor production and adoption.
Germany
Germany's automotive OEMs and industrial machinery sectors are core demand drivers for advanced electric motors. The EU's Ecodesign Directive, enforced via CE marking, mandates higher efficiency standards for motors. The Baden-Württemberg region, with its strong automotive and industrial automation clusters, leads in the adoption of high-performance motors.
The United States
The United States sees robust demand driven by electric vehicle adoption and industrial upgrades across manufacturing. The US Department of Energy sets minimum efficiency performance levels for various motor types, influencing design and market access. Michigan, a traditional automotive manufacturing stronghold, is undergoing significant retooling for EV powertrain production.
Japan
Japanese robotics and industrial automation sectors are significant consumers of compact, high-precision motors. The Ministry of Economy, Trade and Industry (METI) promotes energy efficiency targets, encouraging the adoption of advanced motor technologies. The Kanto region, encompassing Tokyo, remains a key cluster for electronics and precision manufacturing, including motor components.
India
India's ongoing infrastructure development and industrialization initiatives fuel demand for industrial motors. The Bureau of Indian Standards (BIS) defines motor efficiency standards, promoting the use of energy-efficient models. Maharashtra and Gujarat, with their burgeoning industrial machinery and automotive component manufacturing bases, are key growth areas.
Electric Motor Sales Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, shaping a competitive landscape that spans from broad industrial solutions to niche high-precision applications. Global industrial giants leverage extensive portfolios to serve diverse end-user segments, while specialized motor manufacturers focus on compact designs or advanced technologies. Strategic archetypes include integrated automation providers, dedicated motor component suppliers, and regional market leaders. Many firms engage in portfolio diversification and strategic partnerships to expand their technological reach.
Among the established industrial powerhouses, Siemens AG exemplifies a diversified conglomerate offering comprehensive automation and drive solutions across numerous industrial sectors globally. Nidec Corporation, a Japanese entity, represents a specialized motor manufacturer known for its compact and high-precision motors, particularly for automotive and consumer electronics applications. This firm consistently innovates within its core areas. WEG S.A., a Brazilian corporation, occupies a position as a global industrial motor supplier, competing with a broad range of products for various industrial machinery segments, often emphasizing energy efficiency.
| Leading Market Players |
|---|
| Denso Corporation |
| WEG S.A. |
| Nidec Corporation |
| Toshiba Corporation |
| Mitsubishi Electric Corporation |
| Siemens AG |
| General Electric Company |
| Yaskawa Electric Corporation |
| ABB Ltd |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and large conglomerates influence electric motor supply behavior and pricing discipline across the market. This dynamic creates varying pricing structures depending on product complexity and regional manufacturing capabilities.
Pricing Analysis
Premium pricing often applies for short lead times on specialized motors, while standard products are more susceptible to spot market fluctuations. Per-unit transactional pricing dominates for high-volume industrial motors, whereas project-based contracts are common for complex automation systems. Price differentiation stems from the motor's efficiency class, such as IE3 or IE4, and the inclusion of advanced control features. Pricing softness reflects intense competition for standard AC induction motors, especially in markets like China. Automotive OEMs, prioritizing performance and integration, demonstrate lower price sensitivity compared to industrial machinery end-users focused on initial acquisition cost.
Supply Chain Analysis
Logistics and freight costs significantly influence the delivered price of electric motors, especially for heavy industrial units shipped globally. Geographic supply concentration for critical raw materials like rare earth elements centers heavily in China, creating single-source vulnerability for permanent magnet motors. Copper and specialized steel also represent key material dependencies for all motor types. Geopolitical risks associated with rare earth processing introduce significant supply chain risk for motor producers. Distribution runs through a mix of direct sales channels to large OEMs and a network of industrial distributors serving smaller end-users and system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric motor market is a supply-constrained story, with processing capacity bottlenecks for critical rare earth elements propping up pricing for advanced motor types.
For Market Incumbents: Extend existing intellectual property into next-generation motor designs, particularly focusing on SiC power electronics integration. Develop strategic partnerships for secure, diversified sourcing of rare earth elements to mitigate geopolitical risks. This approach counters the threat of input cost volatility and maintains a competitive edge against emerging specialized firms. Investment in advanced manufacturing automation improves production efficiency and reduces labor costs.
For New Entrants and Emerging Players: A price-point gap exists between highly customized, premium servo motors and mass-produced, lower-efficiency industrial units. Target niche applications in robotics and compact automation, where precision and integration capabilities command higher value. Focus on developing service-based models, such as motor performance monitoring, to offer value beyond hardware. The most penetrable segment remains small to medium-sized industrial modernization projects in rapidly industrializing economies.
For Investors and Strategic Acquirers: Distressed-cycle entries favor agile technology specialists in advanced motor control and power electronics across Europe and Japan. The long-term viability of the electric motor market is robust, driven by global decarbonization mandates and electrification trends. Seek acquisition targets with strong R&D in rare-earth-free magnet technologies or advanced thermal management solutions. The signal to watch is the commercialization of cost-effective, high-performance alternatives to traditional permanent magnets.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Efficiency Motors | This initiative addresses the growing demand for IE4 and IE5 class motors mandated by global energy regulations. |
| Strategic Sourcing of Critical Materials | Securing access to rare earth elements and copper mitigates supply chain risks for permanent magnet motor production. |
| Investment in SiC Power Electronics R&D | Developing advanced SiC-based motor drives enables higher efficiency and more compact system designs for automotive OEMs. |
| Expansion of Service-Based Offerings | Offering motor performance monitoring and predictive maintenance creates recurring revenue streams and enhances customer loyalty. |
| Partnerships for Robotics Integration | Collaborating with robotics manufacturers ensures motors are optimized for compact, high-precision automated systems. |
Research Approach
Industry reports from the International Energy Agency, EU Ecodesign directives, and US Department of Energy publications formed the secondary backbone of this analysis. This foundational research was complemented by primary interviews with automotive OEM engineers, industrial plant managers, motor R&D specialists, and energy efficiency consultants. The study utilized both bottom-up and top-down triangulation to ensure data accuracy and comprehensive market coverage.
Historical trendline analysis informed the development of the market forecast across the analysis window. The analytical framework modeled key segmentation dimensions including product type, end-user, technology, application, and regional regulatory clusters. Compound annual growth rates were derived from a synthesis of historical market performance and projected impacts of electrification and industrial automation. Electric vehicle production forecasts and industrial capital expenditure plans served as crucial industry-specific forecast inputs.
Inputs from company annual filings and government energy reports were available through the study window; gaps in emerging technology adoption rates introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory enforcement and raw material price stability. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global in-Wheel Motors Market
Electric Motor
Global Automotive Onboard Charger Market
Electric Motor
Australia Solar E-Bike Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
APAC Electric Drives Market
Electric Motor
Traction Motors Market
Electric Motor
Electric Drives Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Electric Traction Motor Market
Electric Motor
Automotive Wiper Motor Market
Electric Motor
Global Hub Motors Market
Electric Motor
Global Two Wheeler Hub Motor Market
Electric Motor
Motorcycle Lead Acid Battery Market
Electric Motor
Torque Motor Market
Electric Motor
Motors for Robot Body and Robot Wheels Market
Electric Motor
Europe Electric Motors for Electric Vehicle Market