
 GCC Electric Motor Market | 2026-2036
GCC Electric Motor Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Electric Motor Market Intelligence
IE4 premium efficiency classification is collapsing the gap between cost-optimized induction motors and permanent magnet alternatives across Gulf industrial estates. ABB leverages its Jeddah service hub to anchor aftermarket revenue from Saudi Aramco's rotating equipment fleet. Siemens competes through localized wound-rotor motor production serving UAE steel re-rolling mills. WEG Industries sustains Brazilian cost engineering adapted to Middle Eastern ambient temperature derating requirements.
An electric motor converts electrical energy into mechanical rotation through electromagnetic induction between stator windings and a rotor assembly, with continuous duty ratings from fractional horsepower to multi-megawatt outputs driving pumps, compressors, and material handling systems across process industries. AC Motor architectures dominate installed bases across GCC desalination and oilfield water injection plants due to mature variable frequency drive pairing and minimal commutator maintenance burden. Brushless technology segments are capturing specification upgrades in robotics and precision conveyor applications where reduced electromagnetic interference and extended bearing life justify capital premiums over conventional asynchronous alternatives.
SASO's mandatory minimum energy performance standards for low-voltage motors, UAE's ECAS conformity assessment scheme, and Kuwait's MEW technical regulations collectively restrict market access for non-compliant import stock while channeling procurement toward certified OEM channels. These frameworks reshape competitive dynamics by embedding efficiency testing documentation into bid compliance requirements for EPC contractors serving national oil companies. Stakeholders must monitor how Saudi giga-project local content rules redirect motor sourcing from direct import to in-Kingdom assembly partnerships.
Market Dynamics
IE4 premium efficiency mandates are compressing replacement cycles across Saudi petrochemical corridors, forcing operators to retire serviceable IE2-class induction motors ahead of mechanical failure. This regulatory compression is restructuring supplier relationships around certified channels.
Growth Catalysts
- SASO energy efficiency mandates:Saudi Arabia's compulsory minimum performance standards for low-voltage motors are accelerating retrofit demand across Aramco's rotating equipment fleet. EPC contractors now embed efficiency testing documentation into bid compliance requirements.
- Kuwait wastewater infrastructure expansion:The country's sanitary engineering authority is procuring medium-voltage motor systems for tertiary treatment plants at Al-Sulaibiya and Al-Jahra. These installations specify IP55 enclosures rated for saline ambient conditions.
- Permanent magnet synchronous motor adoption:Brushless architectures are displacing wound-rotor designs in precision conveyor and robotics applications across UAE industrial free zones. Reduced electromagnetic interference and extended bearing life justify capital premiums.
Market Restraints
- Copper and rare-earth magnet cost volatility:NdFeB magnet prices fluctuate with Chinese export quotas, compressing margins on premium efficiency motor lines. Manufacturers hedge through six-month forward contracts with limited effectiveness.
- Technical limitation in high-temperature derating:Standard insulation class F windings degrade prematurely in Gulf ambient conditions above 50°C, forcing oversizing that erodes efficiency gains. Ambient-compensated thermal modeling remains underdeveloped.
- Regulatory friction from non-harmonized standards:UAE's ECAS conformity assessment scheme diverges from Saudi SASO testing protocols, duplicating certification costs for suppliers serving both markets. Technical documentation must be recompiled for each jurisdiction.
Strategic Opportunities
- Oman underpenetrated industrial base:The Sultanate's downstream petrochemical investments at Duqm and Sohar lack established motor service infrastructure. First-mover aftermarket hubs can anchor long-term maintenance contracts.
- Regulatory tailwind from UAE net-zero pathway:Dubai's Supreme Council of Energy is mandating IE3-class minimums for new municipal water pumping stations. Federal procurement guidelines extend this to federal infrastructure projects.
- Technology convergence of VFD-motor integration:Packaged drive-motor systems with embedded condition monitoring are displacing separately sourced components. Integrated thermal protection and vibration sensing reduce commissioning complexity.
Industry Challenges
- High-voltage motor rewind skill scarcity:Vacuum pressure impregnation expertise for form-wound stators concentrates with aging technicians in Jeddah and Dubai. Knowledge transfer programs at technical institutes lag replacement demand.
- IE4 certification timeline compression:SASO-accredited laboratories face testing backlogs exceeding fourteen weeks for new motor platforms. Product launch schedules slip into subsequent budget cycles.
- Legacy motor inventory stranding:National oil companies hold substantial spare IE2-class rotors and stators purchased under multi-year framework agreements. Accounting write-downs complicate fleet standardization initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Electric Motor Market |
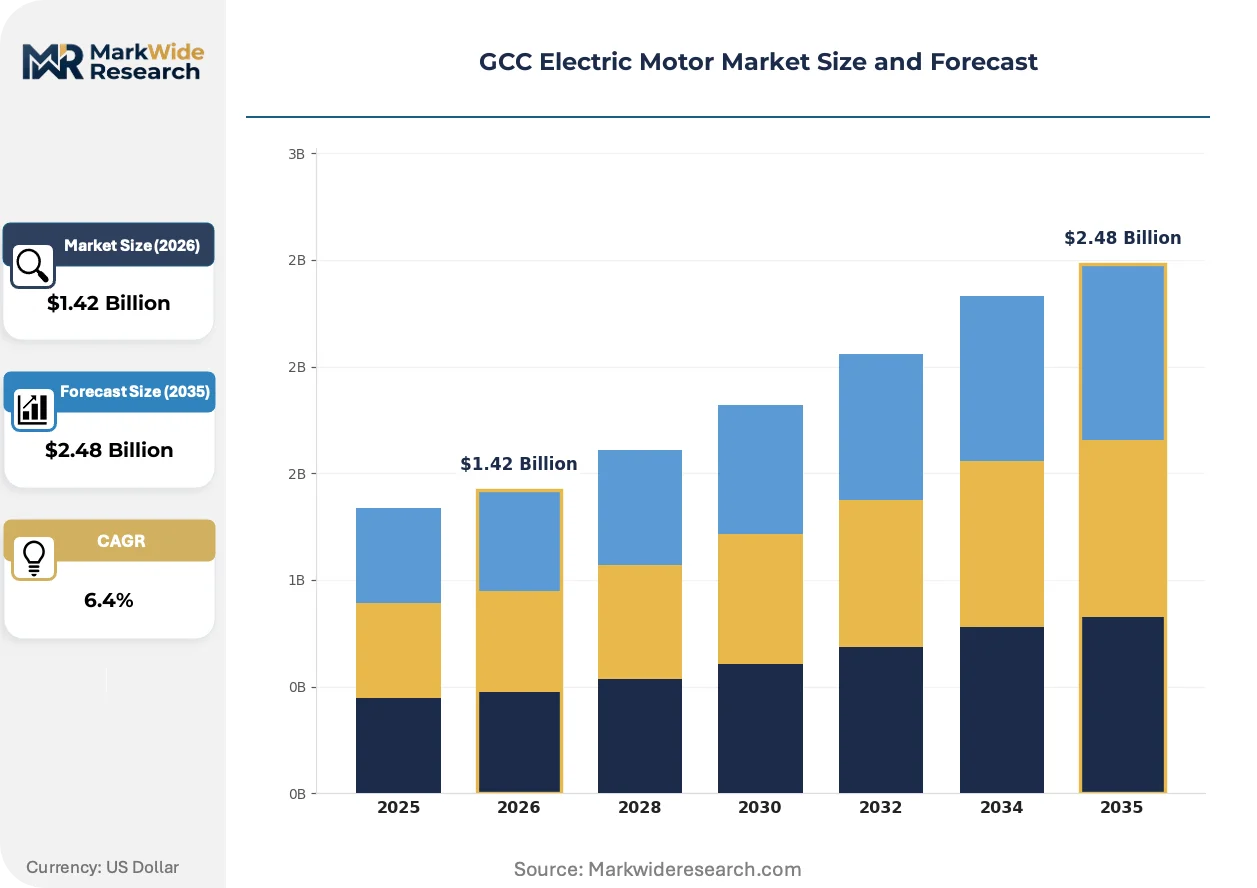
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motor, DC Motor, Servo Motor, Stepper Motor End User: Industrial Automation, HVAC, Transportation, Renewable Energy Application: Conveyor Systems, Pumps, Fans, Robotics Technology: Brushless, Synchronous, Asynchronous, Induction |
| Companies Covered | ABB, Siemens, WEG Industries, NIDEC Corporation, TECO Middle East Electrical and Machinery Co. Ltd, Schneider Electric SE, Regal Beloit Corporation, Johnson Electric Holdings Ltd., Hyundai Electric & Energy Systems Co., Ltd., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Electric Motor Market Strategic Shifts & Innovations
Electromagnetic design software and additive manufacturing are collapsing prototyping cycles for specialized motor geometries. Manufacturers now validate thermal performance through digital twin simulation before cutting physical tooling.
Switched reluctance motor topology is decomposing the traditional induction motor dominance in pump and fan applications. Saudi Aramco's engineering standards division is evaluating SR drives for variable-torque loads in gas compression stations. The technology eliminates rotor losses entirely, enabling efficiency levels approaching permanent magnet designs without rare-earth supply exposure.
UAE's ECAS conformity assessment scheme is tightening market access for non-compliant import stock. Technical regulations now require third-party testing documentation traceable to ISO/IEC 17025-accredited laboratories. European and Asian OEMs are establishing in-country assembly partnerships to satisfy local content verification requirements.
Buyers are unbundling aftermarket service contracts from initial equipment procurement. Kuwait's Ministry of Electricity and Water now separates motor supply from five-year maintenance agreements, enabling specialist service providers to compete against manufacturer-captive channels. This disintermediation is most visible in medium-voltage motor installations above 1kV.
GCC Electric Motor Market Segmentation
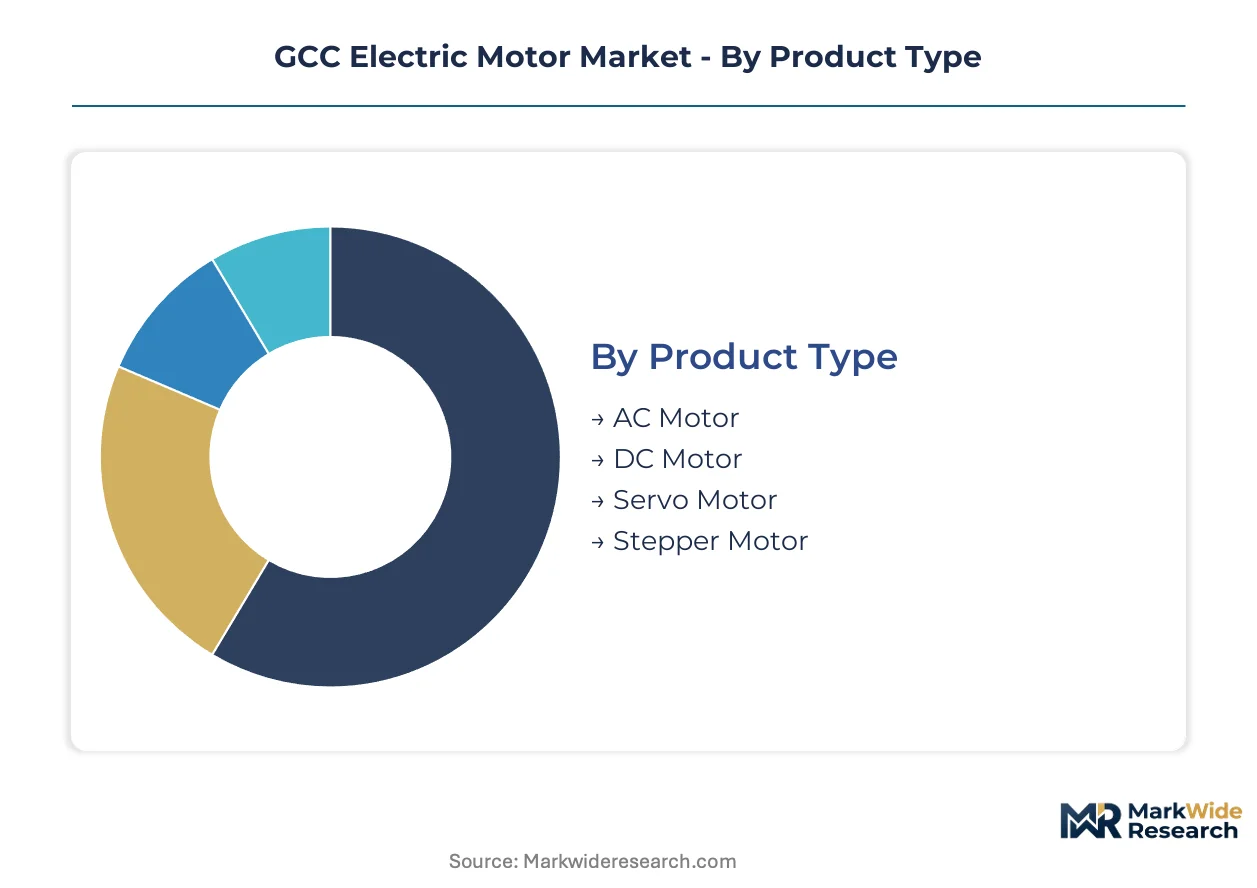
Segmentation in the GCC electric motor market reveals how procurement channels diverge across efficiency classes and voltage ratings. Industrial buyers route high-volume AC induction orders through EPC contractors, while precision motor specifications flow directly to OEM technical teams.
Product Type:
Channel mix varies sharply by motor architecture, with AC and DC platforms dominating contractor-led procurement while servo and stepper systems move through specialized distributor networks serving automation integrators.
- AC Motor:Three-phase induction and synchronous architectures constitute the bulk of medium-voltage installations across Saudi Aramco's rotating equipment fleet. Procurement concentrates through certified EPC channels subject to SASO efficiency documentation requirements.
- DC Motor:Wound-field and permanent magnet designs persist in steel re-rolling mills and crane hoist applications where precise torque control outweighs maintenance burden. UAE steel corridors sustain localized production partnerships for these configurations.
- Servo Motor:Closed-loop positioning systems with integrated encoders serve precision conveyor and packaging lines across Dubai industrial free zones.
- Stepper Motor:Open-loop incremental positioning drives low-cost automation in Kuwaiti light manufacturing clusters.
AC Motor dominates installed base. Servo Motor is where expansion concentrates.
End User:
Cost tier stratification separates premium efficiency specifications in petrochemical automation from standardized HVAC replacements in municipal infrastructure.
- Industrial Automation:Process control systems, robotic workcells, and material handling equipment demand IE3 and IE4 efficiency classes with embedded thermal protection. Saudi giga-projects at NEOM and the Red Sea coast are specifying integrated drive-motor packages with condition monitoring.
- HVAC:Centrifugal chillers and air handling units in UAE commercial real estate operate on fixed-speed and variable-frequency AC platforms. Dubai's Supreme Council of Energy mandates are accelerating replacement of pre-IE2 inventory in district cooling plants.
- Transportation:Traction motors for metro extensions and airport automated people movers specify IP55 enclosures with saline corrosion resistance.
- Renewable Energy:Solar tracking actuators and wind turbine pitch drives require extended temperature range operation above standard insulation ratings.
Industrial Automation commands premium pricing tiers. HVAC represents the highest volume throughput.
Application:
Volume concentration in fluid handling applications creates procurement scale, while robotics specifications fragment across customized integrator relationships.
- Conveyor Systems:Belt and roller drive configurations in UAE logistics hubs and Saudi e-commerce fulfillment centers specify brake motors and encoder feedback for precise positioning. Permanent magnet synchronous designs are displacing conventional induction in high-duty-cycle installations.
- Pumps:Vertical turbine and split-case configurations dominate desalination and oilfield water injection across the GCC. Medium-voltage motors above 1kV concentrate procurement through national oil company framework agreements with mandatory local content verification.
- Fans:Axial and centrifugal blower drives in Kuwait's wastewater tertiary treatment plants specify saline-rated enclosures.
- Robotics:Six-axis articulated arms and SCARA configurations in precision assembly demand low-cogging torque and minimal electromagnetic interference.
Pumps anchor the revenue base. Robotics is climbing the fastest.
Technology:
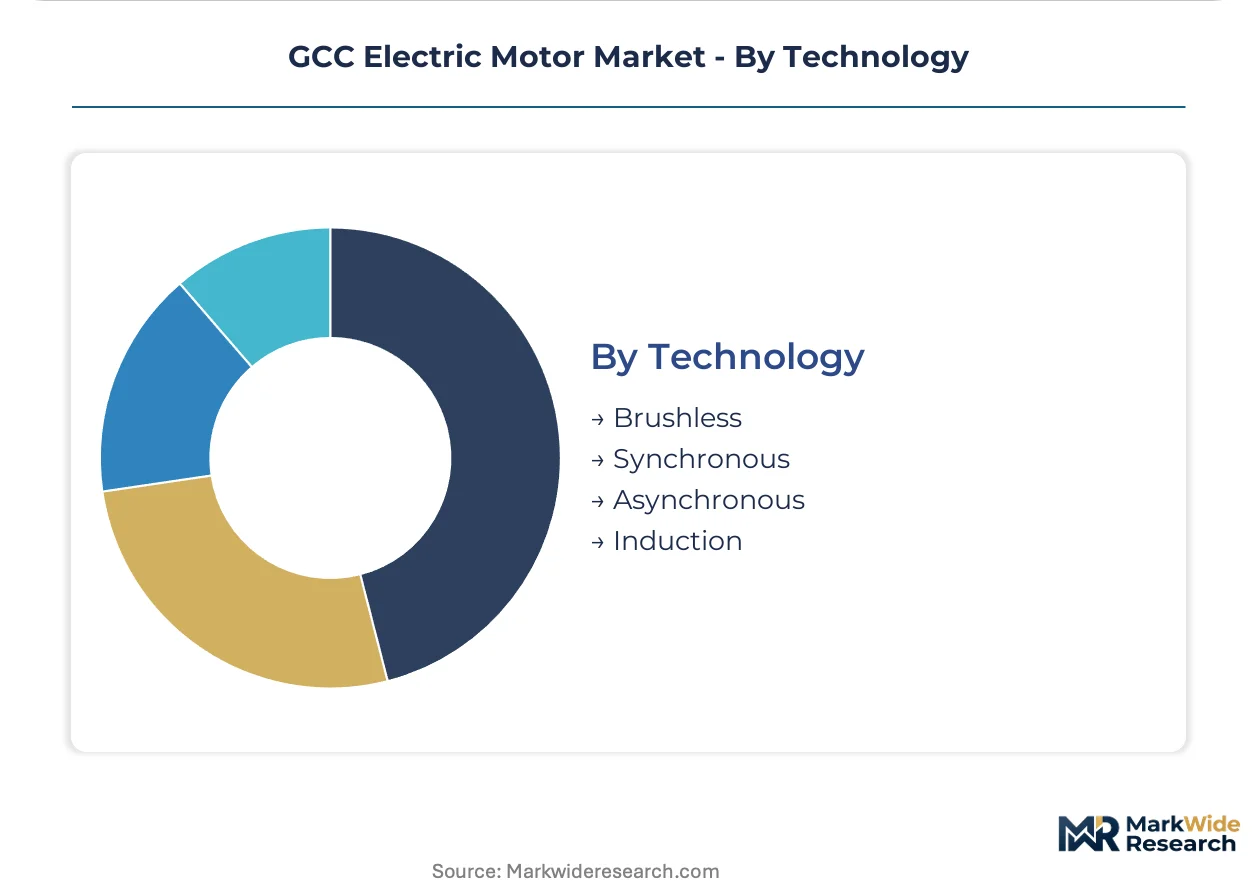
Supply concentration in asynchronous manufacturing creates margin pressure, while brushless and synchronous platforms attract technology premiums through rare-earth magnet integration.
- Brushless:Electronically commutated permanent magnet motors eliminate rotor losses entirely, achieving efficiency levels approaching IE5 without mechanical commutation maintenance. Saudi Aramco's engineering standards division is evaluating these for gas compression station variable-torque loads.
- Synchronous:Permanent magnet and wound-rotor designs maintain constant speed under load variation, critical for power quality in weak grid conditions at remote Omani industrial sites.
- Asynchronous:Squirrel-cage induction remains the default for cost-optimized pump and fan duty below 200kW.
- Induction:Single and polyphase configurations fill fractional horsepower to multi-megawatt ranges across legacy installed bases.
Induction saturates existing infrastructure. Brushless is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency defines the GCC electric motor trade balance, with in-country assembly partnerships displacing direct European and Asian shipments to satisfy local content verification requirements for national oil company procurement.
Saudi Arabia
Petrochemical corridor retrofits at Jubail and Yanbu are driving IE4-class motor demand as SASO mandates accelerate replacement of aging pump drives. The Kingdom's energy efficiency standards now embed testing documentation into EPC contractor bid compliance. Jeddah anchors the aftermarket service infrastructure serving Aramco's rotating equipment fleet.
United Arab Emirates
Steel re-rolling mills in Jebel Ali and Al Ain sustain demand for wound-rotor motor configurations with precise torque control. Dubai's Supreme Council of Energy mandates IE3-class minimums for municipal water pumping stations. ECAS conformity assessment protocols restrict market access for non-compliant import stock.
Kuwait
Tertiary wastewater treatment expansion at Al-Sulaibiya and Al-Jahra is concentrating procurement of medium-voltage motor systems with IP55 saline-rated enclosures. The Ministry of Electricity and Water now unbundles five-year maintenance agreements from initial equipment supply. This procurement shift enables specialist service providers to compete against manufacturer-captive channels.
Oman
Downstream petrochemical investments at Duqm and Sohar lack established motor service infrastructure, creating first-mover opportunities for aftermarket hub establishment. Weak grid conditions at remote industrial sites sustain demand for synchronous motor architectures that maintain constant speed under load variation. The Sultanate's procurement frameworks increasingly mirror Saudi local content requirements.
Qatar
Desalination capacity expansion along the northern coast specifies medium-voltage induction motors for vertical turbine pump configurations. The country's national oil company procurement guidelines emphasize certified OEM channels with ISO/IEC 17025-accredited testing documentation. Doha's industrial zone is attracting drive-motor integration specialists for packaged system supply.
GCC Electric Motor Market Key Industry Players
Concentration sits with diversified industrial conglomerates possessing established Gulf service networks. Market structure shows a tiered configuration with premium efficiency specialists, mid-scale regional assemblers, and import-dependent distributors competing for EPC contractor relationships. Strategic archetypes include drive-technology integrators, efficiency-certification specialists, and ambient-condition engineering adaptors. Dominant competitive moves center on in-Kingdom assembly partnerships and aftermarket service contract anchoring.
Among European-headquartered diversified industrial groups, ABB and Siemens occupy positions representing integrated drive-motor technology and localized wound-rotor production respectively. WEG Industries exemplifies emerging-market cost engineering adapted to Middle Eastern thermal derating requirements. These three anchors illustrate how competitive positioning stratifies across aftermarket service density, manufacturing localization, and efficiency-class certification breadth.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| WEG Industries |
| NIDEC Corporation |
| TECO Middle East Electrical and Machinery Co. Ltd |
| Schneider Electric SE |
| Regal Beloit Corporation |
| Johnson Electric Holdings Ltd. |
| Hyundai Electric & Energy Systems Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Permanent magnet substitution for wound-rotor induction architectures redraws procurement geography toward Chinese NdFeB magnet suppliers while compressing margin structures for European OEMs serving Saudi Aramco efficiency mandates. This input shift simultaneously elevates working capital requirements for rare-earth inventory hedging and fragments pricing power across certified versus non-certified supply channels.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium IE4-certified, standard IE3-compliant, and economy IE2-legacy tiers. Price differentiation rests on SASO-accredited testing documentation and embedded thermal protection features. Cost compression in the economy tier intensifies because Indian and Chinese assemblers bypass Gulf service infrastructure. National oil companies demonstrate lowest price sensitivity due to total-cost-of-ownership procurement frameworks, while Kuwaiti municipal buyers exhibit highest sensitivity through unbundled maintenance contracts.
Supply Chain Analysis
Strait of Hormuz transit underwrites the bulk of European and Asian motor shipments into Jebel Ali and Dammam port complexes. Manufacturing concentrates in Germany, China, and Brazil for complete units, with India and Vietnam feeding component subassemblies. Raw material dependencies center on copper cathode from Chilean smelters, silicon steel from Japanese and South Korean mills, and NdFeB magnets from Chinese processors. Single-source vulnerability concentrates in rare-earth magnet supply. Distribution runs through EPC contractor channels subject to local content verification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Saudi Aramco's framework agreement consolidation and Kuwait's Ministry of Electricity and Water procurement centralization, compressing supplier margins across the GCC.
For Market Incumbents: Compound aftermarket service density through Jeddah and Dubai hub expansion to offset margin erosion from IE4 efficiency mandates. Defend against Brazilian cost-engineered entrants by embedding condition monitoring into drive-motor packages. Prioritize certification investment in SASO-accredited testing documentation to maintain EPC contractor channel access. For New Entrants and Emerging Players: SASO fast-track certification partnerships with Riyadh-based laboratories unlock bid compliance for Saudi giga-projects. White-space targets concentrate in Oman's Duqm and Sohar petrochemical corridors lacking established motor service infrastructure. Kuwait's unbundled maintenance procurement enables specialist service provider positioning against manufacturer-captive channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European industrial service networks possessing Gulf aftermarket footprints. Long-term viability hinges on 5-10 year local content rule durability across Saudi and Omani procurement frameworks. Acquisition candidates include mid-scale regional assemblers with in-Kingdom production partnerships. Monitor SASO testing backlog duration as inflection indicator for certification-constrained supply.| Strategic Initiative | Industry Significance |
|---|---|
| In-Kingdom Assembly Partnership | Satisfies Saudi local content verification requirements for Aramco framework agreements. |
| Aftermarket Service Hub Establishment | Captures long-term maintenance contracts in Oman's underpenetrated industrial zones. |
| Integrated Drive-Motor Package Development | Reduces commissioning complexity for NEOM giga-project automation specifications. |
| SASO Certification Fast-Track Investment | Compresses fourteen-week testing backlogs to align with budget cycle timing. |
| Rare-Earth Magnet Supply Hedging | Mitigates NdFeB price volatility exposure through six-month forward contracting. |
Research Approach
A spread of perspectives from plant engineers at Saudi petrochemical complexes, procurement leads at UAE steel re-rolling mills, EPC contractor technical specialists, and aftermarket service managers converged on the working assumptions. Secondary validation drew from SASO technical regulation filings, UAE ECAS conformity assessment protocols, customs trade data for motor imports through Jebel Ali and Dammam, and SEC disclosures from listed industrial conglomerates. Bottom-up unit economics triangulated against top-down sectoral expenditure patterns.
Segmentation dimensions modeled span efficiency class, voltage rating, motor architecture, end-use industry, and application type across the projection horizon. CAGRs derived from regression analysis against petrochemical capacity expansion timelines, wastewater infrastructure procurement schedules, and regulatory mandate implementation dates. Industry-specific inputs include thermal derating coefficients for Gulf ambient conditions and local content verification threshold trajectories.
Decision-makers should treat outputs as directional under stable regulatory enforcement and commodity price assumptions; material deviation in Chinese rare-earth export policy or SASO mandate acceleration would warrant model refresh. Practitioners should keep alternative scenarios live as Saudi giga-project local content rules and Kuwaiti procurement unbundling trends evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Torque Motor Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Australia Solar E-Bike Market
Electric Motor
Traction Motors Market
Electric Motor
E-Bike Motor Market
Electric Motor
Traction Motor Core Market
Electric Motor
Global Automotive Heating Fan Motor Market
Electric Motor
Europe Electric Commercial Vehicle Battery Pack Market
Electric Motor
Global in-Wheel Motors Market
Electric Motor
Automotive Torque Actuator Motor Market
Electric Motor
EV Traction Motor Control Unit Market
Electric Motor
Global Automotive Onboard Charger Market
Electric Motor
Global Automotive Starter Motor Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Garden Tool Lithium Battery Market
Electric Motor
UK Solar E-Bike Market