
 Global Intelligent Apps Market | 2026-2036
Global Intelligent Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intelligent Apps Market Foresight
The EU AI Act is rebalancing compliance burdens across the intelligent apps stack, forcing vendors to embed audit trails and risk-management protocols from architecture phase onward. Microsoft Corporation leverages its Azure AI portfolio to anchor enterprise deployments with built-in governance tooling. Google LLC differentiates through TensorFlow-powered custom model pipelines that compete for workloads requiring on-premises flexibility.
Intelligent apps are software systems that embed machine learning, natural language processing, or computer vision to autonomously adapt behavior based on real-time data inputs and user context. These systems typically process streaming data through API-connected inference engines, delivering predictive outputs or automated decisions without human-in-the-loop latency. Machine Learning deployments currently occupy the largest technology slice, while Edge Computing infrastructure is accelerating fastest as manufacturers push inference closer to sensor arrays. Natural Language Processing applications in customer support command premium pricing due to integration complexity and enterprise SLA requirements.
The US Federal Trade Commission scrutinizes algorithmic discrimination in credit and hiring apps, while the EU's GDPR and AI Act jointly enforce explainability mandates that constrain black-box model deployment. China's SAMR and MIIT enforce algorithm recommendation transparency rules that affect intelligent app distribution on domestic platforms. Stakeholders must monitor regulatory divergence across Washington, Brussels, and Beijing to avoid fragmentation of their compliance architecture and product versioning.
Market Dynamics
The EU AI Act's risk-classification framework is forcing intelligent app vendors to rearchitect product pipelines around embedded auditability, compressing development cycles for high-risk financial and healthcare deployments while creating compliance moats for early movers.
Growth Catalysts
- Real-time fraud detection mandates:Financial services regulators in the United States and European Union now require sub-second transaction monitoring, pulling GPU-accelerated inference engines into core banking infrastructure.
- Edge AI silicon cost curves:Foundry capacity expansion for 5nm and 3nm process nodes is driving down per-TOPS pricing for on-device neural processing units, enabling sensor-integrated manufacturing lines.
- GDPR Article 22 enforcement:Automated decision-making restrictions in credit and hiring applications are creating demand for explainable AI middleware that generates human-readable audit trails.
Market Restraints
- Cloud compute concentration:Hyperscaler dominance in GPU-as-a-service creates single-supplier vulnerability for training workloads, with spot pricing volatility exceeding 40% during peak demand windows.
- Training data licensing friction:Copyright litigation around large language model training corpora is raising indemnification costs and forcing synthetic data investments that degrade model performance.
- On-premise integration legacy:Mainframe-dependent enterprises in insurance and government face 18-36 month modernization timelines that delay intelligent app deployment.
Strategic Opportunities
- India's Digital Public Infrastructure:The country's unified payments interface and Aadhaar identity layer create a ready substrate for voice-enabled vernacular banking applications in 22 scheduled languages.
- Federated learning architectures:Cross-silo model training without raw data movement is opening healthcare consortiums in Germany and Switzerland where patient privacy rules previously blocked centralized AI.
- Carbon accounting convergence:CSRD disclosure requirements are pulling intelligent emissions-tracking applications into supply chain software stacks previously dominated by static reporting tools.
Industry Challenges
- MLOps talent scarcity:Production-grade model monitoring and drift detection expertise commands 2-3x base salary premiums, constraining enterprise scale-out timelines.
- Conformity assessment bottlenecks:EU AI Act notified body capacity for high-risk system certification remains below 200 applications annually, creating 14-month approval queues.
- API dependency fragility:Third-party model provider rate limits and deprecation schedules force contingency engineering that consumes 15-20% of engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intelligent Apps Market |
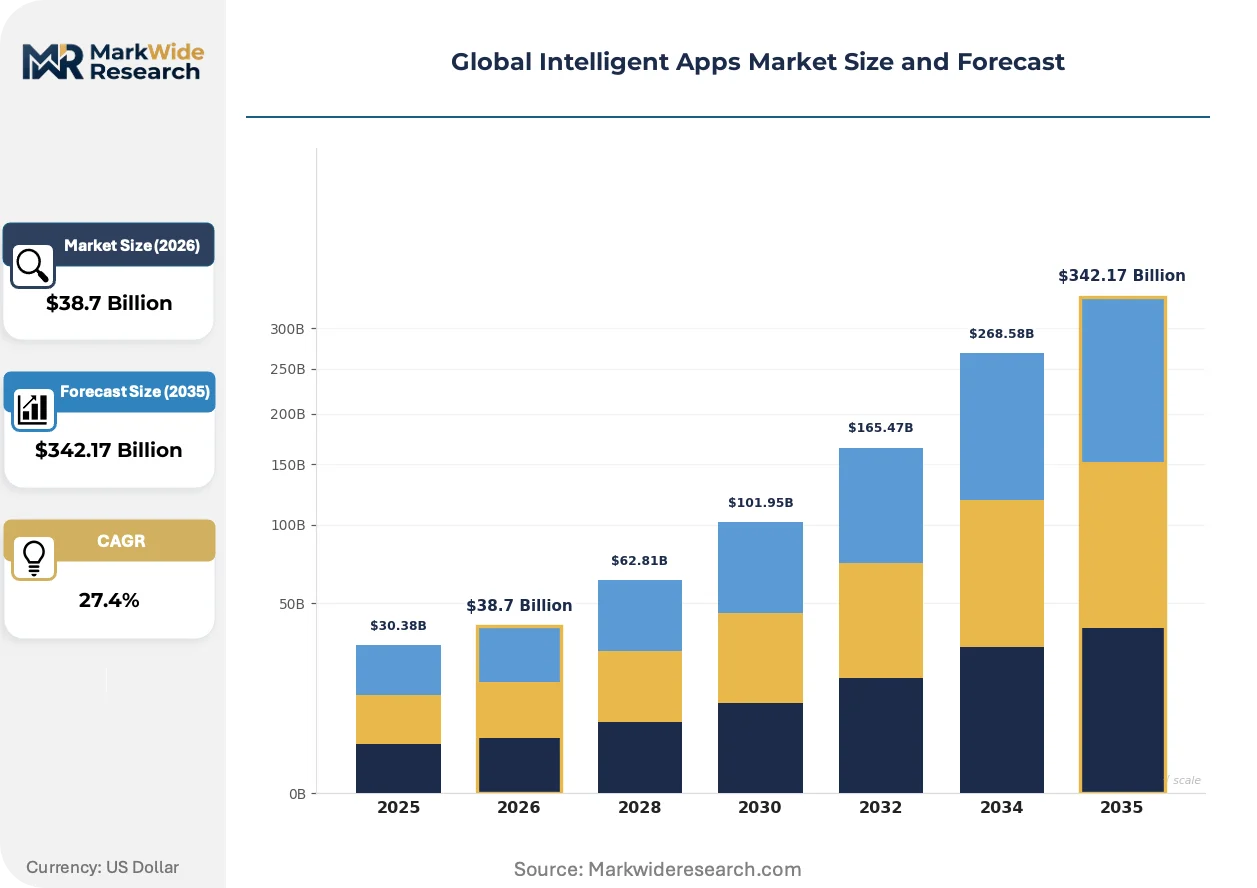
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $342.17 Billion |
| CAGR (2026 – 2036) | 27.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Home Automation, Predictive Maintenance, Fraud Detection, Customer Support, Supply Chain Optimization Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Technology: Natural Language Processing, Machine Learning, Computer Vision, Robotic Process Automation, Context-Aware Computing End User: Financial Services Firms, Telecom Providers, Retail Chains, Manufacturing Plants, Government Agencies |
| Companies Covered | Microsoft Corporation, Google LLC, Apple Inc., Amazon Web Services, Inc., International Business Machines Corporation, SAP SE, Oracle Corporation, Salesforce, Inc., ServiceNow, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intelligent Apps Market Shifts & Advancements
Foundation model commoditization is compressing value capture toward application-layer orchestration and vertical-specific tuning, while regulatory fragmentation across Washington, Brussels, and Beijing forces multi-jurisdictional compliance engineering.
Retrieval-augmented generation architectures are consolidating enterprise knowledge management by grounding large language model outputs in proprietary document corpora without retraining. Manufacturing quality assurance teams at automotive suppliers adopt these systems to query engineering change orders against live production telemetry. The technology is consolidating vendor landscapes previously split between search, business intelligence, and static reporting tools.
The EU AI Act's conformity assessment deadlines are forcing product roadmap prioritization around risk-classification tiers, with high-risk systems requiring notified body involvement before market entry. Healthcare diagnostic applications face the steepest compliance burden, with some vendors withdrawing from the European market rather than absorbing certification costs. German medical device manufacturers are responding by pre-certifying modular AI components that can be recombined across product lines.
Buyers are unbundling intelligent app procurement from incumbent enterprise software suites, creating direct vendor relationships for specialized NLP and computer vision components. This disintermediation is most pronounced in United States financial services, where compliance teams demand direct SLAs from model providers rather than accepting bundled uptime guarantees from cloud platforms. Procurement teams now negotiate separate contracts for inference infrastructure, model weights, and fine-tuning services.
Global Intelligent Apps Market Segmentation
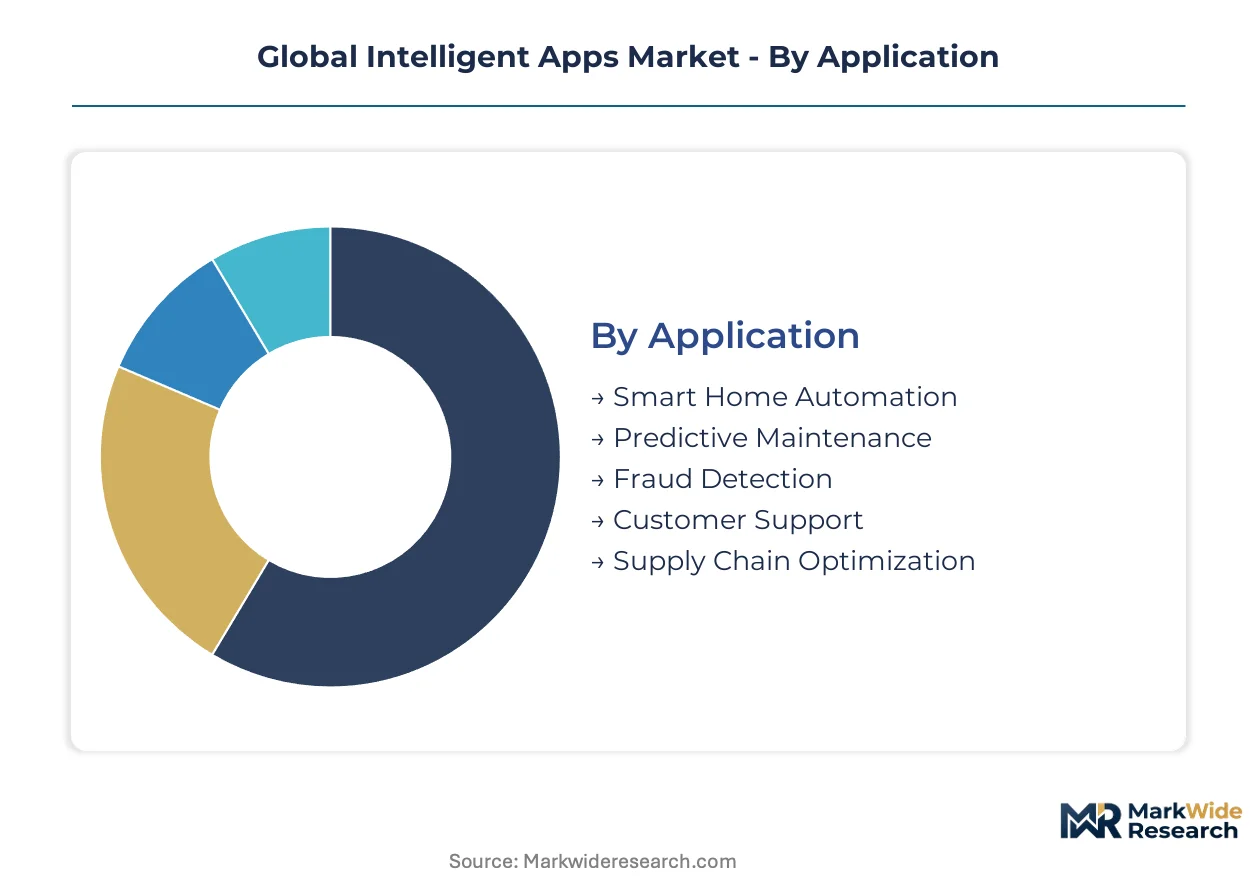
Intelligent apps fragment across multiple deployment paradigms and technology stacks, each carrying distinct compliance obligations and infrastructure requirements. Vendors architect product lines around these boundaries to capture differential pricing and reduce cross-segment engineering overhead.
Application:
Upgrade cycles in enterprise software accelerate as legacy rule-based systems face replacement pressure from adaptive inference engines.
- Fraud Detection:Real-time transaction scoring engines process sub-second inference on streaming payment data. United States financial services regulators now mandate automated monitoring, pulling GPU-accelerated infrastructure into core banking stacks.
- Customer Support:Conversational AI platforms handle multi-turn dialogue with enterprise SLA guarantees. Natural language applications command premium pricing in North American telecom and retail sectors due to integration complexity and uptime requirements.
- Smart Home Automation:Sensor-fusion systems orchestrate device networks through edge-local inference.
- Predictive Maintenance:Vibration and thermal anomaly detection extends asset life in industrial settings.
- Supply Chain Optimization:Demand forecasting models ingest multi-source telemetry for inventory positioning.
Fraud Detection sits at the top of the volume ranking, with Customer Support climbing the fastest.
Deployment:
Cost tiering separates hyperscaler-managed infrastructure from self-hosted alternatives, with hybrid architectures capturing mid-budget enterprises.
- Cloud-Based:Managed inference APIs abstract hardware provisioning and model serving. United States enterprises dominate consumption as cloud infrastructure spending outpaces other national markets.
- Edge Computing:On-device neural processing enables sub-10ms response for manufacturing quality control. German automotive suppliers deploy sensor-integrated lines where foundry cost curves for 5nm silicon drive down per-TOPS pricing.
- On-Premises:Air-gapped deployments satisfy data residency mandates in government and defense.
- Hybrid:Split workloads route sensitive preprocessing locally while leveraging cloud training.
Cloud-Based deployments retain the largest installed base, with Edge Computing expanding most quickly.
Technology:
Application maturity determines vendor investment priority, with production-grade tooling concentrating in established categories.
- Machine Learning:Supervised and unsupervised model pipelines power predictive analytics across verticals. Financial services firms in the United States deploy ensemble methods for algorithmic trading and credit scoring.
- Natural Language Processing:Transformer architectures enable document understanding and generation tasks. EU GDPR Article 22 enforcement creates demand for explainable middleware that generates human-readable audit trails.
- Computer Vision:Convolutional and vision-transformer models process visual inspection and surveillance feeds.
- Robotic Process Automation:Rule-based task automation bridges legacy system gaps before ML substitution.
- Context-Aware Computing:Sensor and location fusion personalizes outputs based on environmental state.
Machine Learning holds the dominant technology share, with Natural Language Processing gaining share fastest.
End User:
Customer type dictates procurement complexity, with regulated industries demanding direct vendor relationships and custom SLA terms.
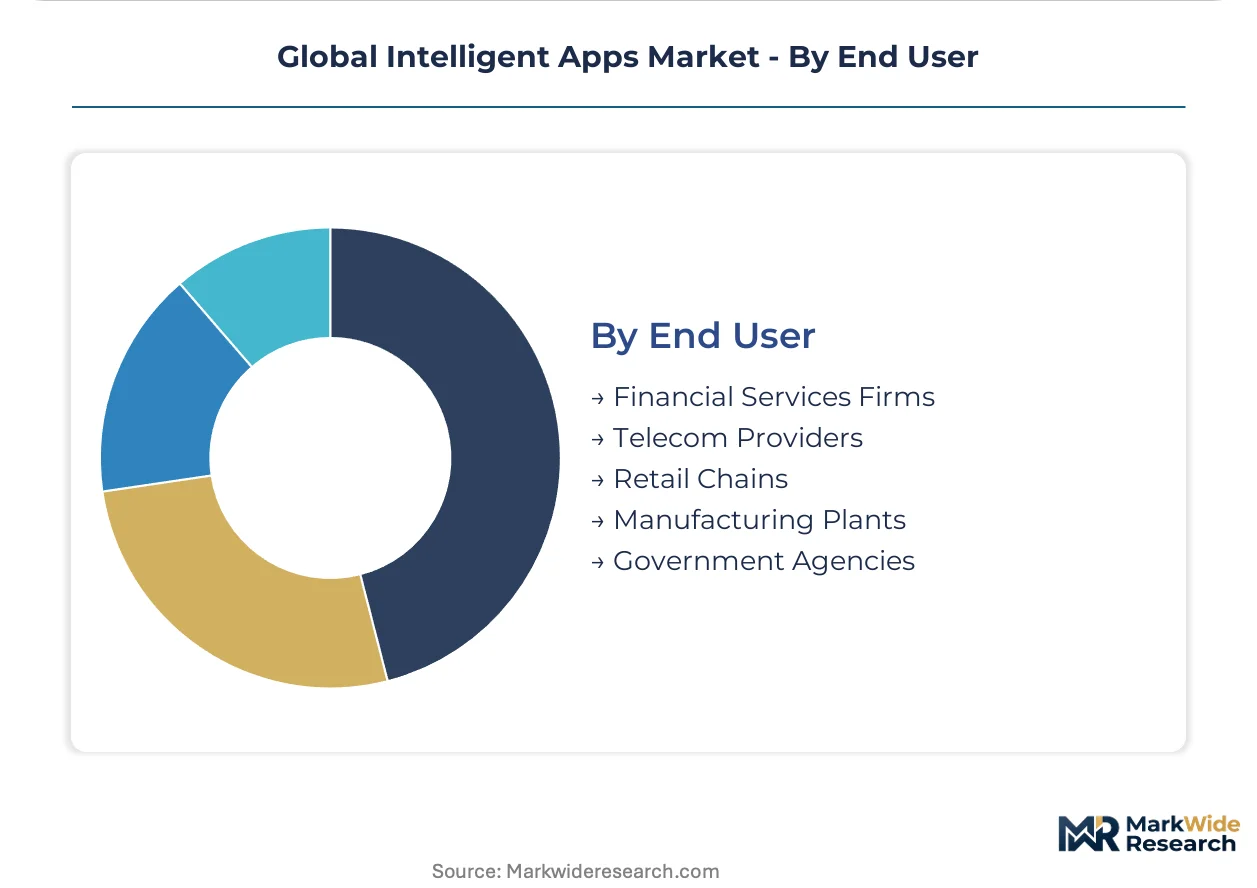
- Financial Services Firms:Banks and insurers deploy real-time fraud detection and algorithmic trading systems. United States compliance teams negotiate separate contracts for inference infrastructure, model weights, and fine-tuning services rather than accepting bundled cloud guarantees.
- Manufacturing Plants:Quality assurance and predictive maintenance applications integrate with SCADA and MES layers. German automotive suppliers adopt retrieval-augmented generation to query engineering change orders against live production telemetry.
- Telecom Providers:Network optimization and customer churn prediction drive infrastructure investment.
- Retail Chains:Demand forecasting and personalization engines compete on inventory turns.
- Government Agencies:Procurement cycles extend 18-36 months due to legacy mainframe dependencies and security clearance requirements.
Financial Services Firms anchor current demand, with Manufacturing Plants showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine learning engineers and MLOps specialists cluster in San Francisco, Bengaluru, and Berlin, anchoring regional development velocity for intelligent applications. Talent density shapes where vendors establish research centers and where enterprises secure implementation partners.
United States
Financial services firms in New York and Chicago deploy real-time fraud detection systems that process sub-second transaction scoring. The FTC enforces algorithmic discrimination rules in credit and hiring applications, constraining black-box model deployment. San Francisco Bay Area cloud infrastructure spending outpaces other national markets, pulling GPU-accelerated inference engines into enterprise stacks.
Germany
Automotive suppliers in Stuttgart and Munich adopt sensor-integrated manufacturing lines with edge-local neural processing. The EU AI Act imposes conformity assessments on high-risk systems, compressing development cycles for healthcare deployments. Bavarian medical device manufacturers pre-certify modular AI components for recombination across product lines.
China
Manufacturing plants in Shenzhen and Shanghai deploy computer vision for quality assurance at scale. SAMR and MIIT enforce algorithm recommendation transparency rules affecting intelligent app distribution on domestic platforms. Yangtze River Delta foundry capacity expansion for 5nm silicon drives down per-TOPS pricing for on-device neural processing units.
India
Banks and telecom providers in Mumbai and Bengaluru pilot voice-enabled vernacular applications across 22 scheduled languages. RBI guidelines on digital lending algorithms create compliance frameworks for automated credit decisions. Karnataka's engineering talent pool supports federated learning architectures for healthcare consortiums where patient privacy rules previously blocked centralized AI.
United Kingdom
London financial services firms unbundle intelligent app procurement from incumbent enterprise suites, negotiating direct SLAs with model providers. GDPR Article 22 enforcement creates demand for explainable AI middleware generating human-readable audit trails. The city's insurance sector faces 18-36 month modernization timelines from mainframe dependencies that delay deployment.
Global Intelligent Apps Market Competitive Landscape
The competitive structure tilts toward hyperscaler-dominated infrastructure layers with specialized vertical vendors occupying application niches. Cloud platforms consolidate training and inference workloads while boutique providers capture premium pricing for regulated industry deployments. Three archetypes dominate: horizontal AI platforms, vertical SaaS with embedded intelligence, and infrastructure-agnostic model providers. Strategic moves concentrate on M&A for talent acquisition and geographic expansion through local compliance partnerships.
Within the hyperscaler tier, Microsoft Corporation exemplifies platform consolidation through Azure-anchored enterprise deployments with governance tooling. Google LLC occupies a position emphasizing open-source model ecosystems and custom pipeline flexibility. Among enterprise software incumbents, SAP SE and Salesforce, Inc. represent the vertical integration archetype, embedding predictive capabilities into core workflow applications where data residency and audit trails command pricing premiums.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Apple Inc. |
| Amazon Web Services, Inc. |
| International Business Machines Corporation |
| SAP SE |
| Oracle Corporation |
| Salesforce, Inc. |
| ServiceNow, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up MLOps specialists anchor supply-side discipline through portfolio consolidation, while hyperscaler capex cycles compress pricing power for GPU-as-a-service tiers and create tiered access to inference infrastructure.
Pricing Analysis
Bundled cloud platform subscriptions compete against unbundled procurement of model weights, inference APIs, and fine-tuning services. Three-tier pricing structure across premium, standard, and economy levels separates enterprise SLA-guaranteed deployments from developer-tier consumption and batch inference alternatives. Price differentiation hinges on GDPR Article 22 explainability certification and vertical-specific compliance modules. Cost compression in standard-tier SaaS is intensifying because foundation model commoditization erodes application-layer margins. Government agencies exhibit highest price sensitivity due to 18-36 month procurement cycles, while United States financial services firms accept premium pricing for direct vendor SLAs.
Supply Chain Analysis
GPU foundry capacity rests on Taiwan Semiconductor Manufacturing, Samsung Electronics, and Intel Corporation for advanced process nodes at 5nm and 3nm geometries. Neural processing unit silicon draws from Yangtze River Delta packaging facilities and Malaysian back-end assembly operations. Supply chain risk centers on single-source vulnerability for high-bandwidth memory from South Korean producers. Distribution runs through hyperscaler marketplaces, direct enterprise sales teams, and systems integrators with vertical specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through edge AI silicon cost curves that compress per-TOPS pricing and enable premium-tier sensor-integrated deployments.
For Market Incumbents: Anchor enterprise retention through pre-certified modular AI components that recombine across EU AI Act risk tiers. Deepen backward integration into sovereign cloud infrastructure to offset hyperscaler concentration risk. Lock in financial services procurement teams with direct SLAs on model weights and inference uptime rather than bundled platform guarantees. For New Entrants and Emerging Players: Begin with India's Digital Public Infrastructure layer for voice-enabled vernacular banking applications across 22 scheduled languages. Target German healthcare consortiums with federated learning architectures that bypass patient privacy barriers to centralized training. Pursue carbon accounting convergence opportunities where CSRD disclosure requirements displace static reporting tools. For Investors and Strategic Acquirers: Hyperscaler cloud divisions are the most active acquirer in this space, consolidating vertical SaaS vendors for embedded intelligence capabilities. Over the coming decade, model orchestration tooling and explainable AI middleware represent durable value-capture layers. Monitor EU AI Act notified body capacity expansion as the inflection signal for high-risk system market entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Modular AI Component Pre-certification | German medical device manufacturers recombine certified modules across product lines to compress EU AI Act compliance timelines. |
| Federated Learning Architecture Deployment | Healthcare consortiums in Germany and Switzerland train models without raw data movement, bypassing patient privacy restrictions. |
| Edge AI Silicon Integration | Automotive suppliers in Stuttgart deploy sensor-integrated lines where 5nm cost curves drive down per-TOPS pricing. |
| Explainable AI Middleware Development | GDPR Article 22 enforcement creates demand for human-readable audit trails in credit and hiring applications. |
| Vernacular Language Model Tuning | Indian banks pilot voice-enabled applications across 22 scheduled languages atop unified payments infrastructure. |
Research Methodology
Direct dialogue with MLOps engineering leads, enterprise IT procurement officers, regulatory compliance directors, and cloud platform solution architects grounds qualitative assessment. Secondary validation draws from SEC 10-K hyperscaler disclosures, EU AI Act implementation guidance, FDA algorithmic device submissions, and RBI digital lending circulars. Bottom-up and top-down triangulation reconciles vendor shipment data with enterprise spending surveys across deployment models and vertical segments.
Top-down macroeconomic drivers and bottom-up customer adoption curves converge across the analysis window. Segmentation dimensions include application type, deployment paradigm, underlying technology stack, organization size tier, and regional regulatory cluster. CAGRs derive from curve-fitting historical adoption rates against infrastructure capacity expansion and compliance deadline schedules. Forecast inputs incorporate GPU foundry utilization rates and notified body certification queue lengths.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor supply, sudden EU AI Act enforcement intensity shifts, and foundation model capability breakthroughs that obsolete application-layer value capture. Forecasts reflect documented assumptions on edge silicon cost trajectories and regulatory harmonization timelines. A small set of named triggers warrants ongoing watch: hyperscaler spot pricing volatility exceeding historical bands, copyright litigation outcomes affecting training data licensing, and MLOps talent scarcity metrics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Financial Corporate Performance Management (FCPM) Software Market
Software & Services
Debt Collection Software Market
Software & Services
Global Intellectual Property Management Software Market
Software & Services
House Cleaning App Market
Software & Services
Fiber Simulation Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Global Customer Communications Management (CCM) Software Market
Software & Services
Admission Management Software Market
Software & Services
Landscaping Engineering Software Market
Software & Services
Middle East and Africa Workforce Management Software Market
Software & Services
Intellectual Property Software Market
Software & Services
Hypervisor Market
Software & Services
Cricket Analysis Software Market
Software & Services
Equipment Management Software Market
Software & Services
Global Configuration Management Software Market