
 Asia-Pacific Feed Pigments Market | 2026-2036
Asia-Pacific Feed Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Feed Pigments Market Outlook
Broiler integrators are collapsing the historical price premium that layer operations once commanded for carotenoid-enriched feeds. BASF SE anchors its position through captive production of nature-identical astaxanthin at scale, while Kemin Industries differentiates via microencapsulation technology that stabilizes pigment bioavailability in tropical humidity. Guangzhou Leader Bio-Technology Co., Ltd. dominates distribution into China's southern provincial feed mills, leveraging direct technical service teams.
Feed pigments comprise carotenoids, spirulina extracts, beetroot red, and anthocyanins—bioactive compounds dosed at parts-per-million levels to impart coloration in animal tissues, eggs, and aquaculture products. Carotenoids constitute the dominant product class due to proven transfer efficiency into poultry skin and egg yolk, while spirulina gains traction among organic-certified aquafeed formulators seeking non-synthetic alternatives. The poultry end-user segment absorbs the largest volume share, though aquaculture applications exhibit the fastest structural expansion as shrimp and salmonid producers chase export-grade color specifications.
China's SAMR enforces GB standards on feed additive safety and labeling, while India's FSSAI and BIS jointly regulate maximum residue thresholds for pigment carriers. The EU Green Deal's due diligence requirements, extraterritorially affecting Asia-Pacific exporters, are forcing reformulation away from synthetic azo dyes toward nature-derived carotenoids. Stakeholders must monitor regulatory divergence between ASEAN harmonization initiatives and national registration pathways, as this friction will determine which pigment suppliers retain market access.
Market Dynamics
Broiler integrators across Southeast Asia are collapsing the historical price premium that layer operations once commanded for carotenoid-enriched feeds, compressing margin structures throughout the value chain and forcing pigment suppliers to differentiate on bioavailability stability rather than color intensity alone.
Growth Catalysts
- EU Green Deal due diligence:Extraterritorial requirements on Asia-Pacific exporters are accelerating reformulation away from synthetic azo dyes toward nature-derived carotenoids, expanding addressable market for compliant suppliers.
- Vietnam's Mekong Delta aquaculture belt:Shrimp farmers prioritize astaxanthin supplementation for shell pigmentation to meet export-grade color specifications, driving volume concentration in this delta cluster.
- Microencapsulation technology:Advanced stabilization systems protect pigment bioavailability under tropical humidity conditions, enabling reliable performance in Southeast Asian feed mill environments.
Market Restraints
- Synthetic astaxanthin supply concentration:Captive production of nature-identical carotenoids remains concentrated among a limited number of chemical conglomerates, creating procurement bottlenecks for mid-tier feed formulators.
- GB standards compliance costs:China's SAMR enforcement of feed additive safety and labeling protocols imposes substantial registration burdens on imported pigment products, extending market entry timelines.
- Spirulina extract substitution ceiling:Organic-certified aquafeed formulators face technical limitations in achieving equivalent transfer efficiency to synthetic carotenoids for intensive salmonid coloration.
Strategic Opportunities
- India's FSSAI-aligned feed safety expansion:Joint BIS-FSSAI regulation of maximum residue thresholds creates first-mover advantage for suppliers establishing compliant pigment carrier portfolios in this underpenetrated market.
- Direct technical service distribution:Southern China's provincial feed mills respond to embedded technical teams that optimize dosage protocols, creating defensible channel relationships against trading-house competitors.
- Anthocyanin-beetroot red convergence:Blending these non-synthetic colorants for niche organic poultry applications addresses regulatory tailwinds while differentiating from commodity carotenoid positioning.
Industry Challenges
- Pigment analytical chemist scarcity:Feed mills across the region lack personnel capable of validating parts-per-million dosing accuracy and transfer efficiency into target tissues, creating quality control vulnerabilities.
- Dual registration pathway friction:ASEAN harmonization initiatives diverge from national registration requirements in Thailand, Indonesia, and Vietnam, forcing suppliers to maintain parallel compliance documentation.
- Tropical supply chain reconfiguration:Cold-chain integrity for heat-sensitive natural extracts requires capital deployment into climate-controlled logistics infrastructure that legacy distributors cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Feed Pigments Market |
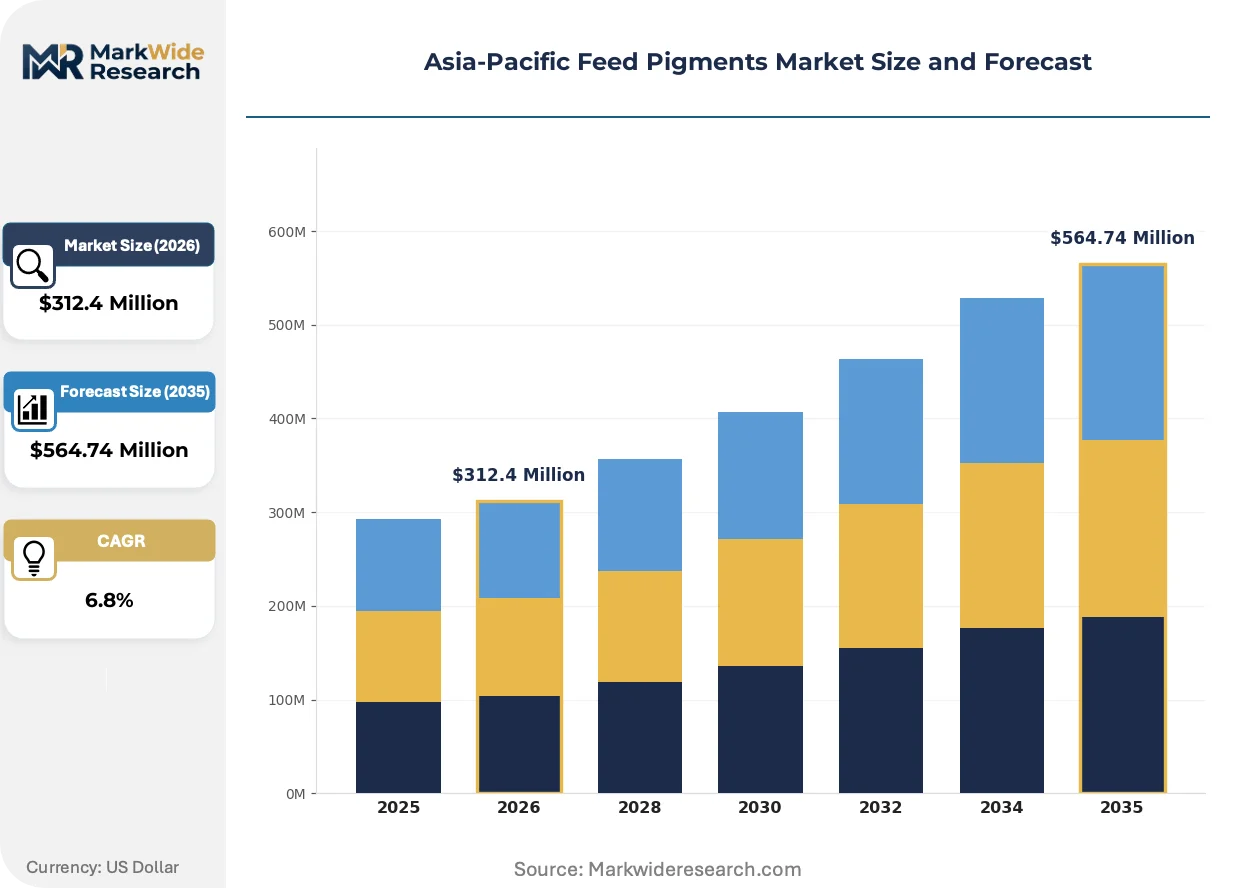
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carotenoids, Spirulina, Beetroot Red, Anthocyanins End User: Poultry, Swine, Aquaculture, Ruminants Application: Color Enhancement, Nutritional Supplement, Feed Formulation, Health Maintenance Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Synthite Industries Ltd, Royal DSM N.V., BASF SE, Guangzhou Leader Bio-Technology Co., Ltd., Behn Meyer Group, Kemin Industries, EW Nutrition (Novus International Inc.), D.D. Williamson & Co. Inc., Nutrex NV, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Feed Pigments Market Strategic Shifts
Formulation science is actively displacing commodity trading as the primary value-creation mechanism in Asia-Pacific feed pigments, with technical service capabilities now determining supplier selection more than price positioning.
Microencapsulation technology is miniaturizing protective shell structures around carotenoid molecules to sub-micron scales, enabling BASF SE and specialized ingredient houses to guarantee bioavailability through tropical feed mill processing conditions. Broiler integrators in Thailand and Indonesia are adopting these stabilized formats at accelerated procurement cycles, compressing the competitive advantage of unprotected commodity pigments and raising technical barriers for trading-house distributors lacking formulation expertise.
China's GB standards on feed additive safety and labeling, enforced by SAMR, are tightening maximum residue thresholds and documentation requirements for imported pigment carriers. This regulatory compression is forcing multinational suppliers to establish in-country analytical laboratories and local registration teams, while domestic competitors leverage existing relationships with provincial feed safety inspectors. The poultry end-use segment faces the steepest compliance burden, as integrators must now trace pigment batch lineage through finished product distribution.
Certification-driven procurement is consolidating buyer power among ASEAN aquafeed formulators seeking ASC and BAP certification for shrimp export markets. Large-scale Mekong Delta operations are unbundling pigment sourcing from compound feed contracts, establishing direct supplier relationships that bypass traditional trading intermediaries. This channel disintermediation is most visible in Vietnam, where vertically integrated shrimp producers now specify astaxanthin suppliers by name in feed mill service agreements rather than accepting pigment-included pricing.
Asia-Pacific Feed Pigments Market Segmentation
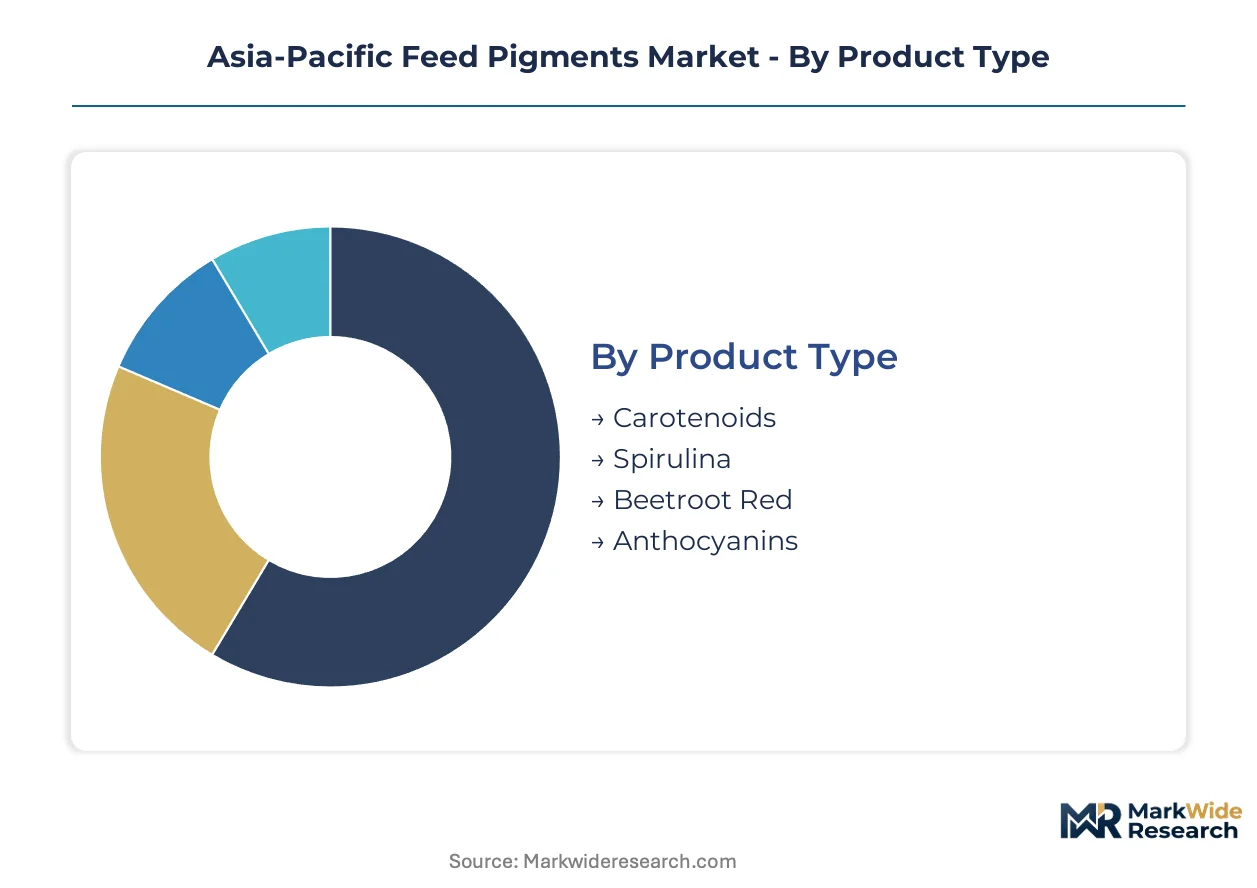
Segmentation in Asia-Pacific feed pigments reveals where substitution pressure reshapes procurement patterns. Carotenoid suppliers face spirulina encroachment in organic aquafeed, while distribution channel selection determines whether pigment houses capture margin or cede it to intermediaries.
Product Type:
Carotenoid segments confront the most acute substitution threat from nature-derived alternatives as EU Green Deal due diligence propagates through export supply chains.
- Carotenoids:Synthetic and nature-identical astaxanthin, canthaxanthin, and lutein dominate commercial formulations due to proven transfer efficiency into poultry skin and egg yolk. Broiler integrators across Thailand and Indonesia specify these compounds for consistent coloration metrics that satisfy domestic retail and export inspection protocols.
- Spirulina:Microalgae-derived phycocyanin and carotenoid complexes attract organic-certified aquafeed formulators seeking non-synthetic alternatives for salmonid and shrimp pigmentation. Vietnam's Mekong Delta shrimp producers increasingly trial spirulina blends to meet ASC certification requirements for European export markets.
- Beetroot Red:Betalain pigments from Beta vulgaris provide heat-stable red coloration for niche organic poultry applications where synthetic azo dye exclusion is mandatory.
- Anthocyanins:Water-soluble flavonoid extracts from berry and vegetable sources address regulatory tailwinds in premium layer feed segments demanding clean-label positioning.
Carotenoids retain volume leadership; spirulina holds the steepest expansion curve.
End User:
Cost tier stratification separates commodity protein producers from export-oriented operations willing to absorb pigment premiums for certification compliance.
- Poultry:Broiler and layer operations absorb the largest pigment volumes, with skin coloration specifications driving carotenoid inclusion rates in Southeast Asian integrator contracts. China's provincial feed mills optimize dosage protocols through embedded technical service relationships that bypass trading-house intermediaries.
- Aquaculture:Shrimp and salmonid producers chase export-grade color specifications with the most intensive pigment dosing regimes. Mekong Delta operations now unbundle astaxanthin sourcing from compound feed contracts, establishing direct supplier specifications in mill service agreements.
- Swine:Pork producers utilize limited pigment supplementation for fat color modification in premium domestic market segments, though volume concentration remains marginal compared to poultry.
- Ruminants:Dairy and beef operations show minimal pigment adoption outside niche butterfat coloration applications in high-value export-oriented herds.
Poultry commands absolute volume; aquaculture climbs the fastest on export certification demand.
Application:
Application segmentation tracks how pigment functionality expands beyond aesthetic into nutritional positioning as formulators seek differentiation.
- Color Enhancement:Primary driver of carotenoid demand across all species, with yolk color fan scoring and skin pigmentation metrics determining procurement decisions in integrated poultry operations.
- Nutritional Supplement:Provitamin A activity and antioxidant properties of certain carotenoids support premium feed positioning, though bioavailability claims require analytical validation that many regional feed mills cannot execute.
- Feed Formulation:Process integration of microencapsulated pigments protects bioavailability through tropical humidity conditions and pelleting thermal stress.
- Health Maintenance:Immunomodulatory and reproductive health claims associated with specific carotenoid profiles remain secondary to coloration in commercial purchasing criteria.
Color enhancement anchors volume; nutritional supplement gains share fastest on premium tier expansion.
Distribution Channel:
Channel selection determines whether pigment suppliers capture technical service premiums or compete as commodity traders on price alone.
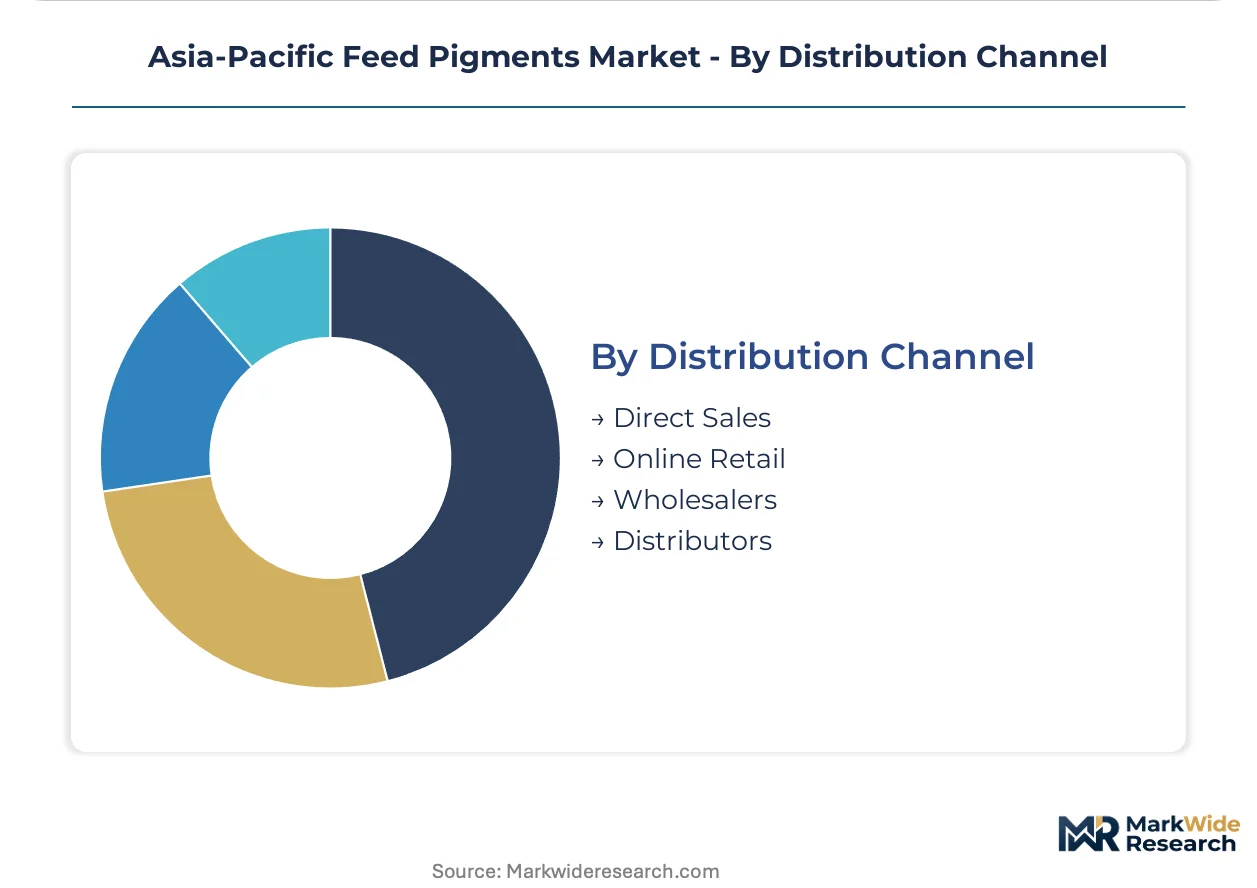
- Direct Sales:Technical teams embedded with southern China's provincial feed mills optimize dosage protocols and validate transfer efficiency, creating defensible relationships against distributor competitors. BASF SE and Kemin Industries prioritize this channel for high-value microencapsulated formulations.
- Distributors:Legacy trading houses dominate commodity carotenoid movement but lose ground as vertically integrated aquaculture operations specify suppliers by name in feed mill agreements.
- Wholesalers:Volume aggregation for mid-tier formulators without technical service requirements, particularly in India's emerging FSSAI-aligned feed safety environment.
- Online Retail:Minimal current penetration for industrial-scale pigment procurement, though digital platforms gain traction among smallholder aquaculture cooperatives in Vietnam and Indonesia.
Direct sales holds margin leadership; distributor channel faces steepest compression from disintermediation pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese aquaculture exports to EU retail chains are accelerating astaxanthin demand across the Mekong Delta, while Chinese feed mills redirect domestic carotenoid consumption toward GB-compliant formulations ahead of SAMR enforcement deadlines.
China
Provincial feed mills in Guangdong and Shandong provinces absorb the largest carotenoid volumes for broiler skin coloration. SAMR's tightened GB standards on feed additive labeling force multinational suppliers to establish in-country analytical laboratories. Yangtze River Delta integrators now require batch lineage documentation through finished product distribution.
Vietnam
Mekong Delta shrimp producers unbundle astaxanthin sourcing from compound feed contracts to secure ASC certification for European export markets. The country's national feed safety regulator aligns with ASEAN harmonization initiatives while maintaining separate pigment registration pathways. Vertically integrated aquaculture operations in Cần Thơ specify suppliers by name in mill service agreements.
Thailand
Broiler integrators in the Central Plains region specify microencapsulated carotenoids for consistent coloration metrics satisfying domestic retail inspection protocols. The country's feed control department enforces dual registration requirements that diverge from ASEAN mutual recognition schemes. Pathum Thani feed mills optimize dosage protocols through embedded technical service relationships.
India
Poultry operations in Haryana and Telangana drive carotenoid absorption for yolk color fan scoring in premium domestic market segments. FSSAI and BIS jointly regulate maximum residue thresholds for pigment carriers, creating compliance complexity for imported formulations. Maharashtra-based feed formulators face extended market entry timelines under new safety protocols.
Indonesia
Layer operations in Java's feed mill clusters prioritize lutein inclusion for export-grade egg coloration to Singapore and Malaysian buyers. The country's national drug and food control agency maintains pigment registration requirements separate from ASEAN harmonization efforts. Surabaya-area integrators compress procurement cycles for stabilized pigment formats.
Asia-Pacific Feed Pigments Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with captive fermentation capacity and specialized ingredient houses with formulation expertise. Market structure concentrates around nature-identical carotenoid production and microencapsulation technology differentiation. Strategic archetypes include scale-driven synthetic producers, technology-anchored stabilizers, and distribution-embedded service providers. Dominant competitive moves encompass backward integration into fermentation assets and geographic expansion through direct technical service deployment.
Among diversified chemical conglomerates, BASF SE anchors the nature-identical astaxanthin segment through captive production scale, while Kemin Industries exemplifies the technology-anchored archetype via microencapsulation capabilities. Guangzhou Leader Bio-Technology Co., Ltd. occupies a position within the distribution-embedded tier, representing suppliers that leverage direct technical service teams to secure provincial feed mill relationships in southern China. Royal DSM N.V. and Synthite Industries Ltd sit within the specialty ingredient segment, with the former's Dutch corporate structure and the latter's Indian origin reflecting geographic diversification strategies among second-tier formulators.
| Leading Market Players |
|---|
| Synthite Industries Ltd |
| Royal DSM N.V. |
| BASF SE |
| Guangzhou Leader Bio-Technology Co., Ltd. |
| Behn Meyer Group |
| Kemin Industries |
| EW Nutrition (Novus International Inc.) |
| D.D. Williamson & Co. Inc. |
| Nutrex NV |
| Others |
Value Chain & Pricing Dynamics
Spirulina extract substitution for synthetic carotenoids in Vietnam's ASC-certified shrimp operations simultaneously redraws procurement geography toward domestic algae cultivation and compresses price premiums that chemical conglomerates once commanded for nature-identical astaxanthin.
Pricing Analysis
Microencapsulated pigment formats command substantial premiums over unprotected commodity carotenoids due to guaranteed bioavailability through tropical processing conditions. Pricing stratifies across premium, standard, and economy tiers based on certification grade and embedded technical service intensity. Cost compression in the commodity tier intensifies as broiler integrators consolidate procurement volumes and demand dosage optimization support. Mid-tier feed formulators exhibit highest price sensitivity, while export-oriented aquaculture operations absorb premium positioning for ASC and BAP compliance.
Supply Chain Analysis
Inventory lead times for heat-sensitive natural extracts have extended as cold-chain infrastructure gaps force regional distributors into climate-controlled logistics investments. Captive fermentation capacity concentrates in China, Germany, and the Netherlands, while Southeast Asian feed mills draw from distributed blending operations. Raw material dependencies center on petrochemical precursors for synthetic carotenoids, microalgae biomass for spirulina, and beetroot cultivation for betalain pigments. Single-source vulnerability pervades nature-identical astaxanthin production. Distribution runs through direct technical service teams for premium formulations and legacy trading houses for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical formulation capabilities now outrank price positioning as the scarcest competitive asset, with embedded analytical chemists and registration specialists commanding premium compensation across the Asia-Pacific feed pigment value chain.
For Market Incumbents: Compound defensive moats through backward integration into fermentation assets and captive supply of nature-identical carotenoids that mid-tier competitors cannot replicate. BASF SE's production scale and Kemin Industries' microencapsulation IP exemplify barriers that trading-house distributors cannot breach. Prioritize in-country analytical laboratory deployment ahead of SAMR enforcement deadlines to secure GB standards compliance for multinational formulations. For New Entrants and Emerging Players: FSSAI-aligned feed safety certification fast-tracks create viable entry pathways into India's underpenetrated Haryana and Telangana poultry belts where incumbent technical service coverage remains thin. Target India's emerging FSSAI environment before BIS residue threshold harmonization consolidates supplier relationships. Deploy direct technical teams to southern China's provincial feed mills where dosage protocol optimization determines procurement decisions. For Investors and Strategic Acquirers: The market sits at a regulatory compression phase that favors technology-anchored stabilizers with microencapsulation IP and established GB registration dossiers. Long-term viability hinges on formulation science displacement of commodity trading as the primary value-creation mechanism. Monitor ASEAN harmonization initiative divergence from national registration pathways as the critical inflection signal for supplier access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Assets | Captive astaxanthin production secures supply continuity against chemical conglomerate concentration. |
| Microencapsulation Technology Licensing | Sub-micron protective shell structures guarantee bioavailability through tropical humidity conditions. |
| In-Country Analytical Laboratory Deployment | SAMR GB standards compliance accelerates registration timelines for imported pigment carriers. |
| Direct Technical Service Team Expansion | Embedded dosage optimization creates defensible relationships against trading-house competitors. |
| ASC Certification Alignment Program | Vietnam's Mekong Delta shrimp producers unbundle sourcing for European export market access. |
Study Parameters
Operator-level perspectives from feed mill procurement managers, aquaculture integration specialists, regulatory affairs leads at pigment houses, and technical service directors anchored the qualitative base. These primary interviews combined with secondary validation from SAMR GB standard filings, FSSAI feed safety notifications, ASEAN harmonization documentation, and customs trade flow records. Bottom-up volume modeling across product type, end user, and application segments triangulated against top-down market sizing from chemical industry federation reports.
Sensitivity analysis tested forecast robustness across regulatory enforcement intensity scenarios and substitution elasticity parameters for spirulina versus synthetic carotenoids. The analytical framework segmented by product class, species application, and distribution channel complexity across the projection horizon. CAGRs derived from weighted average growth contributions across modeled segments, incorporating pigment dosing rate trajectories in Vietnam's Mekong Delta aquaculture belt and compliance-driven reformulation timelines in China's provincial feed mill clusters.
Decision-makers should treat outputs as directional under sustained ASEAN regulatory divergence and stable EU Green Deal enforcement; material deviation in harmonization timelines or certification adoption rates would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Asia-Pacific Pigments Market
Dyes and Pigments
Global Paint Pigments Market
Dyes and Pigments
Metal Complex Dyes Market
Dyes and Pigments
Polymer Colorant Market
Dyes and Pigments
Global Architectural Paint Oxide Market
Dyes and Pigments
Phthalocyanine Pigments Market
Dyes and Pigments
High Performance Pigments Market
Dyes and Pigments
Global Paper Dyes Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Light Interference Pigments Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Laser Sensitive Pigments Market
Dyes and Pigments
Ultramarine Pigments Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
Azo Pigments Market