
 OTC Health Products Market | 2026-2036
OTC Health Products Market Size, Share, and Industry Trends Forecast 2026-2036
OTC Health Products Market Insights
The FDA OTC monograph reform is consolidating the cost-of-entry calculus for new market participants. Haleon leverages its heritage brand portfolio to sustain shelf dominance across multiple retail formats. Bayer anchors its position through deep manufacturing scale in analgesics and gastrointestinal categories. Kenvue competes aggressively in the personal health space with differentiated pediatric and dermatological offerings.
OTC health products comprise non-prescription pharmaceuticals, dietary supplements, and medical devices regulated for self-diagnosis and self-treatment, typically formulated as tablets, capsules, liquids, or gummies with defined active ingredient concentrations and stability profiles. These products serve commercial purposes by reducing healthcare system burden while enabling consumers to manage acute symptoms and chronic conditions without physician intervention. Pain relievers occupy the largest revenue pool due to universal symptom prevalence and repeat purchase frequency, while gummy formulations represent the fastest-growing segment as palatability drives compliance among children and elderly end users. Online retailers are capturing disproportionate growth by bypassing traditional pharmacy margin structures and enabling direct-to-consumer subscription models.
FDA monograph compliance, EPA good manufacturing practice audits, and ISO 13485 certification for device-drug combinations collectively determine which manufacturers can access the US market and at what compliance cost. The EU MDR and REACH frameworks impose parallel substantiation requirements for any European market entry, forcing dual-track regulatory investment. Stakeholders must monitor how pharmacovigilance data requirements evolve under revised monograph systems and decide whether to absorb compliance costs internally or exit marginal SKU positions.
Market Dynamics
The FDA OTC monograph reform is consolidating manufacturing compliance burdens while retail pharmacy chains expand self-care aisles, creating a bifurcation between scaled incumbents and capital-constrained entrants.
Growth Catalysts
- Monograph Reform Acceleration:The FDA's ongoing OTC monograph modernization is streamlining safety substantiation pathways, reducing time-to-market for compliant manufacturers while raising barriers for marginal producers.
- Aging Demographics:United States population aging is amplifying chronic condition self-management, driving repeat purchase frequency in analgesics and gastrointestinal categories without physician gatekeeping.
- Gummy Formulation Technology:Palatability-driven delivery systems are expanding compliance among pediatric and elderly cohorts, capturing share from traditional tablet and liquid formats.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient sourcing concentrates in China and India, exposing formulators to geopolitical disruption and customs inspection volatility.
- Dual-Track Regulatory Burden:Simultaneous FDA monograph compliance and EU MDR substantiation requirements force redundant clinical investment for cross-Atlantic market access.
- Private Label Substitution:Retail pharmacy chains are accelerating store-brand analgesic and cough-cold launches, compressing branded margin structures at shelf.
Strategic Opportunities
- Subscription Direct-to-Consumer:Online retailers are bypassing traditional pharmacy margin structures with automated replenishment models for chronic condition management products.
- Pediatric Dermatology White Space:Underpenetrated eczema and sunscreen segments targeting infant and toddler demographics offer formulation differentiation with premium pricing headroom.
- Device-Drug Combination Convergence:ISO 13485-certified manufacturers are integrating diagnostic wearables with topical delivery systems for condition monitoring and treatment adherence.
Industry Challenges
- Pharmacovigilance Data Infrastructure:Revised FDA monograph systems mandate real-world adverse event tracking, forcing legacy IT system overhauls and specialized hiring.
- Stability Testing Bottlenecks:Accelerated shelf-life validation for novel delivery formats strains contract laboratory capacity, extending launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OTC Health Products Market |
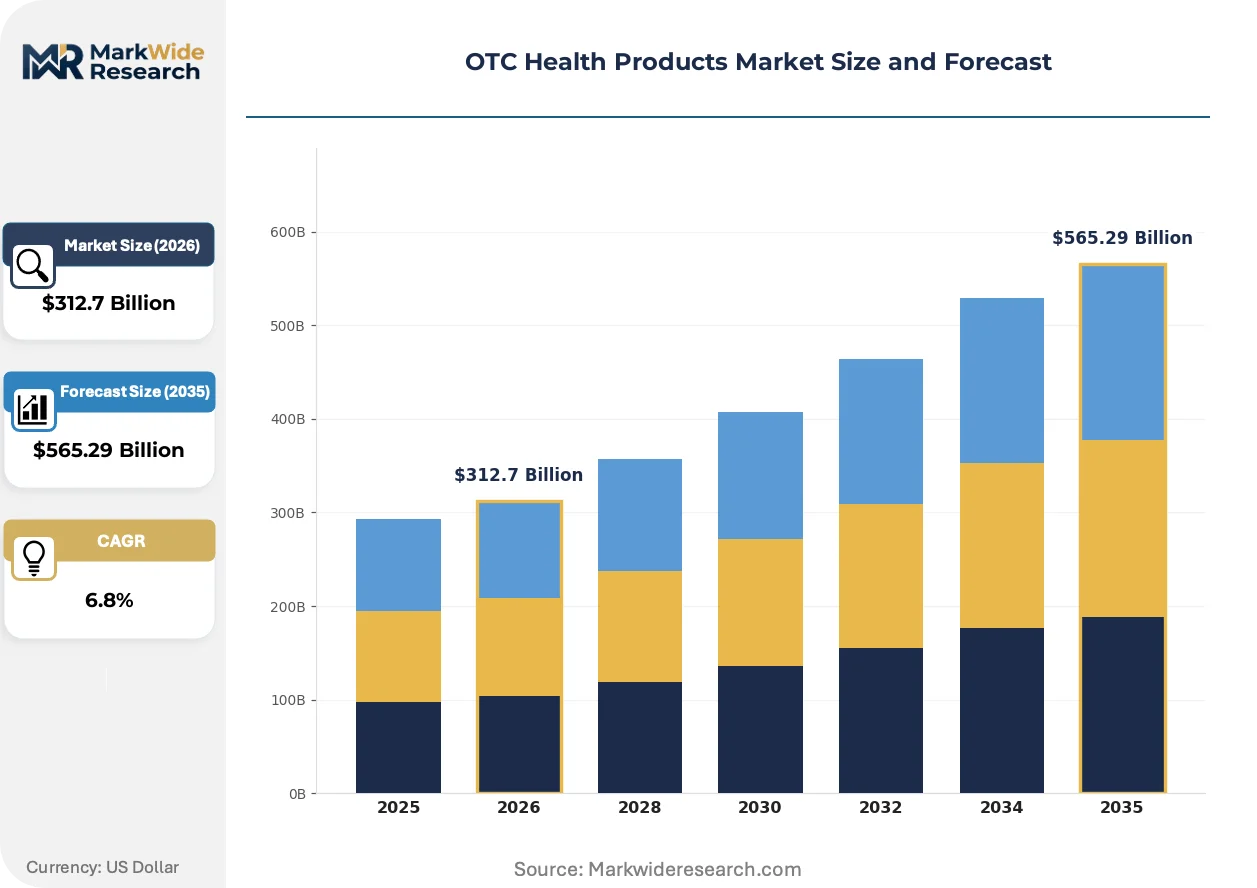
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pain Relievers, Cough Remedies, Digestive Aids, Allergy Medications Formulation: Tablets, Capsules, Liquids, Gummies Distribution Channel: Pharmacies, Supermarkets, Online Retailers, Health Stores End User: Adults, Children, Elderly, Caregivers |
| Companies Covered | Haleon, Kenvue, Bayer, Procter & Gamble, Johnson & Johnson, Reckitt, GlaxoSmithKline, Pfizer, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OTC Health Products Market Trends and Innovations
Formulation science and channel architecture are converging to redefine how consumers access self-treatment options, with palatability and convenience displacing traditional efficacy-only positioning.
Microencapsulation technology is expanding into controlled-release analgesic and gastrointestinal products, enabling 12-hour efficacy claims from single-dose formats. Pediatric and elderly caregivers are adopting these formats at twice the rate of standard immediate-release alternatives. The technology is expanding into subscription-based chronic pain management bundles that bypass retail pharmacy shelf competition entirely.
REACH framework amendments on chemical substance authorization are forcing reformulation of preservative systems across topical OTC categories. European manufacturers face supply chain requalification costs that favor scaled producers with dedicated regulatory affairs teams. The United States market is responding with preemptive FDA monograph alignment to maintain export eligibility.
Consumers are consolidating purchase decisions through pharmacy mobile applications that integrate symptom checkers with automated product recommendations. Independent community pharmacies are losing traffic to chain-owned digital platforms that bundle OTC with prescription fulfillment. This behavioral shift concentrates most visibly in United States suburban markets where insurance cost-shifting has already trained consumers toward self-directed health management.
OTC Health Products Market Segmentation
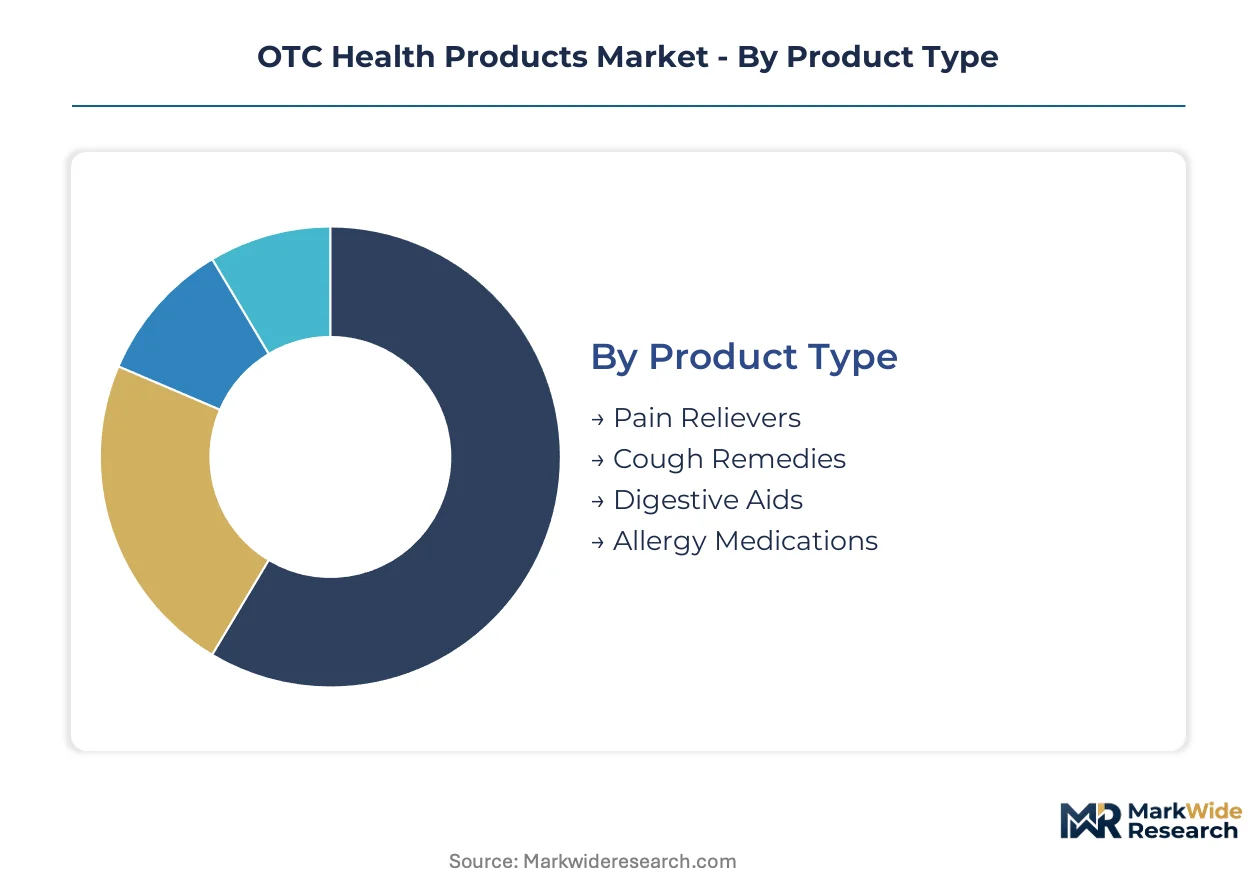
OTC health product manufacturers allocate capital unevenly across segment boundaries, with formulation technology and channel infrastructure demanding the heaviest upfront investment. Segmentation choices directly determine regulatory compliance burdens, manufacturing scale requirements, and margin capture potential.
Product Type:
Pain relievers command the steepest capital commitments due to API synthesis scale, stability testing infrastructure, and FDA monograph documentation requirements.
- Pain Relievers:Non-prescription analgesics incorporating acetaminophen, ibuprofen, or naproxen sodium at standardized concentrations. United States retail pharmacy chains concentrate demand through high-velocity shelf placement driven by insurance cost-shifting and repeat purchase behavior.
- Cough Remedies:Expectorant and suppressant formulations containing dextromethorphan, guaifenesin, or menthol actives. Seasonal demand spikes in suburban United States markets strain contract manufacturing capacity during influenza cycles.
- Digestive Aids:Antacid, laxative, and anti-diarrheal formulations with aluminum, magnesium, or bismuth compounds.
- Allergy Medications:Second-generation antihistamines and intranasal corticosteroids for seasonal rhinitis self-treatment.
Pain relievers absorb the bulk of installed capacity; allergy medications are expanding most quickly.
Formulation:
Delivery format selection determines equipment amortization schedules, with gummy production lines requiring specialized deposition and coating systems.
- Tablets:Compressed powder matrices with defined dissolution profiles and enteric coatings for gastric protection. United States manufacturing facilities concentrate tablet press capacity due to FDA inspection density and labor qualification requirements.
- Gummies:Gelatin or pectin-based matrices with microencapsulated actives for pediatric and elderly compliance. Online retailers capture disproportionate growth through subscription replenishment models bypassing traditional pharmacy margins.
- Capsules:Hard gelatin or HPMC shells enclosing powder or liquid fills for taste masking.
- Liquids:Aqueous or alcohol-based suspensions with calibrated dosing devices for infant and geriatric administration.
Tablets retain the largest installed equipment base; gummies climb the fastest on palatability-driven substitution.
Distribution Channel:
Channel selection dictates working capital intensity, with online fulfillment requiring inventory positioning against pharmacy chains' consignment arrangements.
- Pharmacies:Brick-and-mortar retail chains and independent dispensaries with licensed pharmacist oversight. United States suburban markets concentrate traffic where insurance cost-shifting has trained consumers toward self-directed symptom management.
- Online Retailers:Direct-to-consumer platforms and marketplace aggregators with automated replenishment algorithms. FDA monograph compliance documentation enables cross-border shipping eligibility to European markets under parallel REACH substance notifications.
- Supermarkets:Mass merchandisers with expanded self-care aisles and private label substitution pressure.
- Health Stores:Specialty retailers emphasizing natural positioning and practitioner recommendation channels.
Pharmacies dominate current throughput; online retailers gain share fastest on subscription model adoption.
End User:
Target demographic determines formulation complexity, with pediatric and elderly segments demanding specialized stability and palatability investment.
- Adults:Working-age consumers managing acute symptoms and chronic condition self-treatment without physician gatekeeping. United States demand concentrates in analgesic and gastrointestinal categories driven by workforce productivity pressure.
- Elderly:Aging consumers with polypharmacy considerations and swallowing difficulty requiring modified-release or alternative delivery formats. Gummy and liquid formulations capture preference due to compliance advantages over traditional tablets.
- Children:Pediatric populations requiring weight-calibrated dosing and palatability-optimized delivery systems.
- Caregivers:Proxy purchasers managing medication administration for dependent children or aging parents.
Adults represent the largest addressable population; elderly end users show the steepest expansion trajectory on demographic aging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-designated pharmaceutical industrial zones in China and India concentrate bulk active ingredient manufacturing, while FDA-registered facilities in the United States and Germany dominate finished-dosage form production.
United States
Insurance cost-shifting and aging suburban demographics drive repeat purchases of analgesics and gastrointestinal products. FDA monograph reform mandates real-world pharmacovigilance tracking, raising compliance costs for marginal producers. New Jersey and Pennsylvania host dense clusters of FDA-inspected tablet and liquid manufacturing facilities serving domestic retail pharmacy chains.
Germany
REACH framework amendments on chemical substance authorization force preservative system reformulations across topical categories. BfArM and EMA parallel oversight requires dual-track documentation for cross-border European distribution. The Rhine-Main and Bavarian industrial corridors concentrate ISO 13485-certified device-drug combination manufacturing for export markets.
China
NMPA Good Manufacturing Practice certification upgrades and dual carbon goals reshape production economics for acetaminophen and ibuprofen API synthesis. Zhejiang and Jiangsu provinces concentrate chemical intermediate production, with Shandong emerging as a hub for gummy formulation technology serving pediatric export demand.
India
CDSCO manufacturing license harmonization with WHO prequalification standards opens access to African and Southeast Asian markets. Gujarat and Maharashtra states dominate contract research and manufacturing organization capacity for generic OTC analgesics, with Hyderabad emerging as a center for stability testing infrastructure.
Japan
PMDA reclassification of certain quasi-drugs to full OTC status expands self-treatment categories for aging consumers. METI subsidies for continuous manufacturing technology adoption reduce batch-to-batch variability in analgesic production. The Kansai corridor around Osaka maintains concentration of traditional Kampo formulation expertise alongside modern dosage form capabilities.
OTC Health Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation technology and channel access vectors. The market structure tiers between scaled incumbents with captive regulatory affairs infrastructure and capital-constrained entrants facing monograph compliance barriers. Three archetypes dominate: heritage consumer health spin-offs with deep retail relationships, pharmaceutical majors leveraging API backward integration, and device-drug combination specialists with ISO certification advantages. Competitive moves concentrate on portfolio rationalization to absorb compliance costs and direct-to-consumer subscription channel development.
Within the heritage consumer health tier, Haleon and Kenvue exemplify archetypes built on brand equity and retail pharmacy shelf dominance. Bayer occupies a position representing pharmaceutical-origin players with manufacturing scale in core analgesic categories. These three entities anchor the competitive structure through differentiated approaches to regulatory compliance absorption and channel architecture investment.
| Leading Market Players |
|---|
| Haleon |
| Kenvue |
| Bayer |
| Procter & Gamble |
| Johnson & Johnson |
| Reckitt |
| GlaxoSmithKline |
| Pfizer |
| Sanofi |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FDA monograph-compliant and marginal producers manifests in both pricing premiums and supply chain redundancy investments. Premium-tier manufacturers absorb pharmacovigilance infrastructure costs to maintain retail pharmacy shelf access, while commodity players face margin compression from private label substitution and API sourcing volatility.
Pricing Analysis
Lead-time-driven pricing stratification rewards manufacturers with domestic FDA-registered facilities and validated stability data. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, brand heritage, and geographic delivery reliability. Pricing pressure stems from retail pharmacy chains accelerating store-brand launches in analgesic and cough-cold categories. Hospital procurement committees show lowest price sensitivity for pediatric dermatology formulations; mass-market adult analgesic buyers exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in New Jersey and Pennsylvania anchor hub-and-spoke patterns serving domestic retail pharmacy chains. Active pharmaceutical ingredient synthesis concentrates in China and India, with acetaminophen and ibuprofen intermediates drawing from Zhejiang and Gujarat industrial corridors. Single-source vulnerability in gelatin and pectin supply for gummy formulations exposes formulators to agricultural commodity volatility. Distribution runs through chain-owned consignment arrangements at retail and direct-to-consumer subscription fulfillment for online channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation technology is displacing immediate-release legacy formats across analgesic and gastrointestinal categories, compressing launch timelines for manufacturers lacking controlled-release expertise.
For Market Incumbents: Deploy pharmacovigilance data infrastructure as a defensive moat against private label substitution and regulatory scrutiny. Absorb FDA monograph compliance costs through portfolio rationalization, exiting marginal SKUs with insufficient volume to justify real-world adverse event tracking investments. Backward integration into API synthesis reduces exposure to China-India customs inspection volatility. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable route for capital-constrained entrants lacking retail pharmacy chain relationships. Target pediatric dermatology white space in eczema and sunscreen segments where formulation differentiation commands premium pricing. Leverage ISO 13485 certification for device-drug combination convergence opportunities in diagnostic-integrated delivery systems. For Investors and Strategic Acquirers: Re-rating potential sits with heritage consumer health spin-offs possessing captive regulatory affairs infrastructure and deep retail shelf relationships given FDA monograph reform acceleration. Long-term viability favors scaled incumbents with diversified geographic manufacturing footprints and subscription channel development capabilities. Watch pharmacovigilance data infrastructure buildout pace as inflection indicator for compliance cost absorption capacity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Monograph Compliance Investment | Real-world adverse event tracking infrastructure secures retail pharmacy shelf access against private label encroachment. |
| Gummy Formulation Technology Scale-Up | Specialized deposition and coating systems capture pediatric and elderly compliance-driven substitution from tablets. |
| Direct-to-Consumer Subscription Launch | Automated replenishment algorithms bypass traditional pharmacy margin structures for chronic condition management. |
| API Backward Integration | Captive acetaminophen and ibuprofen synthesis reduces geopolitical disruption exposure from China-India concentration. |
| Pediatric Dermatology Portfolio Extension | Eczema and sunscreen formulations targeting infant demographics exploit underpenetrated segments with premium pricing headroom. |
Research Methodology
Document review covered FDA monograph filings, EMA substance authorization databases, and retail pharmacy chain annual reports, complemented by interviews with regulatory affairs directors, contract manufacturing executives, and hospital procurement managers. Secondary validation drew from pharmacovigilance data repositories, customs trade records, and GPO contract databases. Bottom-up SKU-level volume builds triangulated against top-down category spending estimates from healthcare expenditure tracking.
Cross-reference between historical FDA approval timelines and expert panel input on monograph reform implementation shaped the analytical framework. Segmentation dimensions modeled include product type, formulation technology, distribution channel, and end-user demographic across the analysis window. CAGRs derived from fitted growth curves applied to normalized baseline data, with inputs from aging demographic projections and insurance cost-shifting patterns in United States suburban markets.
The model holds under stable FDA monograph implementation pacing and continued retail pharmacy chain self-care aisle expansion; deviation in API trade policy or REACH framework enforcement stringency would shift volume and value trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
PTBCHA Market
Personal Health
Biohacking Market
Personal Health
Patient Health Management Market
Personal Health
Menstrual Cup Market
Personal Health
Obesity Treatment Market
Personal Health
Global Health and Wellness Market
Personal Health
Interdental Brush Market
Personal Health
Parents-In-Waiting: Global Prenatal Market
Personal Health
Asia-Pacific Maternity & Personal Care Market
Personal Health
Menopause Wellness Market
Personal Health
Blackhead Removing Vacuum Market
Personal Health
Tongue Scraper Market
Personal Health
Corporate Wellness Market
Personal Health
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market
Personal Health
Sleeping Aids Market
Personal Health
North America Hair Loss Treatment Products Market