
 Sleeping Aids Market | 2026-2036
Sleeping Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Sleeping Aids Market Outlook
Subscription-based digital sleep coaching and app-integrated wearable monitoring is recalibrating what consumers purchase as a complete sleep solution rather than isolated pills or devices. Merck & Co., Inc. leverages its pharmaceutical pipeline depth to sustain prescription hypnotic leadership. Koninklijke Philips N.V. anchors the connected sleep device segment through hardware-software integration. Jazz Pharmaceuticals differentiates via narcolepsy and sleep disorder specialty therapeutics.
Sleeping aids encompass pharmacological agents, botanical formulations, and electronic devices engineered to reduce sleep latency, extend sleep duration, or improve sleep architecture, with melatonin receptor agonists typically targeting MT1/MT2 receptors and CPAP devices maintaining positive airway pressure between 4-20 cm H2O. Tablets and capsules retain the largest revenue footprint within product type segmentation due to established reimbursement pathways and physician familiarity. Gummies and sprays within delivery mode segmentation capture faster growth as younger demographics reject pill-form consumption. Prescription drugs under ingredient type segmentation command premium pricing, while natural ingredients expand through direct-to-consumer channels with lighter regulatory burden.
FDA oversees prescription hypnotic approvals and boxed warning requirements in the United States, while EMA harmonizes somnolence-related risk assessments across European member states, and Japan's PMDA maintains distinct pharmacovigilance reporting for sleep medications. These frameworks elevate clinical trial costs but create defensible moats for compliant manufacturers. Stakeholders must weigh biosimilar erosion against device-as-a-service recurring revenue models when allocating capital across the sleep health value chain.
Market Dynamics
FDA's boxed warning expansion for sedative-hypnotics is forcing pharmaceutical developers toward receptor-selective agonists with cleaner safety profiles, while subscription-based digital sleep platforms are modularizing what consumers purchase as complete solutions.
Growth Catalysts
- Japan's PMDA pharmacovigilance framework:Stringent adverse event reporting requirements for sleep medications elevate clinical trial standards, creating defensible barriers for compliant manufacturers against biosimilar erosion.
- Geriatric long-term care facilities:Aging populations in institutional settings generate sustained demand for non-pharmacological interventions and connected monitoring devices.
- Melatonin receptor agonist pipelines:MT1/MT2-selective compounds reduce next-day impairment compared to GABA-A modulators, attracting physician preference shifts in prescription hypnotics.
Market Restraints
- EMA somnolence risk harmonization:Cross-border safety labeling requirements extend approval timelines and inflate clinical development costs for European market entry.
- Active pharmaceutical ingredient concentration:Manufacturing of zolpidem, eszopiclone, and zaleplon concentrates in limited facilities, exposing supply chains to single-source vulnerabilities.
- Device reimbursement fragmentation:CPAP and connected sleep hardware face inconsistent coverage determination across private and public payers, compressing adoption velocity.
Strategic Opportunities
- Gummy and spray delivery formats:Direct-to-consumer channels with lighter regulatory burden capture younger demographics rejecting traditional pill-form consumption.
- Hardware-software integration:Wearable sleep staging combined with AI-driven coaching creates recurring revenue models distinct from one-time device sales.
- Germany's DiGA fast-track pathway:Digital health applications for insomnia qualify for statutory insurance reimbursement, accelerating market access for app-based interventions.
Industry Challenges
- Sleep medicine specialist scarcity:Board-certified somnologists remain concentrated in academic medical centers, limiting diagnostic capacity for complex sleep disorder cases.
- Legacy EHR integration:Connected sleep devices struggle with interoperability standards across hospital systems and long-term care facility networks.
- CE marking under MDR:Reclassification of sleep apnea devices under stricter medical device regulations extends conformity assessment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleeping Aids Market |
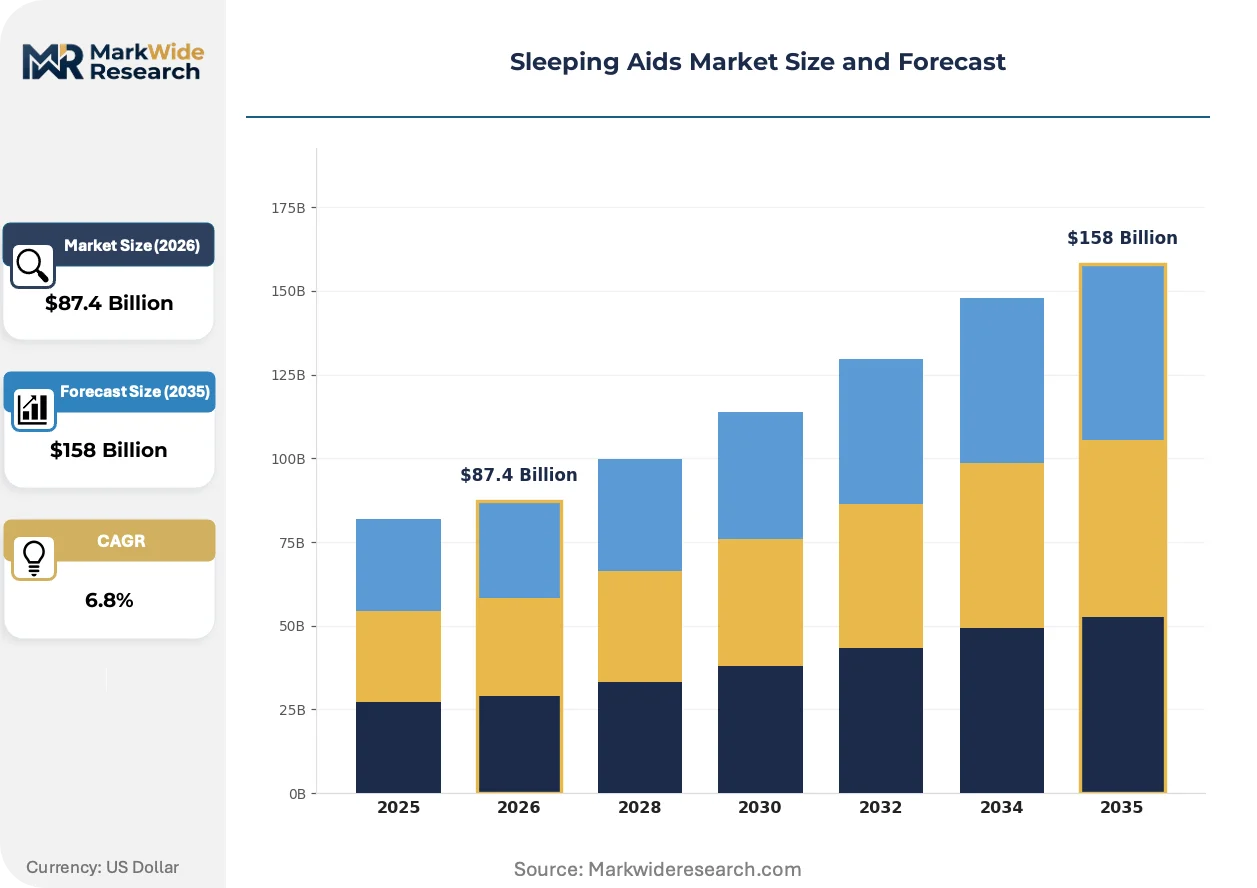
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Melatonin, Herbal Supplements Delivery Mode: Oral, Sublingual, Gummies, Sprays Target Audience: Adults, Seniors, Children, Shift Workers Ingredient Type: Prescription Drugs, OTC Products, Natural Ingredients, Others |
| Companies Covered | Merck & Co., Inc, Pfizer Inc., Sanofi S.A., GSK plc, Teva Pharmaceutical Industries Ltd., Koninklijke Philips N.V., ResMed Inc., Jazz Pharmaceuticals, Eisai Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleeping Aids Market Strategic Shifts
Digital sleep health platforms are fragmenting the traditional pharmaceutical-device boundary, with consumers assembling personalized solutions from modular components rather than accepting standardized care protocols.
Closed-loop CPAP systems with auto-titrating algorithms are modularizing therapeutic delivery. Sleep clinics and home medical equipment providers are adopting these adaptive pressure devices at accelerating rates. The technology is modularizing the traditional sleep study-to-treatment pathway, compressing diagnostic-to-therapy intervals from weeks to days.
REACH restrictions on persistent organic pollutants are reshaping polymer selection for device housings and tubing. Manufacturers face reformulation costs for polycarbonate alternatives in mask assemblies. European device producers are responding with bio-based thermoplastic elastomers to maintain market access under evolving chemical safety frameworks.
Subscription bundling of coaching, wearables, and supplements is displacing single-product purchases. Direct-to-consumer brands capture sleep hygiene education and behavioral intervention spend previously directed toward physician consultations. This pattern concentrates in United States metropolitan markets with high digital health literacy and flexible health savings account utilization.
Sleeping Aids Market Segmentation
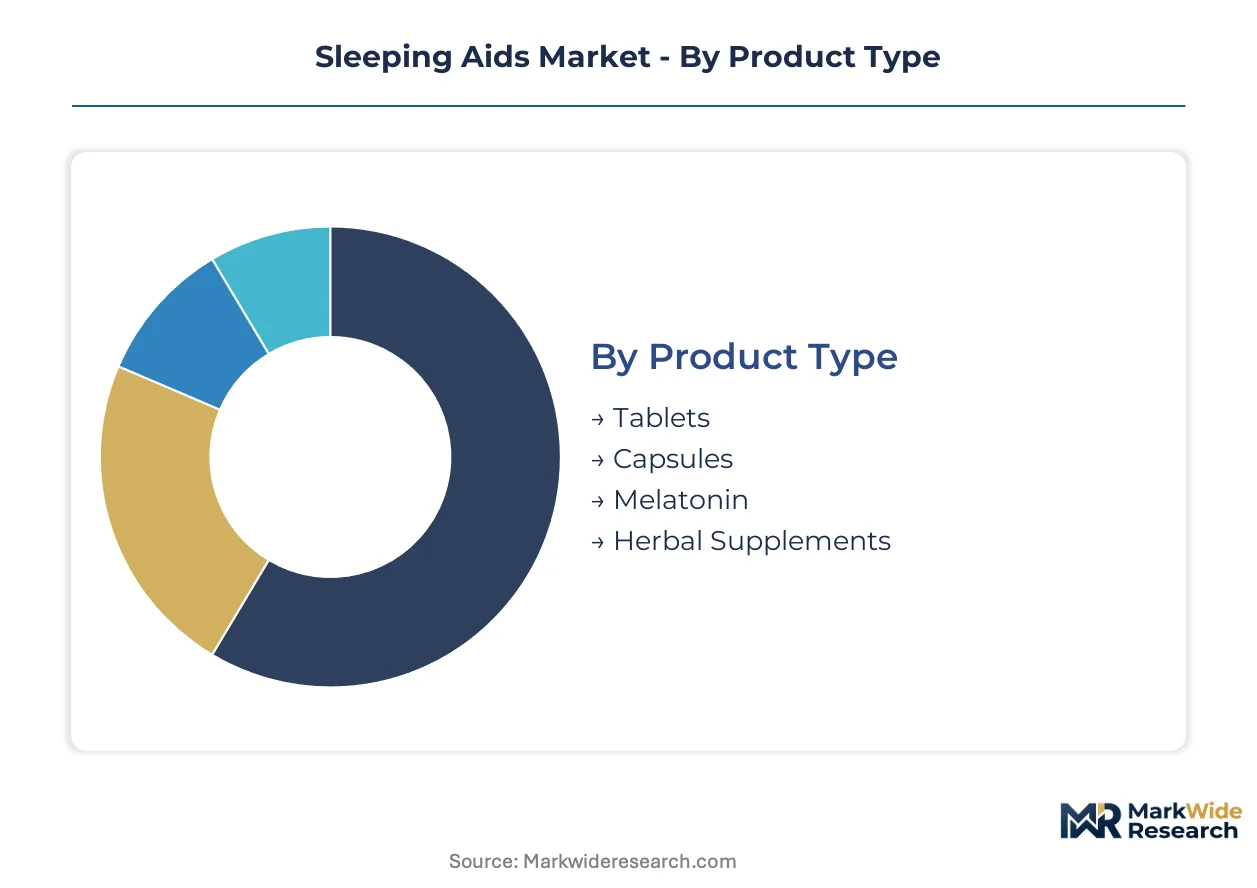
Sleeping aids fragment across pharmacological, botanical, and device-based modalities, each carrying distinct regulatory pathways and reimbursement profiles. Manufacturers must align formulation chemistry with delivery technology to capture specific patient compliance patterns and prescriber preferences.
Product Type:
Tablet dissolution rates and capsule shell composition determine bioavailability windows and manufacturing cost structures across this category.
- Tablets:Compressed formulations with established dissolution profiles dominate institutional procurement through long-term care facilities. United States geriatric populations in nursing homes generate sustained volume through Medicare Part D reimbursement channels.
- Capsules:Gelatin or hypromellose shells enable modified-release kinetics and combination therapies. German statutory health insurance funds favor capsule formulations for their dosing flexibility in polypharmacy scenarios.
- Melatonin:Synthetic pineal hormone analogs target circadian rhythm disorders with minimal next-day impairment.
- Herbal Supplements:Valerian root and passionflower extracts occupy direct-to-consumer channels with lighter regulatory scrutiny.
Tablets lead on scale; melatonin leads on momentum.
Delivery Mode:
Absorption kinetics and patient compliance thresholds vary sharply across mucosal versus gastrointestinal administration routes.
- Oral:Swallowed tablets and capsules retain the deepest physician familiarity and pharmacy distribution infrastructure. Japan's PMDA maintains streamlined approval pathways for conventional oral hypnotics.
- Sublingual:Rapid buccal absorption bypasses first-pass hepatic metabolism for faster sleep onset. United States shift workers in transportation sectors drive demand for sublingual zolpidem variants.
- Gummies:Gelatin-based chewables reduce pill anxiety among younger demographics.
- Sprays:Metered-dose nasal or oral mist formulations enable precise titration.
Oral administration leads on scale; gummies lead on momentum.
Target Audience:
Age-related pharmacokinetic changes and occupational sleep disruption patterns dictate formulation potency and timing specifications.
- Adults:Working-age populations with primary insomnia drive prescription hypnotic volumes through employer-sponsored health plans. United States metropolitan markets with high deductible health plans show preference for OTC alternatives.
- Seniors:Heightened sensitivity to anticholinergic effects and fall risks necessitates lower-dose regimens. German long-term care facilities prioritize non-pharmacological interventions before pharmacological escalation.
- Children:Pediatric sleep disorders require specialized formulations with limited approved options.
- Shift Workers:Circadian misalignment from rotating schedules demands timing-specific interventions.
Adults lead on scale; shift workers lead on momentum.
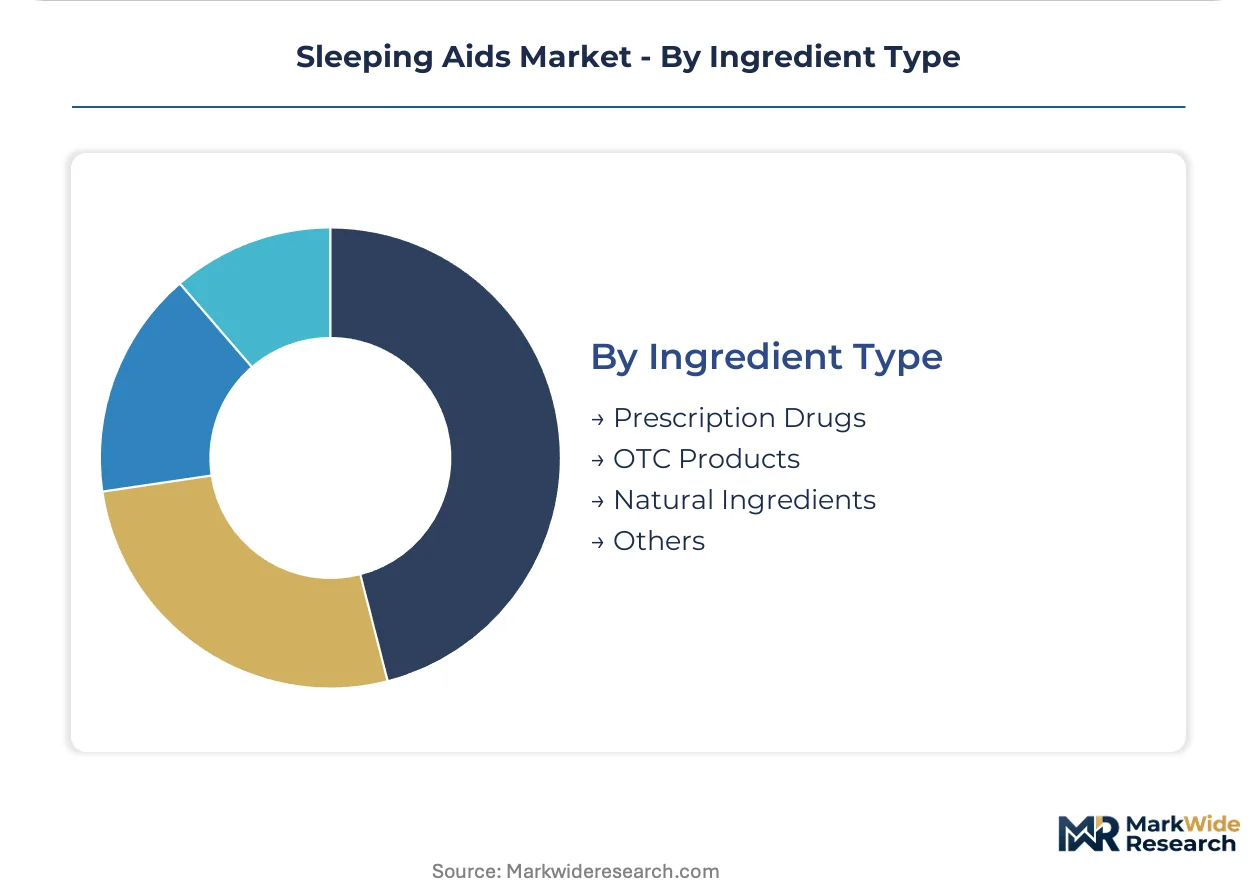
Ingredient Type:
Regulatory classification determines clinical trial investment, marketing authorization scope, and distribution channel access.
- Prescription Drugs:GABA-A modulators and orexin antagonists require FDA boxed warnings and controlled substance scheduling. United States sleep medicine specialists concentrate prescribing authority for these agents.
- OTC Products:Diphenhydramine and doxylamine formulations face fewer distribution restrictions. German pharmacy-only status elevates professional consultation requirements compared to United States mass retail availability.
- Natural Ingredients:Melatonin, L-theanine, and magnesium compounds occupy supplement regulatory categories.
- Others:Homeopathic preparations and traditional medicine formulations occupy niche distribution.
Prescription drugs lead on scale; natural ingredients lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates higher prescription hypnotic volumes than Germany, yet Japan's PMDA pharmacovigilance framework elevates clinical trial standards that German manufacturers increasingly emulate for European market entry.
United States
Medicare Part D reimbursement channels sustain tablet demand through nursing home procurement. FDA boxed warning requirements for sedative-hypnotics force developers toward receptor-selective agonists. Boston's medical technology corridor concentrates digital sleep platform startups integrating wearable hardware with coaching subscriptions.
Germany
Statutory health insurance funds favor capsule formulations for polypharmacy flexibility in aging populations. EMA somnolence risk harmonization extends approval timelines for hypnotic developers. Bavaria's medical device manufacturing belt advances closed-loop CPAP systems with auto-titrating algorithms for home care deployment.
Japan
Shift workers in transportation sectors drive sublingual zolpidem variant consumption. PMDA maintains distinct pharmacovigilance reporting requirements that elevate compliance costs for foreign entrants. Tokyo's pharmaceutical corridor anchors melatonin receptor agonist pipeline development targeting MT1/MT2 selectivity.
United Kingdom
High-deductible health plan penetration pushes working-age adults toward OTC alternatives. MHRA alignment with EMA safety labeling creates regulatory continuity post-Brexit. London's digital health cluster incubates app-based sleep coaching platforms qualifying for NHS reimbursement pilots.
India
Direct-to-consumer channels expand natural ingredient formulations through pharmacy networks. CDSCO streamlined approval pathways for conventional oral hypnotics accelerate generic market entry. Maharashtra's pharmaceutical manufacturing zone concentrates active pharmaceutical ingredient production for zolpidem and eszopiclone intermediates.
Sleeping Aids Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical developers commanding premium pricing in prescription hypnotics while device makers pursue recurring revenue through hardware-software integration. The prescription drug tier concentrates around GABA-A modulator and orexin antagonist portfolios, whereas connected sleep devices fragment across CPAP manufacturers and wearable startups. Three archetypes dominate: Big Pharma incumbents with pipeline depth, medical device conglomerates with distribution scale, and digital health insurgents with direct-to-consumer reach. M&A activity targets digital sleep platforms for pharmaceutical portfolio extension, while capacity expansion concentrates in Asia-Pacific API manufacturing.
Within the pharmaceutical archetype, Merck & Co., Inc. and Jazz Pharmaceuticals exemplify contrasting strategic positions—Merck leveraging broad pipeline resources across therapeutic categories, Jazz occupying specialty concentration in narcolepsy and sleep disorder segments. Koninklijke Philips N.V. anchors the device tier through Dutch engineering heritage and hospital system relationships, representing how industrial conglomerates modularize sleep hardware into broader respiratory care portfolios. These three companies illustrate the tripartite competitive structure: diversified pharmaceutical, specialty pharmaceutical, and integrated device-industrial.
| Leading Market Players |
|---|
| Merck & Co., Inc |
| Pfizer Inc. |
| Sanofi S.A. |
| GSK plc |
| Teva Pharmaceutical Industries Ltd. |
| Koninklijke Philips N.V. |
| ResMed Inc. |
| Jazz Pharmaceuticals |
| Eisai Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap API manufacturers in Maharashtra and Gujarat anchor zolpidem intermediate production, translating concentrated ownership into disciplined capacity expansion that resists the price erosion seen in commoditized generic segments. Their selective investment patterns preserve margin structures across prescription hypnotic tiers while limiting spot-market volatility for contract formulation buyers.
Pricing Analysis
Capacity additions in India are reshaping price floors for eszopiclone and zaleplon active pharmaceutical ingredients. Three-tier pricing structure across premium receptor-selective agonists, standard GABA-A modulators, and economy-tier diphenhydramine formulations stratifies the market. Cost compression in OTC natural ingredient segments is intensifying because direct-to-consumer brands bypass pharmacy distribution markups. Geriatric long-term care facilities exhibit highest price sensitivity due to fixed Medicare reimbursement rates, while shift-worker sublingual variants command lowest sensitivity given limited therapeutic alternatives.
Supply Chain Analysis
Domestic-content mandates in Japan's PMDA framework are reshaping sourcing patterns for foreign device manufacturers seeking market access. API production concentrates in India, China, and the United States, with melatonin synthesis anchored in Chinese fermentation facilities and zolpidem intermediates flowing from Indian chemical parks. Polycarbonate alternatives for CPAP mask housings draw from bio-based thermoplastic elastomer suppliers in Bavaria and the Netherlands. Single-source vulnerability persists for orexin antagonist precursors. Distribution runs through hospital system GPOs, long-term care facility networks, and direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sleeping aids market reads as a late-cycle quality story, with demand pivoting toward MT1/MT2-selective compounds that reduce next-day impairment and justify premium positioning over legacy GABA-A modulators.
For Market Incumbents: Anticipate biosimilar erosion in conventional hypnotic categories by accelerating receptor-selective agonist pipeline advancement and securing backward integration into melatonin analog synthesis. FDA boxed warning expansion for sedative-hypnotics threatens GABA-A modulator franchises, making certification investment in cleaner safety profiles the critical defensive lever. For New Entrants and Emerging Players: AI-driven sleep coaching platforms integrated with wearable staging hardware offer a technology-first wedge into the subscription-based digital health segment. Germany's DiGA fast-track pathway for insomnia applications represents the most penetrable regulatory entry point, with statutory insurance reimbursement reducing customer acquisition costs versus United States HSA-dependent markets. For Investors and Strategic Acquirers: Valuations sit cheapest among contract API manufacturers with captive orexin antagonist chemistry capabilities. Long-term viability centers on defensible positioning against biosimilar commoditization and device-as-a-service recurring revenue capture. Watch FDA guidance on digital therapeutics classification as the signal indicating whether hardware-software sleep platforms achieve pharmaceutical-tier pricing or face consumer-electronics margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Receptor-Selective Agonist Pipeline Advancement | MT1/MT2 selectivity reduces next-day impairment liability under FDA boxed warning expansion. |
| Hardware-Software Integration Platform | Wearable sleep staging combined with AI coaching creates recurring revenue distinct from one-time device sales. |
| DiGA Fast-Track Pathway Navigation | Germany's statutory insurance reimbursement accelerates market access for app-based insomnia interventions. |
| Backward Integration into API Synthesis | Captive melatonin analog production insulates against Indian and Chinese intermediate supply volatility. |
| Long-Term Care Facility Partnership | Medicare Part D reimbursement channels sustain tablet volume through nursing home procurement networks. |
Study Parameters
Direct dialogue with pharmaceutical development executives, regulatory affairs leads at FDA and EMA, hospital formulary directors, and sleep medicine specialists grounded qualitative insights, cross-checked against FDA filings, ClinicalTrials.gov records, PMDA pharmacovigilance reports, and Medicare Part D claims data. Bottom-up and top-down triangulation validated volume estimates across prescription hypnotic, OTC, and device-based modalities.
Bottom-up modeling aggregated patient population sizing, treatment penetration rates, and average revenue per user across product type, delivery mode, and ingredient type segments. Top-down analysis cross-referenced manufacturer revenue disclosures, GPO contract values, and statutory insurance reimbursement schedules. CAGRs derived from segment-level growth trajectory convergence throughout the forecast period, incorporating PMDA adverse event reporting trends and DiGA adoption curves as industry-specific forecast inputs.
The model holds under stable FDA-EMA regulatory convergence and continued Medicare Part D coverage for institutional hypnotic prescribing; deviation in digital therapeutics classification or orexin antagonist safety signal emergence would shift volume projections between pharmaceutical and device-based modalities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Reusable Face Mask Market
Personal Health
Sexual Wellness Market
Personal Health
Feminine Hygiene Market
Personal Health
Health Check-Up Market
Personal Health
Asia-Pacific Maternity & Personal Care Market
Personal Health
Earwax Removal Products Market
Personal Health
Foot Insole Market
Personal Health
Europe Hair Loss Treatment Products Market
Personal Health
Sleep Mask Market
Personal Health
Maternity and Personal Care Market
Personal Health
Skin Tag Remover Market
Personal Health
Corporate Wellness Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Disposable Underwear Market
Personal Health
Smoking Cessation and Nicotine De Addiction Market
Personal Health
Sextech and Sexual Wellness Market