
 Maternity Personal Care Products Market | 2026-2036
Maternity Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Maternity Personal Care Products Market Outlook
Specialty chemical producers in Germany and France is broadening output of pregnancy-safe emollients and botanical extracts for cosmetic formulators. L'Oréal leverages its dermatological research infrastructure to develop clinically tested stretch mark therapies. The Himalaya Drug Company anchors its portfolio in Ayurvedic herbals for prenatal skin care across South Asian and Middle Eastern markets. Earth Mama differentiates through USDA Organic certification and clean-label positioning in North American natural retail channels.
Maternity personal care products encompass cleansers, moisturizers, topical treatments, and lactation accessories formulated with pregnancy-compatible ingredients such as hyaluronic acid, shea butter, and colloidal oatmeal, manufactured under cosmetic good manufacturing practice standards to address epidermal elasticity loss, barrier dysfunction, and nipple trauma during gestation and postpartum recovery. Stretch mark cream commands sustained margin pools due to consumer willingness to pay for clinically substantiated claims, while online retail represents the fastest-growing distribution channel as subscription models and telehealth referrals redirect expectant mothers from brick-and-mortar pharmacy aisles. Breastfeeding pads retain stable demand through hospital discharge kit inclusion and lactation consultant recommendations.
FDA oversight of cosmetic ingredient safety under the Modernization of Cosmetics Regulation Act and ECHA REACH restrictions on endocrine-disrupting chemicals compel reformulation investments across multinational portfolios. BIS certification requirements in India and China's NMPA cosmetic registration rules create divergent compliance pathways that fragment product registration strategies. Stakeholders must monitor evolving per- and polyfluoroalkyl substance prohibitions and state-level clean beauty legislation that will redefine permissible preservative systems and fragrance compounds.
Market Dynamics
REACH compliance and the EU Green Deal are forcing wholesale reformulation of preservative systems and fragrance compounds across maternity skincare portfolios, compressing time-to-market cycles and elevating R&D spend as a percentage of revenue.
Growth Catalysts
- Urban first-time motherhood:Dense metropolitan centers in the United States, China, and Germany concentrate demand for clinically substantiated stretch mark therapies and barrier-repair formulations.
- Telehealth referral networks:Lactation consultants and maternal-fetal medicine specialists drive hospital discharge kit inclusion of breastfeeding pads and nipple care balms.
- Subscription commerce infrastructure:Automated replenishment models for prenatal vitamin and skincare bundles reduce customer acquisition costs for direct-to-consumer brands.
Market Restraints
- Botanical extract supply concentration:She butter and colloidal oatmeal sourcing clusters in West African and North American agricultural regions, exposing formulators to climate-driven harvest volatility.
- Endocrine-disruptor screening costs:ECHA REACH restrictions on phthalates and parabens require expensive toxicological dossiers for each reformulated SKU.
- Clean-label substitution ceiling:Plant-derived preservatives deliver shorter shelf stability than synthetic alternatives, constraining distribution radius for mass-market retail placement.
Strategic Opportunities
- Ayurvedic export corridors:South Asian and Middle Eastern markets underpenetrated by pregnancy-safe herbals present expansion vectors for standardized ashwagandha and gotu kola extracts.
- USDA Organic certification arbitrage:Premium positioning through third-party clean-label validation commands margin expansion in North American natural retail channels.
- Postpartum recovery verticals:Cesarean-section scar therapy and perineal repair formulations represent adjacent white space beyond traditional stretch mark SKUs.
Industry Challenges
- Cosmetic toxicologist talent scarcity:Pregnancy safety assessment expertise concentrates in European and North American contract research organizations, elongating hiring timelines for Asia-Pacific headquarters.
- Multi-jurisdiction registration fragmentation:Divergent BIS certification requirements in India and NMPA cosmetic registration rules in China force parallel compliance track investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maternity Personal Care Products Market |
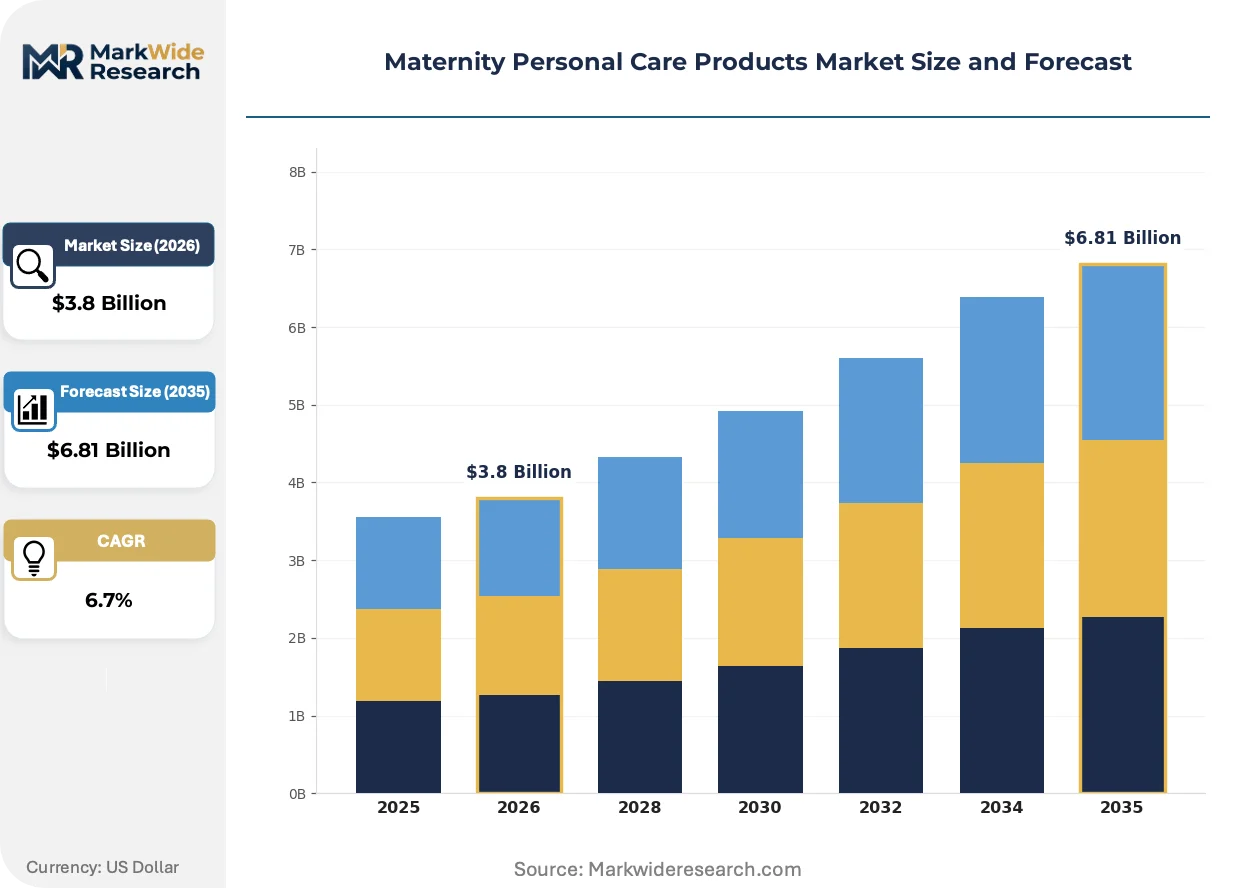
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Wash, Moisturizing Lotion, Stretch Mark Cream, Breastfeeding Pads Application: Skin Care, Bathing Products, Breast Care, Hair Care End User: Expectant Mothers, New Mothers, Healthcare Providers, Retailers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | L'Oréal, E.T. Browne Drug, The Himalaya Drug Company, Clarins Group, Mama Mio, Earth Mama, The Honest Company, Lansinoh Laboratories, Johnson's Baby, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maternity Personal Care Products Market Strategic Shifts
Biotechnology-derived alternatives to petroleum-based emollients are compressing the cost premium between clean-label and conventional formulations, while regulatory pressure on fragrance allergens accelerates transparency mandates across ingredient lists.
Biotechnology platforms producing fermentation-derived squalane and hyaluronic acid are electrifying raw material sourcing for pregnancy-safe moisturizers. Mid-tier cosmetic formulators in Germany and France are adopting these inputs at triple-digit annual volume growth. The technology is electrifying supply chain decarbonization commitments while compressing price premiums previously commanded by marine and animal-derived alternatives.
Modernization of Cosmetics Regulation Act implementation by the FDA is mandating adverse event reporting and fragrance allergen disclosure for all cosmetic manufacturers distributing in the United States. The industrial consequence is a forced upgrade of quality management systems and batch traceability infrastructure. Maternity-specific brands with limited regulatory affairs headcount face disproportionate compliance burden compared to multinational dermatological portfolios.
Subscription-based replenishment models for prenatal skincare regimens are displacing pharmacy aisle discovery as the primary customer acquisition channel. Direct-to-consumer brands bypass wholesale margin structures through telehealth partnerships and influencer-driven content ecosystems. This channel rotation is most visible in United States metropolitan markets where maternity wellness apps aggregate purchasing intent data for targeted cohort marketing.
Maternity Personal Care Products Market Segmentation
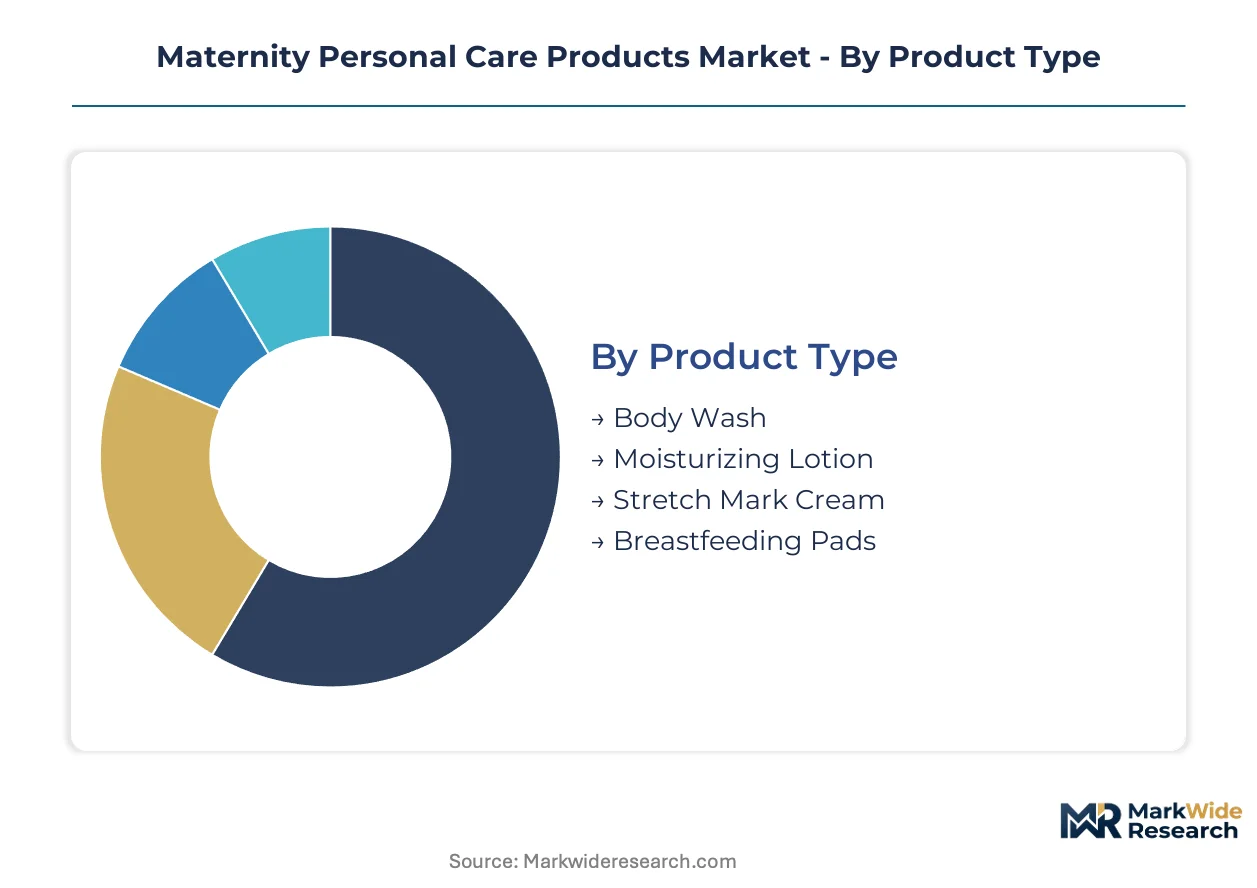
Maternity personal care purchasing patterns diverge sharply across usage occasions, with hospital discharge protocols and subscription commerce redefining how expectant mothers acquire regimen-based products. Segmentation clarity enables suppliers to align formulation investments with distinct safety, convenience, and clinical credibility requirements.
Product Type:
Upgrade cycles in maternity skincare accelerate as mothers progress from first-trimester prevention to postpartum repair, driving sequential purchases across specialized formats.
- Stretch Mark Cream:Clinically substantiated formulations containing hyaluronic acid and botanical extracts command sustained margin pools through dermatologist endorsement and hospital gift bag inclusion. Demand concentrates in urban United States and German metropolitan centers where first-time mothers prioritize evidence-based prevention over commodity alternatives.
- Moisturizing Lotion:Barrier-repair formulations with colloidal oatmeal and shea butter address epidermal elasticity loss during gestation. Volume placements cluster in mass retail channels across China and India where price sensitivity shapes procurement decisions for daily-use regimens.
- Body Wash:pH-balanced cleansers formulated without sulfates or synthetic fragrances serve pregnancy-compatible hygiene needs. Mid-tier brands in France and Germany emphasize fermentation-derived surfactants for clean-label positioning.
- Breastfeeding Pads:Disposable and reusable absorbent pads address nipple trauma and leakage during lactation. Hospital discharge kit inclusion and lactation consultant recommendations sustain stable demand through institutional procurement channels.
Volume placements concentrate in Moisturizing Lotion; the faster expansion belongs to Stretch Mark Cream.
Application:
Cost tier stratification separates premium clinical formats from mass-market daily care, with reimbursement eligibility and professional recommendation determining price realization.
- Skin Care:Stretch mark prevention, barrier repair, and hyperpigmentation treatment dominate R&D investment across multinational portfolios. FDA Modernization of Cosmetics Regulation Act compliance costs disproportionately burden maternity-specific brands with limited regulatory affairs infrastructure.
- Breast Care:Nipple balms, soothing gels, and lactation support accessories address trauma recovery and milk expression comfort. Telehealth referral networks in United States metropolitan markets drive subscription-based replenishment models for this application.
- Bathing Products:Gentle cleansers and bath soaks formulated for pregnancy-sensitive skin compete on ingredient transparency and fragrance-free positioning. ECHA REACH restrictions on endocrine-disrupting chemicals compel reformulation investments across European portfolios.
- Hair Care:Shampoos and conditioners addressing gestational hair thinning and scalp sensitivity represent emerging white space with limited specialized competition. Ayurvedic herbals from The Himalaya Drug Company anchor penetration in South Asian markets.
Revenue concentrates in Skin Care; Breast Care gains share fastest through institutional channel expansion.
End User:
Customer type determines channel access, information consumption, and willingness to pay for certification premiums versus convenience positioning.
- Expectant Mothers:First-time urban mothers drive adoption of clinically tested stretch mark therapies and prenatal vitamin bundles. Subscription commerce infrastructure in United States and Chinese metropolitan centers reduces customer acquisition costs for direct-to-consumer brands targeting this cohort.
- New Mothers:Postpartum recovery needs span cesarean-section scar therapy, perineal repair, and lactation support. Hospital discharge kit inclusion and lactation consultant recommendations shape initial product trial for this segment.
- Healthcare Providers:Maternal-fetal medicine specialists and lactation consultants influence brand selection through professional endorsement and prescription-adjacent recommendation. Procurement decisions prioritize FDA-registered and clinically substantiated formulations.
- Retailers:Pharmacy chains and natural food cooperatives curate assortments based on clean-label certification, margin structure, and inventory velocity. USDA Organic certification arbitrage commands premium positioning in North American natural retail channels.
Transaction volume concentrates in Expectant Mothers; Healthcare Provider channel development offers the steepest expansion trajectory.
Distribution Channel:
Supply concentration in digital infrastructure and pharmacy networks determines geographic reach and inventory carrying costs for perishable botanical formulations.
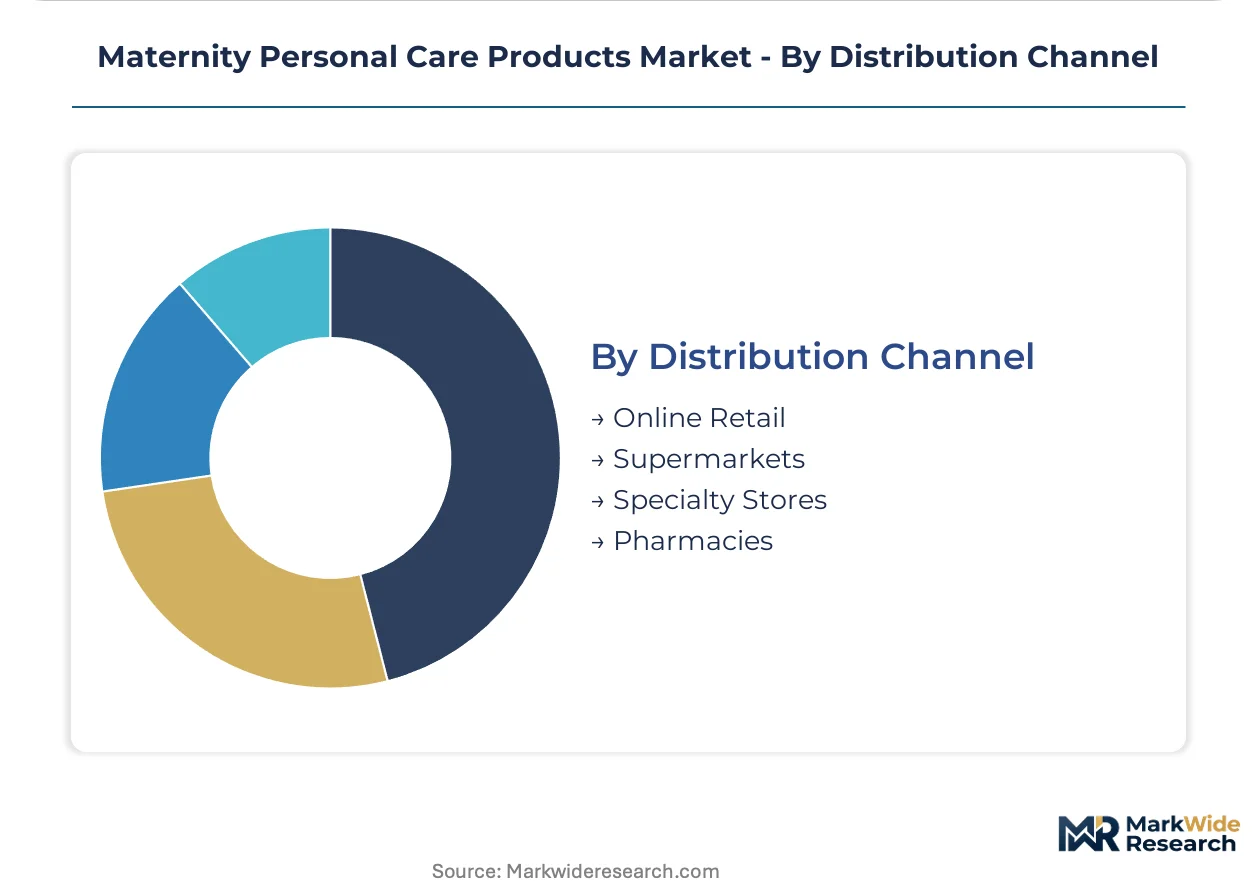
- Online Retail:Subscription models and telehealth partnerships displace pharmacy aisle discovery as the primary customer acquisition channel. Automated replenishment for prenatal skincare bundles gains traction in United States metropolitan markets where maternity wellness apps aggregate purchasing intent data.
- Pharmacies:Retail pharmacy chains in Germany and the United States expand maternity wellness portfolios through pharmacist consultation and private-label development. REACH compliance and EU Green Deal mandates elevate R&D spend as percentage of revenue for shelf placement.
- Supermarkets:Mass-market placement of body wash and basic moisturizers serves price-sensitive daily replenishment needs. Clean-label substitution ceiling constrains distribution radius due to shorter shelf stability of plant-derived preservatives.
- Specialty Stores:Natural product retailers and motherhood boutiques emphasize third-party certification and ingredient transparency. Earth Mama leverages USDA Organic positioning to defend margin structure in this channel.
Volume concentrates in Pharmacies; Online Retail climbs the fastest as subscription infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shea butter cooperatives in Burkina Faso and Ghana anchor raw material sourcing for pregnancy-safe emollients, while colloidal oatmeal processors in North American prairie regions supply barrier-repair formulations. Botanical extract concentration in these agricultural zones shapes manufacturing location decisions for multinational cosmetic formulators.
United States
First-time mothers in metropolitan New York and Los Angeles drive demand for clinically substantiated stretch mark therapies. FDA Modernization of Cosmetics Regulation Act mandates adverse event reporting and fragrance allergen disclosure, elevating compliance costs for maternity-specific brands. Direct-to-consumer subscription models in California and Texas displace traditional pharmacy discovery through telehealth partnerships.
Germany
Urban centers in Bavaria and North Rhine-Westphalia concentrate procurement of dermatologically tested prenatal skincare. ECHA REACH restrictions on endocrine-disrupting chemicals compel reformulation investments across preservative systems. Specialty chemical producers in Frankfurt-Rhine-Main expand fermentation-derived squalane output for clean-label moisturizers.
China
Metropolitan Shanghai and Beijing anchor demand for pregnancy-safe barrier-repair formulations among professional-class mothers. NMPA cosmetic registration rules create divergent compliance pathways that elongate product approval timelines. Domestic formulators in Yangtze River Delta clusters adopt biotechnology-derived hyaluronic acid at accelerating volume.
India
Ayurvedic herbals penetrate South Asian maternity routines through standardized ashwagandha and gotu kola extracts. BIS certification requirements for cosmetic safety testing fragment registration strategies for multinational entrants. Manufacturing concentration in Maharashtra and Gujarat supports export corridors into Middle Eastern markets.
France
Paris and Lyon metropolitan areas sustain premium positioning for fermentation-derived surfactants in pregnancy-compatible body washes. EU Green Deal mandates accelerate plant-derived ingredient substitution across fragrance compounds. Cosmetic research clusters in Île-de-France develop clinically tested perineal repair formulations for postpartum segments.
Maternity Personal Care Products Market Competitive Environment
Global majors compete with regional champions across certification standards and channel access. The vendor base stratifies between multinational dermatological portfolios with regulatory affairs infrastructure and agile direct-to-consumer specialists leveraging subscription commerce. Three archetypes dominate: premium clinical brands with hospital discharge kit placement, clean-label organic specialists commanding natural retail margins, and mass-market formulations serving price-sensitive daily regimens. Competitive moves concentrate on USDA Organic certification arbitrage and telehealth partnership networks that bypass wholesale margin structures.
Within the premium clinical tier, L'Oréal and Clarins Group exemplify multinational dermatological research capabilities, while Earth Mama and The Honest Company occupy positions in the clean-label organic segment. Lansinoh Laboratories anchors institutional channel access through lactation consultant networks. These named entities represent strategic positioning across certification, channel, and formulation archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| L'Oréal |
| E.T. Browne Drug |
| The Himalaya Drug Company |
| Clarins Group |
| Mama Mio |
| Earth Mama |
| The Honest Company |
| Lansinoh Laboratories |
| Johnson's Baby |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between USDA Organic and conventional formulations splits pricing power along supply chain control lines, with third-party verified tiers commanding shelf-stability premiums while commodity botanicals compete on volume scale in mass retail. This bifurcation forces manufacturers to dual-source preservative systems and fragrance compounds to serve divergent margin structures without cross-contamination.
Pricing Analysis
Subscription bundling of prenatal skincare regimens includes automated replenishment and telehealth consultation access, while transactional pharmacy purchases exclude these services. Three-tier pricing structure across premium, standard, and economy levels reflects certification investment, with USDA Organic and dermatologist-endorsed formats at the top. Cost compression in mass-market moisturizers stems from shea butter price volatility in West African cooperatives. Hospital procurement officers show lowest price sensitivity; supermarket shoppers in China and India exhibit highest.
Supply Chain Analysis
Direct-to-consumer channels handle subscription-based replenishment demand from United States metropolitan markets, while retail pharmacy networks manage institutional procurement for hospital discharge kits. Raw material sourcing draws from Burkina Faso and Ghana for shea butter, North American prairie regions for colloidal oatmeal, and Yangtze River Delta clusters for fermentation-derived hyaluronic acid. Single-source vulnerability concentrates in climate-exposed agricultural zones. Distribution runs through e-commerce platforms, pharmacy chains, and natural product retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The maternity personal care sector functions as a cost-of-compliance arena where FDA Modernization of Cosmetics Regulation Act implementation erects regulatory affairs barriers that favor incumbents with dedicated toxicologist teams and batch traceability infrastructure.
For Market Incumbents: Anchor market position through captive supply agreements with shea butter cooperatives in Burkina Faso and Ghana to secure input cost stability against climate volatility. Deepen regulatory affairs capacity in Asia-Pacific headquarters to compress NMPA and BIS registration timelines. Defensive priority targets direct-to-consumer entrants leveraging subscription commerce to bypass wholesale margin structures. For New Entrants and Emerging Players: Telehealth partnership networks offer the most penetrable route for clinical credibility acquisition without legacy regulatory infrastructure. Target postpartum recovery verticals—cesarean-section scar therapy and perineal repair formulations—as white space beyond saturated stretch mark segments. Go-to-market angle emphasizes Ayurvedic herbals for South Asian and Middle Eastern export corridors where standardized extracts remain underpenetrated. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational dermatological portfolios seeking clean-label certification assets. Long-term viability favors targets with USDA Organic positioning and established lactation consultant referral networks. Signal to watch: state-level clean beauty legislation accelerating beyond federal minimums, which would amplify compliance cost advantages for pre-positioned players.| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Investment | Third-party validation commands margin expansion in North American natural retail channels. |
| Telehealth Partnership Development | Lactation consultant networks drive hospital discharge kit inclusion and subscription conversion. |
| Fermentation-Derived Input Adoption | Biotechnology platforms compress cost premiums for clean-label emollients and surfactants. |
| Postpartum Recovery Line Extension | Cesarean-section scar therapy represents adjacent white space beyond traditional stretch mark SKUs. |
| Asia-Pacific Regulatory Capacity Buildout | Dedicated toxicologist teams accelerate NMPA and BIS registration timelines for multinational portfolios. |
Study Parameters
Independent corroboration across primary interviews with cosmetic formulators, regulatory affairs directors, and lactation consultants, combined with secondary validation through FDA adverse event databases, ECHA REACH dossiers, and Nielsen retail audit data, underwrites the qualitative findings. Bottom-up triangulation from SKU-level pricing and top-down reconciliation against maternity wellness portfolio disclosures complete the analytical foundation.
Rate-of-change decomposition separates volume expansion from price realization across the analysis window, with segmentation modeling across product type, application, end user, and distribution channel dimensions. CAGRs derive from regression of historical procurement patterns against regulatory milestone timelines. Industry-specific inputs include shea butter harvest forecasts from West African agricultural cooperatives and biotechnology platform capacity announcements from German and French specialty chemical producers.
The model holds under stable regulatory enforcement intensity; deviation in REACH restriction expansion or state-level clean beauty legislation acceleration would shift compliance cost assumptions and forecast trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Asia-Pacific Maternity & Personal Care Market
Personal Health
Global on Site Preventive Care Market
Personal Health
Menstrual Cup Market
Personal Health
Reusable Face Mask Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Patient Health Management Market
Personal Health
Global Weight Loss Services Market
Personal Health
Feminine Hygiene Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Foot Insole Market
Personal Health
Blackhead Removing Vacuum Market
Personal Health
Asia-Pacific Mobile Health Market
Personal Health
Interdental Brush Market
Personal Health
Tick Repellent Market
Personal Health
Maternity and Personal Care Market
Personal Health
Workplace Wellness Market