
 Hbsag Testing Market | 2026-2036
Hbsag Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Hbsag Testing Market Foresight
Diagnostic laboratories is rotating toward higher-volume automated HBsAg screening, displacing slower manual workflows in blood banks and reference centers. Abbott Laboratories leverages its immunoassay installed base to sustain recurring reagent revenue across centralized lab networks. Bio-Rad Laboratories specializes in quality control panels that anchor laboratory confidence in test accuracy. Siemens Healthineers dominates high-throughput analyzer placements that integrate HBsAg with multiplex hepatitis panels.
Hepatitis B surface antigen testing detects the outer envelope protein of HBV through serological or molecular methods, with chemiluminescent immunoassays achieving sensitivity thresholds below 0.05 IU/mL for early infection identification. ELISA kits retain cost advantages in resource-limited settings where batch processing offsets longer turnaround times. Molecular diagnostic tests capture margin pools in confirmation workflows and viral load quantification, while rapid test kits extend access to point-of-care settings where infrastructure constraints prevent laboratory-based testing. Nucleic acid testing segments are gaining fastest as nucleic acid amplification technologies displace serological confirmation in high-prevalence regions.
FDA 510(k) clearances and WHO prequalification frameworks shape product standards and determine market access eligibility for manufacturers targeting procurement channels. CLIA complexity classifications in the United States segment reimbursement and placement strategies between waived point-of-care devices and moderate-complexity laboratory platforms. Stakeholders must monitor evolving EMA in vitro diagnostic regulation harmonization timelines that will reshape conformity assessment burdens for kits entering European markets.
Market Dynamics
The WHO prequalification pathway is compressing time-to-market for diagnostic manufacturers while simultaneously elevating performance benchmarks for serological sensitivity thresholds.
Growth Catalysts
- National Viral Hepatitis Control Program:India's nationwide testing infrastructure expansion is generating concentrated demand for high-throughput analyzers and automated screening platforms in public health laboratories.
- CLIA complexity classifications:The United States reimbursement framework segments placement strategies between waived point-of-care devices and moderate-complexity laboratory platforms, creating dual-channel market expansion.
- Chemiluminescent immunoassays:Sensitivity thresholds below 0.05 IU/mL are enabling earlier infection identification in blood safety protocols, driving replacement cycles in centralized diagnostic networks.
Market Restraints
- ELISA cost structure:Batch processing economics in resource-limited settings create price anchoring that constrains premium platform penetration in lower-tier laboratories.
- Reagent supply concentration:Specialized antibody and enzyme suppliers cluster in concentrated manufacturing geographies, exposing procurement chains to single-source vulnerability.
- EMA in vitro diagnostic regulation:Evolving harmonization timelines reshape conformity assessment burdens, extending certification timelines for kits entering European markets.
Strategic Opportunities
- Point-of-care channel innovation:Rapid test kits extend access to settings where infrastructure constraints prevent laboratory-based testing, opening decentralized diagnostic networks.
- Nucleic acid amplification convergence:NAT segments displace serological confirmation workflows in high-prevalence regions, capturing margin pools in viral load quantification.
- PLI scheme incentives:India's production-linked incentive framework for medical devices reduces landed cost disadvantages for domestic manufacturing investments.
Industry Challenges
- Multiplex integration complexity:Laboratory information systems require specialized interfacing protocols to accommodate HBsAg panels bundled with hepatitis C and HIV screening on single analyzers.
- ISO 15189 accreditation timelines:Quality management system certification for diagnostic laboratories extends validation cycles, delaying test kit deployment in newly established screening programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hbsag Testing Market |
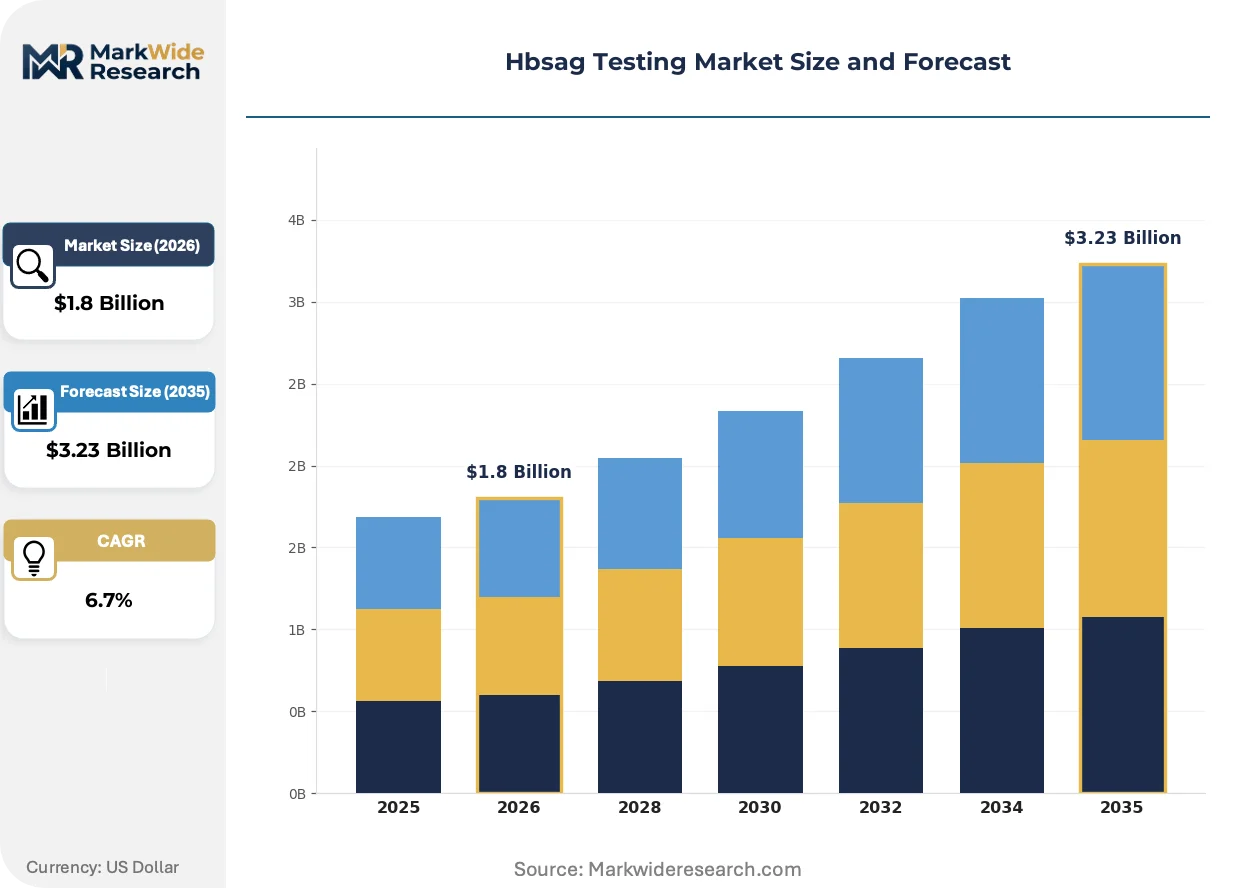
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Test Kits, ELISA Kits, Molecular Diagnostic Tests, Reagents End User: Hospitals, Diagnostic Laboratories, Clinics, Research Institutions Technology: Immunoassays, Nucleic Acid Testing, Point-of-Care Testing, Microarray Distribution Channel: Direct Sales, Distributors, Online Retail, Hospital Pharmacies |
| Companies Covered | F. Hoffmann-La Roche, Abbott Laboratories, Siemens Healthineers, Bio-Rad Laboratories, Beckman Coulter, Ortho Clinical Diagnostics, Thermo Fisher Scientific, Cepheid, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hbsag Testing Market Shifts & Advancements
Automation architectures are reconfiguring laboratory workflows while regulatory convergence pressures reshape competitive entry barriers across procurement channels.
Automated immunoassay platforms is fragmenting the installed base between high-throughput centralized laboratories and distributed mid-volume testing sites. Blood banks and reference centers are adopting these systems at accelerated replacement cycles. The technology is fragmenting vendor lock-in patterns by enabling modular reagent sourcing across multiple analyzer brands.
EMA in vitro diagnostic regulation harmonization is compressing certification pathway divergence across European member states. Manufacturers face consolidated technical documentation requirements replacing national notified body fragmentation. High-complexity laboratory platforms face the steepest adaptation burden as clinical evidence thresholds escalate for class C device classifications.
Blood safety procurement is consolidating toward integrated service contracts bundling analyzers, reagents, and quality control materials. Hospital networks and national screening programs are displacing transactional kit purchasing with multi-year partnership structures. India and Southeast Asian public health systems exhibit the most pronounced contract aggregation, driven by WHO prequalification eligibility requirements for donor-funded procurement windows.
Hbsag Testing Market Segmentation
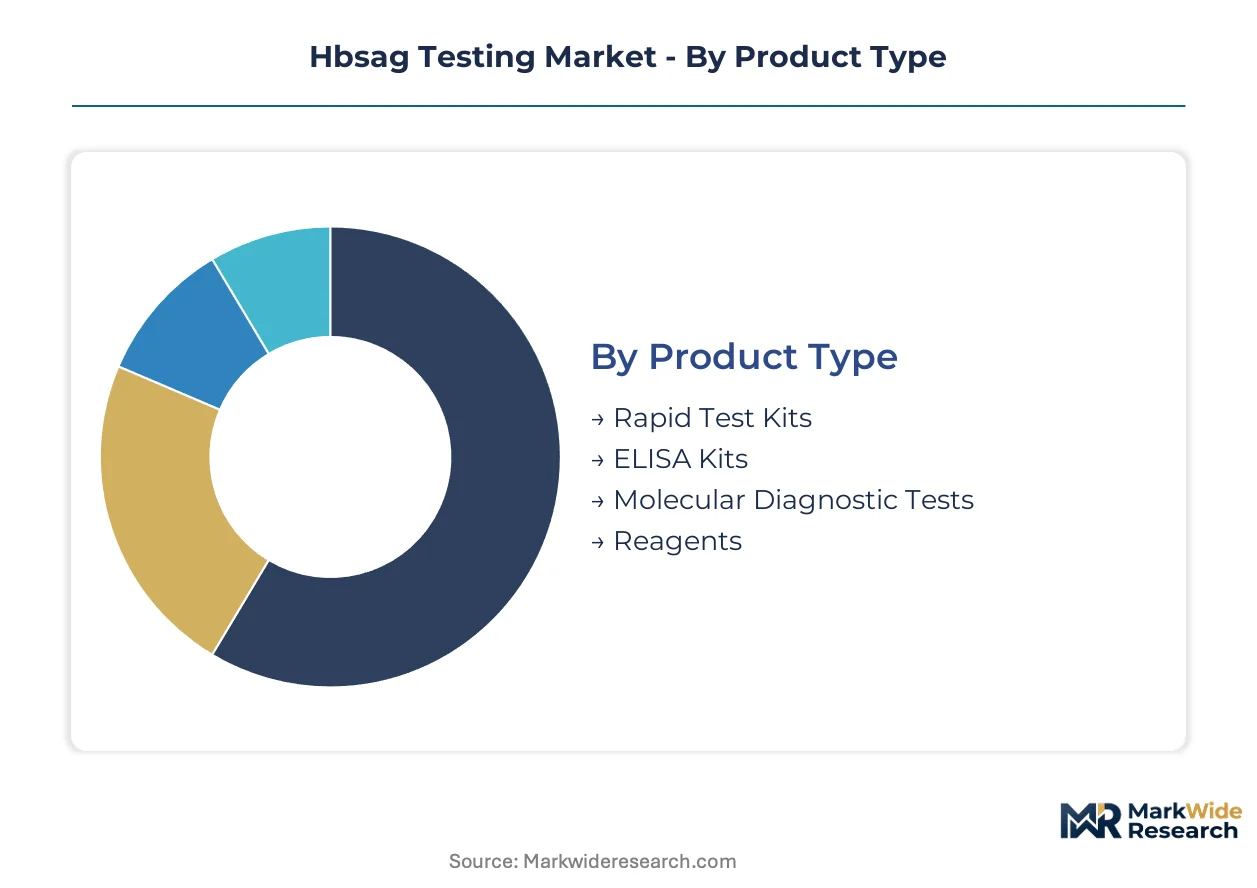
HBsAg testing markets fragment across technology maturity curves and procurement channel structures. Regulatory complexity tiers—FDA 510(k), WHO prequalification, and EMA IVDR—create divergent entry barriers that reshape competitive positioning within each segment cluster.
Product Type:
FDA CLIA complexity classifications and WHO prequalification tiers segment placement economics across centralized versus decentralized settings.
- Rapid Test Kits:Lateral flow immunochromatography delivers results within 15-20 minutes without laboratory infrastructure. WHO prequalification eligibility unlocks donor-funded procurement in India's National Viral Hepatitis Control Program and sub-Saharan African blood safety initiatives.
- ELISA Kits:Enzyme-linked immunosorbent assays process 96-well microplates with optical density readouts, achieving cost-per-test advantages through batch economics. Resource-limited settings in Southeast Asia anchor sustained demand despite longer turnaround times.
- Molecular Diagnostic Tests:Nucleic acid amplification platforms target viral load quantification and confirmation workflows.
- Reagents:Specialized antibodies, conjugates, and calibrators supply analyzer-dependent recurring revenue streams.
Established volume favors ELISA kits; emerging adoption favors rapid test kits.
End User:
Customer procurement sophistication tiers segment pricing tolerance and service contract structures.
- Diagnostic Laboratories:High-throughput analyzers integrate HBsAg with multiplex hepatitis panels on chemiluminescent platforms. India's public health laboratory network drives concentrated analyzer placements under national screening program tenders.
- Hospitals:Emergency departments and pre-surgical screening units demand STAT turnaround capabilities. Blood bank integration within hospital networks sustains reagent pull-through on installed immunoassay systems.
- Clinics:Point-of-care deployment targets antenatal and primary care screening with waived complexity devices.
- Research Institutions:Epidemiological surveillance and vaccine efficacy studies consume specialized assay formats.
Contract aggregation concentrates in diagnostic laboratories; margin expansion concentrates in hospital networks.
Technology:
Performance sensitivity thresholds and capital intensity differentiate competitive moats across methodological approaches.
- Immunoassays:Chemiluminescent microparticle technology achieves sub-0.05 IU/mL sensitivity for early infection detection. Centralized laboratory networks in the United States and Western Europe anchor replacement cycles as sensitivity benchmarks escalate.
- Nucleic Acid Testing:Polymerase chain reaction and transcription-mediated amplification displace serological confirmation in high-prevalence regions. Viral load quantification commands premium pricing in hepatitis B management protocols.
- Point-of-Care Testing:Immunochromatographic and electrochemical biosensor formats extend access beyond laboratory infrastructure.
- Microarray:Multiplexed protein detection enables simultaneous hepatitis B genotyping and antigen profiling.
Reagent revenue stability favors immunoassays; steepest expansion trajectory favors nucleic acid testing.
Distribution Channel:
Supply chain configuration and procurement authority concentration determine margin capture and customer stickiness.
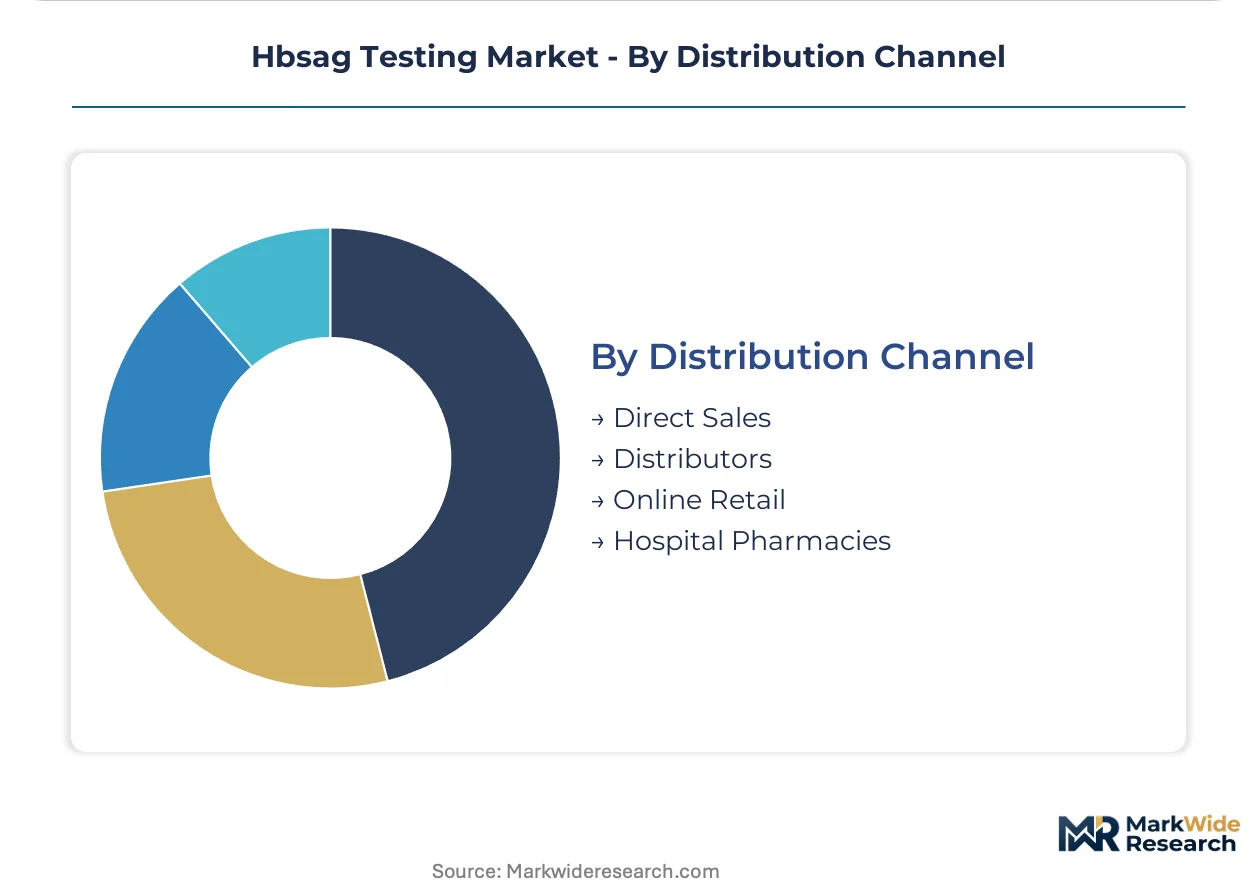
- Direct Sales:Manufacturer field organizations negotiate multi-year service contracts bundling analyzers, reagents, and quality control materials. India's national tendering system exhibits pronounced contract aggregation toward direct procurement models.
- Distributors:Regional logistics networks penetrate mid-tier laboratories and clinic chains with localized technical support. Southeast Asian markets rely on distributor infrastructure for post-installation service coverage.
- Online Retail:E-commerce platforms serve research institutions and small clinic procurement with catalog-based purchasing.
- Hospital Pharmacies:Captive supply channels within integrated delivery networks consolidate point-of-care test kit purchasing.
Service bundling favors direct sales; geographic penetration favors distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports high-throughput diagnostic analyzers to blood safety networks across India, Brazil, and Southeast Asia, consolidating European manufacturing dominance in automated immunoassay platforms.
United States
FDA CLIA complexity classifications segment procurement between waived point-of-care devices and moderate-complexity laboratory platforms. The IRA's diagnostic reimbursement provisions shape placement economics in hospital networks. Greater Boston anchors molecular diagnostic R&D clusters where nucleic acid amplification technologies displace serological confirmation workflows.
India
The National Viral Hepatitis Control Program drives concentrated demand for automated screening platforms in public health laboratories. CDSCO's streamlined medical device registration accelerates market access for WHO-prequalified test kits. Maharashtra's diagnostic manufacturing corridor in Mumbai-Pune hosts expanding reagent production facilities serving domestic tender requirements.
Germany
EMA's in vitro diagnostic regulation harmonization compresses certification timelines while elevating clinical evidence thresholds for class C devices. The country's central bank stability supports long-term service contract financing for hospital networks. Baden-Württemberg's industrial belt concentrates chemiluminescent analyzer manufacturing for export to European screening programs.
China
NMPA's streamlined Class II/III diagnostic registration accelerates domestic test kit commercialization against imported platforms. National hepatitis B screening mandates in maternal health programs sustain volume demand. Yangtze River Delta biotech clusters in Shanghai-Suzhou scale nucleic acid testing manufacturing for regional supply.
Brazil
ANVISA's diagnostic import regulations favor WHO-prequalified manufacturers in public procurement tenders. Blood safety protocols in the national transfusion service drive analyzer replacement cycles. São Paulo's clinical laboratory networks concentrate high-throughput hepatitis screening capacity for southeastern Brazil's population corridor.
Hbsag Testing Market Competitive Landscape
Player mix skews toward diversified diagnostics conglomerates with installed-base leverage, creating tiered competition between platform-integrated giants and specialized reagent suppliers. Consolidation pressures favor manufacturers bundling analyzers, reagents, and quality control materials under multi-year service contracts. Two strategic archetypes dominate: installed-base incumbents monetizing recurring reagent streams, and molecular diagnostic specialists capturing confirmation workflow premiums. Competitive moves center on analyzer placement financing and geographic expansion through WHO prequalification pathways.
Among diversified diagnostics conglomerates, F. Hoffmann-La Roche and Abbott Laboratories exemplify installed-base incumbents leveraging immunoassay platform dominance. Siemens Healthineers occupies a position at the high-throughput analyzer tier. Bio-Rad Laboratories represents the specialized reagent and quality control archetype. These three companies collectively illustrate how European and US-based manufacturers anchor procurement channel concentration through service bundling and regulatory prequalification advantages.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Abbott Laboratories |
| Siemens Healthineers |
| Bio-Rad Laboratories |
| Beckman Coulter |
| Ortho Clinical Diagnostics |
| Thermo Fisher Scientific |
| Cepheid |
| bioMérieux |
| Others |
Supply & Pricing Matrix
Multi-year service contracts bundling analyzers, reagents, and quality control materials lock in supply access and price visibility for hospital networks and national screening programs, compressing procurement volatility while anchoring reagent pull-through economics. India's National Viral Hepatitis Control Program tenders and blood safety networks in Brazil exemplify this contract-structure pattern, displacing transactional kit purchasing with integrated partnership frameworks.
Pricing Analysis
Next-generation chemiluminescent immunoassays command premium positioning against prior-generation ELISA kits and economy-tier rapid test strips. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade—FDA 510(k) and WHO prequalification tiers anchor the premium band—while volume scale and after-sales service bundling differentiate mid-tier placements. Pricing pressure stems from ELISA batch-processing economics in resource-limited settings, where cost-per-test advantages constrain premium platform penetration. Diagnostic laboratories exhibit lowest price sensitivity due to integrated analyzer financing, while primary care clinics in decentralized networks show highest sensitivity to per-unit kit costs.
Supply Chain Analysis
Germany and the United States anchor high-throughput analyzer manufacturing, while India and China concentrate reagent and rapid test kit production. Specialized antibody and enzyme inputs draw from concentrated biotechnology clusters in Baden-Württemberg and the Yangtze River Delta, with conjugate and calibrator supplies tethered to ISO 13485-certified facilities. Single-source vulnerability in specialized enzyme suppliers exposes procurement chains to disruption risk. Distribution runs through direct sales organizations for multi-year hospital contracts, with regional distributors penetrating mid-tier laboratories in Southeast Asia and Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of WHO prequalification expertise and nucleic acid amplification manufacturing capability concentrates competitive advantage among established diagnostics conglomerates, creating asymmetric entry barriers for specialized players lacking regulatory navigation assets or integrated platform portfolios.
For Market Incumbents: Secure analyzer placement financing in India's public health laboratory network to preempt competitor lock-in under National Viral Hepatitis Control Program tenders. Deepen backward integration into specialized antibody production to reduce single-source enzyme supplier vulnerability. Anchor recurring reagent revenue through multi-year service contracts bundling quality control materials, defending against emerging molecular diagnostic specialists capturing confirmation workflow premiums. For New Entrants and Emerging Players: Post-installation technical service gaps in Southeast Asian distributor networks present white-space entry points where incumbents under-serve mid-tier laboratories. Target Brazil's ANVISA-regulated public procurement channel with WHO-prequalified rapid test kits, penetrating blood safety protocols before analyzer-integrated competitors consolidate. Pursue point-of-care channel innovation with CLIA-waived devices for antenatal screening in decentralized clinic settings. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among installed-base incumbents with immunoassay platform dominance, offering superior cash-flow predictability across the analysis window. Prioritize acquisition targets with nucleic acid testing manufacturing capabilities and WHO prequalification pathway expertise, as NAT segments displace serological confirmation in high-prevalence regions. Monitor EMA IVDR harmonization timelines as inflection signal for European market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway Investment | Unlocks donor-funded procurement in India's national screening programs and sub-Saharan African blood safety initiatives. |
| Analyzer-Reagent Bundle Financing | Locks in multi-year service contracts with hospital networks, displacing transactional kit purchasing. |
| Nucleic Acid Testing Manufacturing Scale-Up | Captures margin pools in viral load quantification as NAT displaces serological confirmation workflows. |
| Point-of-Care Device CLIA Waiver Pursuit | Extends access to primary care and antenatal settings where laboratory infrastructure constraints prevent centralized testing. |
| Backward Integration into Enzyme Production | Reduces single-source supplier vulnerability in specialized antibody and conjugate manufacturing. |
Research Methodology
Cross-validation between primary interviews with diagnostic laboratory directors, regulatory affairs specialists at IVD manufacturers, hospital procurement committee members, and blood bank technical officers anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, WHO prequalification assessments, CDSCO medical device registrations, and EMA IVDR technical documentation. Bottom-up triangulation across product-type demand curves and top-down reconciliation against national screening program budgets solidify volume estimates.
Sensitivity analysis across chemiluminescent immunoassay sensitivity thresholds, ELISA batch-size economics, and rapid test kit penetration rates informs the analytical framework over the projection horizon. Segmentation dimensions modeled include technology maturity tier, CLIA complexity classification, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from installed-base replacement cycle analysis and nucleic acid testing adoption curves in high-prevalence regions. Forecast inputs incorporate India's PLI scheme incentive structures and EMA harmonization timeline scenarios.
Underlying assumptions cover WHO prequalification pathway stability and nucleic acid amplification technology cost curves, with deviation risk concentrated in EMA IVDR implementation delays and reagent supply chain disruptions. Recalibration cycles align with material shifts in national hepatitis control program tender schedules and regulatory harmonization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Adenovirus Testing Market
Testing Services
Urodynamic Testing Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
Pancreatic Stone Protein Testing Market
Testing Services
North America Drug Screening Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Global Endocrine Testing Market
Testing Services
Ovulation Test Kit Market
Testing Services
Blood Borne Testing Market
Testing Services
Antimicrobial Susceptibility Testing Market
Testing Services
Redox Meter Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Home Care Testing Market
Testing Services
Fungal Testing Kits Market
Testing Services
US Pharmaceutical Sterility Testing Market