
 Loose Fill Packaging Systems Market | 2026-2036
Loose Fill Packaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Loose Fill Packaging Systems Market Foresight
REACH is realigning material sourcing costs for European loose fill producers, forcing reformulation of polystyrene-based products toward compliant alternatives. Sealed Air Corporation leverages its global manufacturing footprint to navigate multi-jurisdictional chemical standards, while Storopack specializes in expanded foam systems with reduced residual monomer content. DS Smith plc anchors its competitive position through integrated paper-based fill production tied directly to recycled fiber supply chains.
Loose fill packaging systems encompass dispensable cushioning materials—typically expanded polystyrene foam peanuts, inflatable air cushions, crumpled paper, or starch-derived biodegradable granules—engineered to fill void spaces within shipping containers and absorb shock during transit, with densities ranging from 0.5 to 2.5 pounds per cubic foot depending on material composition. These systems protect fragile goods across temperature fluctuations from -20°C to 60°C while allowing single-operator dispensing at rates exceeding 50 cubic feet per minute. Biodegradable fill derived from cornstarch commands widening preference among food and beverage shippers facing compostability mandates, while air cushions dominate electronics fulfillment due to minimal material weight and dimensional efficiency. Paper fill retains structural importance in automotive aftermarket parts distribution where oil resistance and fiber recyclability outweigh cushioning performance.
The EPA regulates volatile organic compound emissions from expanded polystyrene manufacturing under Clean Air Act provisions, while the EU F-Gas Regulation constrains blowing agent chemistries in foam production. China's SAMR enforces GB standards for packaging material migration limits that directly affect polyethylene loose fill exports. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
E-commerce fulfillment networks are compressing damage tolerance thresholds to sub-2% return rates, forcing loose fill specification upgrades across automotive aftermarket, electronics, and temperature-sensitive pharmaceutical corridors. This operational imperative is restructuring converter priorities around dispensing speed, material density calibration, and closed-loop recovery infrastructure.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds are accelerating converter migration from virgin polystyrene toward certified compostable starch granules and post-consumer paper fiber systems.
- Automotive parts export density:German OEM aftermarket distribution networks specify oil-resistant paper fill for engine component shipments, creating premium demand for fiber-based cushioning with controlled moisture absorption.
- Automated dispensing integration:Robotic void-fill stations operating at 50+ cubic feet per minute are eliminating manual packing labor in high-velocity electronics fulfillment centers.
Market Restraints
- Expanded polystyrene feedstock volatility:Benzene and styrene monomer price swings compress margin predictability for conventional foam peanut producers without backward integration into resin supply.
- Blowing agent chemistry constraints:EU F-Gas Regulation phase-down schedules for hydrofluorocarbon propellants force capital-intensive retooling of extrusion lines toward pentane or CO2-based expansion systems.
- Air cushion substitution threat:On-demand inflatable film systems from film extruders capture volume in lightweight electronics shipping where dimensional efficiency outweighs loose fill shock absorption.
Strategic Opportunities
- India cross-border e-commerce corridors:DGFT export packaging incentives and Amazon-Flipkart fulfillment expansion create first-mover positioning for biodegradable fill converters establishing local compounding capacity.
- Pharmaceutical cold chain convergence:Integration of loose fill with phase-change material panels enables unified thermal-and-mechanical protection for biologics shipping, displacing separate insulation layers.
- Retail take-back channel innovation:Curbside collection programs for starch-based fill recovery align with municipal composting infrastructure investments in California and Pacific Northwest metropolitan clusters.
Industry Challenges
- Compostability certification latency:ASTM D6400 and EN 13432 testing timelines extending 6-12 months delay product launches for converters pursuing food-contact and agricultural end-use approvals.
- Legacy ERP integration friction:Automated dispensing systems require real-time inventory signaling that conflicts with warehouse management platforms deployed by mid-tier 3PL operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loose Fill Packaging Systems Market |
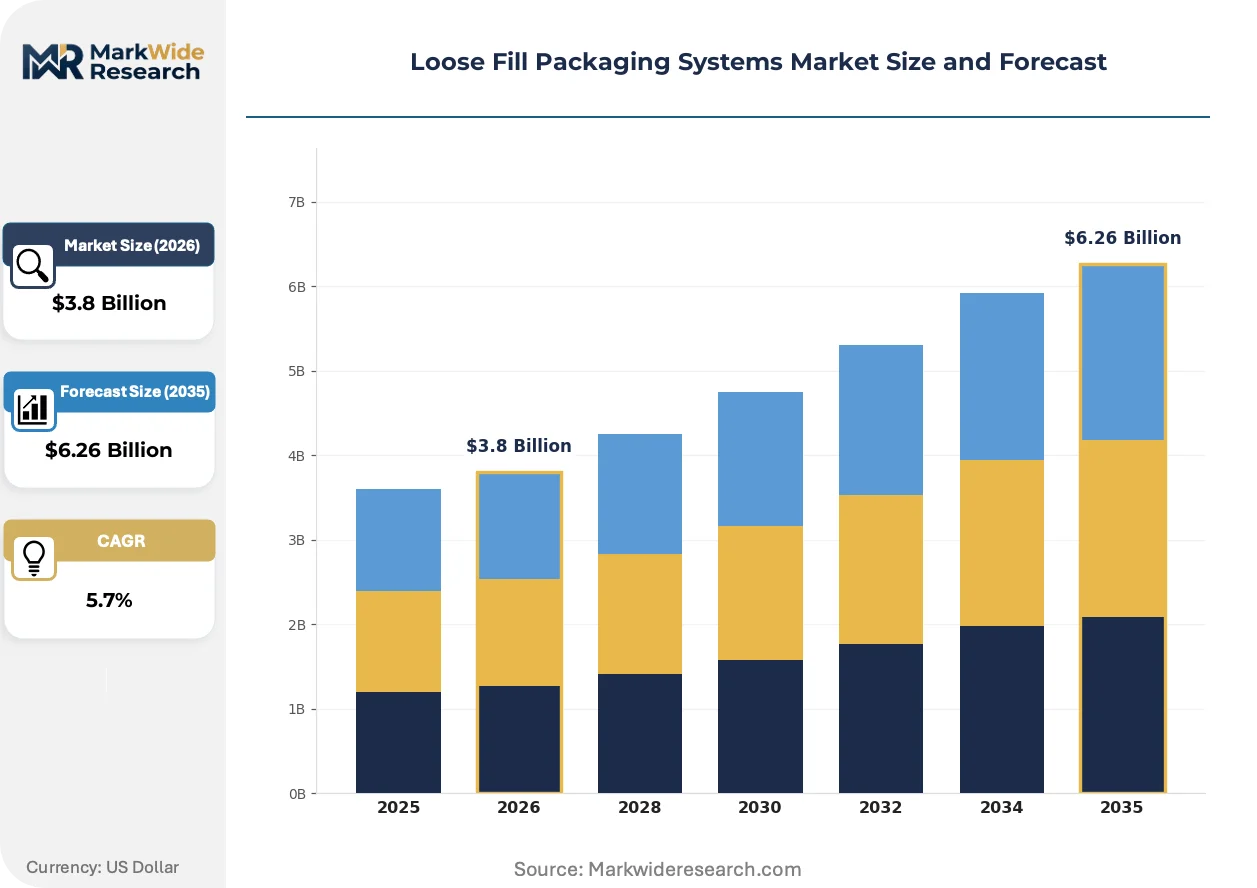
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Peanuts, Air Cushions, Paper Fill, Biodegradable Fill Material: Polyethylene, Polystyrene, Paper, Cornstarch End User: E-Commerce, Electronics, Food & Beverage, Automotive Distribution Channel: Online Retail, Wholesale, Direct Sales, Third-Party Logistics |
| Companies Covered | Sealed Air Corporation, Amcor plc, AptarGroup, Inc., Storopack, DS Smith plc, Mondi Group, Smurfit Kappa Group plc, Pregis LLC, WestRock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loose Fill Packaging Systems Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are converging to displace conventional petroleum-based loose fill architectures. Three distinct vectors are restructuring competitive positioning: bio-based formulation breakthroughs, jurisdictional chemical standard divergence, and fulfillment automation forcing dispensing speed thresholds.
Starch-foam expansion technology is rewriting protective packaging economics for temperature-sensitive agricultural exports. Modified cornstarch formulations with controlled gelatinization profiles now achieve compression set performance comparable to expanded polystyrene at densities below 1.0 pound per cubic foot. California produce distributors and Dutch flower exporters are specifying these materials for shipments requiring EN 13432 compostability verification at destination.
REACH substance restriction lists are fragmenting material approval pathways across European converter networks. ECHA candidate list updates for microplastic definitions and residual monomer thresholds force reformulation of conventional loose fill chemistries on 18-month regulatory cycles. German automotive suppliers and French luxury goods shippers now require extended safety data sheet documentation that many Asian exporters cannot provision, creating sourcing preference for REACH-registered European compounders.
Same-day delivery service level agreements are compressing packing station cycle times to under 45 seconds per parcel. Electronics fulfillment operators in Shenzhen, Rotterdam, and Dallas are retrofitting gravity-fed loose fill dispensers with vision-guided robotic placement to eliminate operator reach time. This automation shift favors free-flowing granule geometries over interlocking peanut configurations that jam in high-speed dispensing throats.
Loose Fill Packaging Systems Market Segmentation
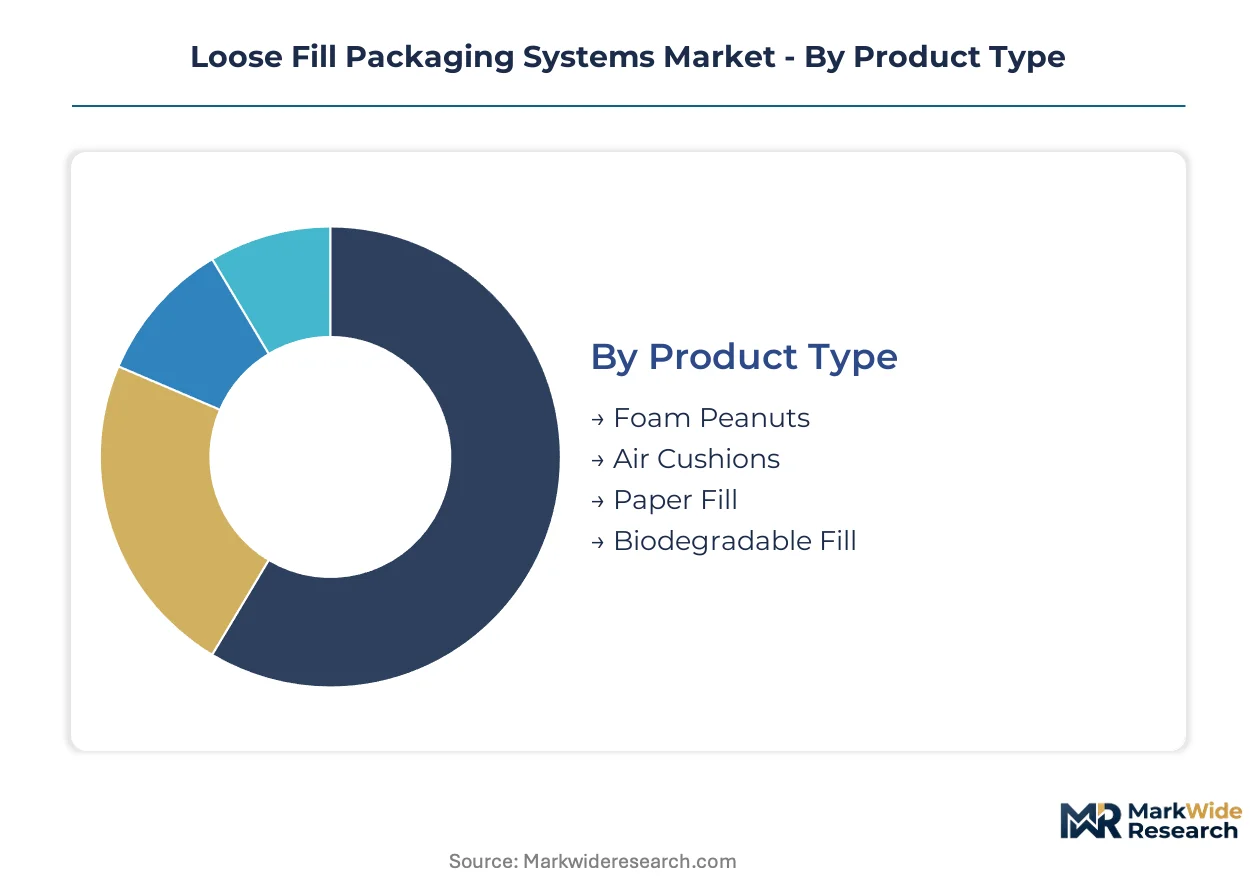
Loose fill packaging systems demand fragments across material chemistries, fulfillment velocities, and regulatory compliance tiers. Converter strategy requires matching product architecture to specific end-use damage tolerance thresholds and compostability mandates.
Product Type:
Foam Peanuts carries ASTM D6400 certification burden for food-contact applications, while Biodegradable Fill requires EN 13432 verification for EU agricultural exports. Air Cushions and Paper Fill face lighter documentation loads but must meet dimensional efficiency specifications in automated dispensing environments.
- Foam Peanuts:Expanded polystyrene beads with interlocking geometry provide compression set performance at 0.5-1.2 pounds per cubic foot density. Electronics fulfillment centers in Shenzhen and Dallas specify virgin-grade material for static-sensitive component protection despite REACH residual monomer scrutiny.
- Biodegradable Fill:Modified cornstarch granules with controlled gelatinization profiles achieve compostable cushioning at sub-1.0 pound per cubic foot density. Dutch flower exporters and California produce distributors mandate EN 13432 verification for destination composting infrastructure compliance.
- Air Cushions:On-demand inflatable film systems minimize material weight for lightweight electronics shipping where dimensional efficiency outweighs shock absorption.
- Paper Fill:Crumpled post-consumer fiber provides oil resistance for German automotive aftermarket parts distribution with controlled moisture absorption properties.
Foam Peanuts sits at the top of the volume ranking, with Biodegradable Fill climbing the fastest.
Material:
Cost tier stratification separates commodity resin feedstocks from certified bio-based alternatives with extended safety data sheet documentation.
- Polystyrene:Virgin and recycled-grade resin systems dominate conventional foam peanut production with established extrusion infrastructure. Benzene and styrene monomer price volatility compress margin predictability for converters lacking backward integration into resin supply.
- Cornstarch:Modified agricultural feedstock with controlled expansion properties commands premium positioning in food-contact and agricultural export corridors. German automotive suppliers and French luxury goods shippers require REACH-registered compounder sourcing that many Asian exporters cannot provision.
- Polyethylene:Low-density film-grade resin serves inflatable cushion systems with minimal material weight for electronics fulfillment velocity.
- Paper:Post-consumer recycled fiber with controlled fiber length distribution anchors oil-resistant cushioning for engine component shipments.
Polystyrene maintains the largest installed base, though Cornstarch is gaining share fastest amid EU recycled content mandates.
End User:
Application-specific damage tolerance thresholds drive material selection, with E-Commerce and Pharmaceuticals demanding the tightest performance specifications.
- E-Commerce:High-velocity fulfillment networks require dispensing speeds exceeding 50 cubic feet per minute with sub-2% damage rate targets. Robotic void-fill stations in Rotterdam and Dallas retrofit gravity-fed dispensers with vision-guided placement to eliminate operator reach time.
- Electronics:Static-sensitive component protection mandates virgin-grade polystyrene or conductive film laminates with controlled surface resistivity. Same-day delivery service level agreements compress packing station cycle times to under 45 seconds per parcel.
- Food & Beverage:Compostability mandates from municipal infrastructure investments in California and Pacific Northwest metropolitan clusters drive starch-based fill specification.
- Automotive:Oil-resistant paper fill with fiber recyclability anchors German OEM aftermarket distribution networks for engine component shipments.
E-Commerce commands the highest volume throughput, with Food & Beverage expanding most quickly on compostability tailwinds.
Distribution Channel:
Customer type and fulfillment integration depth determine channel selection, with Third-Party Logistics operators facing the steepest ERP integration friction.
- Third-Party Logistics:Mid-tier warehouse management platforms conflict with real-time inventory signaling requirements from automated dispensing systems. Legacy ERP integration projects extend 12-18 months for converters pursuing high-velocity electronics fulfillment contracts.
- Direct Sales:Converter-direct relationships with German automotive suppliers and French luxury goods shippers enable extended safety data sheet documentation and REACH registration verification.
- Wholesale:Distributor networks aggregate demand from smaller fulfillment operators without capital for robotic void-fill station deployment.
- Online Retail:E-commerce platform procurement teams specify loose fill systems through digital sourcing portals with automated compliance documentation upload.
Third-Party Logistics handles the greatest throughput volume, with Direct Sales climbing fastest on certification-intensive automotive and luxury goods demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized packaging engineers cluster in German industrial zones and Chinese manufacturing corridors, anchoring technical development for void-fill systems. These talent concentrations shape regional competitive dynamics and regulatory compliance capabilities.
United States
E-commerce fulfillment operators in Dallas and Pacific Northwest metropolitan clusters drive automated dispensing adoption. The EPA regulates volatile organic compound emissions from expanded polystyrene manufacturing under Clean Air Act provisions. California produce distributors mandate ASTM D6400 compostability verification for starch-based fill recovery through curbside collection programs.
Germany
Automotive aftermarket parts distribution networks specify oil-resistant paper fill for engine component shipments. The EU F-Gas Regulation constrains blowing agent chemistries in foam production, forcing retooling toward pentane or CO2-based expansion systems. Bavarian OEM suppliers require REACH-registered compounder sourcing with extended safety data sheet documentation.
China
Electronics fulfillment centers in Shenzhen compress packing station cycle times to under 45 seconds per parcel. The SAMR enforces GB standards for packaging material migration limits affecting polyethylene loose fill exports. Yangtze River Delta manufacturers retrofit gravity-fed dispensers with vision-guided robotic placement for high-velocity operations.
India
Cross-border e-commerce corridors through Amazon-Flipkart fulfillment expansion create demand for biodegradable fill converters. DGFT export packaging incentives support local compounding capacity establishment. Maharashtra-based 3PL operators face legacy ERP integration friction with real-time inventory signaling requirements.
Netherlands
Dutch flower exporters mandate EN 13432 compostability verification for destination infrastructure compliance. REACH substance restriction lists fragment material approval pathways for European converter networks. Rotterdam electronics fulfillment operators deploy robotic void-fill stations operating at 50+ cubic feet per minute.
Loose Fill Packaging Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material chemistry and dispensing technology vectors. The vendor base stratifies into three tiers: integrated packaging conglomerates with global manufacturing footprints, regional compounders with REACH registration advantages, and automation-focused equipment specialists. Strategic moves concentrate on backward integration into resin supply chains and geographic expansion into India cross-border corridors.
Among diversified packaging conglomerates, Sealed Air Corporation and Amcor plc occupy positions spanning multiple protective packaging categories. DS Smith plc anchors the paper-based fill segment through integrated recycled fiber supply chain control. Storopack exemplifies the European specialist archetype with focused expertise in expanded foam systems. These three companies represent distinct strategic postures: global scale diversification, fiber-based circular economy integration, and regional technical specialization.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Amcor plc |
| AptarGroup, Inc. |
| Storopack |
| DS Smith plc |
| Mondi Group |
| Smurfit Kappa Group plc |
| Pregis LLC |
| WestRock |
| Others |
Supply & Pricing Matrix
Benzene and styrene monomer feedstock costs cascade through polystyrene foam peanut production into three-tier pricing structures across premium, standard, and economy levels. REACH-registered European compounders capture margin premiums from German automotive suppliers requiring extended safety data sheet documentation that Asian exporters cannot provision.
Pricing Analysis
Bundled equipment-and-material service contracts dominate high-velocity electronics fulfillment, while unbundled per-unit transactional pricing persists among mid-tier 3PL operators lacking capital for robotic void-fill station deployment. Price differentiation separates virgin-grade polystyrene with static-dissipative properties from recycled-content alternatives and certified compostable starch granules. Cost compression in standard-grade foam peanuts intensifies because benzene price volatility compresses margin predictability for converters without backward integration into resin supply. Mid-tier wholesale distributors exhibit highest price sensitivity, while German OEM aftermarket networks demonstrate lowest sensitivity due to specification-locked oil-resistant paper fill requirements.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke fulfillment patterns for loose fill packaging systems. Manufacturing concentration draws from Yangtze River Delta extrusion infrastructure for polystyrene foam, Bavarian compounders for REACH-registered starch formulations, and Pacific Northwest recycled fiber mills for oil-resistant paper fill. Single-source vulnerability runs through benzene and styrene monomer supply chains tethered to petrochemical complexes. Distribution runs through converter-direct relationships with automotive suppliers, wholesale aggregator networks for smaller fulfillment operators, and e-commerce platform procurement portals with automated compliance documentation upload.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in biodegradable fill segments where EU recycled content mandates drive premium-tier substitution away from virgin polystyrene. Compostability certification investments and automated dispensing integration costs represent the primary cost-down pathways for competitive positioning.
For Market Incumbents: Hedge against air cushion substitution threats by deepening captive supply of cornstarch feedstock through agricultural processor partnerships in Iowa and Ukraine. Accelerate REACH registration maintenance for residual monomer threshold compliance as ECHA candidate list updates force 18-month reformulation cycles. Prioritize robotic dispensing equipment bundling to lock in high-velocity electronics fulfillment contracts before film extruder competitors capture volume. For New Entrants and Emerging Players: Launch via direct sales to French luxury goods shippers and Dutch flower exporters requiring EN 13432 compostability verification that established polystyrene incumbents cannot rapidly provision. Target India cross-border e-commerce corridors where DGFT export packaging incentives and Amazon-Flipkart fulfillment expansion create first-mover positioning for local compounding capacity. Pursue white-label supply agreements with California produce distributors mandating ASTM D6400 verification for curbside collection program participation. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration advantages fragment competitive positioning between European compounders and Asian exporters lacking extended safety data sheet documentation capabilities. Five-to-ten year viability favors converters with integrated recycled fiber supply chains or backward control over agricultural starch feedstock. Acquisition target archetype: mid-scale biodegradable fill producers with pending EN 13432 certification and established relationships with municipal composting infrastructure operators. Monitor EU F-Gas Regulation phase-down enforcement as inflection indicator for pentane and CO2-based expansion system retrofitting demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstock | Cornstarch supply agreements with Iowa and Ukrainian processors secure cost stability for biodegradable fill production. |
| REACH Registration Maintenance Investment | Extended safety data sheet capabilities satisfy German automotive supplier sourcing requirements that Asian exporters cannot meet. |
| Robotic Dispensing Equipment Bundling | Vision-guided void-fill stations operating at 50+ cubic feet per minute lock in high-velocity electronics fulfillment contracts. |
| EN 13432 Certification Acceleration | Compostability verification enables penetration of Dutch flower export and California produce distribution corridors. |
| India Local Compounding Capacity Establishment | DGFT export packaging incentives support first-mover positioning in Amazon-Flipkart cross-border e-commerce corridors. |
Research Methodology
Coverage spans the United States, Germany, China, India, and the Netherlands, with primary inputs from each market cluster combining interviews with packaging engineers, fulfillment center operations managers, automotive aftermarket procurement leads, and municipal composting infrastructure coordinators. Secondary validation draws from EPA Clean Air Act enforcement records, ECHA candidate list updates, SAMR GB standard filings, DGFT export incentive notifications, and SEC 10-K disclosures from diversified packaging conglomerates. Bottom-up demand modeling across e-commerce, electronics, food and beverage, and automotive end-use segments triangulates against top-down macroeconomic indicators.
Granularity-level modeling operates at material chemistry tier, dispensing automation intensity, and regulatory compliance grade dimensions across the projection horizon. Segment-specific CAGRs derive from elasticity-adjusted demand curves incorporating e-commerce fulfillment velocity growth, EU Packaging and Packaging Waste Regulation recycled content mandate schedules, and automotive aftermarket parts export density trends. Industry-specific forecast inputs include robotic void-fill station deployment rates in Rotterdam and Dallas, and municipal composting infrastructure investment pipelines in California and Pacific Northwest metropolitan clusters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under benzene price volatility spikes, REACH substance restriction acceleration, or air cushion technology breakthroughs displacing loose fill shock absorption economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Shrink Wrap Sealers Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Filling Equipment Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Gas-Flushing Band Sealing Systems Market
Packaging Equipment
Strapping Equipment Market
Packaging Equipment
Bag Re-Sealer Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Global Dispensing Systems Market
Packaging Equipment
Food Packaging Equipment Market
Packaging Equipment
Global Cap Applicators Market
Packaging Equipment
Shrink Wrapper Market
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Packer Market