
 Asia-Pacific Bicycle Market | 2026-2036
Asia-Pacific Bicycle Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bicycle Market Outlook
E-commerce platforms is reshaping how bicycles reach end consumers across the Asia-Pacific region. Giant Manufacturing Co. Ltd. leverages its vertically integrated manufacturing base in Taiwan to control quality and cost across premium and mass-market lines. Merida Industry Co. Ltd. sustains engineering leadership through sustained R&D investment in carbon fiber frame technology. Hero Cycles Limited anchors its competitive position through extensive distribution depth across India's tier-two and tier-three cities.
A bicycle is a human-powered or electrically assisted vehicle consisting of a tubular metal frame, two wheels, a drivetrain, and steering mechanism, typically manufactured through aluminum welding, carbon fiber layup, or steel tube forming processes, designed for personal transportation, recreation, or sport. Electric bikes now command the fastest expansion trajectory within product type categories, driven by lithium-ion battery cost declines and urban congestion. Hybrid bikes occupy the broadest addressable base among usage purpose segments, spanning recreation and transportation applications with minimal consumer switching costs.
India's PLI scheme and China's GB standards for electric two-wheelers together establish divergent compliance pathways that manufacturers must navigate for market access. Japan's METI energy efficiency regulations and JIS standards further constrain product specifications for imported e-bikes. Stakeholders must monitor regulatory fragmentation between national subsidy regimes and technical standards as the primary determinant of manufacturing location and export feasibility.
Market Dynamics
China's GB standards for electric two-wheelers and India's PLI scheme are creating divergent compliance pathways that manufacturers must navigate simultaneously, forcing dual-track product development and supply chain duplication across the Asia-Pacific region.
Growth Catalysts
- Lithium-ion battery cost compression:Cell price declines are expanding e-bike addressable markets into India's tier-three cities and Southeast Asian urban centers previously priced out of electrification.
- Japan's METI energy efficiency mandates:Regulatory pressure on urban transport emissions is accelerating fleet electrification for last-mile delivery operators in Tokyo and Osaka metropolitan zones.
- Jiangsu-Zhejiang production clustering:Concentrated component ecosystems enable rapid prototyping cycles and compressed lead times for carbon fiber frame iterations.
Market Restraints
- Aluminum and steel input volatility:Raw material price swings compress margin buffers for welded-frame manufacturers dependent on commodity spot markets.
- Single-source battery dependency:Concentration of cylindrical cell supply within Chinese tier-one producers creates vulnerability for assemblers in Vietnam and Indonesia.
- Regulatory fragmentation:India's BIS certification requirements diverge from China's GB standards, forcing redundant testing protocols for cross-border product flows.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:E-bike penetration rates below regional averages present first-mover positioning for brands establishing localized assembly.
- India's PLI scheme for electric mobility:Production-linked incentives are channeling capital toward domestic manufacturing capacity for export-oriented suppliers.
- Subscription and fleet-as-a-service models:Commercial operators in Australian and Japanese urban cores are piloting usage-based procurement replacing outright purchase.
Industry Challenges
- Carbon fiber layup technician scarcity:Specialized composite manufacturing skills concentrate in Taiwan and select Chinese coastal provinces, constraining quality scaling.
- Multi-standard certification timelines:Parallel BIS, GB, and JIS approval processes extend product launch cycles by 8-14 months for regional platform strategies.
- Legacy dealer network integration:Established mechanical-bike service infrastructure requires retraining investment to support e-bike diagnostics and battery management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bicycle Market |
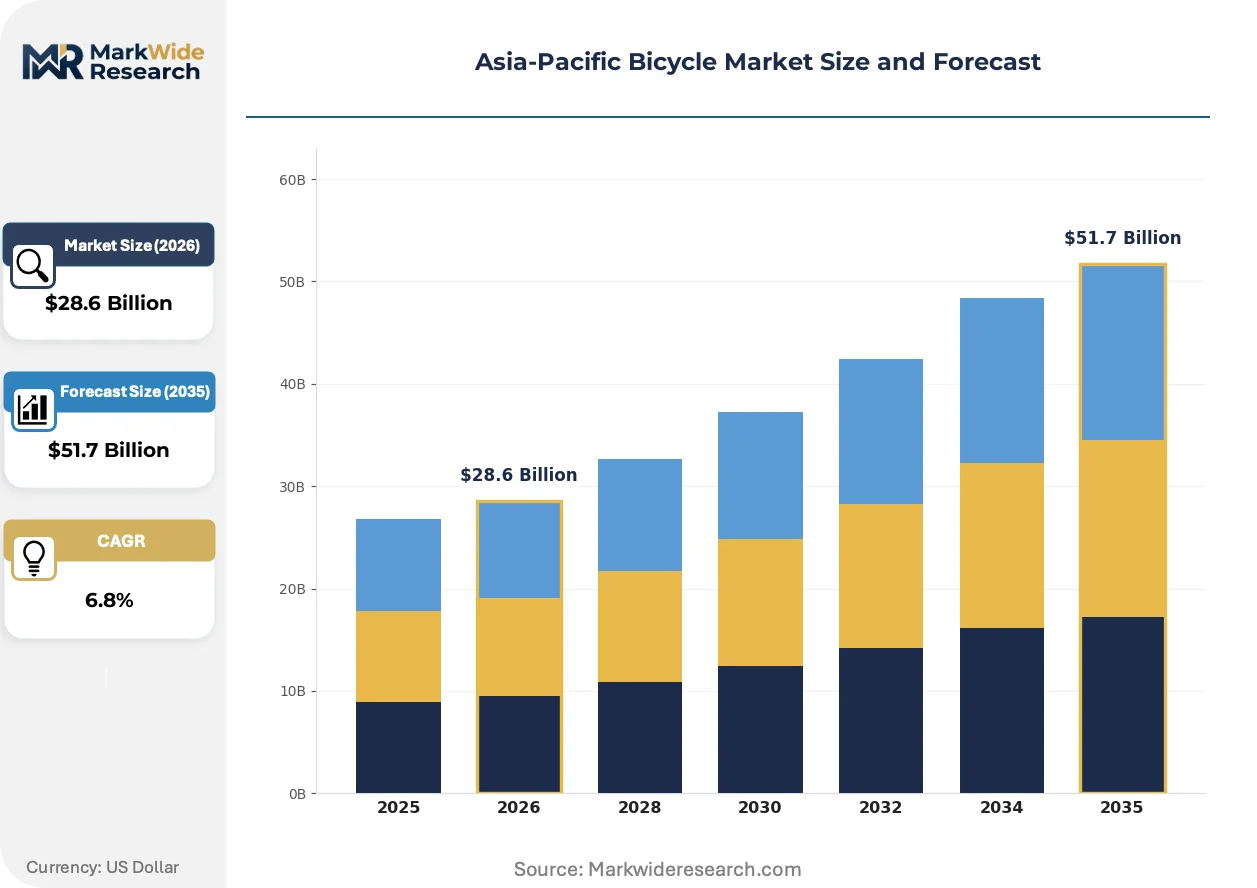
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain Bike, Road Bike, Hybrid Bike, Electric Bike End User: Adults, Children, Fitness Enthusiasts, Commuters Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Department Stores Usage Purpose: Recreation, Sports, Transportation, Adventure |
| Companies Covered | Giant Manufacturing Co. Ltd., Merida Industry Co. Ltd., Yadea Group Holdings Ltd., AIMA Technology Group Co. Ltd., Yamaha Motor Company, Hero Cycles Limited, NIU Technologies, Panasonic, Bridgestone Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bicycle Market Strategic Shifts
Telematics integration and connected vehicle architectures are redefining product value propositions across the Asia-Pacific bicycle market, shifting competitive differentiation from hardware specifications to data-enabled service ecosystems.
Integrated GPS-IoT modules embedded in handlebar stems are digitizing theft recovery and usage analytics for fleet operators. Japanese logistics companies and Australian municipal bike-share programs are deploying these systems at scale. The technology is digitizing insurance underwriting and maintenance scheduling, converting hardware sales into recurring revenue relationships.
China's GB 42296-2022 standard for lithium-ion battery safety is mandating thermal runaway containment and smart battery management systems across all domestic e-bike sales. Manufacturers serving the Chinese market must redesign pack architectures and source fire-resistant casing materials. The regulation is compressing informal aftermarket battery replacement channels while elevating certified OEM service networks.
Direct-to-consumer channel expansion is fragmenting traditional wholesale-distributor hierarchies that dominated bicycle retail for decades. Urban millennials in Seoul, Singapore, and Sydney are configuring specifications online and receiving doorstep assembly. This pattern is most pronounced in premium e-bike categories where customization and subscription financing options displace standardized dealer inventory models.
Asia-Pacific Bicycle Market Segmentation
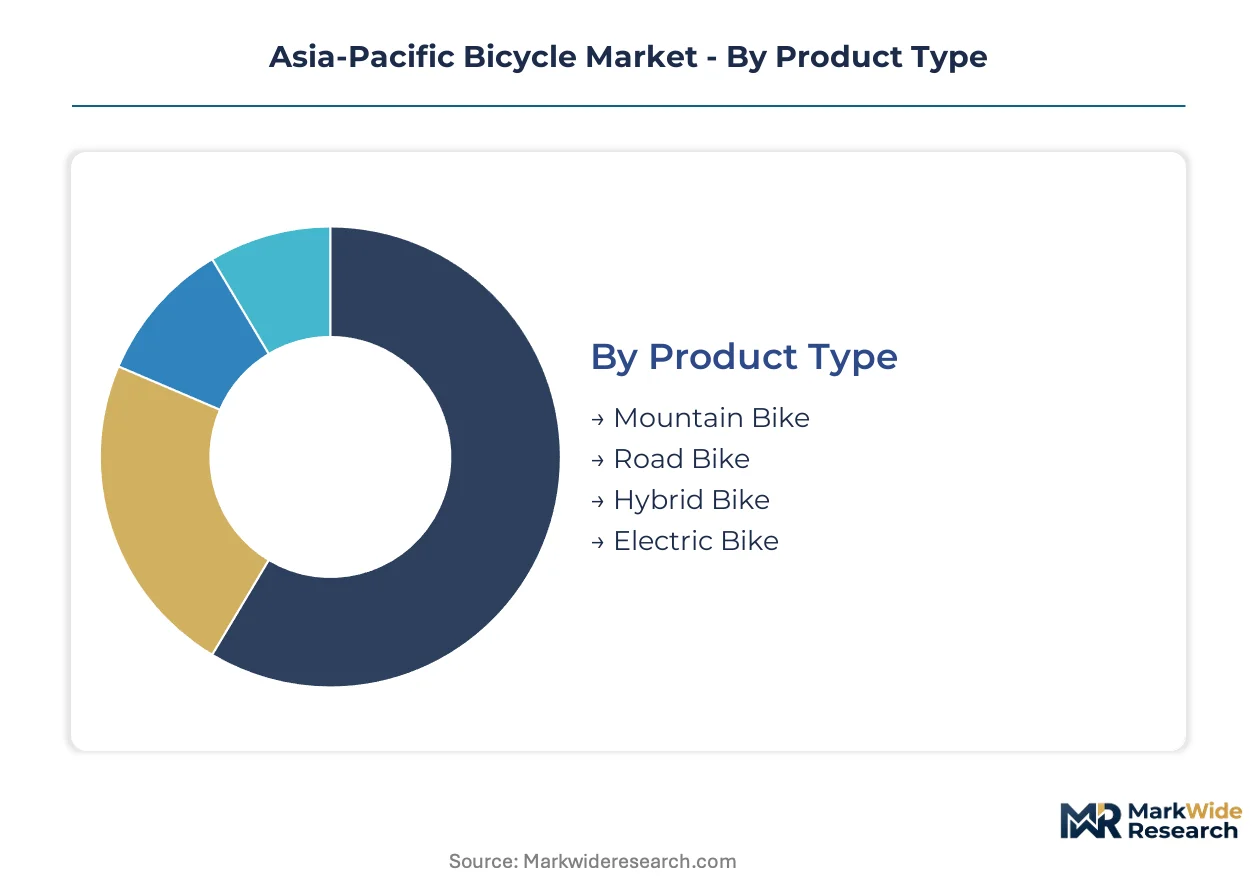
Segmentation in the Asia-Pacific bicycle market reveals divergent growth vectors across electrification, urban mobility, and channel digitization. Understanding these partitions enables manufacturers to allocate R&D and distribution investments against divergent regulatory and consumer environments.
Product Type:
Cost tier stratification separates premium carbon fiber platforms from mass-market aluminum and steel alternatives, with electrification premiums reshaping price architecture across all categories.
- Mountain Bike:Suspension-equipped frames with 27.5-inch or 29-inch wheel configurations dominate technical trail riding. Demand concentrates in Australia's Blue Mountains and Japan's Nagano Prefecture, where adventure tourism operators refresh fleet inventories annually.
- Electric Bike:Lithium-ion powered pedal-assist systems with 250W-750W motors now penetrate India's tier-three cities as battery costs compress. Jiangsu and Zhejiang production clusters supply 80% of regional e-bike motor controllers.
- Road Bike:Drop-handlebar designs optimized for paved surfaces with carbon fiber or aluminum frames serve competitive cycling and fitness segments.
- Hybrid Bike:Flat-handlebar configurations blending road efficiency with trail durability capture the broadest addressable consumer base across urban commuting and recreational use.
Electric bikes hold installed capacity. Hybrid bikes are rotating up the share rankings.
End User:
Application focus distinguishes performance-oriented purchasers from utility-driven buyers, with fitness and commuting segments driving divergent product specification priorities.
- Commuters:Urban professionals in Tokyo, Seoul, and Sydney prioritize integrated lighting, fenders, and rack compatibility for daily transport. Japan's METI efficiency mandates accelerate fleet electrification among corporate last-mile delivery operators.
- Fitness Enthusiasts:Power meter integration, heart rate monitor compatibility, and aerodynamic frame geometries define purchasing criteria. Demand clusters in Australia's eastern seaboard metropolitan gyms and Japan's corporate wellness programs.
- Adults:General recreational riders seeking durability and comfort for weekend use represent volume foundation across mass-market channels.
- Children:Size-scaled frames with coaster brakes and training wheel compatibility serve family purchase occasions through department store and online channels.
Commuters command production scheduling priority. Fitness enthusiasts are climbing the fastest in margin contribution.
Distribution Channel:
Customer type determines service intensity requirements, with premium purchasers demanding technical consultation and mass-market buyers prioritizing convenience and price transparency.
- Online Retail:Direct-to-consumer platforms enable specification customization and subscription financing for premium e-bike categories. Urban millennials in Seoul, Singapore, and Sydney configure purchases digitally with doorstep assembly delivery.
- Specialty Stores:Mechanic-staffed showrooms provide fitting services, test ride facilities, and post-sale maintenance for performance-oriented segments. These outlets anchor brand positioning in Taiwan and Japanese urban cores.
- Supermarkets:High-volume, low-margin mass-market bikes with standardized specifications serve impulse and gift purchase occasions.
- Department Stores:Mid-tier family-oriented inventory with seasonal promotional cycles captures children's bike and recreational hybrid demand.
Online retail is gaining share fastest. Specialty stores retain pricing power in premium tiers.
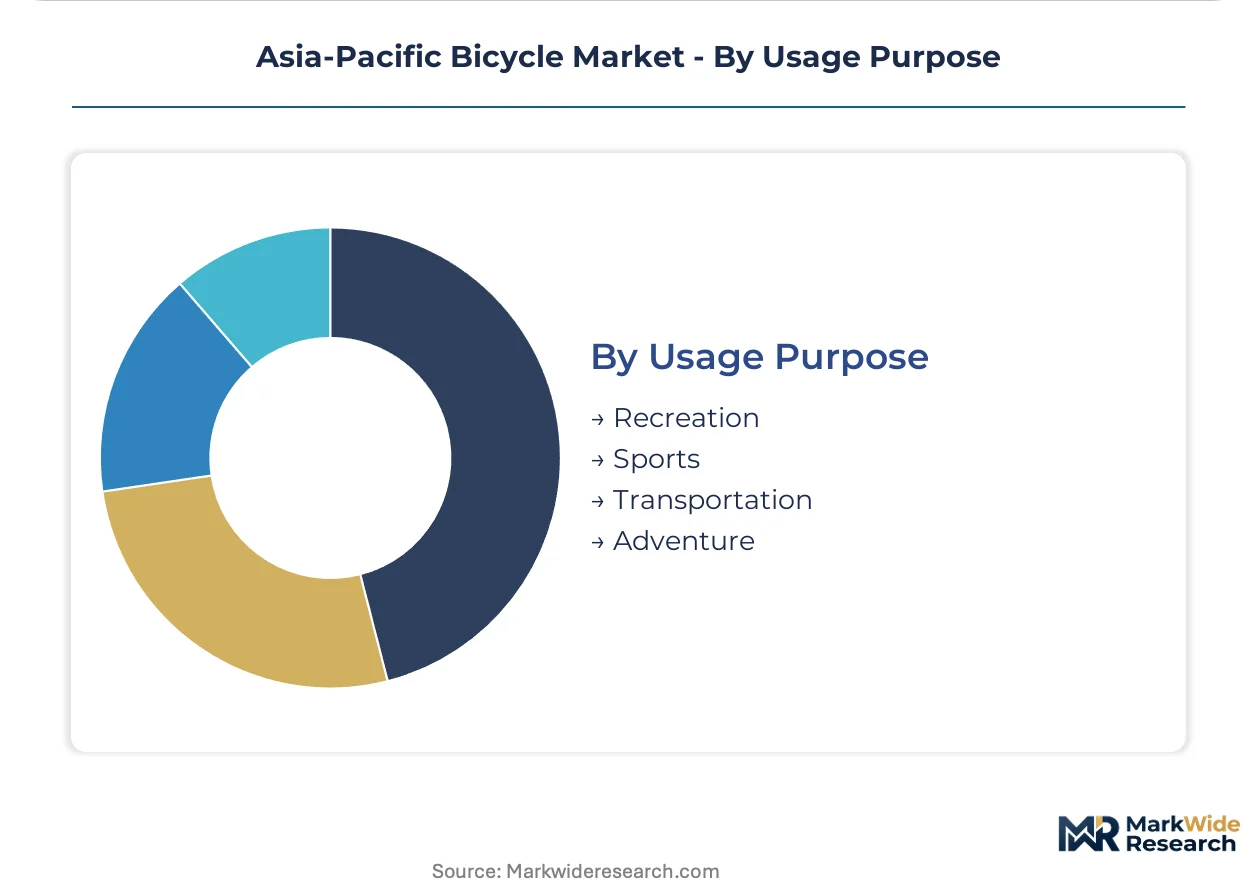
Usage Purpose:
Volume concentration varies by geography, with transportation applications dominating dense Asian megacities and recreation commanding share in Australian and Japanese suburban markets.
- Transportation:Utility-focused specifications with cargo capacity, weather protection, and theft-deterrent features address urban mobility substitution. India's PLI scheme for electric mobility channels investment toward domestic manufacturing for this segment.
- Recreation:Comfort-oriented geometry and accessory compatibility support weekend leisure riding. Australian municipal bike-share programs and Japanese resort operators deploy connected telematics for fleet management.
- Sports:Race-legal specifications with weight minimization and aerodynamic optimization serve competitive cycling federations and event organizers.
- Adventure:Expedition-capable designs with frame bag mounts and multi-terrain tire clearance support bikepacking and long-distance touring.
Transportation holds installed capacity. Recreation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex anchors Asia-Pacific bicycle trade flows, handling over 60% of regional component imports and finished exports through integrated container terminals and bonded assembly zones.
China
Jiangsu and Zhejiang provinces concentrate 80% of regional e-bike motor controller production, with Suzhou and Hangzhou hosting vertically integrated carbon fiber frame operations. GB 42296-2022 battery safety standards mandate thermal runaway containment systems, forcing pack architecture redesigns across domestic manufacturers. The Yangtze River Delta cluster enables rapid prototyping cycles through concentrated component ecosystems.
India
Tier-three urban centers drive e-bike penetration as lithium-ion cell prices compress entry-level price points. The PLI scheme for electric mobility channels capital toward Ludhiana and Pune assembly operations, incentivizing domestic manufacturing capacity for export-oriented suppliers. BIS certification requirements diverge from Chinese GB standards, creating redundant testing protocols for cross-border flows.
Japan
Tokyo and Osaka metropolitan zones accelerate fleet electrification for last-mile delivery operators under METI energy efficiency mandates. JIS standards constrain imported e-bike specifications, favoring domestic producers with established compliance pathways. Nagano Prefecture hosts adventure tourism operators that refresh mountain bike fleet inventories annually.
Australia
The Blue Mountains and eastern seaboard metropolitan gyms concentrate demand for suspension-equipped mountain bikes and power meter-integrated fitness platforms. Municipal bike-share programs in Sydney and Melbourne deploy connected telematics for fleet management. Subscription financing models displace standardized dealer inventory for premium e-bike categories.
Vietnam
E-bike penetration rates lag regional averages, presenting first-mover positioning for brands establishing localized assembly in Ho Chi Minh City industrial zones. Single-source battery dependency on Chinese tier-one producers creates supply vulnerability for Vietnamese assemblers. The country's national standards body is drafting technical regulations for electric two-wheeler safety certification.
Asia-Pacific Bicycle Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream controlling motors, batteries, and frame materials. The vendor base stratifies across three tiers: multinational assemblers with captive distribution, regional specialists serving single-country markets, and contract manufacturers producing white-label inventory for retail chains. Two dominant competitive moves define current positioning: backward integration into battery pack assembly and direct-to-consumer channel expansion fragmenting traditional wholesale hierarchies.
Within the multinational assembler tier, Giant Manufacturing Co. Ltd. and Merida Industry Co. Ltd. exemplify platform integrators leveraging Taiwan-based manufacturing depth, while Hero Cycles Limited anchors the regional specialist archetype through distribution density across India's secondary cities. These three entities represent divergent strategic postures: the Taiwan-based pair emphasize upstream control over carbon fiber and motor controller supply, whereas the Indian incumbent prioritizes last-mile retail penetration over vertical integration.
| Leading Market Players |
|---|
| Giant Manufacturing Co. Ltd. |
| Merida Industry Co. Ltd. |
| Yadea Group Holdings Ltd. |
| AIMA Technology Group Co. Ltd. |
| Yamaha Motor Company |
| Hero Cycles Limited |
| NIU Technologies |
| Panasonic |
| Bridgestone Corporation |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Ningbo port complex channels 60% of regional bicycle trade flows, with container rate volatility compressing margin buffers for Jiangsu-Zhejiang assemblers while amplifying price spreads between premium carbon fiber platforms and mass-market welded-frame alternatives. This logistics corridor's cost dynamics concentrate pricing power among vertically integrated Taiwanese manufacturers and fragment margin structures for Indian and Vietnamese contract assemblers dependent on spot-market aluminum and steel inputs.
Pricing Analysis
Volume-discount tiering separates premium carbon fiber road bikes from standard aluminum commuter frames and economy-grade steel children's models. Certification under China's GB 42296-2022 battery safety standards and Japan's JIS quality tiers command 15-25% price premiums over uncertified alternatives. Cost compression in lithium-ion cells is intensifying pricing pressure at the entry-level e-bike tier, where Indian tier-three city buyers exhibit acute price sensitivity while Tokyo corporate fleet operators prioritize total cost of ownership over upfront acquisition.
Supply Chain Analysis
Contract manufacturing concentrates among Taiwan-based platform integrators and Jiangsu-Zhejiang production clusters, with Giant Manufacturing and Merida Industry anchoring high-end carbon fiber capacity. Battery cell supply draws from Chinese tier-one producers, motor controllers from Suzhou-Hangzhou ecosystems, and raw aluminum from Australian and Indonesian smelters. Single-source dependency on cylindrical lithium-ion cells creates vulnerability for Vietnamese and Indonesian assemblers. Distribution runs through specialty stores in Japanese urban cores, direct-to-consumer platforms in Australian and South Korean metropolitan markets, and fragmented dealer networks across India's secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific bicycle market is approaching a platform-economics inflection where connected telematics and subscription service architectures are displacing transactional hardware sales. Interoperability between battery management systems and fleet management software is creating ecosystem lock-in effects that reshape competitive moats.
For Market Incumbents: Harden defensive positioning through backward integration into battery pack assembly and captive production of motor controllers in Jiangsu-Zhejiang clusters. Certification investment under divergent BIS, GB, and JIS standards creates compliance moats against emerging Vietnamese assemblers. Channel control through retraining legacy dealer networks for e-bike diagnostics preserves service revenue streams against direct-to-consumer entrants.
For New Entrants and Emerging Players: Pursue white-space expansion in Vietnam and Indonesia where e-bike penetration trails regional averages and localized assembly gaps persist. Ho Chi Minh City industrial zones offer first-mover positioning for brands establishing regional battery sourcing alternatives to Chinese tier-one dependency. Direct-to-consumer launch with doorstep assembly and subscription financing captures urban millennial demand in Seoul, Singapore, and Sydney.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists controlling motors, batteries, and carbon fiber frame materials over pure-play assemblers. Long-term viability across the projection horizon rests on ecosystem integration capabilities rather than manufacturing scale alone. Acquisition target archetypes include telematics platform developers and certified battery pack assemblers with cross-border compliance pathways. The signal to watch is subscription revenue attachment rates in Australian and Japanese fleet deployments as an indicator of platform transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Captures margin from cylindrical cell supply concentration and satisfies GB 42296-2022 thermal runaway mandates. |
| Direct-to-Consumer Channel Expansion | Fragments traditional wholesale hierarchies and enables subscription financing for premium e-bike categories in Seoul and Sydney. |
| Telematics Platform Development | Converts hardware sales into recurring revenue through GPS-IoT integration for Japanese logistics and Australian municipal bike-share operators. |
| Multi-Standard Certification Investment | Compresses 8-14 month launch cycles for regional platform strategies spanning BIS, GB, and JIS requirements. |
| Localized Assembly in Vietnam and Indonesia | Addresses underpenetration gaps and reduces tariff exposure and logistics chokepoint vulnerability through Shanghai-Ningbo corridor diversification. |
Study Parameters
Operator-level perspectives from bicycle OEM procurement directors, Tier 1 component supplier sales heads, specialty store owners in Tokyo and Sydney, fleet management operators in Australian municipal bike-share programs, and regulatory affairs specialists at India's BIS and China's SAMR anchored the qualitative base. Primary interview insights combined with secondary validation from customs trade databases, SEC filings of listed bicycle manufacturers, Jiangsu and Zhejiang provincial industrial output statistics, and METI energy efficiency disclosure filings. Bottom-up demand modeling across commuter, fitness, and recreational segments triangulated against top-down production capacity assessments from Taiwan and Yangtze River Delta clusters.
Scenario-bracketing framed optimistic, baseline, and constrained demand pathways across the projection horizon without specifying discrete year markers. Segmentation dimensions modeled included product type electrification tiers, end-user application focus, distribution channel digitization intensity, and usage purpose transportation-recreation-sport-adventure splits. CAGRs derived from installed base turnover rates, replacement cycle compression from connected telematics, and lithium-ion battery cost elasticity parameters. Industry-specific forecast inputs incorporated PLI scheme incentive trajectories for Indian electric mobility and METI fleet electrification mandate compliance timelines for Japanese last-mile operators.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese battery cell producers to forward-integrate into finished e-bike assembly, or sudden tariff escalations disrupting Shanghai-Ningbo corridor flows, would shift outcomes beyond modeled ranges. Cross-checking against IEA urban mobility electrification benchmarks and national bicycle association registration data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Backboard Market
Sports Equipment
Swimming Gear Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Quad Skate Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Soccer Gear Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Inflatable Sleds Market
Sports Equipment
Windsurf Masts Market
Sports Equipment
Baseball Equipment Market
Sports Equipment
Global Golf Rangefinders Market
Sports Equipment
Field Hockey Equipment Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Global Skateboard Market