
 Edge Computing in Healthcare Market | 2026-2036
Edge Computing in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Edge Computing in Healthcare Market Insights
Hospital IT procurement channels is rewriting how edge computing vendors access healthcare buyers, with direct-to-health-system contracts displacing traditional distributor relationships. NVIDIA Corporation leverages its GPU-accelerated edge platforms to dominate AI inference workloads in surgical suites. Microsoft Corporation anchors enterprise trust through Azure Stack HCI deployments that sustain hybrid cloud connectivity for HIPAA-sensitive environments. Cisco Systems, Inc. competes on network equipment integration, controlling the gateway layer where clinical data first leaves the device tier.
Edge computing in healthcare deploys localized processing nodes—typically sub-50ms latency architectures with hardware-level encryption and containerized orchestration—to execute clinical analytics without transmitting protected health information to distant cloud data centers. Software solutions capture expanding margin pools as hospitals prioritize Kubernetes-based orchestration platforms over commodity hardware. Remote monitoring and surgical robotics represent the fastest-growing application segments, with predictive analytics remaining nascent due to integration complexity with legacy EHR systems. Edge devices and gateways still occupy the largest volume share, though margin compression intensifies as Intel Corporation and Amazon Web Services, Inc. extend their silicon-to-cloud stacks into this layer.
FDA cybersecurity guidance for networked medical devices and HIPAA breach notification rules jointly shape product development roadmaps, forcing vendors to embed hardware root-of-trust modules and audit logging at the edge node level. The EU AI Act adds conformity assessment burdens for any edge-deployed diagnostic algorithm marketed in Europe, creating divergent certification pathways that IBM Corporation and Google LLC must navigate separately. Stakeholders should monitor how national health IT agencies in Japan and South Korea adapt their data localization standards, as these will determine which deployment models—on-premises, hybrid, or sovereign cloud—gain regulatory preference across major healthcare economies.
Market Dynamics
Hospital procurement teams now demand sub-50ms latency guarantees with hardware-level encryption, forcing vendors to redesign edge node architectures around containerized orchestration rather than traditional server stacks.
Growth Catalysts
- Surgical robotics latency requirements:Real-time haptic feedback in operating suites mandates localized processing nodes that bypass cloud round-trips entirely.
- HIPAA breach notification rules:Stringent US enforcement of protected health information safeguards accelerates on-premises edge deployments over hybrid alternatives.
- German diagnostic imaging networks:Siemens Healthineers and regional hospital consortiums build sovereign edge infrastructure to process radiology workloads locally.
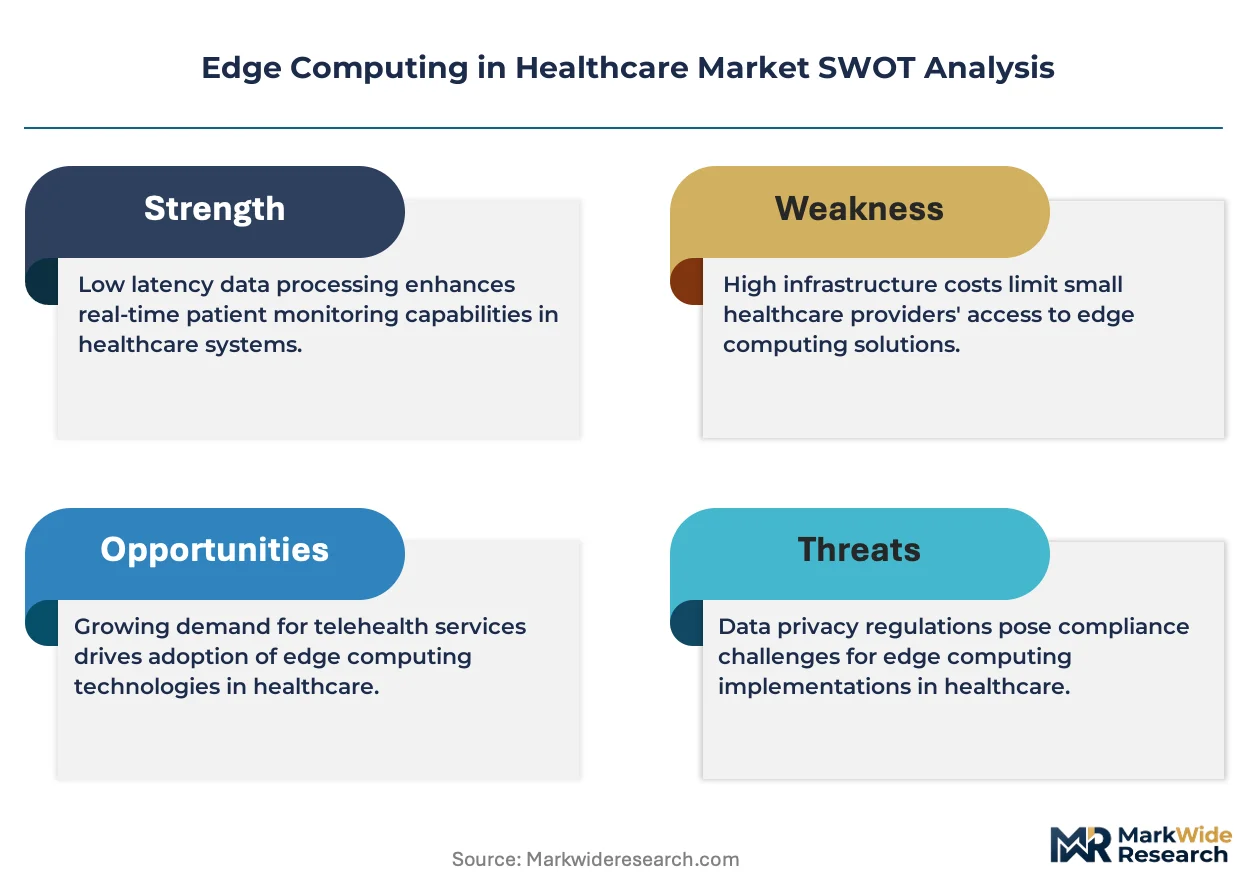
Market Restraints
- Silicon supply concentration:GPU and AI accelerator fabrication concentrates in Taiwan and South Korea, creating single-source vulnerability for edge inference hardware.
- EU AI Act conformity assessments:Divergent certification pathways for diagnostic algorithms marketed across Europe extend product launch timelines by 12-18 months.
- Legacy EHR integration complexity:Proprietary data formats in Cerner and Epic systems resist standardized API connectivity with Kubernetes-based edge platforms.
Strategic Opportunities
- Remote patient monitoring white space:Post-acute care facilities in Japan adopt wearable-connected edge gateways for continuous vital sign analytics outside hospital walls.
- FDA cybersecurity guidance tailwinds:Pre-market submission requirements for networked medical devices create first-mover advantage for vendors embedding hardware root-of-trust modules.
- 5G private network convergence:Telecommunications carriers partner with health systems to deploy dedicated spectrum slices for guaranteed-quality edge connectivity in surgical suites.
Industry Challenges
- Container orchestration talent scarcity:Health IT departments lack Kubernetes-certified engineers capable of managing distributed edge node fleets across multiple facilities.
- Hardware root-of-trust capex burden:Each edge gateway requires dedicated secure enclave chips that add 15-20% to unit manufacturing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge Computing in Healthcare Market |
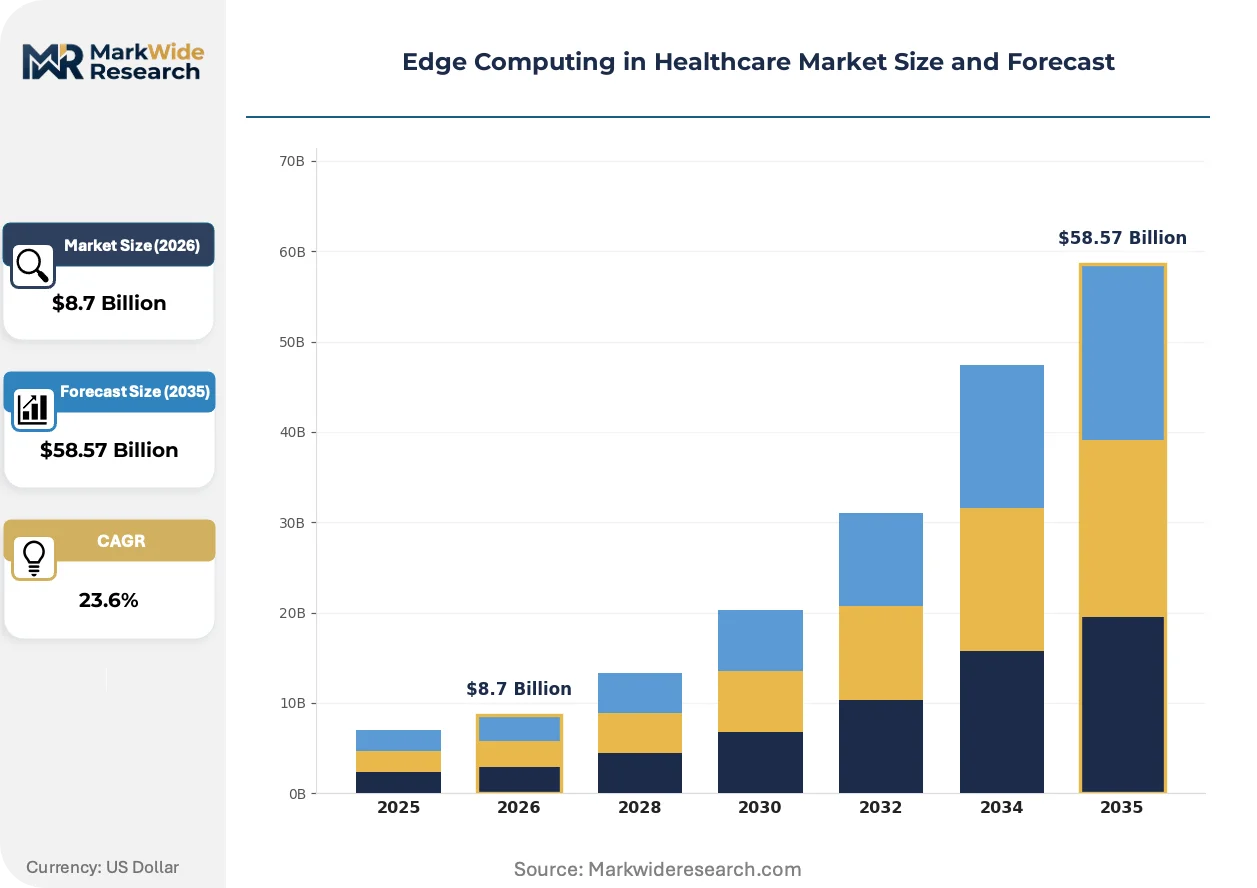
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $58.57 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edge Devices, Gateways, Network Equipment, Software Solutions Application: Remote Monitoring, Telemedicine, Surgical Robotics, Predictive Analytics End User: Hospitals, Clinics, Laboratories, Patient-Centric Organizations Deployment Model: On-Premises, Hybrid, Public Cloud, Private Cloud |
| Companies Covered | NVIDIA Corporation, Microsoft Corporation, Cisco Systems, Inc., Intel Corporation, Amazon Web Services, Inc., IBM Corporation, Hewlett Packard Enterprise Company, Google LLC, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge Computing in Healthcare Market Trends and Innovations
Healthcare edge computing is pivoting from hardware-centric deployments toward software-defined orchestration layers that abstract infrastructure complexity from clinical workflows.
Federated learning architectures are rendering obsolete the centralized model training paradigm that previously required raw patient data migration to distant cloud facilities. Academic medical centers in Boston and Stanford pilot these privacy-preserving frameworks for multi-site oncology studies. The approach compresses regulatory approval timelines by eliminating cross-border data transfer agreements.
The EU AI Act's risk-based classification system imposes conformity assessment burdens on edge-deployed diagnostic algorithms marketed in Europe. Medium-risk clinical decision support tools now require notified body certification before commercial deployment. German radiology AI vendors restructure product roadmaps to segregate European and non-European feature sets.
Direct contracting between health systems and edge platform vendors displaces traditional value-added reseller channels. Hospital procurement teams negotiate enterprise-wide Kubernetes licenses spanning dozens of facilities. This channel shift concentrates buying power among integrated delivery networks in California and Texas.
Edge Computing in Healthcare Market Segmentation
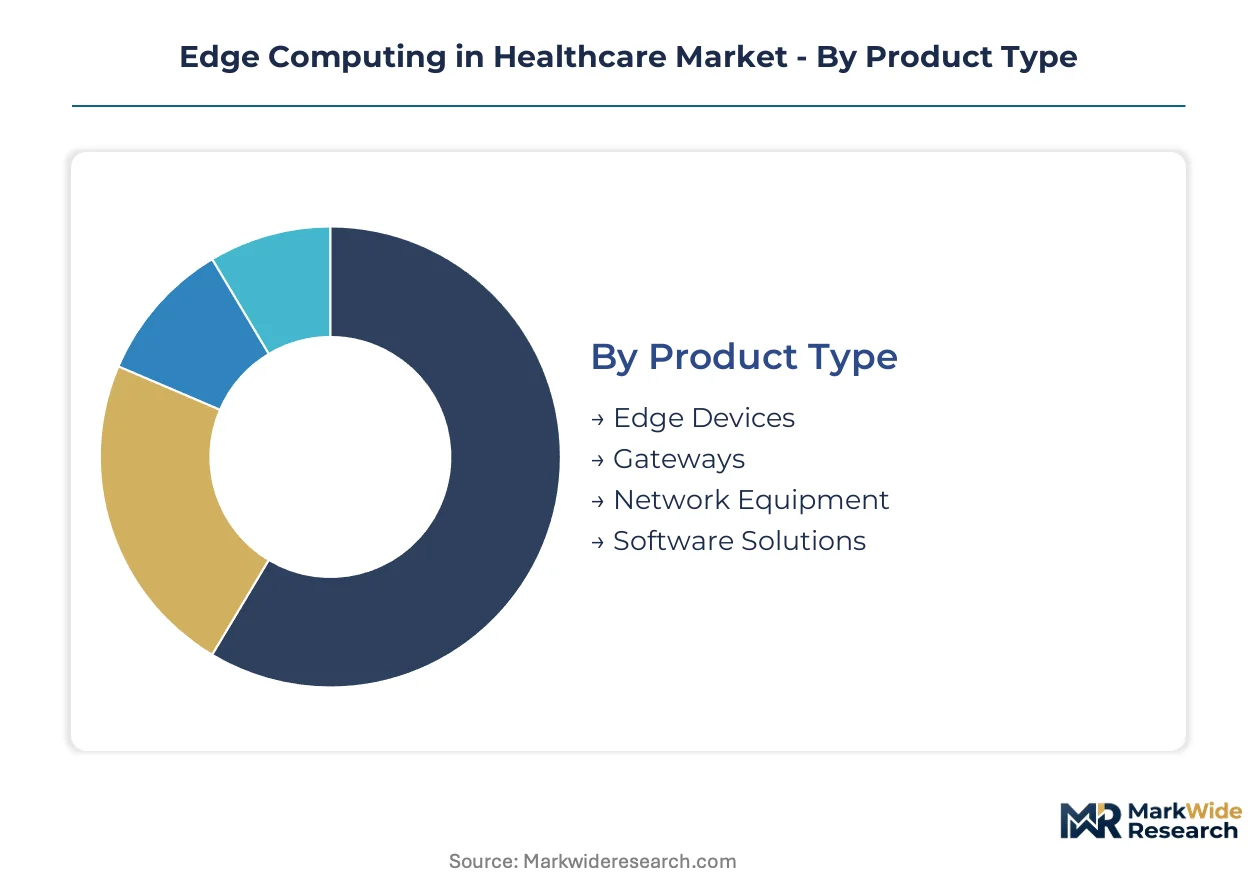
Edge computing in healthcare fragments across four distinct dimensions that determine procurement priorities, regulatory exposure, and margin architecture. Product type dictates hardware versus software spend ratios. Application use cases separate latency-critical surgical workloads from bandwidth-tolerant remote monitoring. End user categories expose divergent IT sophistication levels. Deployment models carry HIPAA and EU AI Act compliance implications that reshape vendor selection criteria.
Product Type:
The use-case spectrum spans bedside physiological sensors to centralized orchestration platforms, with each tier commanding different procurement cycles and technical specifications.
- Edge Devices:Physiological monitors, infusion pumps, and imaging modalities embed ARM-based processors with hardware root-of-trust modules for FDA-compliant cybersecurity. Demand concentrates in surgical suites at Massachusetts General Hospital and Cleveland Clinic where sub-10ms latency governs patient safety.
- Gateways:Aggregation nodes running containerized workloads consolidate streams from 50-200 bedside devices, typically deployed with Intel Xeon-D or NVIDIA Jetson silicon. German university hospitals in Berlin and Munich prioritize these for radiology PACS integration with legacy Siemens infrastructure.
- Software Solutions:Kubernetes orchestration platforms and AI inference engines capture expanding margin pools as hospitals depreciate commodity hardware.
- Network Equipment:Clinical-grade switches and 5G small cells control the gateway layer where protected health information first leaves the device tier.
The dominant share belongs to Edge Devices, while Software Solutions is closing the gap fastest.
Application:
Latency tolerance separates emergency interventions from routine surveillance, with reimbursement codes increasingly tied to real-time analytics capabilities.
- Surgical Robotics:Haptic feedback loops between surgeon console and patient-side manipulators mandate sub-10ms processing with zero packet loss. Stanford Medicine and Johns Hopkins deploy localized NVIDIA Clara Holoscan nodes that bypass cloud round-trips entirely for robotic-assisted prostatectomy.
- Remote Monitoring:Post-acute wearables transmit encrypted vital signs through residential edge gateways to predictive algorithms. Japan's Ministry of Health subsidizes these deployments for congestive heart failure patients discharged to rural Hokkaido and Okinawa prefectures.
- Telemedicine:Video consultation platforms with AI-augmented diagnostic overlays serve outpatient clinics lacking on-site specialist coverage.
- Predictive Analytics:Sepsis detection and deterioration forecasting algorithms remain nascent due to Epic and Cerner EHR integration complexity.
Surgical Robotics commands the premium pricing tier, yet Remote Monitoring is expanding most quickly as post-acute reimbursement shifts to value-based models.
End User:
IT maturity and capital availability fragment procurement authority across facility types with divergent vendor relationship histories.
- Hospitals:Integrated delivery networks in California and Texas negotiate enterprise-wide Kubernetes licenses spanning dozens of facilities, displacing traditional value-added reseller channels. Their procurement teams demand sub-50ms latency guarantees with hardware-level encryption.
- Clinics:Federally qualified health centers and rural outpatient facilities prioritize managed service models with predictable opex structures over capital-intensive on-premises deployments.
- Laboratories:High-throughput sequencing and digital pathology workflows drive specialized edge configurations with GPU acceleration for genomic variant calling.
- Patient-Centric Organizations:Home health agencies and accountable care organizations pilot wearable-connected edge gateways for continuous monitoring outside institutional walls.
Hospitals retain the dominant procurement volume, though Patient-Centric Organizations are gaining share fastest as reimbursement shifts toward home-based care.
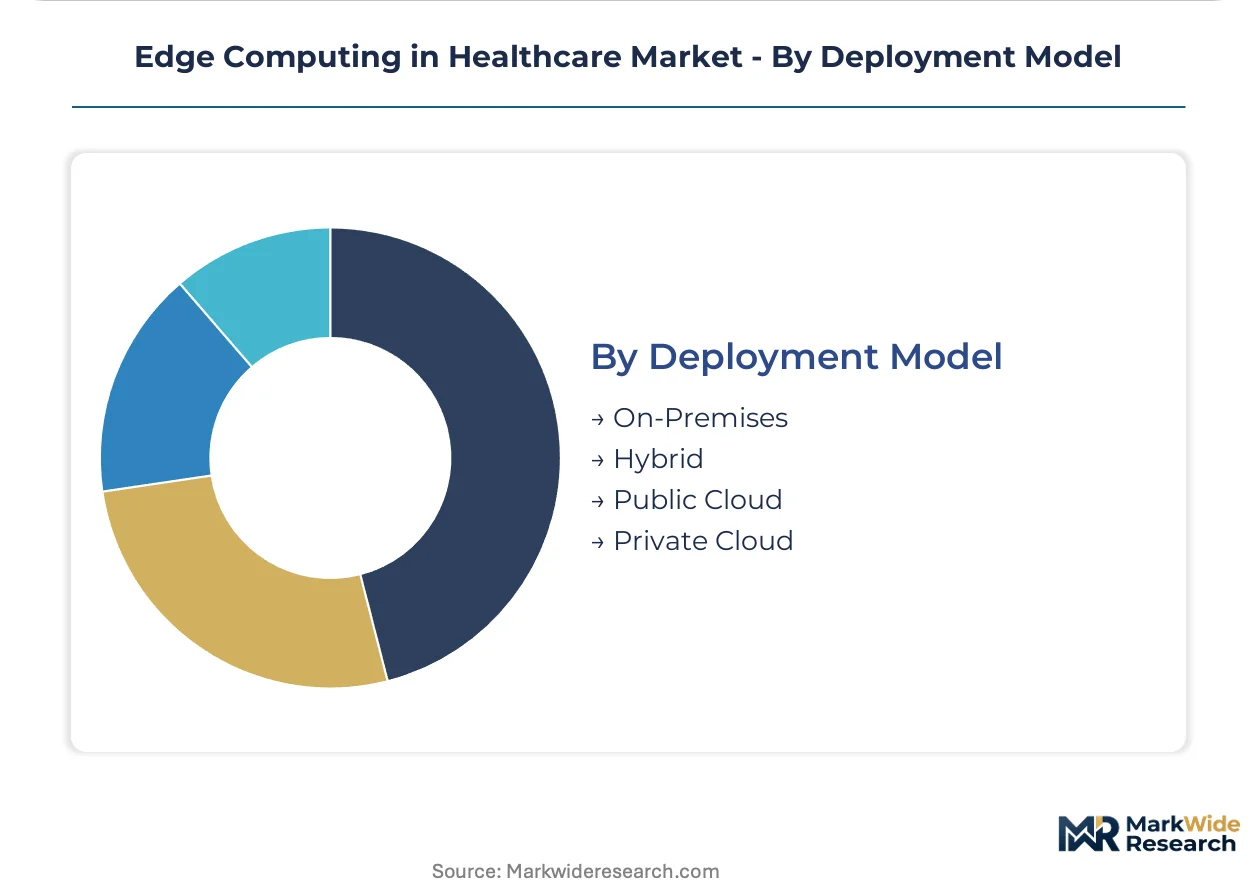
Deployment Model:
Data sovereignty mandates and breach notification exposure reshape infrastructure location decisions across HIPAA-covered entities and EU AI Act-regulated algorithms.
- On-Premises:Fully air-gapped edge nodes with hardware root-of-trust modules satisfy FDA cybersecurity guidance and HIPAA breach notification constraints. Stringent US enforcement accelerates these deployments over hybrid alternatives at academic medical centers.
- Hybrid:Azure Stack HCI and AWS Outposts sustain cloud connectivity for non-clinical workloads while keeping protected health information within facility firewalls.
- Private Cloud:Sovereign infrastructure operated by telecommunications carriers or regional health information exchanges serves German diagnostic imaging networks requiring EU data residency.
- Public Cloud:Hyperscaler regions process de-identified training data and non-clinical analytics with limited penetration in primary diagnostic workflows.
On-Premises deployments hold the dominant share, while Hybrid configurations are climbing the fastest as health systems seek operational flexibility without regulatory exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains its position through dense fiber-optic backbones linking academic medical centers in Boston, Baltimore, and Houston. Submarine cables landing at Virginia Beach and Los Angeles anchor transatlantic and transpacific data flows for healthcare AI training clusters.
United States
Stanford Medicine and Johns Hopkins drive surgical robotics edge deployments requiring sub-10ms latency for haptic feedback loops. FDA cybersecurity guidance for networked medical devices mandates hardware root-of-trust modules in pre-market submissions. Massachusetts General Hospital and Cleveland Clinic operate localized NVIDIA Clara Holoscan nodes for robotic-assisted procedures.
Germany
Siemens Healthineers and regional hospital consortiums build sovereign edge infrastructure for real-time diagnostic imaging workloads. The EU AI Act imposes conformity assessment burdens on medium-risk clinical decision support tools requiring notified body certification. Berlin and Munich university hospitals prioritize gateway nodes for radiology PACS integration with legacy Siemens infrastructure.
Japan
The Ministry of Health subsidizes wearable-connected edge gateways for congestive heart failure patients discharged to rural Hokkaido and Okinawa prefectures. METI standards for medical device data security shape procurement specifications for post-acute monitoring networks. Tokyo academic medical centers pilot federated learning architectures for multi-site oncology studies.
South Korea
Seoul National University Hospital and Samsung Medical Center deploy 5G private network slices for guaranteed-quality edge connectivity in surgical suites. MFDS cybersecurity requirements for connected medical devices accelerate hardware-level encryption adoption. The Pangyo Techno Valley cluster hosts GPU fabrication facilities supplying AI accelerators for edge inference hardware.
United Kingdom
NHS England procurement frameworks favor Azure Stack HCI deployments sustaining hybrid cloud connectivity for HIPAA-equivalent data environments. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device certification with EU MDR timelines. London teaching hospitals and the Oxford-Cambridge arc concentrate Kubernetes orchestration talent for distributed edge node management.
Edge Computing in Healthcare Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability layers: silicon-to-cloud stacks, network infrastructure integration, and clinical workflow software. GPU-accelerated platforms, enterprise hybrid cloud systems, and container orchestration engines represent the dominant strategic archetypes. Competitive positioning intensifies through direct-to-health-system contracting displacing traditional distributor channels, and through embedded hardware security modules satisfying FDA pre-market submission requirements.
Within the GPU-accelerated tier, NVIDIA Corporation anchors AI inference workloads in surgical suites through localized processing nodes. Microsoft Corporation exemplifies the enterprise hybrid cloud archetype with Azure Stack HCI deployments that sustain connectivity for HIPAA-sensitive environments. Cisco Systems, Inc. occupies the network integration position, controlling gateway layers where clinical data first leaves device tiers.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Intel Corporation |
| Amazon Web Services, Inc. |
| IBM Corporation |
| Hewlett Packard Enterprise Company |
| Google LLC |
| Siemens Healthineers |
| Others |
Pricing and Supply Chain Analysis
Taiwanese GPU and AI accelerator fabrication concentrates upstream supply for edge inference hardware, anchoring margin capture downstream at the Kubernetes orchestration and software-defined networking layers where hospital procurement teams concentrate buying power.
Pricing Analysis
Volume-discount tiering structures dominate enterprise-wide Kubernetes licenses negotiated by integrated delivery networks spanning dozens of facilities. Pricing stratifies across premium surgical robotics configurations with sub-10ms latency guarantees, standard gateway nodes for radiology PACS integration, and economy-tier remote monitoring wearables. Cost compression in gateway hardware intensifies as Intel and Amazon Web Services extend silicon-to-cloud stacks into this layer. Federally qualified health centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between Taiwan and the United States dominates supply chain risk planning for edge computing vendors dependent on NVIDIA and TSMC fabrication. GPU silicon, ARM-based secure enclave chips, and 5G small cell components draw from Taiwan, South Korea, and Japan. Single-source vulnerability concentrates in advanced node semiconductor manufacturing. Distribution runs through direct-to-health-system contracts displacing traditional value-added reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge computing in healthcare represents a high-growth disruption as FDA cybersecurity guidance and the EU AI Act impose hardware-level security mandates that reshape vendor certification requirements and procurement specifications simultaneously.
For Market Incumbents: Harden market position through backward integration into secure enclave chip supply and embedded hardware root-of-trust module development. Expand Kubernetes certification training programs to address container orchestration talent scarcity threatening deployment timelines. Deepen channel control via direct enterprise-wide licensing with integrated delivery networks. For New Entrants and Emerging Players: Post-acute remote monitoring networks in rural Japan and congestive heart failure discharge programs represent the most penetrable entry points. Federated learning architectures for multi-site oncology studies offer regulatory pathway advantages. Pursue managed service models with predictable opex structures over capital-intensive on-premises deployments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed edge gateway manufacturers lacking software orchestration capabilities. Five-to-ten year viability hinges on successful transition from hardware-centric to software-defined revenue models. Monitor FDA pre-market submission timelines for networked medical devices as inflection indicator for first-mover advantage realization.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware Root-of-Trust Module Integration | FDA cybersecurity guidance mandates embedded secure enclaves for pre-market networked device submissions. |
| Kubernetes Orchestration Platform Development | Hospital IT departments prioritize containerized workload management over commodity hardware procurement. |
| EU AI Act Conformity Assessment Pathway | Notified body certification for medium-risk diagnostic algorithms enables European market access. |
| 5G Private Network Partnership | Telecommunications carriers deploy dedicated spectrum slices for guaranteed-quality surgical suite connectivity. |
| Federated Learning Architecture Deployment | Privacy-preserving multi-site oncology studies eliminate cross-border data transfer agreement complexity. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR submissions, hospital procurement databases, and hyperscaler capex disclosures preceded structured interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and edge platform engineering leads. Primary fieldwork combined with secondary validation through CMS Medicare reimbursement data and GPO contract repositories. Bottom-up facility-level deployment estimates triangulated against top-down vendor revenue segmentation.
Assumptions held fixed include HIPAA breach notification enforcement intensity and EU AI Act risk classification timelines, while variables included 5G private network deployment pace and Kubernetes adoption curves across hospital IT departments. Segmentation modeling spanned product type, application use case, end user category, and deployment architecture. CAGRs derived from logistic diffusion curves fitted to historical technology adoption patterns in healthcare IT, with surgical robotics latency requirements and remote monitoring reimbursement shifts as key demand-side inputs.
Practitioners should monitor FDA cybersecurity guidance enforcement actions and EU notified body certification backlogs for early signals of regulatory pathway congestion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
One-Way Degassing Valve Market
Others
Latin America Smart Home Market
Others
Global Hydraulics Market
Others
Space Power Supply Market
Others
Global Microcontroller Embedded Systems Market
Others
Small Office Home Office (SOHO) Servers Market
Others
Canada Laser Hair Removal Market
Others
Brazil Cane Sugar Market
Others
Bitcoin Mining Hardware Market
Others
Spain Smart Home Market
Others
Molecular Spectroscopy Market
Others
Mobile Computer Market
Others
Managed Testing Services Market
Others
Running Apparel Market
Others
Medium-Voltage Switchgear Market
Others
Global Crowdsourced Testing Market