
 Global Humidifier Market | 2026-2036
Global Humidifier Market Size, Share, and Industry Trends Forecast 2026-2036
Global Humidifier Market Intelligence
Hospital-grade humidification specification is bifurcating the competitive landscape into clinical-precision and consumer-welfare tiers. Condair Group leverages its industrial-scale electrode steam technology to dominate commercial infrastructure contracts across Europe. Honeywell International Inc. sustains channel control through integrated HVAC distribution partnerships in North America. Dyson Ltd. differentiates via ultrasonic transducer miniaturization and air-quality sensor fusion in premium residential units.
A humidifier is an electromechanical device that adds water vapor to ambient air through ultrasonic nebulization, evaporative wicking, or thermal steam generation, typically maintaining relative humidity between 30% and 60% to prevent respiratory irritation, material degradation, and electrostatic discharge. Ultrasonic product types occupy the fastest-expanding tier due to silent operation and low energy draw, though steam vaporizer segments retain higher margin pools in clinical and industrial settings. Cool mist technology leads residential volume while warm mist variants anchor premium positioning in cold-climate agricultural facilities and museum conservation environments.
The EPA regulates antimicrobial additive claims and ozone emission thresholds for electronic air cleaners sold in the United States, compelling manufacturers to reformulate water tank materials and UV-C sterilization modules. The EU Ecodesign Directive and REACH constrain energy consumption benchmarks and substance restrictions for plastics and biocides in European market access. China's GB standards and SAMR certification requirements impose additional electromagnetic compatibility and safety testing layers for imported units. Stakeholders must monitor evolving harmonization between energy-efficiency mandates and antimicrobial performance claims as regulatory divergence between Washington, Brussels, and Beijing intensifies compliance complexity.
Market Dynamics
Hospital-grade humidification specification is bifurcating the competitive landscape into clinical-precision and consumer-welfare tiers, forcing manufacturers to maintain dual R&D tracks while navigating diverging certification pathways.
Growth Catalysts
- EPA antimicrobial mandates:The EPA's tightening ozone emission thresholds for electronic air cleaners compel manufacturers to reformulate water tank materials and UV-C sterilization modules, creating upgrade cycles across installed bases.
- Healthcare infrastructure expansion:Hospital systems in the United States, China, and Germany are expanding adoption of precision humidity control systems to reduce surgical site infections and protect sterile processing environments.
- Ultrasonic miniaturization:Advances in piezoelectric transducer density enable silent, low-energy residential units that displace noisier evaporative alternatives in noise-sensitive urban apartments.
Market Restraints
- Input cost volatility:Rare earth elements in piezoelectric ceramics and semiconductor components for sensor modules expose margins to supply disruptions concentrated in Chinese processing facilities.
- REACH substance restrictions:The EU Ecodesign Directive and REACH constrain biocide formulations and plastic additives, forcing reformulation of tank materials and antimicrobial coatings ahead of compliance deadlines.
- Technical limitation of ultrasonic scaling:Mineral dust deposition from unfiltered tap water limits ultrasonic adoption in hard-water regions without integrated demineralization cartridges, adding cost and maintenance burden.
Strategic Opportunities
- Underpenetrated Indian residential segment:India's BIS certification framework and PLI scheme for domestic manufacturing create entry pathways for cost-optimized ultrasonic units targeting emerging middle-class households.
- Agricultural greenhouse convergence:Integration of humidity control with precision irrigation and LED grow-light systems opens controlled-environment agriculture as a high-margin vertical beyond traditional HVAC channels.
- EU Green Deal retrofit incentives:Building renovation subsidies in Germany and France accelerate replacement of legacy steam humidifiers with heat-recovery evaporative systems in commercial real estate.
Industry Challenges
- Electromagnetic compatibility certification:China's SAMR and GB standards impose extended testing timelines for wireless-enabled smart humidifiers, delaying product launches by 6-12 months versus non-connected equivalents.
- Skill gap in clinical validation:Shortage of biomedical engineers capable of executing FDA 510(k) equivalence studies for hospital-grade units lengthens time-to-market for precision humidity systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Humidifier Market |
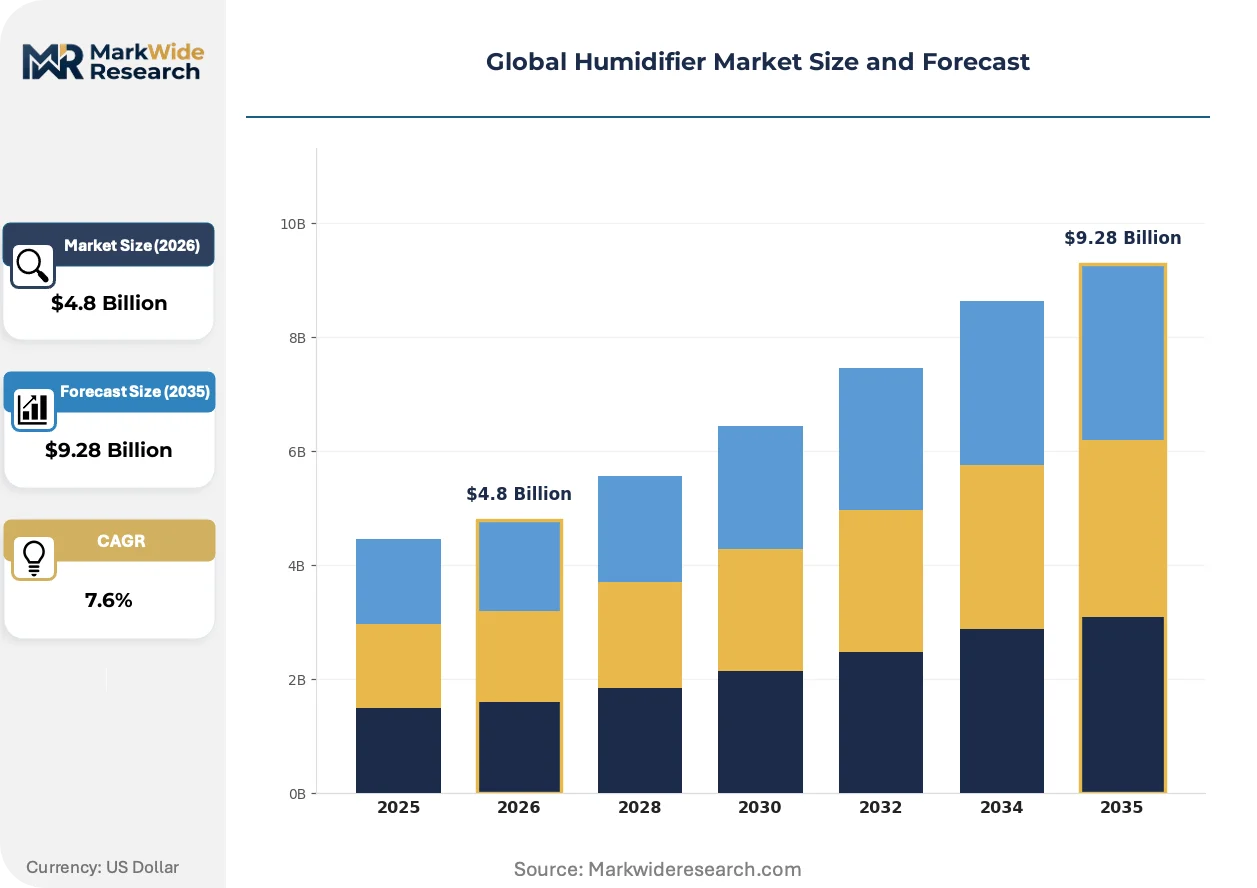
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Evaporative, Steam Vaporizer, Impeller, Central Humidifier Technology: Cool Mist, Warm Mist, Hybrid, Ultrasonic Transducer, Piezoelectric, Mechanical Application: Residential Spaces, Commercial Offices, Educational Institutes, Data Centers, Museums, Greenhouses End User: Households, Corporate Workplaces, Research Facilities, Cultural Institutions, Agricultural Facilities |
| Companies Covered | Condair Group, Procter & Gamble, Honeywell International Inc., Carel Industries, Newell Brands, Dyson Ltd., Boneco AG, Guardian Technologies, Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Humidifier Market Strategic Shifts & Innovations
Electromechanical humidification is fragmenting into application-specific architectures as sensor fusion, connectivity, and energy recovery systems redefine performance benchmarks across residential, commercial, and clinical segments.
Ultrasonic transducer arrays with integrated TDS (total dissolved solids) sensors and automatic demineralization cartridge switching are decomposing the traditional trade-off between silent operation and water quality tolerance. Residential buyers in Japanese and South Korean apartment complexes are adopting these self-monitoring units at accelerating rates. The technology is compressing market share for basic evaporative wick systems that require manual maintenance and produce audible fan noise.
REACH substance restrictions and the EU F-Gas Regulation are compelling manufacturers to eliminate hydrofluorocarbon-based cooling circuits in combined dehumidifier-humidifier units sold in European markets. Industrial consequence includes accelerated R&D into thermoelectric and desiccant wheel alternatives for climate control systems. Germany's KBA and building energy auditors are most affected, specifying heat-recovery ventilators with integrated evaporative humidification in new commercial construction.
Facility managers in United States hospital systems are unbundling humidification service contracts from bundled HVAC maintenance agreements, creating direct procurement relationships with specialized OEMs. The segment being disrupted is traditional mechanical contractor distribution, replaced by manufacturer-direct service subscriptions with predictive maintenance telemetry. This pattern is most visible in California and Texas healthcare networks where energy benchmarking mandates drive demand for performance-guaranteed humidity control.
Global Humidifier Market Segmentation
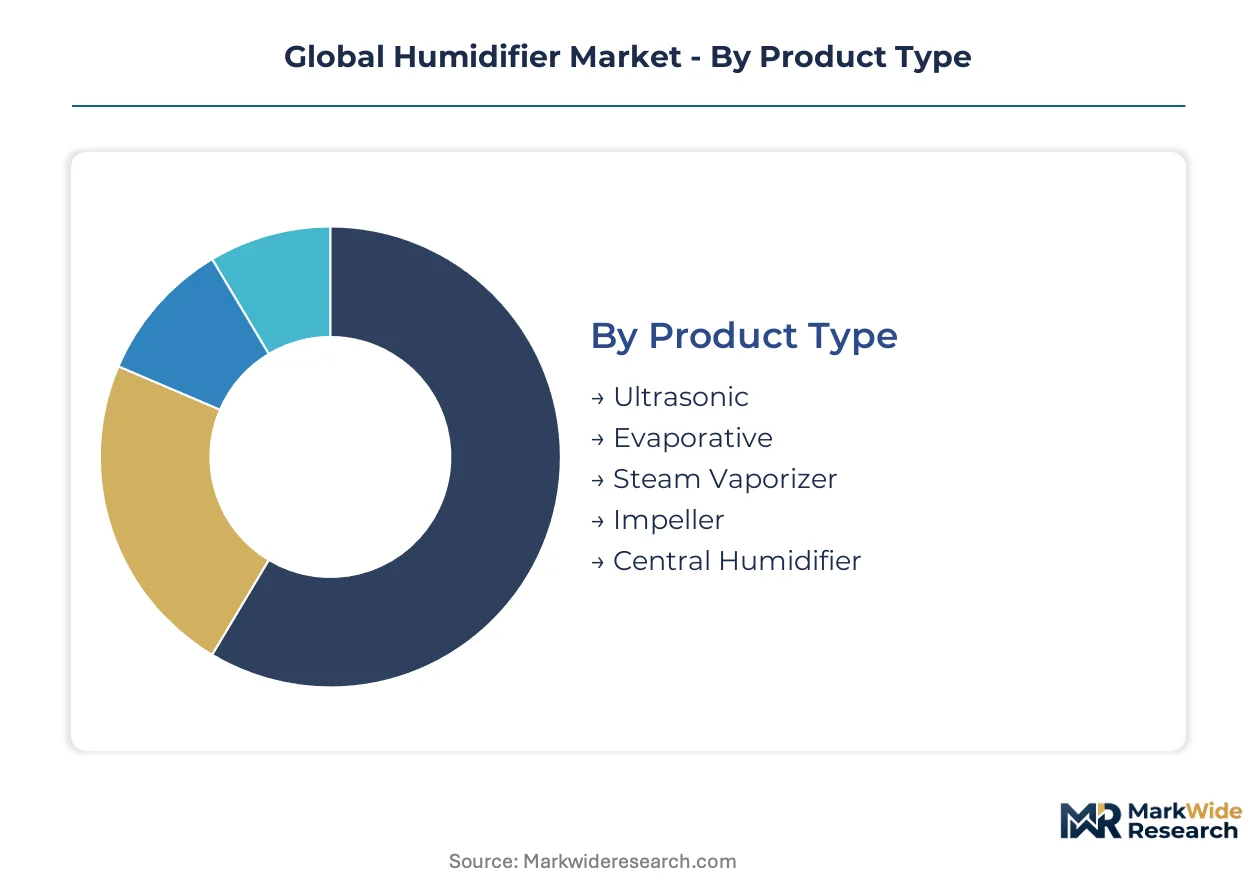
Humidifier segmentation reflects divergent channel economics: mass retail drives residential volume, specialized HVAC contractors control commercial installation, and biomedical distributors manage hospital-grade procurement. Technology choices cascade through these channels, determining margin structure and certification burden.
Product Type:
Channel mix varies sharply by product architecture: ultrasonic and evaporative units flow through big-box retail and e-commerce, while central and steam systems depend on mechanical contractor networks and specification engineering.
- Ultrasonic:Piezoelectric transducers nebulize water into micron-scale droplets without heating elements, enabling silent operation below 30 decibels. Demand clusters in Japanese and South Korean apartment complexes where noise ordinances restrict evaporative alternatives, though mineral dust deposition from hard water constrains adoption without demineralization cartridges.
- Evaporative:Wicking filters draw water across large surface areas with forced-air evaporation, naturally self-regulating output as ambient humidity rises. Corporate workplaces in Germany specify these units for open-plan offices where the white noise of integrated fans masks conversational privacy concerns.
- Steam Vaporizer:Thermal boiling eliminates microbial contamination without chemical additives, serving clinical environments where FDA 510(k) equivalence studies validate performance claims.
- Impeller:Rotating disks fling water against diffusers to create cool mist, occupying budget retail tiers with simpler mechanical construction and lower price points.
- Central Humidifier:Duct-integrated systems serve whole-building humidity control through existing HVAC infrastructure, requiring professional installation and recurring maintenance contracts.
Evaporative units dominate installed base in North American commercial real estate. Ultrasonic products are where expansion concentrates, climbing fastest in Asian residential markets.
Technology:
Cost tier segmentation separates premium sensor-fusion systems from commodity mechanical alternatives, with warm mist commanding price premiums in cold-climate applications and cool mist anchoring volume production.
- Cool Mist:Ambient-temperature output eliminates burn risks for pediatric and elderly users, making these systems mandatory in California eldercare facilities per state licensing requirements.
- Warm Mist:Heated vaporization raises output temperature to 100-105°F, preferred in Minnesota and Wisconsin agricultural greenhouses where cold infiltration would otherwise condense cool mist before distribution.
- Hybrid:Switchable temperature modes adapt to seasonal load variation, reducing inventory complexity for retailers serving climates with wide annual temperature swings.
- Ultrasonic Transducer:High-frequency ceramic oscillators at 1.6-2.4 MHz generate droplets below 5 microns, the core technology enabling miniaturization in premium residential units.
- Piezoelectric:Lead zirconate titanate ceramics convert electrical to mechanical energy with 95%+ efficiency, though rare earth supply concentration in Chinese processing creates input cost volatility.
- Mechanical:Basic motor-driven fans and wicks serve price-sensitive segments with minimal electronic content, simplifying compliance with India's BIS electromagnetic compatibility standards.
Cool mist technology anchors volume production across mass-market channels. Warm mist variants capture margin concentration in agricultural and conservation applications.
Application:
Customer type segmentation distinguishes between individual purchasing decisions and institutional procurement processes, with museums and data centers requiring specialized specification support.
- Residential Spaces:Individual households purchase through retail and direct-to-consumer channels, with smart home integration driving replacement cycles in connected-device ecosystems.
- Commercial Offices:Facility managers procure through integrated HVAC service contracts, though unbundling trends in Texas and California healthcare networks are creating direct OEM relationships.
- Educational Institutes:K-12 districts and universities specify units for indoor air quality compliance, with EPA antimicrobial additive claims influencing bid evaluations.
- Data Centers:Precision humidity control prevents electrostatic discharge and corrosion in server environments, requiring ±3% RH accuracy unavailable in consumer-grade products.
- Museums:Conservation-grade specifications protect organic artifacts from dimensional instability, with the Smithsonian and Rijksmuseum setting technical benchmarks for the segment.
- Greenhouses:Controlled-environment agriculture integrates humidity with irrigation and lighting systems, opening high-margin verticals beyond traditional HVAC channels.
Residential spaces command unit volume leadership. Data centers and museums represent the steepest expansion trajectory as precision requirements intensify.
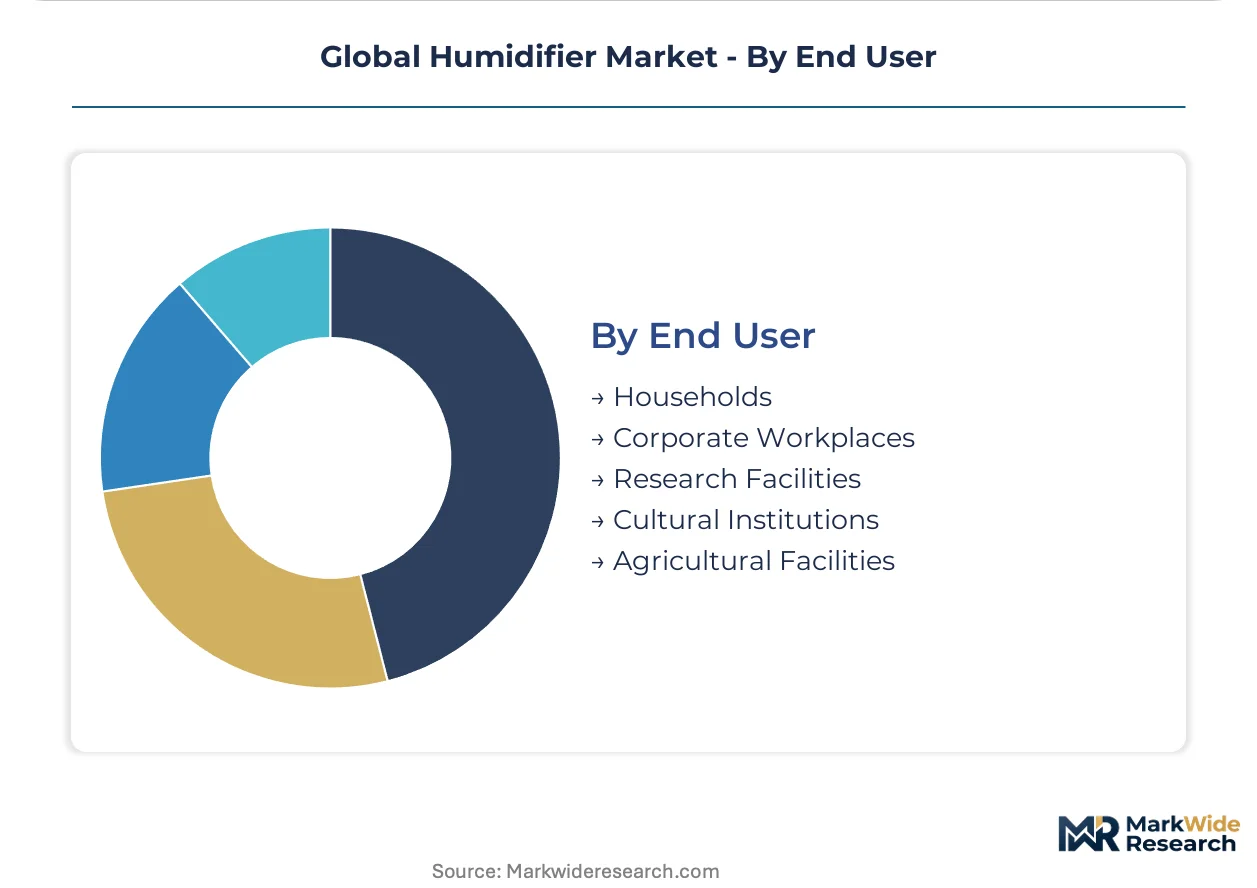
End User:
Geographic concentration of end-user demand shapes regional manufacturing investment, with agricultural facilities clustering in specific climate zones and cultural institutions concentrating in historic urban centers.
- Households:Individual consumers prioritize silent operation and aesthetic integration, with Dyson's design-led positioning capturing premium urban demographics.
- Corporate Workplaces:Enterprise procurement favors standardized fleet deployments with centralized monitoring, driving demand for Wi-Fi-enabled units with cloud-based maintenance alerts.
- Research Facilities:Biomedical and pharmaceutical laboratories require ISO 14644 cleanroom compatibility, with FDA-regulated environments mandating documented calibration protocols.
- Cultural Institutions:Museum conservation departments specify tight humidity tolerances for loan exhibition agreements, with international traveling shows demanding portable precision systems.
- Agricultural Facilities:Dutch and Israeli greenhouse operators lead adoption of integrated climate control, with humidity tied to precision irrigation and LED grow-light optimization.
Households dominate unit shipments. Research facilities and agricultural operations are where specification complexity and margin expansion concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, China, and Germany together absorb the majority of humidifier trade flows, with import dependency shifting toward Asian manufacturing hubs while European and North American markets concentrate on specification-grade and clinical-precision systems.
United States
Healthcare infrastructure expansion and residential smart-home integration drive demand across California and Texas hospital networks. EPA antimicrobial mandates and ozone emission thresholds compel manufacturers to reformulate water tank materials and UV-C sterilization modules. The Southeast manufacturing corridor around Atlanta hosts distribution centers serving retail and HVAC contractor channels.
Germany
Commercial real estate retrofit cycles and museum conservation specifications anchor demand in Berlin and Munich metropolitan areas. The EU Ecodesign Directive and F-Gas Regulation constrain energy consumption benchmarks and eliminate hydrofluorocarbon-based cooling circuits in combined climate control units. Baden-Württemberg's precision engineering cluster supplies heat-recovery ventilator integration components.
China
Domestic middle-class consumption and export manufacturing capacity expansion concentrate demand in the Yangtze River Delta and Pearl River Delta. SAMR certification requirements and GB standards impose electromagnetic compatibility and safety testing layers for wireless-enabled smart units. Shenzhen's electronics ecosystem dominates piezoelectric transducer and sensor module production.
India
Emerging middle-class households in Delhi-NCR and Mumbai Metro drive residential ultrasonic adoption. BIS certification framework and PLI scheme for domestic manufacturing create entry pathways for cost-optimized units. Tamil Nadu's industrial corridor hosts assembly operations targeting price-sensitive volume segments.
Japan
Apartment complex noise ordinances and aging population respiratory health priorities sustain demand in Tokyo and Osaka metropolitan areas. METI energy-efficiency guidelines and JIS standards shape product specifications for silent operation below 30 decibels. Nagoya's ceramics industry supplies high-frequency piezoelectric components.
Global Humidifier Market Key Industry Players
Concentration sits with diversified industrial conglomerates and specialized climate-control engineering firms that have secured specification relationships with healthcare networks and commercial HVAC contractors. The competitive structure bifurcates between clinical-precision systems requiring FDA 510(k) equivalence validation and consumer-welfare tiers competing on design integration and smart-home connectivity. Three archetypes dominate: industrial-scale steam technology specialists, integrated HVAC distribution partners, and design-led premium residential brands. Capacity expansion in Asian manufacturing hubs and strategic partnerships with biomedical distributors represent the primary competitive vectors.
Among diversified multinational manufacturers, Honeywell International Inc. and Dyson Ltd. exemplify contrasting positioning archetypes, with the former anchoring integrated HVAC channel control and the latter representing design-led premium residential differentiation. Condair Group occupies a position within the industrial-scale climate control tier, reflecting European engineering specialization in commercial infrastructure applications. These three entities collectively illustrate the market's segmentation across specification-grade, channel-integrated, and consumer-premium vectors.
| Leading Market Players |
|---|
| Condair Group |
| Procter & Gamble |
| Honeywell International Inc. |
| Carel Industries |
| Newell Brands |
| Dyson Ltd. |
| Boneco AG |
| Guardian Technologies |
| Philips |
| Others |
Cost & Logistics Intelligence
Piezoelectric ceramic substitution for legacy steam-generation components simultaneously concentrates transducer sourcing in Chinese processing facilities and compresses margin pools for ultrasonic unit manufacturers competing against evaporative alternatives. EPA antimicrobial mandates and REACH substance restrictions add compliance cost layers that pricing structures must absorb or pass through to healthcare procurement committees.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with FDA 510(k) certification tier and volume scale driving price differentiation between clinical-precision and consumer-welfare segments. Pricing pressure stems from rare earth input cost volatility in piezoelectric ceramics, while hospital procurement committees demonstrate lowest price sensitivity due to infection-control liability exposure.
Supply Chain Analysis
Strategic stockpile preferences dominate humidifier supply chains as manufacturers buffer against rare earth processing concentration in China and semiconductor component lead time variability. Piezoelectric transducers, UV-C sterilization modules, and sensor electronics draw from Chinese, Japanese, and South Korean production clusters. Single-source vulnerability in lead zirconate titanate ceramics threatens margin stability. Distribution runs through HVAC contractor networks for commercial specification-grade units and big-box retail for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as integrated HVAC systems with built-in humidity control threaten standalone unit demand in new commercial construction.
For Market Incumbents: Fortify specification-grade positioning by deepening FDA 510(k) validation investments and securing exclusive service contracts with California and Texas healthcare networks. Backward integration into piezoelectric ceramic sourcing mitigates Chinese supply concentration risk. For New Entrants and Emerging Players: BIS certification fast-track through India's PLI scheme unlocks cost-optimized ultrasonic penetration of Delhi-NCR and Mumbai Metro residential segments. Agricultural greenhouse integration partnerships in the Netherlands and Israel offer white-space expansion beyond saturated HVAC channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed climate-control engineering firms holding hospital-grade specification relationships. Long-term viability hinges on clinical-precision segment defensibility against integrated HVAC substitution. Watch for unbundling trends in healthcare procurement as inflection signals for direct OEM relationship value.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Condair and Honeywell leverage equivalence studies to defend clinical-tier pricing against consumer-grade entrants. |
| Backward Integration into Ceramics | Transducer captive supply secures margin stability against Chinese rare earth processing volatility. |
| Healthcare Service Contract Unbundling | Texas and California hospital networks create direct procurement relationships bypassing mechanical contractors. |
| Greenhouse Climate System Integration | Dutch and Israeli operators bundle humidity control with precision irrigation and LED optimization. |
| India PLI Manufacturing Localization | Tamil Nadu assembly operations target BIS-compliant cost structures for emerging middle-class demand. |
Research Approach
Operator-level perspectives from HVAC contractors, biomedical engineers, hospital procurement managers, and agricultural facility managers anchored the qualitative base. Primary fieldwork combined with secondary validation from EPA regulatory filings, EU Ecodesign Directive documentation, SAMR certification records, and customs trade data. Bottom-up unit shipment modeling and top-down value aggregation triangulated market sizing across product type, technology, application, and end-user dimensions.
Sensitivity analysis tested forecast robustness across the projection horizon, with segmentation modeling spanning ultrasonic, evaporative, steam, and central system architectures alongside cool mist, warm mist, and hybrid temperature technologies. CAGRs derived from historical trajectory analysis and demand driver elasticity assessment incorporated healthcare infrastructure expansion rates, residential smart-home penetration curves, and agricultural greenhouse investment cycles as industry-specific inputs.
Decision-makers should treat outputs as directional under stable regulatory enforcement and input cost assumptions; material deviation would warrant model refresh. Forecasts reflect documented base-case parameters including EPA antimicrobial mandate timelines and REACH substance restriction implementation schedules. Revision becomes warranted when rare earth supply disruption severity or healthcare procurement unbundling velocity crosses threshold levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Paper Towel Dispenser Market
Household Items
Stainless Steel Vacuum Flask Market
Household Items
Europe & UK Nonstick Cookware Market
Household Items
LAMEA Robotic Pool Cleaner Market
Household Items
Smart Air Purifier Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
North America B2B Air Care Market
Household Items
Portable Iron Market
Household Items
Latex Mattress Market
Household Items
Sleeping Pods Market
Household Items
Portable Showers Market
Household Items
Cast Iron Cookware Market
Household Items
Air Freshener Market
Household Items
Ultrasonic Diffusers Market
Household Items
Hangers Market
Household Items
Electric Soap Dispenser Market