
 Reduced Salt Packaged Foods Market | 2026-2036
Reduced Salt Packaged Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Reduced Salt Packaged Foods Market Analytics
A capital-intensity divergence between multinational reformulators and regional private-label suppliers is rotating competitive advantage toward firms with in-house sodium-reduction laboratories. Nestlé S.A. leverages its global nutrition science network to sustain patent pipelines for potassium-based salt substitutes. PepsiCo, Inc. anchors North American shelf space through direct-store-delivery infrastructure that controls placement velocity for reduced-salt snack variants.
Reduced salt packaged foods are processed consumer goods formulated with sodium chloride levels below conventional equivalents, typically achieved through potassium chloride blends, yeast extracts, or flavor-modifier technologies, and manufactured to maintain shelf stability and sensory profiles comparable to standard formulations. The breads and soups categories dominate current volume as mature staples where sodium reduction technology has achieved cost parity, while sauces and snacks represent faster-growing margin pools where flavor-engineering premiums still command price separation from conventional lines. Health-conscious consumers and seniors constitute the dominant end-user clusters, though athlete-targeted formulations in pouch packaging are gaining traction through online retailers and specialty health food stores.
The FDA enforces sodium reduction targets through voluntary industry guidelines and mandatory nutrition labeling, while the European Food Safety Authority evaluates novel salt-replacement additives under novel food regulations, and Food Standards Australia New Zealand mandates interpretive front-of-pack health star ratings that penalize high-sodium formulations. These frameworks compel manufacturers to reformulate ahead of enforcement thresholds or risk exclusion from approved procurement lists for institutional buyers. Stakeholders must monitor pending classification decisions on emerging umami-enhancer technologies that could reshape acceptable ingredient panels and unlock new formulation pathways.
Market Dynamics
Recipe reinvention driven by front-of-pack labeling mandates and sodium reduction targets is compressing formulation cycles while concentrating competitive advantage among firms with captive sodium-reduction R&D infrastructure.
Growth Catalysts
- FDA Voluntary Sodium Targets:The FDA's phased sodium reduction guidelines for processed foods are compelling manufacturers to accelerate reformulation timelines ahead of mandatory enforcement thresholds.
- Yeast Extract Flavor Modifiers:Advanced yeast-derived umami enhancers are enabling 30-40% sodium reduction without sensory degradation in soups and sauces.
- German Private-Label Expansion:Dedicated low-sodium product lines at Aldi Süd and REWE are normalizing reduced-salt options across staple categories.
Market Restraints
- Potassium Chloride Supply Concentration:Over 60% of food-grade potassium chloride originates from Saskatchewan potash mines, creating geographic supply vulnerability.
- EFSA Novel Food Assessment Timelines:Emerging salt-replacement additives face 18-24 month approval cycles under EU novel food regulations, delaying product launches.
- Clean-Label Substitution Pressure:Consumer rejection of "chemical-sounding" potassium-based ingredients limits adoption in premium organic segments.
Strategic Opportunities
- Athlete-Targeted Pouch Formats:Electrolyte-balanced reduced-sodium meals for endurance athletes remain underdeveloped in direct-to-consumer channels.
- Australia Health Star Rating Optimization:Reformulation to achieve 4.0+ star ratings unlocks preferred placement in Woolworths and Coles planograms.
- AI-Driven Flavor Mapping:Machine learning convergence with sensory science is identifying non-sodium taste pathways previously undetectable through traditional methods.
Industry Challenges
- Sodium-Reduction Chemist Scarcity:Formulation specialists capable of balancing potassium chloride bitterness with cost constraints command premium compensation packages.
- Legacy Equipment Retrofit Costs:Hygroscopic potassium blends require humidity-controlled mixing environments incompatible with existing sauce production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reduced Salt Packaged Foods Market |
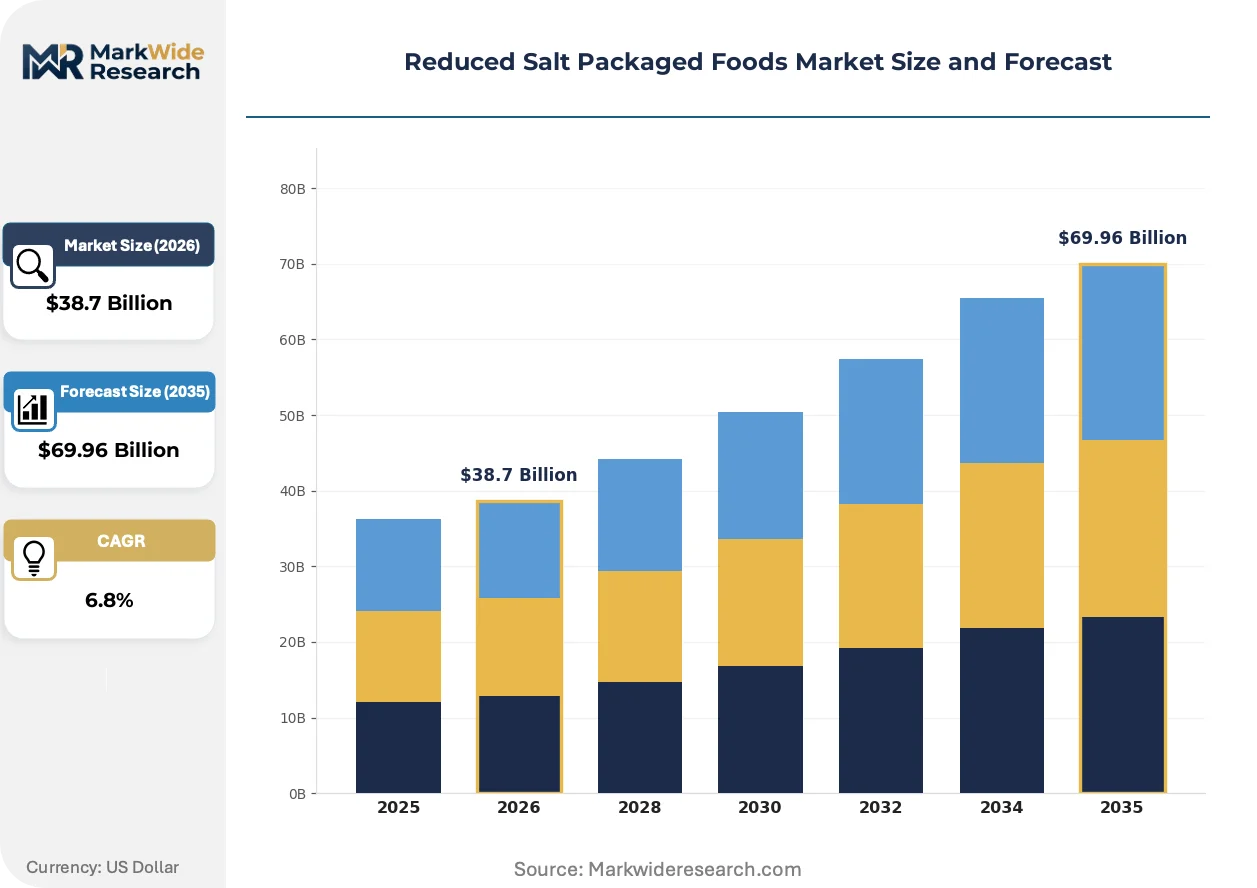
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Soups, Sauces, Snacks End User: Health-Conscious Consumers, Seniors, Athletes, Families Packaging Type: Pouches, Cans, Boxes, Bags Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores |
| Companies Covered | Nestlé S.A., PepsiCo, Inc., General Mills, Inc., The Kraft Heinz Company, Conagra Brands, Inc., Kellogg Company, Unilever PLC, Tyson Foods, Inc., Hormel Foods Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reduced Salt Packaged Foods Market Evolving Landscape
Flavor-engineering breakthroughs and interpretive labeling schemes are recalibrating how manufacturers balance sensory fidelity with regulatory compliance across reformulated product lines.
Fermented flavor bases derived from koji molds and lactic acid bacteria are supplanting conventional salt-reliant taste architectures in premium soup formulations. Specialty retailers and health-conscious seniors are adopting these products at triple the velocity of conventional reduced-sodium lines. This biotechnology shift is compressing R&D timelines for mid-tier manufacturers lacking in-house fermentation capabilities.
The United Kingdom's mandatory front-of-pack traffic-light labeling system now penalizes amber-rated sodium levels in institutional procurement contracts. NHS England and Department for Education catering tenders exclude products exceeding 400mg sodium per serving. Soup and ready-meal manufacturers serving UK healthcare and school channels are accelerating zero-salt-added line extensions to maintain contract eligibility.
Subscription-based personalized nutrition platforms are fragmenting traditional supermarket purchasing patterns for reduced-sodium staples. Direct-to-consumer brands like those targeting hypertensive seniors through telehealth partnerships are capturing shelf-space-equivalent volumes without retail intermediation. This channel displacement is most pronounced in Germany and the Netherlands where digital health integration exceeds southern European adoption rates.
Reduced Salt Packaged Foods Market Segmentation
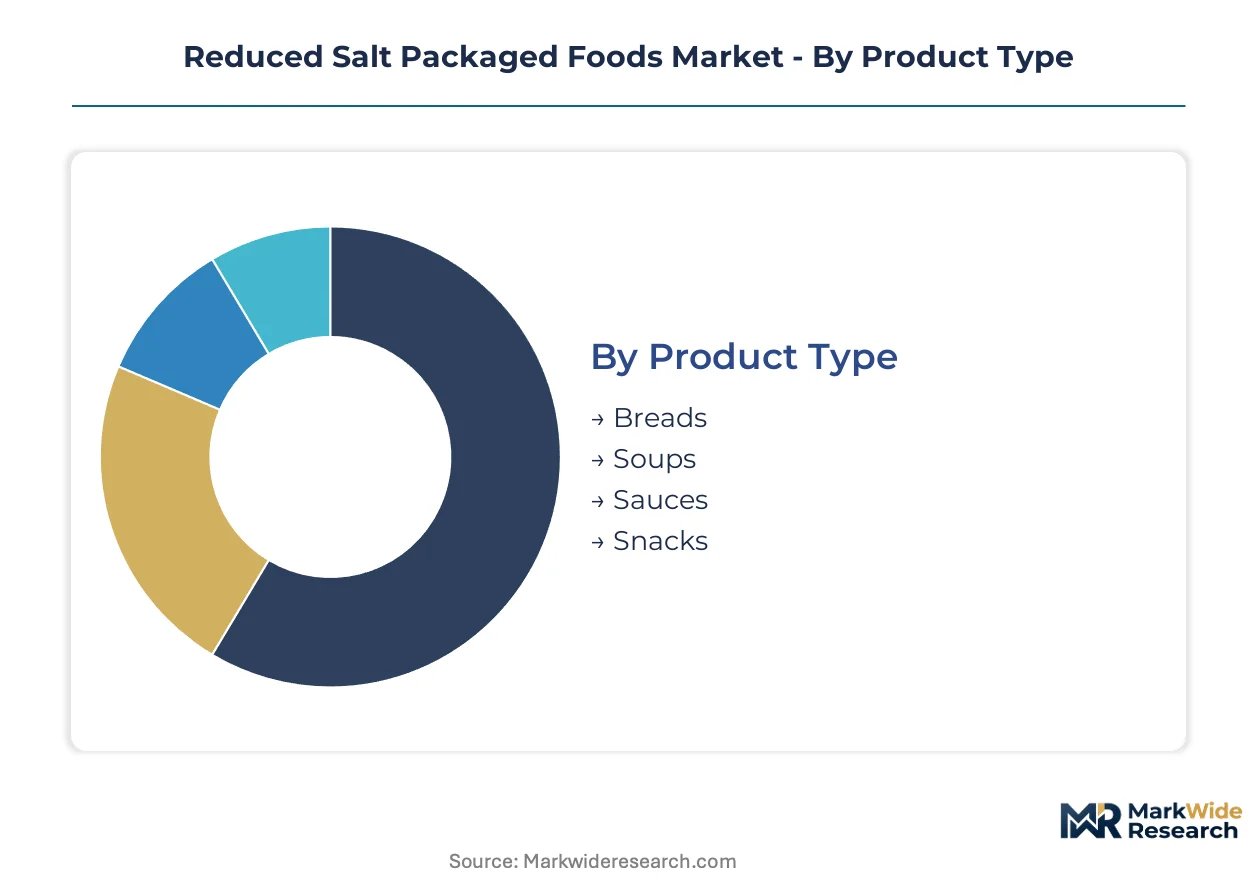
Segmentation in reduced salt packaged foods reveals how regulatory pressure and sensory engineering constraints reshape competitive positioning across formulation complexity tiers. Manufacturers must match sodium-reduction technology maturity to channel-specific velocity requirements and end-user risk tolerance profiles.
Product Type:
FDA voluntary sodium targets and EFSA novel food assessments create divergent compliance burdens across maturity-staggered categories, concentrating R&D investment where flavor-modifier science has achieved cost parity.
- Breads:Mature sodium-reduction technology using potassium chloride blends and yeast extracts maintains structural integrity in industrial baking applications. German private-label retailers Aldi Süd and REWE have normalized low-sodium bread lines through dedicated shelf space allocation, compressing price premiums versus conventional formulations.
- Soups:Liquid matrices enable homogeneous distribution of umami-enhancer technologies, supporting 30-40% sodium reduction without sensory degradation. NHS England catering tenders exclude products exceeding 400mg sodium per serving, forcing zero-salt-added line extensions for institutional contract eligibility.
- Sauces:Viscosity and emulsion stability requirements complicate potassium chloride integration; hygroscopic blends demand humidity-controlled mixing environments.
- Snacks:Surface-salt dependency in extruded and fried formats drives flavor-engineering premiums that still command price separation from conventional lines.
Established volume favors Breads; emerging adoption favors Snacks.
End User:
Health risk profiles and purchasing autonomy determine price elasticity and channel preference across user clusters with divergent sodium sensitivity thresholds.
- Health-Conscious Consumers:Supermarket channel acceleration concentrates among reformulation-early categories where front-of-pack labeling schemes enable rapid quality signaling. Australia's Health Star Rating system penalizes high-sodium formulations, directing this segment toward 4.0+ rated products in Woolworths and Coles planograms.
- Seniors:Hypertension prevalence and fixed-income constraints drive subscription-based personalized nutrition platform adoption, fragmenting traditional supermarket purchasing patterns through telehealth partnerships in Germany and the Netherlands.
- Athletes:Electrolyte-balanced reduced-sodium meals for endurance applications remain underdeveloped in direct-to-consumer channels.
- Families:Multi-generational palatability requirements sustain demand for gradual sodium-reduction formats rather than zero-salt alternatives.
Volume concentration sits with Health-Conscious Consumers; steepest expansion trajectory belongs to Athletes.
Packaging Type:
Shelf stability requirements and sodium-reduction formulation chemistry dictate material barrier specifications and supply chain configuration across format categories.
- Pouches:Flexible formats enable portion-controlled sodium dosing and athlete-targeted electrolyte balancing in direct-to-consumer channels.
- Cans:Thermal processing compatibility with potassium chloride-based formulations supports institutional and emergency food applications.
- Boxes:Dry-mix architectures permit consumer-controlled sodium addition, reducing manufacturer reformulation burden.
- Bags:Snack-specific barrier properties must accommodate hygroscopic salt-replacement ingredient stability.
Institutional procurement favors Cans; premium positioning favors Pouches.
Distribution Channel:
Placement velocity control and labeling transparency requirements segment channel profitability for reformulated product lines.
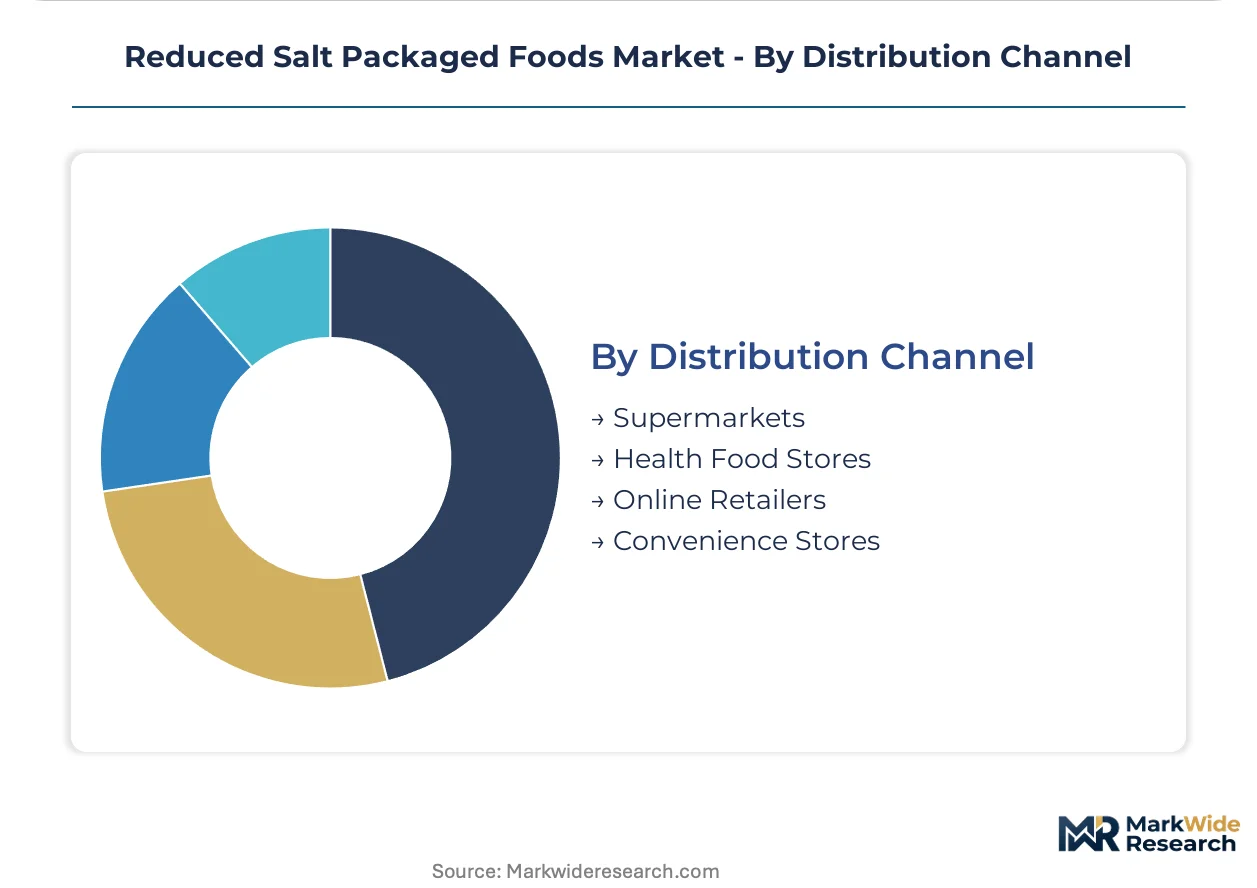
- Supermarkets:Direct-store-delivery infrastructure controls placement velocity for reduced-salt variants, with traffic-light and health-star labeling schemes driving assortment decisions.
- Health Food Stores:Clean-label substitution pressure concentrates demand in premium organic segments rejecting potassium-based ingredients.
- Online Retailers:Algorithmic personalization and subscription mechanics capture hypertensive senior volumes without retail intermediation.
- Convenience Stores:Impulse-driven purchasing patterns and limited SKU depth constrain reduced-salt penetration.
Volume scale runs through Supermarkets; margin extraction favors Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for reduced-salt formulations varies sharply by geography. German and Australian consumers accept modest premiums for reformulated staples, while price-sensitive markets in Southern Europe and emerging Asia resist sodium-reduction surcharges despite health awareness.
United States
FDA voluntary sodium targets are compressing reformulation timelines across processed food manufacturers. The agency's phased guidelines for soups, breads, and snacks are compelling recipe reinvention ahead of potential mandatory thresholds. Chicago and Minneapolis host concentrated R&D operations where Nestlé and General Mills operate captive sodium-reduction laboratories.
Germany
Private-label retailers Aldi Süd and REWE have normalized low-sodium product lines through dedicated shelf space allocation. The country's Federal Ministry of Food and Agriculture supports sodium-reduction initiatives through voluntary industry agreements. Munich and Hamburg anchor reformulation clusters where mid-tier manufacturers license flavor-modifier technologies from specialized suppliers.
United Kingdom
Mandatory front-of-pack traffic-light labeling penalizes amber-rated sodium levels in NHS England and Department for Education catering contracts. Products exceeding 400mg sodium per serving face exclusion from institutional procurement lists. London and the Midlands concentrate contract foodservice operations accelerating zero-salt-added line extensions.
Australia
Health Star Rating optimization drives reformulation toward 4.0+ ratings for preferred placement in Woolworths and Coles planograms. Food Standards Australia New Zealand mandates interpretive labeling that penalizes high-sodium formulations. Sydney and Melbourne host direct-to-consumer brands capturing hypertensive senior volumes through telehealth-integrated subscription platforms.
Japan
Aging demographics and hypertension prevalence sustain demand for reduced-sodium staples despite traditional taste preferences. The Ministry of Health, Labour and Welfare promotes sodium reduction through dietary guidelines and food-labeling standards. Tokyo and Osaka anchor fermentation technology clusters where koji-derived umami enhancers enable clean-label sodium reduction.
Reduced Salt Packaged Foods Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the reduced-salt packaged foods market. Multinational reformulators with captive sodium-reduction R&D infrastructure command premium shelf placement through direct-store-delivery networks. Regional private-label suppliers compete on price through licensed flavor-modifier technologies. Dominant competitive moves include strategic partnerships with biotechnology firms for novel umami enhancers and portfolio diversification into athlete-targeted electrolyte-balanced formats.
Within the integrated multinational tier, Nestlé S.A. and PepsiCo, Inc. exemplify divergent strategic positions. The Swiss nutrition science network sustains patent pipelines for potassium-based salt substitutes, while the North American beverage and snack giant anchors shelf space velocity through distribution infrastructure control. General Mills, Inc. occupies a position between these archetypes, representing mid-tier reformulation capabilities without captive biotechnology assets.
| Leading Market Players |
|---|
| Nestlé S.A. |
| PepsiCo, Inc. |
| General Mills, Inc. |
| The Kraft Heinz Company |
| Conagra Brands, Inc. |
| Kellogg Company |
| Unilever PLC |
| Tyson Foods, Inc. |
| Hormel Foods Corporation |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four-month EFSA novel food assessment timelines compress inventory turnover for potassium chloride-dependent reformulators, concentrating pricing power among Saskatchewan-sourced supply contract holders while forcing mid-tier manufacturers toward licensed flavor-modifier technologies.
Pricing Analysis
Reformulation service contracts and extended ingredient supply agreements drive lifetime value capture across the sodium-reduction value chain. Three-tier pricing structure across premium, standard, and economy levels separates captive-R&D multinationals from licensed-technology mid-tiers and commodity potassium-blend suppliers. Cost compression in standard-tier soups and breads intensifies because German private-label normalization erodes price premiums. Health-conscious supermarket buyers exhibit lowest price sensitivity; institutional procurement officers at NHS England and school districts face strictest budget constraints.
Supply Chain Analysis
Port congestion on Vancouver-Singapore lanes and container availability fluctuations on trans-Pacific routes inflate inbound logistics costs for Asia-Pacific umami-enhancer imports. Over sixty percent of food-grade potassium chloride originates from Saskatchewan, with secondary concentrations in Belarus and Russia. Yeast extract supply draws from fermentation facilities in Japan, Germany, and the United States. Single-source vulnerability concentrates in Saskatchewan potash rail corridors. Distribution runs through direct-store-delivery networks controlling supermarket placement velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Yeast-derived umami enhancers and AI-driven flavor mapping constitute a high-growth disruption. FDA voluntary sodium targets and front-of-pack labeling mandates in the United Kingdom and Australia accelerate reformulation demand.
For Market Incumbents: Shield patent pipelines for potassium-based salt substitutes through accelerated R&D cadence at captive sodium-reduction laboratories. Fortify direct-store-delivery infrastructure to control placement velocity against emerging direct-to-consumer brands. Vertical integration into Saskatchewan potash supply contracts mitigates geographic concentration risk. For New Entrants and Emerging Players: Anchor in athlete-targeted pouch formats for endurance applications, the most penetrable white-space segment. Target hypertensive seniors through telehealth-integrated subscription platforms in Germany and the Netherlands. Lead with clean-label koji-derived umami enhancers to bypass potassium chloride rejection in premium organic channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation-capability acquisitions as biotechnology shifts compress R&D timelines for mid-tier manufacturers. Five-to-ten-year viability favors firms with in-house sodium-reduction infrastructure over licensed-technology assemblers. Monitor EFSA classification decisions on emerging umami-enhancer technologies as inflection indicators for acceptable ingredient panel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Flavor-Modifier Technology Licensing | Mid-tier manufacturers access Nestlé-level sodium-reduction capabilities without captive R&D investment. |
| Direct-to-Consumer Subscription Launch | Telehealth partnerships in Germany capture hypertensive senior volumes without retail intermediation. |
| Potash Supply Contract Securement | Long-term Saskatchewan agreements insulate against geographic concentration and rail corridor disruptions. |
| Zero-Salt-Added Line Extension | NHS England and Department for Education catering tenders exclude products exceeding 400mg sodium per serving. |
| AI-Driven Flavor Mapping Investment | Machine learning convergence with sensory science identifies non-sodium taste pathways at accelerated timelines. |
Research Methodology
The analysis maps breads, soups, sauces, and snacks, each validated through sodium-reduction chemists, supermarket category buyers, institutional procurement officers, and flavor-modifier technology licensors. Primary interviews with reformulation specialists and retail channel managers combined with secondary validation against FDA guidance documents, EFSA novel food registers, Food Standards Australia New Zealand labeling standards, and NHS England catering procurement databases. Bottom-up volume triangulation across product categories and top-down value reconciliation against regulatory enforcement timelines anchored forecast integrity.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user risk profile, packaging format, and distribution channel control intensity. CAGRs derived from regulatory enforcement phasing, private-label expansion velocity, and biotechnology adoption curves. Forecast inputs incorporated EFSA assessment pipeline status and Health Star Rating optimization incentives.
Decision-makers should treat outputs as directional under sustained FDA voluntary guideline adherence and front-of-pack labeling scheme expansion; material deviation toward mandatory enforcement or labeling relaxation would warrant model refresh. Practitioners should keep alternative scenarios live as potassium chloride supply disruptions and novel umami-enhancer approval timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Packaged Burgers Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
Europe Free from Food Market
Packaged Foods
Food and Beverages Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Canned Goods Market
Packaged Foods
Ready Meals Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
North America Pasta Market
Packaged Foods
Japan Packaged Food Products Market