
 Production Printer Market | 2026-2036
Production Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Production Printer Market Outlook
Commercial printing houses is reorganizing procurement priorities around on-demand packaging and variable-data publishing, displacing traditional offset volume buyers from the center of vendor roadmaps. HP Inc. leverages its thermal inkjet head density advantage to dominate narrow-web label installations across North American folding-carton plants. Canon Inc. sustains margin pools in high-speed continuous-feed systems for transactional and direct-mail applications. Ricoh Company Ltd. competes through managed print services bundling that anchors fleet renewal cycles in enterprise publishing environments.
Production printers are industrial-grade digital imaging systems engineered for outputs exceeding 100 pages per minute, utilizing piezoelectric or thermal drop-on-demand mechanisms to deposit aqueous, solvent, or UV-curable inks onto paper, film, or textile substrates for commercial-scale manufacturing. Inkjet technology leads unit growth as single-pass arrays displace electrophotography in corrugated and flexible packaging workflows where substrate versatility determines contract win rates. Laser systems retain margin concentration in security printing and government document issuance where toner adhesion permanence satisfies archival standards. Hybrid configurations that marry continuous-feed speed with sheet-fed substrate flexibility represent the fastest-expanding technology category as converters seek to collapse multiple production lines into single-footprint assets.
The EPA regulates volatile organic compound emissions from offset and digital print facilities through National Emission Standards for Hazardous Air Pollutants, compelling OEMs to certify aqueous ink chemistries and solvent recovery systems. RoHS and REACH restrict heavy metal content in toner formulations and electrical components, raising compliance costs for manufacturers serving European publishers and packaging converters. Stakeholders must monitor how the EU Green Deal's packaging waste directives and emerging state-level extended producer responsibility frameworks in California and New York reshape equipment specification requirements and residual value calculations across installed bases.
Market Dynamics
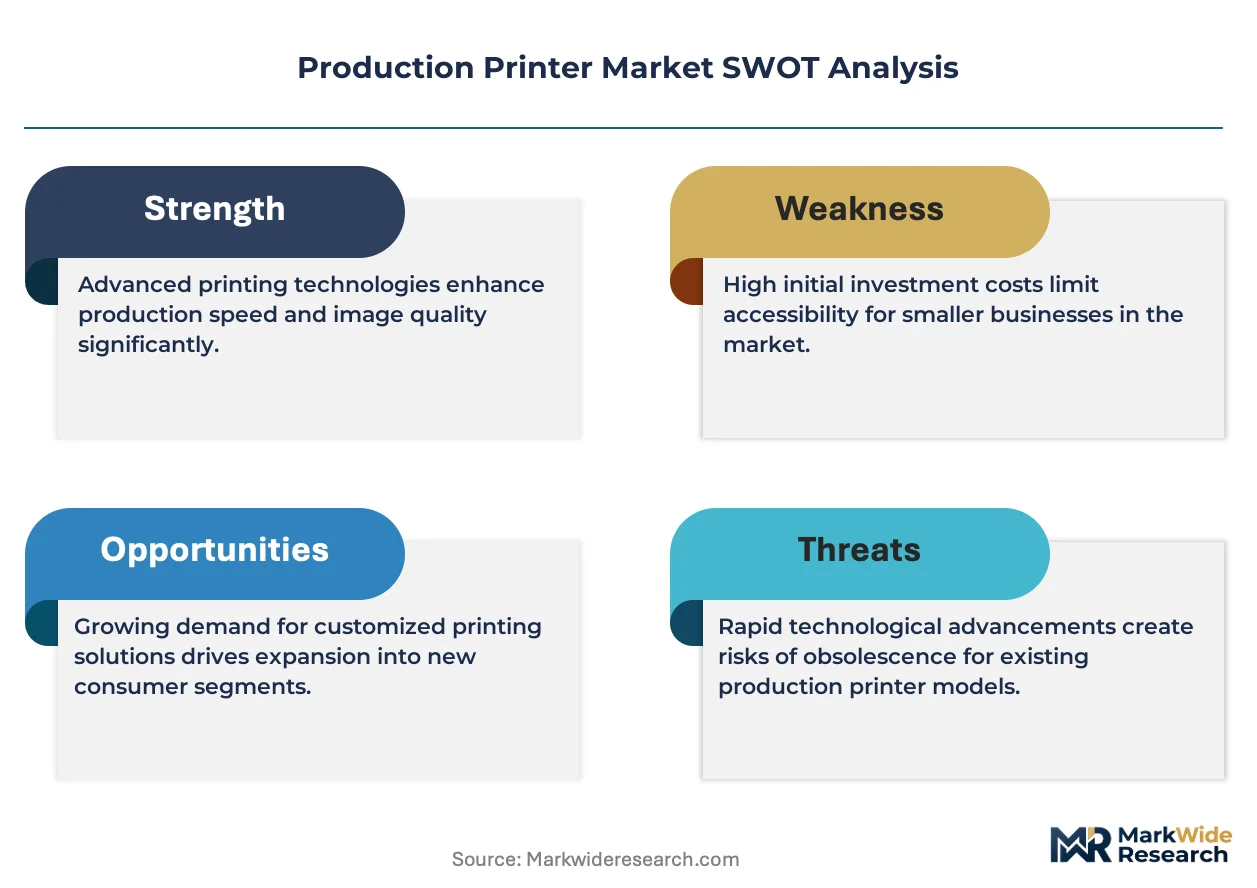
Single-pass inkjet arrays are compressing electrophotography's installed base as packaging converters consolidate multi-line workflows into unified digital assets, forcing OEMs to recalibrate R&D spend toward aqueous and UV-curable chemistries.
Growth Catalysts
- EU Green Deal packaging waste directives:Mandates for recyclable substrates accelerate OEM development of low-VOC ink systems and closed-loop toner recovery architectures across European converter networks.
- Short-run corrugated demand:E-commerce fulfillment centers in Germany and the Netherlands drive inkjet line installations for variable-data shipping boxes with lot-specific barcoding.
- Rhine-Ruhr industrial cluster concentration:Print service provider density around Düsseldorf and Cologne creates localized demand pools for high-speed continuous-feed systems serving transactional document workflows.
Market Restraints
- Piezoelectric printhead supply concentration:Japanese and German component specialists control MEMS fabrication capacity, creating bottlenecks for OEMs scaling single-pass array production.
- Silver and rare earth input volatility:Conductive inks and high-performance ceramics in thermal management subsystems expose manufacturers to commodity price swings affecting gross margins.
- REACH substance restriction timelines:ECHA's rolling candidate list updates force quarterly reformulation cycles that delay product certification and regional launch schedules.
Strategic Opportunities
- Flexible packaging white space:Thin-film substrate printing for food-grade pouches remains underpenetrated by digital systems, with converters in Italy and Spain seeking alternatives to rotogravure setup costs.
- CSRD disclosure mandates:Corporate sustainability reporting requirements create pull for equipment with embedded carbon accounting and lifecycle transparency modules.
- Hybrid workflow convergence:Sheet-fed flexibility married to continuous-feed throughput enables single-asset production of both folding cartons and direct-mail collateral.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of multi-axis substrate handling systems requires cross-trained personnel fluent in both pneumatic mechanics and firmware diagnostics, with German vocational pipelines failing to match retirement outflows.
- Legacy prepress integration friction:ERP and color management systems from prior electrophotography investments resist API-level connectivity with new inkjet controllers, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Production Printer Market |
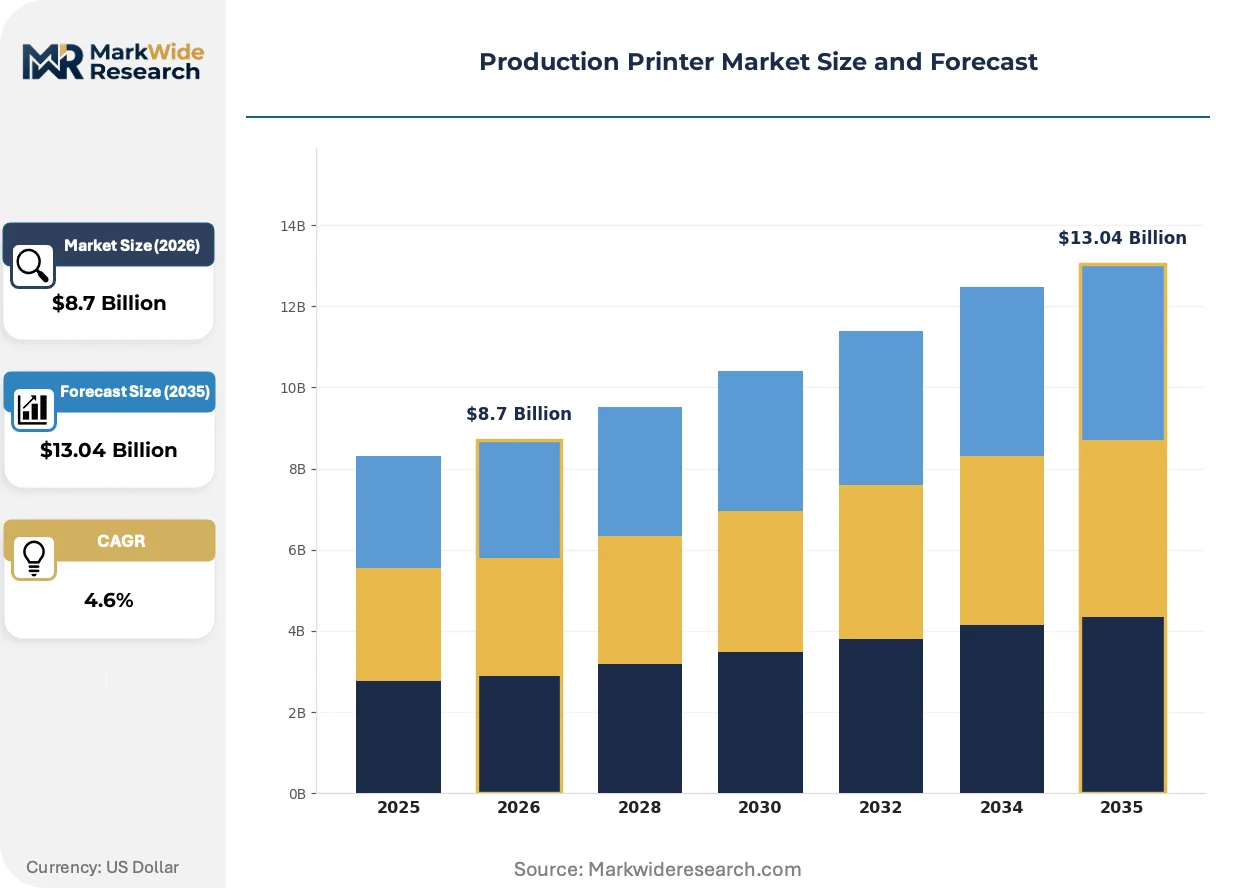
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet, Laser, Digital, Thermal Application: Commercial Printing, Packaging, Labeling, Textile Printing End User: Printers, Publishers, Retailers, Manufacturers Technology: Continuous Feed, Sheet-fed, Hybrid, UV |
| Companies Covered | Ricoh Company Ltd., Fujifilm Business Innovation Corp., Xerox Corporation, Sharp Corporation, Seiko Epson Corporation, HP Inc., Konica Minolta Inc., KYOCERA Corporation, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Production Printer Market Strategic Shifts
Digital print architectures are fragmenting into specialized substrate-optimized variants rather than converging on universal platforms, with regulatory chemistry constraints and end-use permanence requirements driving divergent development paths.
Single-pass inkjet technology is bifurcating into aqueous systems for porous paperboard and UV-curable arrays for non-absorbent films. Folding-carton plants in North America are adopting narrow-web label configurations for pharmaceutical serialization. This technological split is compressing the addressable market for hybrid electrophotographic systems that previously served both substrate categories.
REACH Annex XVII restrictions on perfluorinated compounds are forcing reformulation of water-repellent coatings used in food-contact packaging. German chemical suppliers are accelerating bio-based barrier layer development to maintain EU market access. Flexible packaging converters in Bavaria and Baden-Württemberg are piloting plasma-deposition alternatives ahead of 2025 enforcement milestones.
Print-buying departments are unbundling equipment procurement from consumables contracts and maintenance agreements. Enterprise publishers in France and the UK now tender hardware, ink, and service lines separately, compressing vendor lock-in periods from five-year cycles to eighteen-month renewals. This disaggregation is most visible in transactional print operations where fleet standardization no longer dominates vendor selection criteria.
Production Printer Market Segmentation
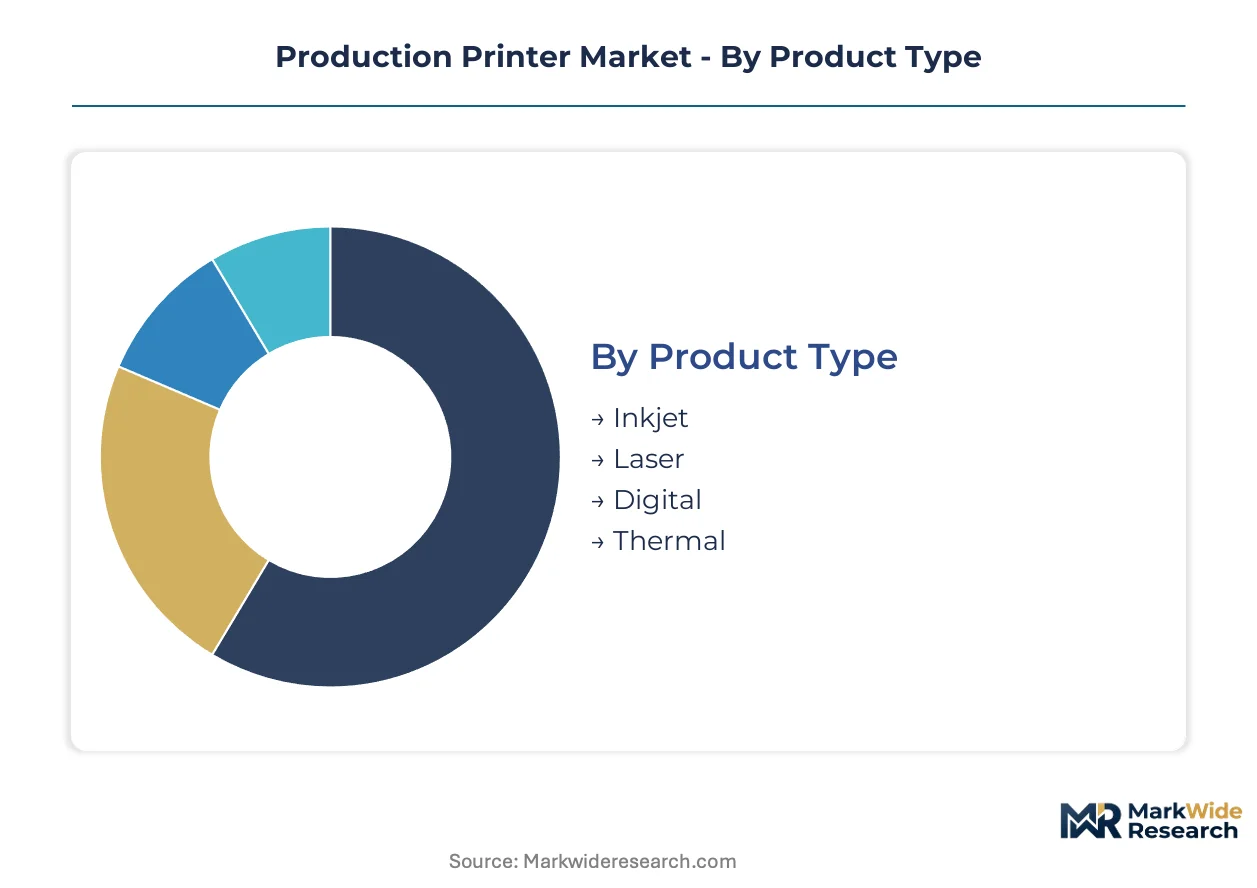
Production printer procurement patterns diverge sharply across product architectures and end-use workflows, with substrate versatility and regulatory chemistry constraints dictating specification requirements. Equipment vendors calibrate R&D roadmaps around these segment boundaries, as technology choices lock buyers into decade-long consumables commitments.
Product Type:
Domestic demand concentrates in aqueous inkjet systems for porous substrates, while export-led growth flows from UV-curable platforms serving non-absorbent film markets in Germany and the Netherlands.
- Inkjet:Piezoelectric and thermal drop-on-demand mechanisms deposit aqueous, solvent, or UV-curable inks at speeds exceeding 100 meters per minute. German packaging converters around Düsseldorf and Cologne drive installations for short-run corrugated with variable-data barcoding, though REACH-compliant ink reformulation cycles extend product launch timelines.
- Laser:Electrophotographic engines utilizing organic photoconductor drums and dry toner fusion achieve archival-grade permanence required for security documents. Demand clusters in government issuance centers and transactional print facilities where toner adhesion standards satisfy long-term retention mandates.
- Digital:Integrated workflows combining raster image processing with automated color management serve hybrid commercial environments. Publishers in France and the UK favor these systems for direct-mail and catalog production.
- Thermal:Direct thermal and thermal transfer mechanisms dominate narrow-web label applications requiring pharmaceutical serialization compliance. North American folding-carton plants specify these for drug packaging track-and-trace mandates.
Inkjet holds the largest share; momentum sits with UV-curable variants expanding into flexible food-grade films.
Application:
Cost tier stratification separates capital-intensive packaging installations from mid-market commercial print fleets, with labeling occupying a distinct premium-service niche.
- Commercial Printing:Transactional document centers and direct-mail operations utilize continuous-feed inkjet for variable-data publishing. Rhine-Ruhr industrial clusters sustain demand pools for high-speed systems serving banking and insurance correspondence workflows.
- Packaging:Single-pass arrays displace rotogravure for corrugated shipping boxes and folding cartons. E-commerce fulfillment centers in the Netherlands specify these for lot-specific barcoding on variable-run boxes.
- Labeling:Narrow-web configurations with pharmaceutical serialization modules command premium pricing. FDA track-and-trace mandates and EU Falsified Medicines Directive compliance drive specification requirements.
- Textile Printing:Reactive dye and pigment ink systems deposit patterns onto cotton and polyester substrates. Italian and Spanish converters pilot these for short-run fashion and home décor applications.
Packaging commands the dominant revenue pool; commercial printing exhibits the steepest margin compression from disaggregated procurement tenders.
End User:
Customer type determines fleet standardization intensity, with enterprise publishers unbundling hardware from consumables contracts while manufacturers seek single-source integration.
- Printers:Commercial print service providers operate mixed-vendor environments with managed print services anchoring renewal cycles. German vocational pipeline shortages for mechatronics technicians constrain maintenance capacity expansion.
- Publishers:Magazine and catalog producers prioritize color consistency across distributed print locations. French and UK enterprises now tender hardware, ink, and service lines separately, compressing vendor lock-in periods.
- Retailers:In-store signage and promotional material production favors sheet-fed flexibility for campaign-responsive turnaround. Private-label packaging specifications increasingly require digital proofing capabilities.
- Manufacturers:Industrial converters integrate production printers directly into packaging lines for just-in-time fulfillment. Bavarian and Baden-Württemberg flexible packaging specialists pilot plasma-deposition barrier layers ahead of perfluorinated compound restrictions.
Printers represent the largest installed base; manufacturers are gaining share fastest through vertical integration of packaging workflows.
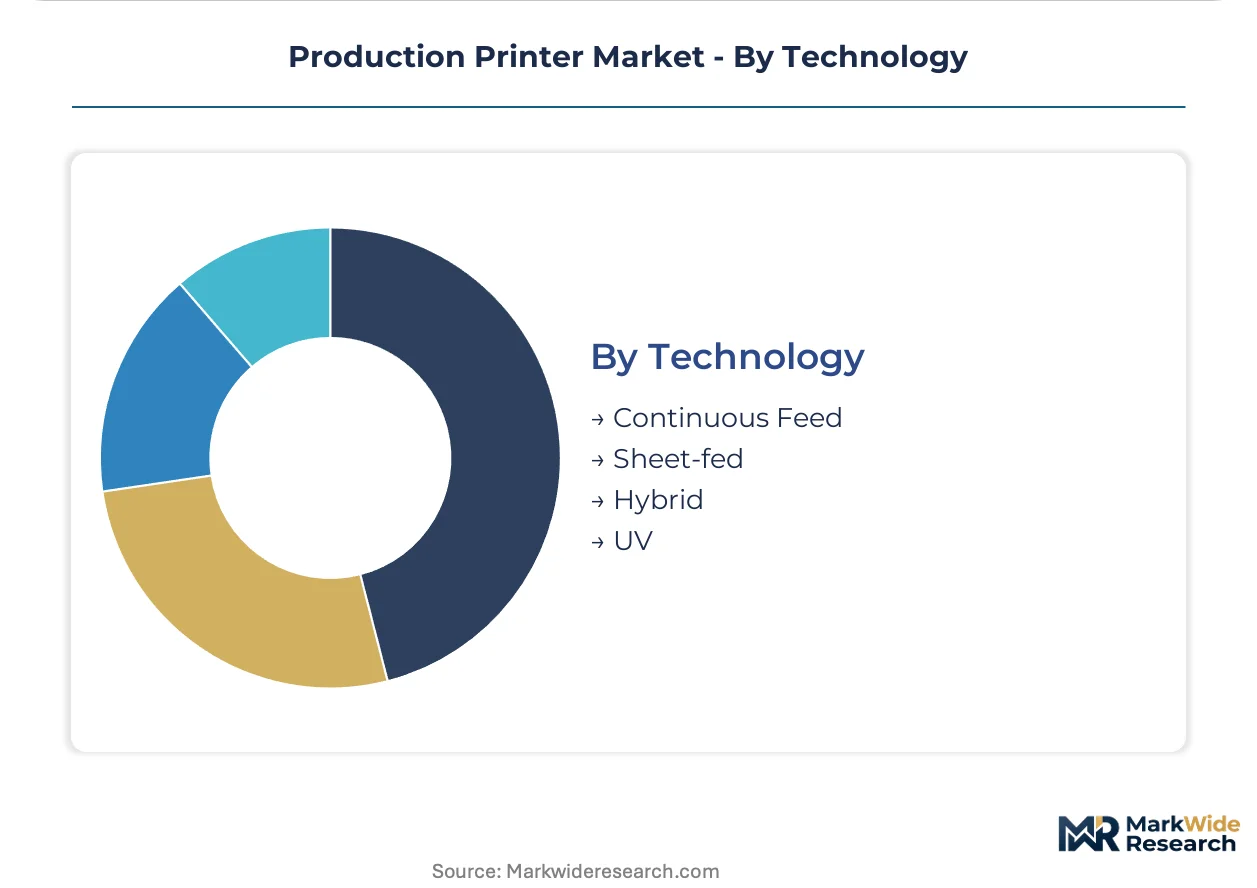
Technology:
Maturity gradients separate established continuous-feed architectures from emerging hybrid configurations that collapse multiple production lines into unified assets.
- Continuous Feed:Roll-fed systems achieve maximum throughput for transactional and direct-mail applications. Rhine-Ruhr density of print service providers sustains localized demand for these high-speed engines.
- Sheet-fed:Cut-sheet flexibility enables substrate switching without web splicing downtime. Commercial printers favor these for campaign-responsive job scheduling.
- Hybrid:Configurations marrying continuous-feed speed with sheet-fed substrate versatility represent the most rapidly expanding category. Converters seek single-footprint assets producing both folding cartons and direct-mail collateral.
- UV:Curable ink systems with instant polymerization enable printing on non-absorbent films and metallic substrates. Food-contact packaging applications face EFSA migration testing requirements for unreacted photoinitiator residues.
Continuous Feed retains the largest installed base; Hybrid configurations are climbing the fastest as converters consolidate multi-line workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial print service providers and packaging converters concentrate procurement authority in Germany, the United States, Japan, and the Netherlands, with regulatory chemistry mandates and e-commerce fulfillment infrastructure dictating specification priorities across each market.
United States
Pharmaceutical serialization mandates from the FDA drive narrow-web thermal installations for drug packaging track-and-trace compliance. EPA National Emission Standards for Hazardous Air Pollutants compel aqueous ink certification and solvent recovery system deployment. Folding-carton plants across the Midwest and Southeast specify HP thermal inkjet configurations for variable-data label production.
Germany
Industrial print service providers cluster around Düsseldorf and Cologne within the Rhine-Ruhr corridor, sustaining demand pools for high-speed continuous-feed transactional systems. REACH Annex XVII restrictions on perfluorinated compounds force quarterly reformulation cycles for water-repellent food-contact coatings. Bavarian flexible packaging converters pilot plasma-deposition barrier layers ahead of enforcement milestones.
Japan
Piezoelectric MEMS fabrication specialists concentrate printhead supply capacity, creating component bottlenecks for OEMs scaling single-pass array production. METI industrial standards govern equipment energy efficiency and chemical handling protocols. Tokyo-Osaka manufacturing belts host precision mechatronics suppliers serving regional OEM assembly networks.
Netherlands
E-commerce fulfillment centers in Rotterdam and Eindhoven drive inkjet line installations for variable-data shipping boxes with lot-specific barcoding. EU Green Deal packaging waste directives mandate recyclable substrate compatibility, accelerating low-VOC system specifications. Dutch converters lead pilot deployments of UV-curable arrays for thin-film food-grade pouch applications.
United Kingdom
Enterprise publishers in London and Manchester unbundle hardware procurement from consumables contracts, compressing vendor lock-in periods to eighteen-month renewal cycles. CSRD disclosure requirements create pull for equipment with embedded carbon accounting modules. Commercial print fleets across the Midlands favor hybrid configurations merging continuous-feed throughput with sheet-fed flexibility.
Production Printer Market Competitive Environment
Player mix skews toward diversified imaging conglomerates with captive consumables supply chains, creating tiered competition between full-stack platform vendors and component-specialist licensors. Strategic archetypes span thermal inkjet head density leaders, electrophotographic permanence specialists, and managed print services bundlers. Dominant competitive moves include strategic partnerships for substrate-optimized ink chemistries and geographic expansion through distributor network consolidation.
Within the diversified conglomerate tier, HP Inc., Canon Inc., and Ricoh Company Ltd. anchor distinct positioning vectors. HP Inc. exemplifies thermal inkjet head density specialization through narrow-web label dominance. Canon Inc. occupies the electrophotographic permanence position for security and archival document applications. Ricoh Company Ltd. represents managed print services bundling that anchors enterprise fleet renewal cycles.
| Leading Market Players |
|---|
| Ricoh Company Ltd. |
| Fujifilm Business Innovation Corp. |
| Xerox Corporation |
| Sharp Corporation |
| Seiko Epson Corporation |
| HP Inc. |
| Konica Minolta Inc. |
| KYOCERA Corporation |
| Canon Inc. |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII substance restrictions gate both European market entry and premium-tier pricing qualification, forcing OEMs to absorb reformulation costs while passing compliance premiums to packaging converters seeking food-contact certification. Buyers in Germany and the Netherlands now treat REACH-compliant ink systems as table stakes, collapsing price differentiation between certified and non-certified suppliers.
Pricing Analysis
Cost-plus contracts with silver and rare earth indexation dominate thermal management subsystem procurement, exposing manufacturers to commodity volatility that compresses gross margins when palladium prices spike. Three-tier pricing structure across premium certified, standard industrial, and economy commercial levels separates archival-grade laser systems from aqueous inkjet workhorses. Pricing pressure stems from disaggregated procurement tenders in France and the UK that compress vendor lock-in periods to eighteen-month cycles. Commercial print service providers exhibit highest price sensitivity due to managed print services margin compression, while pharmaceutical serialization mandates make labeling buyers least sensitive.
Supply Chain Analysis
Japan and Germany anchor piezoelectric MEMS printhead fabrication, with Japanese specialists controlling thermal inkjet head density architectures and German suppliers dominating precision mechatronics for substrate handling systems. Conductive inks draw from silver paste specialists in South Korea, while high-performance ceramics for thermal management rest on rare earth processors in China. Single-source vulnerability concentrates in MEMS foundry capacity, where two Japanese component specialists control single-pass array production scaling. Distribution runs through OEM-direct channels for enterprise publishers and specialized dealer networks serving packaging converters in the Rhine-Ruhr corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward enterprise publishers and packaging converters as procurement unbundling fragments vendor lock-in, with French and UK tender patterns compressing renewal cycles and forcing OEMs to compete on eighteen-month hardware replacement rather than decade-long consumables capture.
For Market Incumbents: Consolidate captive ink formulation capabilities to defend margin pools against independent chemical suppliers entering the REACH-compliant aqueous segment. Deepen backward integration into piezoelectric printhead MEMS fabrication through exclusive offtake agreements with Japanese foundries, countering supply concentration risk that threatens single-pass array scaling timelines. For New Entrants and Emerging Players: Differentiate on flexible packaging substrate versatility, targeting Italian and Spanish converters seeking alternatives to rotogravure setup costs for thin-film food-grade pouches. Penetrate the hybrid workflow convergence segment where sheet-fed flexibility married to continuous-feed throughput commands premium positioning against electrophotographic legacy systems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across UV-curable inkjet array manufacturing as single-pass architecture R&D demands accelerate ahead of flexible packaging commercialization. Target acquisition candidates with embedded carbon accounting modules serving CSRD disclosure mandates, monitoring EU Green Deal packaging waste directive enforcement as the inflection signal for low-VOC system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Ink Formulation Partnership | Locks in European packaging converter access ahead of perfluorinated compound enforcement milestones. |
| Hybrid Configuration Platform Launch | Captures converter demand for single-footprint assets producing folding cartons and direct-mail collateral. |
| MEMS Printhead Capacity Reservation | Secures piezoelectric fabrication slots against Japanese foundry bottlenecks constraining OEM scaling. |
| Managed Print Services Rebundling | Re-anchors enterprise fleet renewal cycles threatened by eighteen-month hardware tender fragmentation. |
| Plasma-Deposition Barrier Layer Pilot | Positions Bavarian flexible packaging specialists ahead of bio-based coating substitution requirements. |
Study Parameters
A standing panel of OEM product strategy directors, packaging converter procurement leads, commercial print service operations managers, and mechatronics maintenance technicians provided ongoing calibration across primary fieldwork phases. Secondary validation drew from EPA National Emission Standards filings, ECHA REACH candidate list updates, EU Green Deal packaging waste directive texts, and SEC 10-K equipment revenue disclosures. Bottom-up installation data triangulated against top-down consumables flow estimates to anchor market sizing.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product architecture, substrate chemistry compatibility, end-use workflow intensity, and regional regulatory cluster stringency. CAGRs were derived from installed base evolution and replacement cycle compression patterns, with forecast inputs incorporating REACH substance restriction timelines and e-commerce fulfillment center expansion trajectories in Germany and the Netherlands.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated single-pass inkjet reliability maturation would require recalibration. Forecasts reflect documented assumptions regarding piezoelectric printhead supply expansion and vocational pipeline replenishment for mechatronics technicians. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Copier, MFP and Printer Market
Printers
Single Function Printer Market
Printers
Global Inkjet Coders Market
Printers
Nanographic Printing Market
Printers
Global Ticket Printers Production Market
Printers
Indonesia Thermal Printer Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Mobile Photo Printer Market
Printers
Electrophotographic Printing Market
Printers
Retail Printers and Consumables Market
Printers
India Inkjet Printer Market
Printers
Dot Matrix Printer Market
Printers
Global Thermal Printing Market
Printers
Inkjet Printing Market
Printers
Printer Ribbons Market
Printers
Aerosol Printing and Graphics Market