
 Global Customer Experience Analytics Market | 2026-2036
Global Customer Experience Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Customer Experience Analytics Market Foresight
Subscription-based SaaS financing is reshaping competitive entry in customer experience analytics by lowering upfront capital barriers for mid-market buyers. Microsoft leverages its Azure cloud infrastructure to bundle analytics with enterprise productivity suites. Qualtrics sustains differentiation through specialized journey analytics modules for hospitality operators. Clootrack anchors its position with AI-native text analytics built for emerging-market retail chains.
Customer experience analytics encompasses the systematic collection, processing, and interpretation of behavioral, transactional, and sentiment data across touchpoints to optimize engagement outcomes. The discipline relies on natural language processing pipelines, real-time event streaming architectures, and probabilistic scoring models to convert unstructured feedback into actionable service interventions. Cloud-based deployment leads solution delivery by enabling elastic compute for seasonal contact center volumes. Journey analytics represents the fastest-expanding solution category as enterprises map cross-channel friction points. Voice analytics retains mature margin pools in regulated sectors requiring call recording compliance.
The EU AI Act, GDPR, and the US FTC's algorithmic fairness guidance collectively tighten consent and explainability standards for automated customer scoring. India's Digital Personal Data Protection Act imposes localization requirements on cross-border feedback processing. Stakeholders must monitor emerging interoperability mandates between CRM platforms and standalone analytics tools.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are forcing enterprises to rebuild automated customer scoring pipelines around explainable AI frameworks, compressing deployment timelines for legacy sentiment models.
Growth Catalysts
- Cloud-native NLP pipelines:Elastic compute architectures enable mid-market retailers to process seasonal contact center surges without capital-heavy infrastructure commitments.
- GDPR consent frameworks:European enterprises are investing in first-party data collection tools to maintain personalization capabilities while satisfying cross-border data governance requirements.
- India's Digital Personal Data Protection Act:Localization mandates are stimulating domestic analytics infrastructure development for multinational brands operating in South Asian markets.
Market Restraints
- GPU compute cost volatility:Real-time voice transcription and large-language model inference require specialized silicon subject to supply chain bottlenecks from Taiwan-based foundries.
- EU AI Act compliance friction:High-risk system classification for automated credit and insurance scoring creates documentation burdens that extend procurement cycles.
- Legacy CRM integration complexity:Proprietary data schemas in installed-base Salesforce and Microsoft Dynamics instances resist standardized API connectivity.
Strategic Opportunities
- Underpenetrated German Mittelstand:Mid-sized industrial manufacturers lack dedicated customer intelligence functions, creating whitespace for managed analytics services.
- Convergence of voice biometrics and sentiment analysis:Unified authentication-emotion detection stacks reduce agent handle times in fraud-sensitive banking workflows.
- US FTC algorithmic fairness guidance:Proactive bias auditing services represent a compliance-adjacent revenue stream for specialized consultancies.
Industry Challenges
- Multilingual NLP talent scarcity:Fluent data scientists capable of tuning Indic-language sentiment models command premium compensation in competitive labor markets.
- ISO 27001 certification timelines:Enterprise buyers require completed information security audits that delay vendor onboarding by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Customer Experience Analytics Market |
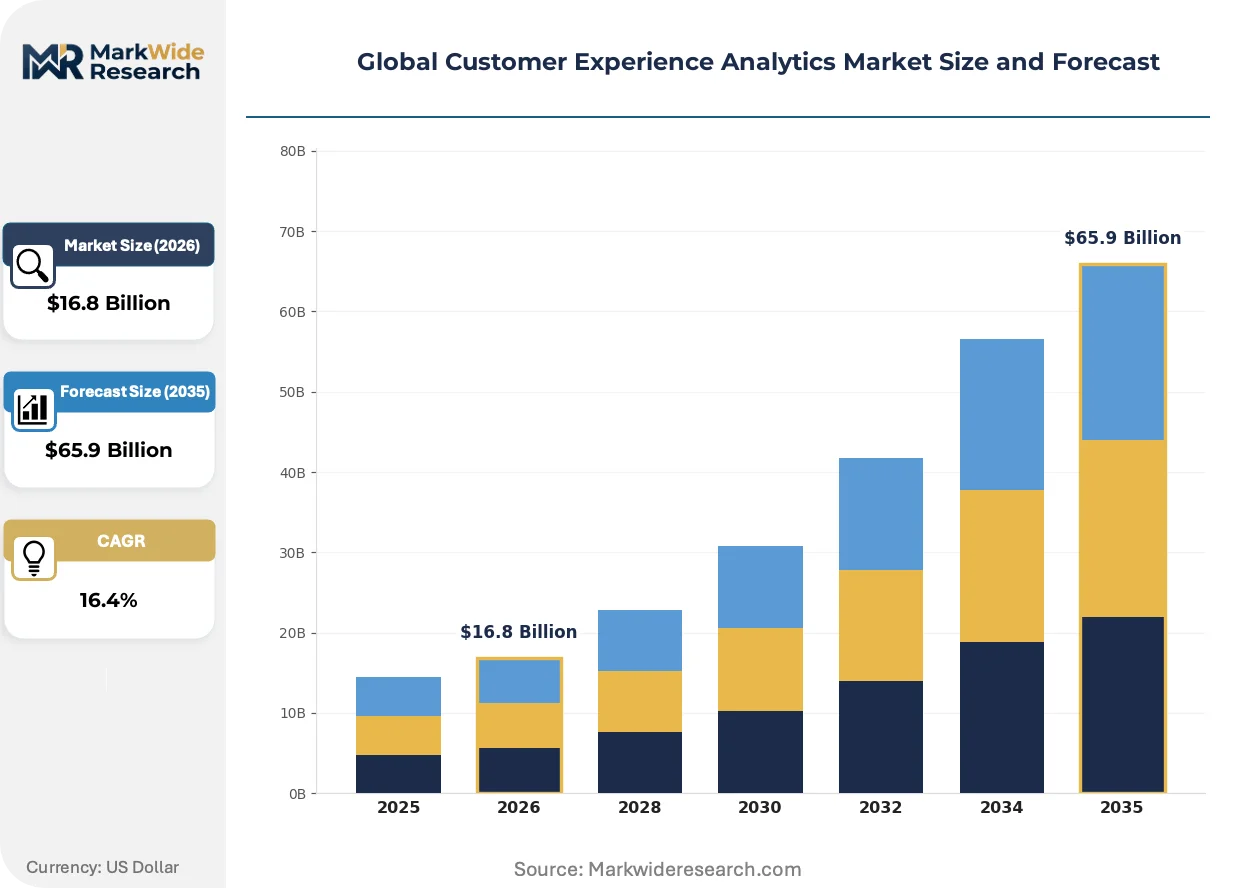
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $65.9 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Offering: Voice Analytics, Text Analytics, Predictive Analytics, Sentiment Analysis, Journey Analytics Application: Customer Retention, Personalization, Marketing Optimization, Product Feedback, Service Improvement End User: Telecommunications Providers, Retail Chains, Financial Institutions, Hospitality Operators, E-Commerce Platforms |
| Companies Covered | Zoom, Microsoft, Medallia, Apple, Google, Qualtrics, Accenture, Clootrack, Zendesk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Customer Experience Analytics Market Shifts & Advancements
Real-time event streaming architectures are compressing the gap between customer action and service response, eliminating batch-processing latency that previously obscured journey friction points.
Edge-deployed speech analytics is collapsing the cost structure of call-center quality assurance. On-device transcription eliminates round-trip latency to cloud inference endpoints. Retail banks in India and telecommunications operators in Germany are piloting these architectures for branch and field service environments. The shift enables continuous monitoring without the bandwidth costs and data residency risks of centralized processing.
CSRD sustainability reporting mandates in Europe are extending disclosure requirements to customer data governance practices. Companies must document how feedback collection aligns with stakeholder materiality assessments. Hospitality chains and luxury goods retailers with significant EU revenue exposure are restructuring consent flows and retention policies ahead of enforcement deadlines.
Subscription-based consumption models are displacing perpetual license arrangements in mid-market procurement. Buyers prefer operational expenditure treatment for analytics capabilities with uncertain utilization patterns. This preference is most pronounced among United States-based healthcare providers and German automotive suppliers modernizing fragmented contact center estates.
Global Customer Experience Analytics Market Segmentation
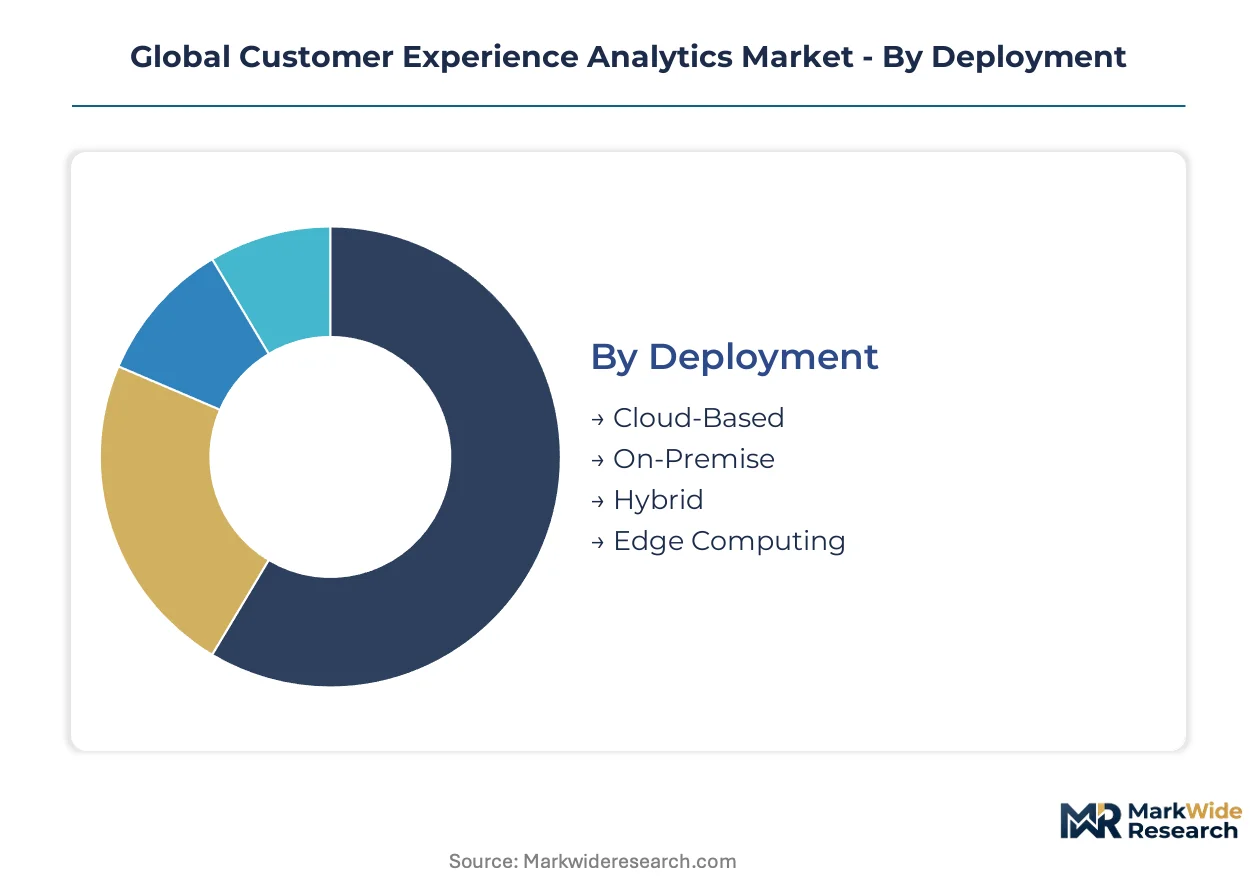
Customer experience analytics segments reflect divergent infrastructure maturity, regulatory exposure, and data gravity requirements. Deployment models determine capital intensity and compliance architecture. Solution offerings map to specific touchpoint instrumentation needs across voice, text, and behavioral channels.
Deployment:
Use-case spectrum spans from elastic seasonal scaling to air-gapped compliance environments.
- Cloud-Based:Elastic compute architectures enable mid-market retailers to absorb Black Friday contact center surges without infrastructure overprovisioning. Demand concentrates in United States healthcare providers modernizing fragmented patient engagement stacks under HIPAA business associate agreements.
- On-Premise:Dedicated hardware deployments satisfy data residency mandates in German automotive suppliers and Indian public sector banks subject to localization requirements. Procurement cycles extend six to nine months due to ISO 27001 certification requirements.
- Hybrid:Split architectures process sensitive authentication data on-site while routing anonymized sentiment signals to cloud NLP endpoints. German Mittelstand manufacturers favor this model for customer intelligence without full cloud migration.
- Edge Computing:On-device transcription eliminates round-trip latency for branch banking quality assurance in India and field service monitoring in Germany. Bandwidth cost reduction drives adoption in connectivity-constrained environments.
Established volume favors Cloud-Based; emerging adoption favors Edge Computing.
Solution Offering:
Cost tier stratification separates enterprise-grade journey orchestration from point solutions.
- Voice Analytics:Real-time call transcription and emotion detection pipelines require GPU-accelerated inference. Mature margin pools persist in United States financial services where call recording compliance is mandatory.
- Text Analytics:AI-native NLP engines process unstructured feedback from chat transcripts, email threads, and social mentions. Retail chains in India deploy these tools for Indic-language sentiment classification at scale.
- Predictive Analytics:Probabilistic scoring models forecast churn propensity and lifetime value trajectories. EU AI Act explainability mandates are forcing architecture rebuilds around interpretable machine learning frameworks.
- Sentiment Analysis:Polarity and emotion classification convert qualitative feedback into structured metrics. Hospitality operators use these signals for real-time service recovery interventions.
- Journey Analytics:Cross-channel friction mapping identifies drop-off points between mobile, web, and physical touchpoints. This category is expanding most quickly as enterprises prioritize end-to-end experience orchestration.
Revenue concentration sits with Voice Analytics; steepest expansion trajectory belongs to Journey Analytics.
Application:
Customer type determines whether analytics investments target acquisition efficiency or retention economics.
- Customer Retention:Churn prediction models integrate transactional, behavioral, and sentiment signals to trigger proactive interventions. Telecommunications providers in Germany deploy these systems against aggressive competitor switching campaigns.
- Personalization:Real-time recommendation engines adapt content and offers based on journey context. E-commerce platforms in the United States invest here to recover margin pressure from customer acquisition cost inflation.
- Marketing Optimization:Attribution modeling and audience segmentation improve campaign return on ad spend. First-party data collection investments are accelerating under GDPR and Digital Personal Data Protection Act consent frameworks.
- Product Feedback:Structured analysis of feature requests and defect reports informs roadmap prioritization. Industrial manufacturers in Germany use these signals for aftermarket service design.
- Service Improvement:Agent performance analytics and quality assurance automation reduce handle times. Banking workflows in India combine voice biometrics with sentiment detection for fraud-sensitive authentication.
Defensive spend dominates Customer Retention; offensive investment favors Personalization.
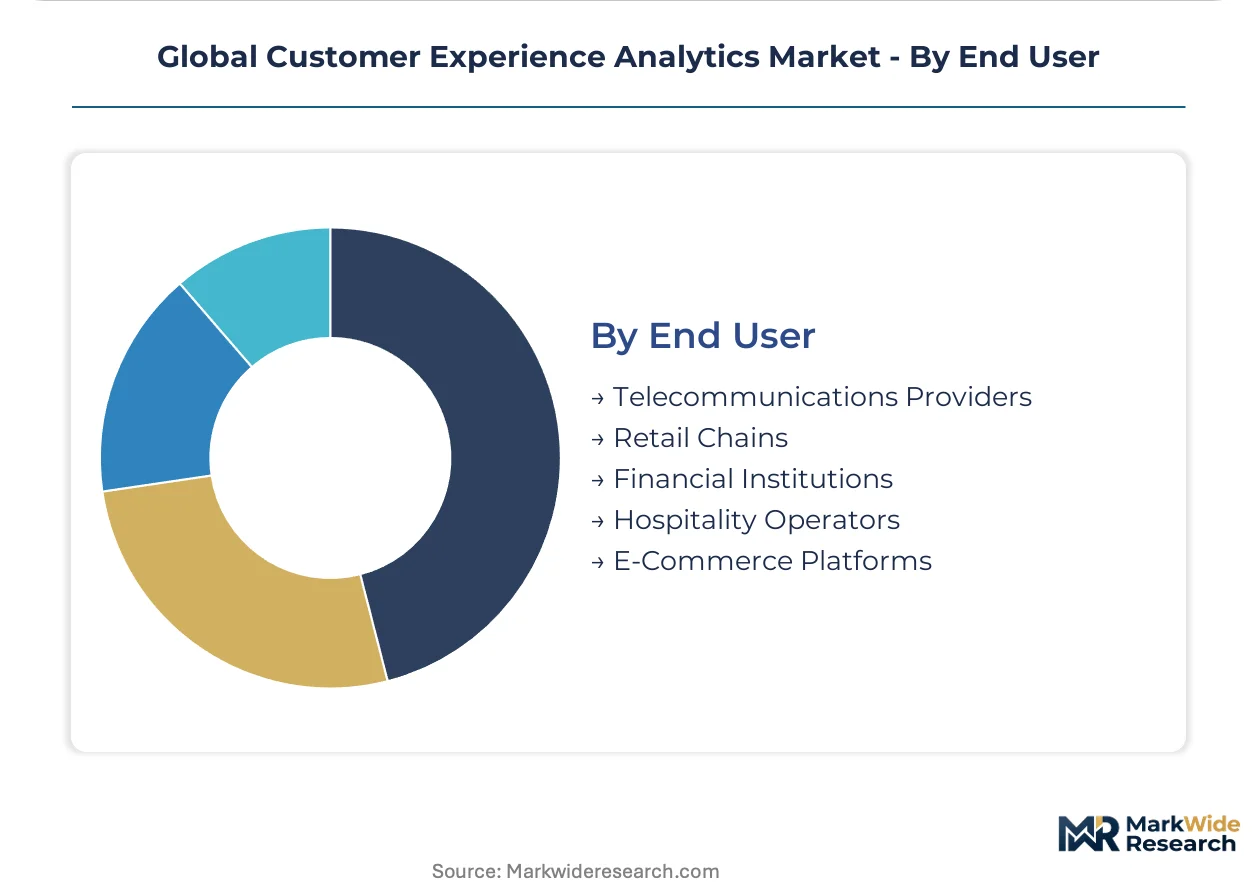
End User:
Geography and regulatory exposure shape procurement priorities across verticals.
- Telecommunications Providers:High churn environments drive investment in real-time intervention systems. Indian operators face TRAI-mandated quality of service reporting requirements.
- Retail Chains:Omnichannel journey analytics unify online and in-store experience measurement. Voice analytics pilots are expanding for real-time service improvement at scale.
- Financial Institutions:Call recording compliance and algorithmic fairness auditing dominate procurement criteria. United States banks navigate FTC guidance on automated credit scoring transparency.
- Hospitality Operators:Specialized journey analytics modules track guest experience across booking, stay, and post-departure touchpoints. CSRD sustainability reporting mandates are restructuring consent flows.
- E-Commerce Platforms:Seasonal volume volatility demands elastic infrastructure for peak transaction periods. Subscription-based SaaS financing lowers entry barriers for mid-market marketplace operators.
Procurement maturity concentrates in Financial Institutions; whitespace opportunity sits with Hospitality Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers concentrate in three distinct archetypes: United States healthcare providers seeking HIPAA-compliant patient engagement stacks, German automotive suppliers modernizing fragmented contact centers, and Indian retail chains deploying Indic-language sentiment classification at scale.
United States
Healthcare providers drive cloud-based procurement under HIPAA business associate agreements, while financial institutions navigate FTC algorithmic fairness guidance for automated credit scoring. The FTC mandates transparency documentation for high-risk automated decision systems. Boston-area health systems and New York Metro financial services clusters anchor demand for real-time journey orchestration.
Germany
Mid-sized industrial manufacturers in the Mittelstand lack dedicated customer intelligence functions, creating whitespace for managed analytics services. The EU AI Act forces architecture rebuilds around explainable AI frameworks for automated scoring pipelines. Bavarian automotive suppliers and North Rhine-Westphalia industrial clusters favor hybrid deployments that process sensitive data on-site while routing anonymized signals to cloud endpoints.
India
Telecommunications providers face TRAI-mandated quality of service reporting requirements, stimulating investment in real-time intervention systems. The Digital Personal Data Protection Act imposes localization mandates on cross-border feedback processing. Mumbai-based retail chains and Bangalore-headquartered e-commerce platforms deploy AI-native text analytics for Indic-language sentiment classification at scale.
United Kingdom
GDPR consent frameworks drive first-party data collection tool investments to maintain personalization capabilities. The Information Commissioner's Office enforces cross-border data governance standards for sentiment processing. London-based hospitality operators and Edinburgh financial services clusters restructure consent flows ahead of CSRD sustainability reporting enforcement deadlines.
Japan
Enterprise productivity suite bundling accelerates as organizations modernize contact center infrastructure under METI digital transformation guidelines. The Personal Information Protection Commission mandates explicit consent for automated customer profiling. Tokyo-headquartered telecommunications operators and Osaka-based retail chains pilot edge-deployed speech analytics for branch quality assurance.
Global Customer Experience Analytics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment models and solution categories. The vendor base organizes around three strategic archetypes: cloud infrastructure bundlers leveraging existing enterprise relationships, vertical specialists delivering industry-specific journey modules, and AI-native challengers built for emerging-market scale. Dominant competitive moves include strategic partnerships for CRM interoperability and portfolio diversification into edge computing architectures.
Within the infrastructure-bundler tier, Microsoft and Google occupy positions that exemplify platform-level control over enterprise analytics procurement. Among specialized journey analytics providers, Qualtrics represents the vertical-specialist archetype with modular offerings for hospitality operators. Clootrack anchors the AI-native challenger segment with text analytics built for emerging-market retail chains.
| Leading Market Players |
|---|
| Zoom |
| Microsoft |
| Medallia |
| Apple |
| Qualtrics |
| Accenture |
| Clootrack |
| Zendesk |
| Others |
Supply & Pricing Matrix
GPU compute cost volatility from Taiwan-based foundry concentration determines both SaaS subscription tier spreads and the geographic distribution of inference infrastructure. Buyers face widening price differentials between cloud-native and edge-deployed architectures as silicon supply constraints persist.
Pricing Analysis
Cost-plus contracts with GPU spot-price indexation dominate enterprise voice analytics procurement. Three-tier pricing structure across premium, standard, and economy levels separates real-time journey orchestration from batch-processed sentiment tools. Price differentiation hinges on ISO 27001 certification status and dedicated tenant isolation. Cost compression in mid-market SaaS tiers is intensifying because hyperscaler bundling subsidizes entry-level analytics seats. Healthcare providers under HIPAA business associate agreements exhibit lowest price sensitivity; Indian retail chains face acute budget constraints.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan Semiconductor Manufacturing Company and Samsung Foundry for AI accelerator silicon. Geographic supply concentration centers on Taiwan, South Korea, and the United States for GPU and NPU fabrication. Raw material dependencies draw from neon gas purification, high-bandwidth memory stacks, and advanced packaging substrates. Single-source vulnerability around CoWoS advanced packaging creates procurement chokepoints for real-time inference hardware. Distribution runs through hyperscaler marketplaces, direct enterprise sales, and regional systems integrators serving German Mittelstand manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Customer experience analytics represents an early-cycle expansion story as EU AI Act explainability mandates force architecture rebuilds across automated scoring pipelines. Cloud-native deployment penetration in mid-market healthcare and retail remains below saturation thresholds.
For Market Incumbents: Entrench platform control through backward integration into proprietary NLP model training infrastructure. Deepen ISO 27001 certification moats to extend procurement cycle advantages against challenger vendors. Defend against AI-native text analytics specialists by embedding journey analytics modules directly into CRM workflows.
For New Entrants and Emerging Players: German Mittelstand manufacturers lacking dedicated customer intelligence functions represent the most penetrable entry point for managed analytics services. Edge-deployed speech analytics for Indian branch banking quality assurance offers second white-space avenue. Pursue channel partnerships with regional systems integrators over direct enterprise sales to bypass incumbent relationship barriers.
For Investors and Strategic Acquirers: EU AI Act high-risk system classification deadlines reshape the acquisition landscape toward explainable AI framework capabilities. Long-term viability favors vertical specialists with hospitality or financial services domain depth over horizontal platform plays. Monitor TRAI quality of service mandate enforcement intensity as inflection indicator for Indian telecommunications analytics demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure bundling captures enterprise productivity suite relationships for analytics cross-sell. |
| Acquisition of Specialist Firm | Journey analytics module purchases address hospitality operator vertical requirements. |
| Strategic Partnership | CRM interoperability agreements with Salesforce reduce legacy integration friction. |
| Geographic Expansion | Indian domestic infrastructure development satisfies Digital Personal Data Protection Act localization. |
| Product Launch | Edge-deployed speech analytics pilots reduce bandwidth costs for German field service monitoring. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and EU regulatory databases. Conversations with contact center operations directors, CRM procurement officers, NLP engineering leads, and hospitality technology executives informed demand-side validation. Bottom-up deployment model sizing triangulates against top-down enterprise software spending analysis.
Forecast inputs encompass deployment elasticity coefficients, regulatory compliance cost pass-through rates, and vertical adoption curves. Segmentation dimensions modeled include deployment architecture, solution category, end-user vertical, and regional regulatory cluster. CAGRs derive from installed base expansion rates and average revenue per account trajectory across the analysis window. GPU supply constraint scenarios and EU AI Act implementation timelines feed sensitivity analysis.
Practitioners should monitor Taiwan foundry capacity allocation, EU AI Act enforcement precedent, and TRAI quality mandate implementation for early signals. Forecasts reflect assumptions around cloud migration velocity and mid-market SaaS financing availability. Quarterly review of hyperscaler infrastructure capex and enterprise CRM renewal rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Event Stream Processing Market
Analytics
Germany Geospatial Analytics Market
Analytics
Global Data Visualization Tools Market
Analytics
HR Analytics Market
Analytics
Product Analytics Market
Analytics
United Kingdom Geospatial Imagery Analytics Market
Analytics
Human Resource Analytics Market
Analytics
Location Analytics Market
Analytics
Europe Edge Analytics Market
Analytics
Drone Analytics Software Market
Analytics
Customer Analytics in E-Commerce Market
Analytics
Pandemic Analytics Market
Analytics
Contact Center Intelligence Market
Analytics
IoT Analytics Market
Analytics
Big Data Analytics in Manufacturing Market
Analytics
Retail Analytics Market