
 Japan Feed Additives Market | 2026-2036
Japan Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Feed Additives Market Foresight
JIS Q 17065 certification for organic feed additives is redrawing competitive boundaries in Japan. Cargill leverages its global procurement network to secure lysine and methionine supply chains into Osaka and Nagoya feed mills. Ajinomoto Co., Inc. anchors domestic production of fermented amino acids through proprietary biotechnology platforms in the Kanto region. BASF SE competes on vitamin stability technology, extending shelf-life advantages for premix formulations distributed through Japan's cooperative feed channels.
Feed additives comprise biologically active substances incorporated into animal diets at inclusion rates typically below one percent to enhance nutrient utilization, growth performance, or health outcomes. Enzyme additives break down non-starch polysaccharides in barley and wheat-based rations common to Japanese swine operations, while amino acid premixes correct lysine and threonine deficits in corn-soy formulations. The aquaculture application segment shows structural momentum as yellowtail and seabass producers in Ehime and Kagoshima prefectures adopt specialized probiotic and nucleotide additives to replace antibiotic growth promoters. Powder and granular forms dominate volume, though liquid enzyme formulations gain share in automated feed manufacturing systems.
PMDA oversight of veterinary feed directives and METI enforcement of feed manufacturing standards constrain antibiotic usage timelines and elevate documentation burdens for feed manufacturers. The EU Green Deal's indirect pressure through Japanese export supply chains accelerates demand for antibiotic-free certification in poultry operations supplying European markets. Stakeholders must monitor regulatory alignment between domestic feed safety protocols and evolving import market requirements to preserve market access and avoid stranded formulation investments.
Market Dynamics
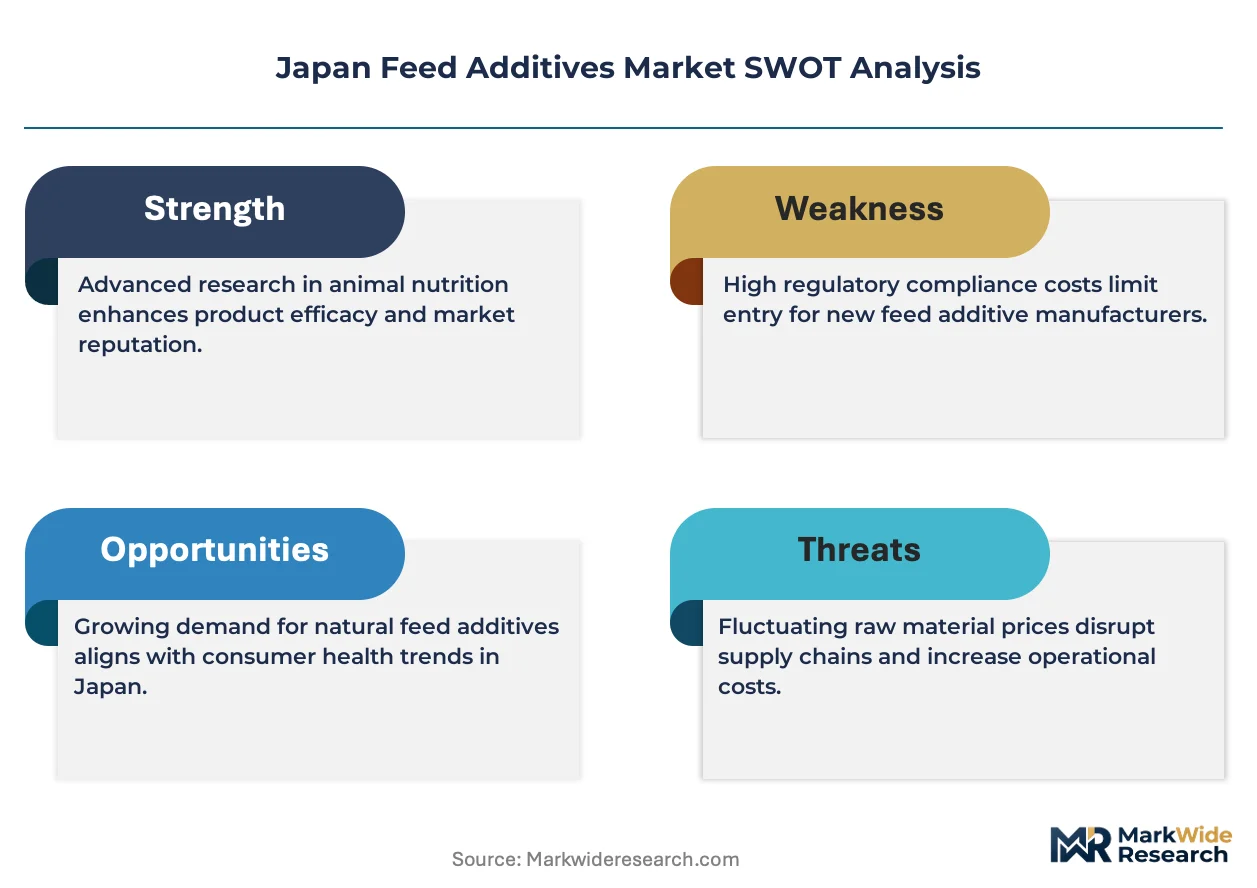
Japan's feed additives sector faces structural recalibration as METI tightens feed safety documentation and the F-Gas Regulation forces refrigeration-dependent vitamin premixes toward ammonia-compatible cold chains. These pressures intersect with regional livestock concentration patterns in Hokkaido and Kyushu, reshaping formulation priorities and distribution logistics simultaneously.
Growth Catalysts
- Antibiotic-free export protocols:EU Green Deal requirements transmitted through Japanese poultry supply chains accelerate probiotic and organic acid adoption in Ehime and Kagoshima processing facilities.
- Aquaculture expansion:Yellowtail and seabass producers in southern prefectures replace antibiotic growth promoters with specialized nucleotide additives, creating new formulation demand.
- Enzyme biotechnology maturation:Fermentation platforms in the Kanto region enable cost-competitive domestic production of xylanase and phytase tailored to barley-wheat rations.
Market Restraints
- Lysine supply concentration:Bulk amino acid imports flow through concentrated Osaka and Nagoya port infrastructure, exposing feed mills to shipping disruption risk.
- PMDA documentation burdens:Veterinary feed directive oversight extends approval timelines for novel additives, compressing product development windows.
- Cold-chain energy costs:F-Gas Regulation compliance requires ammonia cooling system retrofits for vitamin stability, elevating storage capital requirements.
Strategic Opportunities
- Automated feed manufacturing:Liquid enzyme formulations penetrate Kyushu broiler operations adopting continuous mixing systems, displacing powder handling.
- JIS Q 17065 certification:Organic feed additive standards create premium positioning for cooperatives serving Hokkaido dairy producers.
- Swine enzyme customization:Non-starch polysaccharide breakdown technologies address wheat-barley diet structures distinct from corn-soy import dependence.
Industry Challenges
- Fermentation scale-up expertise:Domestic amino acid production requires bioprocess engineering talent concentrated in legacy pharmaceutical clusters.
- Cooperative feed channel integration:Legacy premix distribution systems resist direct manufacturer engagement, complicating technical service deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Feed Additives Market |
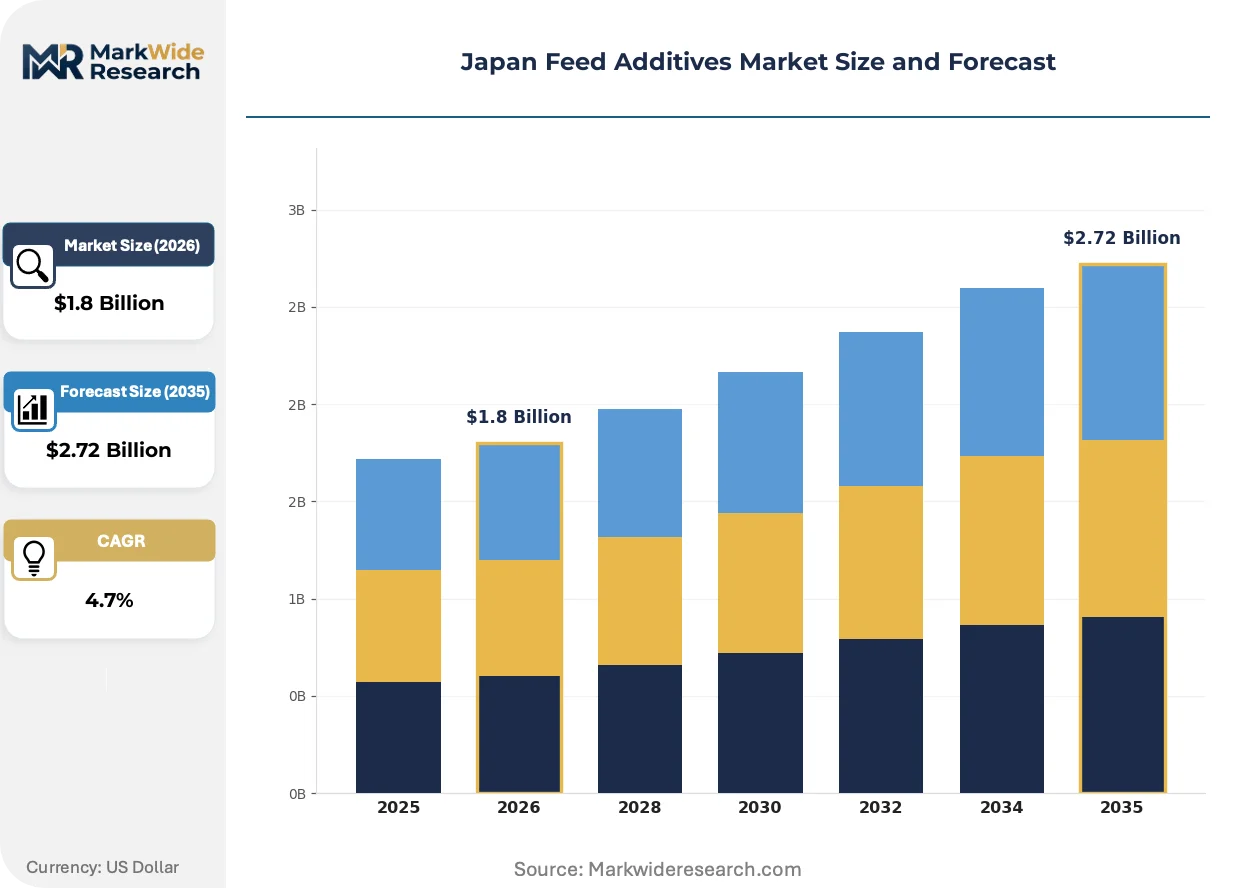
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Vitamins, Enzymes, Antibiotics Application: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granular, Premix End User: Farmers, Feed Manufacturers, Livestock Producers, Veterinary Clinics |
| Companies Covered | Cargill, Japan Nutrition Co., Ltd., BASF SE, Alltech Inc., Feedone Co., Ltd., Lallemand Inc., Ajinomoto Co., Inc., Chr. Hansen Holding A/S, Asahi Biocycle Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Feed Additives Market Shifts & Advancements
Biotechnology platforms and regulatory compliance architectures are converging to redefine competitive advantage in Japanese feed formulation. Three distinct vectors—process intensification, policy transmission, and procurement restructuring—are simultaneously altering how additives reach livestock operations.
Precision fermentation for amino acid production is miniaturizing. Ajinomoto's biotechnology platforms in the Kanto region now enable modular bioreactor deployment closer to feed mill clusters, reducing transport-induced lysine degradation. This distributed manufacturing model compresses supply chain nodes between fermentation output and final inclusion, challenging bulk import economics.
METI's feed manufacturing standards are tightening traceability requirements across the additive supply chain. The enforcement protocol mandates batch-level documentation from raw material sourcing through finished premix distribution, elevating compliance infrastructure costs for smaller cooperative feed mills. Poultry operations in Kyushu respond by consolidating supplier relationships toward vertically integrated amino acid providers capable of end-to-end certification.
Buyer concentration among Hokkaido dairy cooperatives is restructuring procurement negotiations. Large-scale livestock operations now demand multi-year vitamin premix contracts with embedded price adjustment mechanisms tied to energy and refrigeration input costs. This contractual innovation transfers cold-chain volatility risk from feed manufacturers to additive suppliers, compressing margin visibility across the analysis window.
Japan Feed Additives Market Segmentation
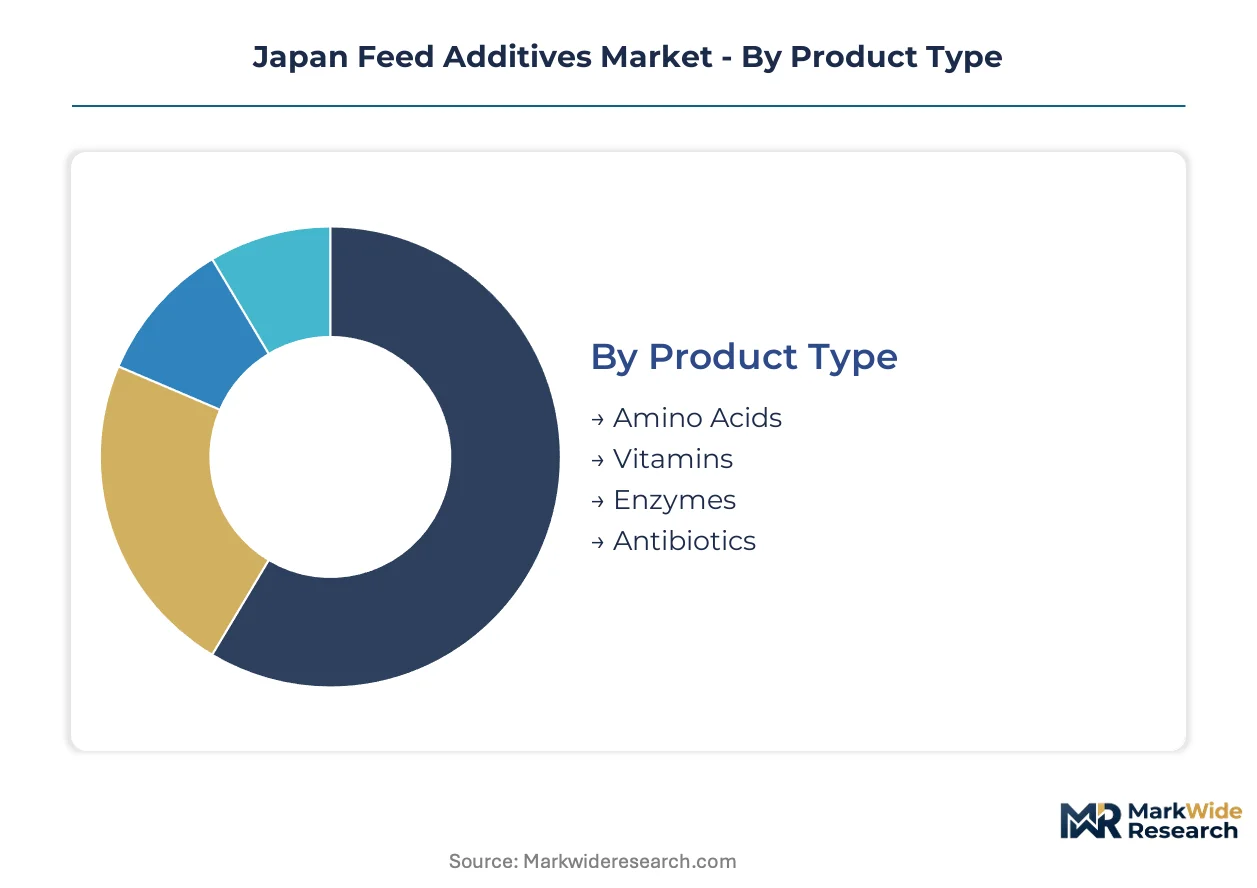
Segmentation in Japan's feed additives market reveals how regulatory pressure and livestock concentration reshape profit pools across product categories. Distinct formulation requirements emerge from Hokkaido's dairy cooperatives versus Kyushu's broiler operations.
Product Type:
Margin concentration follows amino acid and enzyme categories where domestic biotechnology capabilities offset import dependency.
- Amino Acids:Fermented lysine and methionine correct protein deficits in corn-soy rations. Kyushu poultry operations drive uptake as METI documentation requirements favor suppliers with end-to-end traceability systems.
- Enzymes:Xylanase and phytase formulations break down non-starch polysaccharides in barley-wheat diets common to Japanese swine herds. Kanto region fermentation platforms enable cost-competitive domestic output challenging bulk import economics.
- Vitamins:Cold-chain stability determines premix viability under F-Gas Regulation ammonia cooling mandates.
- Antibiotics:PMDA veterinary feed directive oversight compresses approval timelines and elevates documentation burdens.
Amino acids hold installed capacity. Enzymes are rotating up the share rankings.
Application:
Volume distribution tracks regional livestock clustering with aquaculture gaining structural momentum from antibiotic-free export protocols.
- Poultry:Broiler operations in Kyushu concentrate demand for amino acid premixes and liquid enzyme formulations compatible with automated feed manufacturing systems.
- Aquaculture:Yellowtail and seabass producers in Ehime and Kagoshima prefectures adopt specialized probiotic and nucleotide additives to replace antibiotic growth promoters for EU market access.
- Swine:Wheat-barley diet structures require customized non-starch polysaccharide breakdown technologies distinct from corn-soy import dependence.
- Ruminants:Hokkaido dairy cooperatives demand multi-year vitamin premix contracts with embedded energy cost adjustment mechanisms.
Poultry maintains volume leadership. Aquaculture shows the steepest expansion trajectory.
Form:
Physical format selection reflects automation penetration and cold-chain infrastructure maturity across feed mill networks.
- Powder:Dominates volume through legacy handling systems though faces displacement from liquid alternatives in continuous mixing operations.
- Liquid:Enzyme formulations penetrate Kyushu broiler facilities adopting automated feed manufacturing, eliminating powder handling labor and dust containment costs.
- Granular:Flowability advantages suit cooperative feed channel distribution with legacy premix infrastructure.
- Premix:Vitamin stability requirements elevate under F-Gas Regulation compliance pressures on refrigeration-dependent storage.
Powder retains installed base. Liquid is climbing the fastest.
End User:
Procurement authority concentrates among large-scale operations capable of absorbing METI compliance infrastructure costs.
- Feed Manufacturers:Osaka and Nagoya port infrastructure exposure shapes amino acid sourcing strategies with consolidation toward vertically integrated suppliers.
- Livestock Producers:Hokkaido dairy cooperatives leverage buyer concentration to negotiate multi-year contracts transferring cold-chain volatility risk to additive suppliers.
- Farmers:Smaller operations depend on cooperative channels resisting direct manufacturer technical service engagement.
- Veterinary Clinics:PMDA oversight extends feed directive documentation requirements into clinical advisory roles.
Feed manufacturers command procurement volume. Livestock producers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Osaka anchors amino acid import flows into western Japan's feed manufacturing corridor, while Nagoya's port infrastructure handles bulk enzyme shipments for Chubu region mills.
Kanto
Tokyo metropolitan demand concentrates around precision fermentation platforms producing fermented amino acids. METI feed manufacturing standards enforce batch-level traceability from raw material sourcing through finished premix distribution. Bioreactor clusters in Kanto enable modular manufacturing closer to feed mill networks, reducing transport-induced lysine degradation.
Kansai
Osaka and Nagoya port infrastructure exposes bulk amino acid flows to shipping disruption risk. PMDA veterinary feed directive oversight extends documentation requirements into clinical advisory roles. Feed manufacturers in this western corridor consolidate supplier relationships toward vertically integrated amino acid providers capable of end-to-end certification.
Kyushu
Broiler poultry operations drive uptake of liquid enzyme formulations compatible with automated feed manufacturing systems. EU Green Deal requirements transmitted through Japanese poultry supply chains accelerate probiotic adoption in processing facilities. Poultry operations respond by consolidating toward suppliers with embedded price adjustment mechanisms tied to energy costs.
Hokkaido
Dairy cooperatives concentrate procurement authority for cold-chain stable vitamin premixes under F-Gas Regulation ammonia cooling mandates. Large-scale livestock operations demand multi-year contracts transferring cold-chain volatility risk from feed manufacturers to additive suppliers. Buyer concentration among dairy cooperatives restructures procurement negotiations toward vertically integrated providers.
Japan Feed Additives Market Competitive Landscape
Listed leaders compete with private specialists across certification and fermentation technology dimensions, producing a tiered structure where scale advantages intersect with bioprocess expertise. The vendor base spans multinational chemical conglomerates, domestic biotechnology platforms, and cooperative feed channels resisting direct manufacturer engagement. Three archetypes dominate: global procurement networks securing bulk amino acid flows, domestic fermentation specialists leveraging proprietary biotechnology, and vitamin stability technology providers extending shelf-life advantages. Capacity expansion in modular bioreactor deployment and backward integration into captive amino acid supply represent the dominant competitive moves.
Within the domestic biotechnology tier, Ajinomoto Co., Inc. and Asahi Biocycle Co., Ltd. exemplify fermentation platform specialists leveraging Kanto region bioprocess engineering talent. Cargill represents the global procurement network archetype, anchoring bulk lysine and methionine supply chains through concentrated port infrastructure exposure. These three occupy distinct competitive positions: Ajinomoto anchors domestic fermented amino acid production, Asahi Biocycle sits within the organic feed additive certification vector, and Cargill exemplifies scale-driven import logistics mastery.
| Leading Market Players |
|---|
| Cargill |
| Japan Nutrition Co., Ltd. |
| BASF SE |
| Alltech Inc. |
| Feedone Co., Ltd. |
| Lallemand Inc. |
| Ajinomoto Co., Inc. |
| Chr. Hansen Holding A/S |
| Asahi Biocycle Co., Ltd. |
| Others |
Supply & Pricing Matrix
Modular bioreactor scale economies in the Kanto region compress unit production costs for fermented amino acids while simultaneously elevating price floors for bulk import alternatives. This dual dynamic concentrates supply authority among domestic biotechnology platforms and reshapes procurement negotiations across Hokkaido dairy cooperatives and Kyushu poultry operations.
Pricing Analysis
Three-tier pricing structure across JIS Q 17065 certified organic, METI-compliant standard, and uncertified economy grades dominates contract negotiations. Price differentiation rests on certification level and volume scale, with Hokkaido dairy cooperatives leveraging buyer concentration to extract multi-year agreements with embedded energy cost adjustments. Cost compression in standard-grade vitamin premixes is intensifying because F-Gas Regulation ammonia cooling retrofits elevate storage capital requirements. Small-scale farmers through cooperative channels exhibit highest price sensitivity, while vertically integrated livestock producers demonstrate lowest sensitivity due to captive formulation capabilities.
Supply Chain Analysis
Strategic stockpile preferences dominate amino acid procurement given Osaka and Nagoya port infrastructure exposure, while just-in-time enzyme flows prevail through Kanto region fermentation clusters. Geographic supply concentration centers on China and Southeast Asia for bulk lysine and methionine, with domestic Japanese biotechnology platforms providing phytase and xylanase. Raw material dependencies include corn and soybean meal for amino acid inclusion matrices, barley and wheat for enzyme-active substrates, and refrigeration-grade ammonia for vitamin stability. Single-source vulnerability through concentrated port infrastructure represents the primary structural risk. Distribution runs through cooperative feed channels resisting direct manufacturer engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of bioprocess engineering talent concentrated in legacy pharmaceutical clusters constrains domestic fermentation scale-up and elevates acquisition premiums for specialized capabilities. This talent bottleneck shapes competitive dynamics across certification tiers and regional procurement negotiations.
For Market Incumbents: Shield market position by securing exclusive amino acid supply agreements with Osaka and Nagoya port operators to mitigate shipping disruption risk. Deepen backward integration into captive lysine production through modular bioreactor deployment in Kanto feed mill clusters. METI documentation burdens favor incumbents with end-to-end traceability systems already operational. For New Entrants and Emerging Players: JIS Q 17065 certification fast-track offers premium positioning entry into Hokkaido dairy cooperative supply chains. White-space targets include liquid enzyme formulations for Kyushu broiler automation and nucleotide additives for Ehime aquaculture export certification. Aquaculture probiotic segments show lowest incumbent saturation and highest regulatory tailwind from EU Green Deal transmission. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation platform specialists with multi-year cooperative contracts. Long-term viability across the projection horizon favors targets with proprietary biotechnology and cold-chain stability IP. Acquisition focus should center on mid-cap domestic players with METI certification infrastructure. Signal to monitor: PMDA veterinary feed directive timeline compression accelerating consolidation toward vertically integrated providers.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Bioreactor Deployment | Kanto region proximity to feed mills reduces lysine transport degradation and import dependency. |
| JIS Q 17065 Certification Investment | Organic feed additive standards unlock premium pricing in Hokkaido dairy cooperative channels. |
| Ammonia Cold-Chain Retrofit | F-Gas Regulation compliance preserves vitamin premix shelf-life for refrigerated distribution. |
| Aquaculture Probiotic Development | EU Green Deal export protocols drive nucleotide additive substitution for antibiotic growth promoters. |
| Cooperative Channel Technical Service | Direct manufacturer engagement overcomes legacy premix distribution resistance in rural feed networks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with feed mill procurement directors, biotechnology platform R&D leads, cooperative channel managers, and METI compliance officers; and secondary validation through customs trade records, PMDA veterinary feed directive filings, JIS certification databases, and livestock production statistics. Bottom-up volume estimates from prefecture-level feed consumption data triangulated against top-down amino acid import flows through Osaka and Nagoya port authorities.
Across the analysis window, forecasts employed segmented modeling by product type, application livestock category, physical form, and end-user procurement authority. CAGRs derived from historical feed additive inclusion rate trajectories, livestock herd expansion projections, and regulatory phase-in timelines. Industry-specific inputs incorporated F-Gas Regulation ammonia cooling adoption curves and PMDA documentation burden escalation patterns.
Underlying assumptions cover stable METI enforcement intensity and continued EU Green Deal supply chain pressure, with deviation risk concentrated in shipping disruption through concentrated port infrastructure and biotechnology talent migration. Forecasts reflect these conditions with acknowledgment that regulatory acceleration or trade flow reconfiguration would warrant model revision. Revision becomes warranted when PMDA approval timeline compression crosses thresholds forcing formulation portfolio restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Low Methoxyl Pectin Market
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
South America Food Acidulants Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Argentina Food Enzymes Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Scrambled Egg Mix Market
Food Additives and Ingredients
Australia Feed Additives Market