
 Nisin for Food Market | 2026-2036
Nisin for Food Market Size, Share, and Industry Trends Forecast 2026-2036
Nisin for Food Market Insights
EU F-Gas Regulation is decoupling synthetic preservative economics from natural antimicrobial viability, elevating nisin's cost-competitiveness against chemical alternatives. Koninklijke DSM NV leverages its fermentation infrastructure across Dutch and Chinese facilities to sustain supply security for European dairy clients. GALACTIC SA/NV anchors its position through specialized lactic acid bacteria strain banks that differentiate purity grades for premium meat processors. DuPont de Nemours, Inc. competes by extending its GRAS certification portfolio into novel beverage applications where thermal stability requirements are tightening.
Nisin is a polycyclic antibacterial peptide produced by fermentation of Lactococcus lactis, containing 34 amino acid residues with molecular weight near 3,354 Da and activity against Gram-positive spoilage organisms and pathogens. The peptide binds lipid II to inhibit cell wall synthesis, making it indispensable for shelf-life extension in minimally processed foods where consumer preference favors label-friendly preservation. Powdered nisin dominates formulation flexibility across industrial bakeries and meat plants, while liquid nisin solutions are capturing fastest growth in beverage pasteurization lines where dosing precision reduces waste. Dairy applications occupy the deepest margin pools due to stringent spoilage thresholds in cheese and flavored milk supply chains.
FDA GRAS status and USDA FSIS compliance frameworks govern nisin deployment in US meat and poultry matrices, while EFSA positive opinions under EU food additive regulations shape formulation acceptance across member states. China's SAMR and NMPA coordinate national food safety standards that progressively align with CODEX specifications for natural preservatives, expanding manufacturing license eligibility for domestic biotech suppliers. Stakeholders must monitor regulatory divergence between jurisdictions on maximum permitted levels and labeling declarations, as these thresholds will determine which production scales achieve viable unit economics.
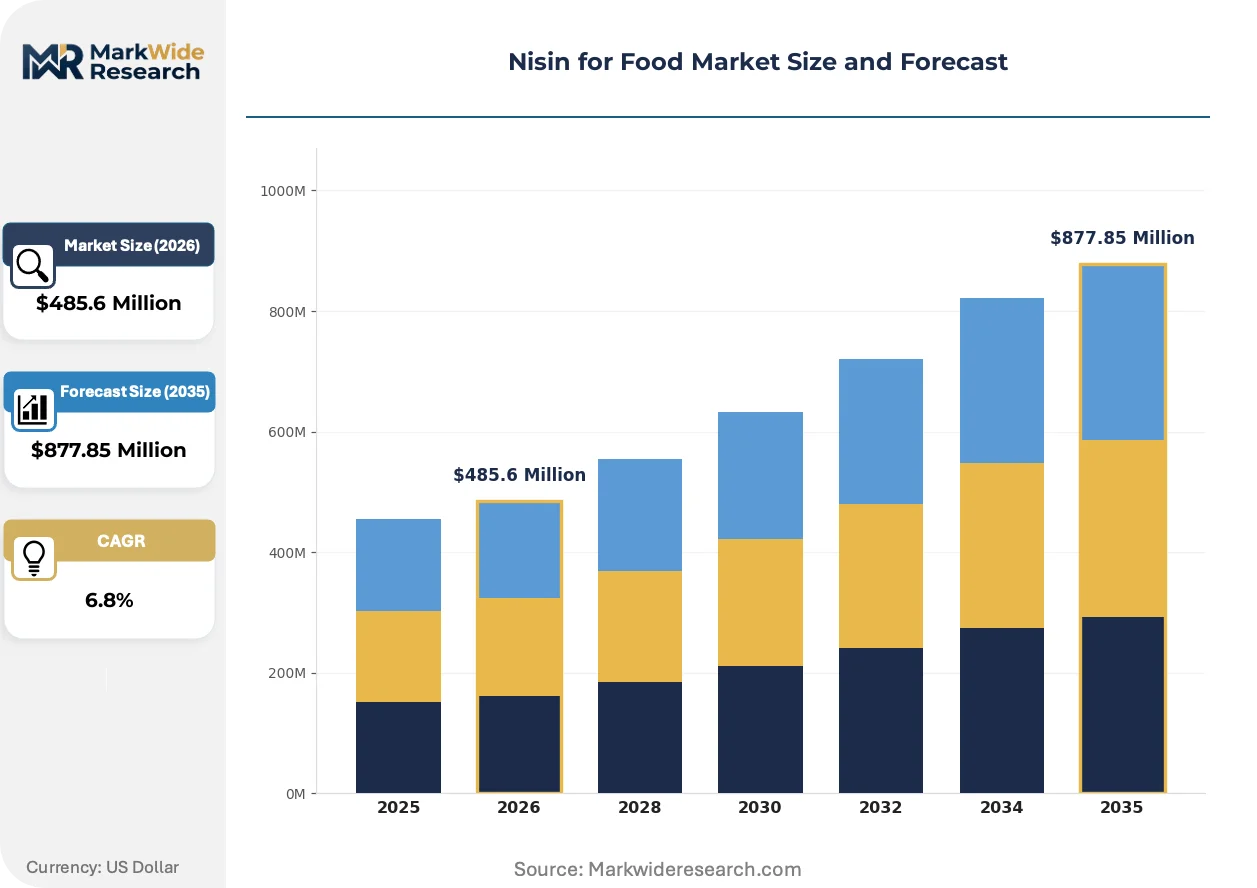
Market Dynamics
EFSA's clean-label mandates are compressing synthetic preservative economics across European dairy and meat supply chains, elevating fermentation-derived nisin as the default cell-wall inhibitor for minimally processed formulations.
Growth Catalysts
- F-Gas Regulation:The EU F-Gas Regulation is raising synthetic preservative production costs, narrowing the price gap between chemical antimicrobials and fermentation-derived nisin in Dutch and German dairy processing.
- Clean-label meat processing:European meat processors are reformulating cured and ready-to-eat products to eliminate benzoates and sorbates ahead of EFSA's tightened additive safety reviews.
- SAMR approvals:China's SAMR is expanding nisin's permitted applications in flavored beverages and bakery, unlocking manufacturing licenses for domestic biotech suppliers in Shandong and Jiangsu provinces.
Market Restraints
- Fermentation feedstock volatility:Lactose and yeast extract prices fluctuate with dairy commodity cycles, squeezing margin stability for nisin producers dependent on agricultural inputs.
- Gram-negative spectrum limitation:Nisin's binding mechanism targets lipid II in Gram-positive organisms only, leaving processors to combine it with other antimicrobials for full-spectrum protection in complex food matrices.
- Thermal degradation threshold:The peptide loses activity above 121°C, restricting deployment in ultra-high-temperature sterilization lines where chemical alternatives retain stability.
Strategic Opportunities
- Plant-based dairy analogues:Oat and almond milk processors in California and Nordic markets are testing nisin for spoilage control in neutral-pH beverages where traditional acidification is unsuitable.
- Biopreservation cocktails:Synergistic formulations combining nisin with natamycin or lysozyme are opening shelf-life extension protocols for clean-label cheese rinds and refrigerated pasta.
- CODEX alignment in India:FSSAI's progressive harmonization with CODEX natural preservative standards is accelerating nisin approval timelines for domestic paneer and processed meat categories.
Industry Challenges
- Fermentation scale-up expertise:Qualified bioprocess engineers capable of optimizing Lactococcus lactis titers in industrial bioreactors remain concentrated in legacy antibiotic and enzyme production hubs.
- GRAS dossier navigation:Novel application submissions to FDA require extensive safety pharmacology data, extending time-to-market for beverage and plant-based categories beyond typical food additive pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nisin for Food Market |
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $877.85 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Nisin, Powdered Nisin, Granular Nisin, Nisin Solutions Application: Dairy Products, Meat Processing, Beverages, Bakery Products Distribution Channel: Online Retail, Wholesale Distribution, Direct Sales, Supermarkets End User: Food Manufacturers, Restaurants, Retailers, Catering Services |
| Companies Covered | Koninklijke DSM NV, GALACTIC SA/NV, DuPont de Nemours, Inc., Siveele B.V., Shandong Freda Biotechnology Co., Ltd, Cayman Chemical Company, Inc., Zhejiang Silver-Elephant Bioengineering, Chihon Biotechnology Co., Ltd, Handary S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nisin for Food Market Trends and Innovations
Microencapsulation technologies are reshaping nisin's thermal stability profile, enabling deployment in heat-intensive processing environments previously closed to peptide-based preservation. These advances coincide with regulatory pressure on synthetic alternatives and processor demand for precision dosing systems.
Encapsulated nisin in lipid or polysaccharide matrices is expanding into UHT beverage and retort pouch applications where unprotected peptide degradation previously excluded natural antimicrobials. Japanese and South Korean dairy conglomerates are piloting these systems in flavored milk lines. The technology is compressing the performance gap between fermentation-derived and chemical preservatives in high-temperature processing.
REACH and F-Gas Regulation compliance costs are accelerating synthetic antimicrobial phase-outs across EU member states. EFSA's 2023-2024 re-evaluations of benzoic acid derivatives have triggered reformulation deadlines for meat and sauce manufacturers. German and Italian processors are advancing nisin adoption in ready-to-eat categories ahead of scheduled additive restrictions.
Buyer concentration among European retail private-label programs is consolidating preservative procurement decisions into centralized technical teams. These teams now specify clean-label thresholds that disqualify traditional chemical options in shelf-stable deli meats and refrigerated soups. The shift is most visible in Netherlands and Denmark, where retailer sustainability scorecards weight natural ingredient sourcing heavily.
Nisin for Food Market Segmentation
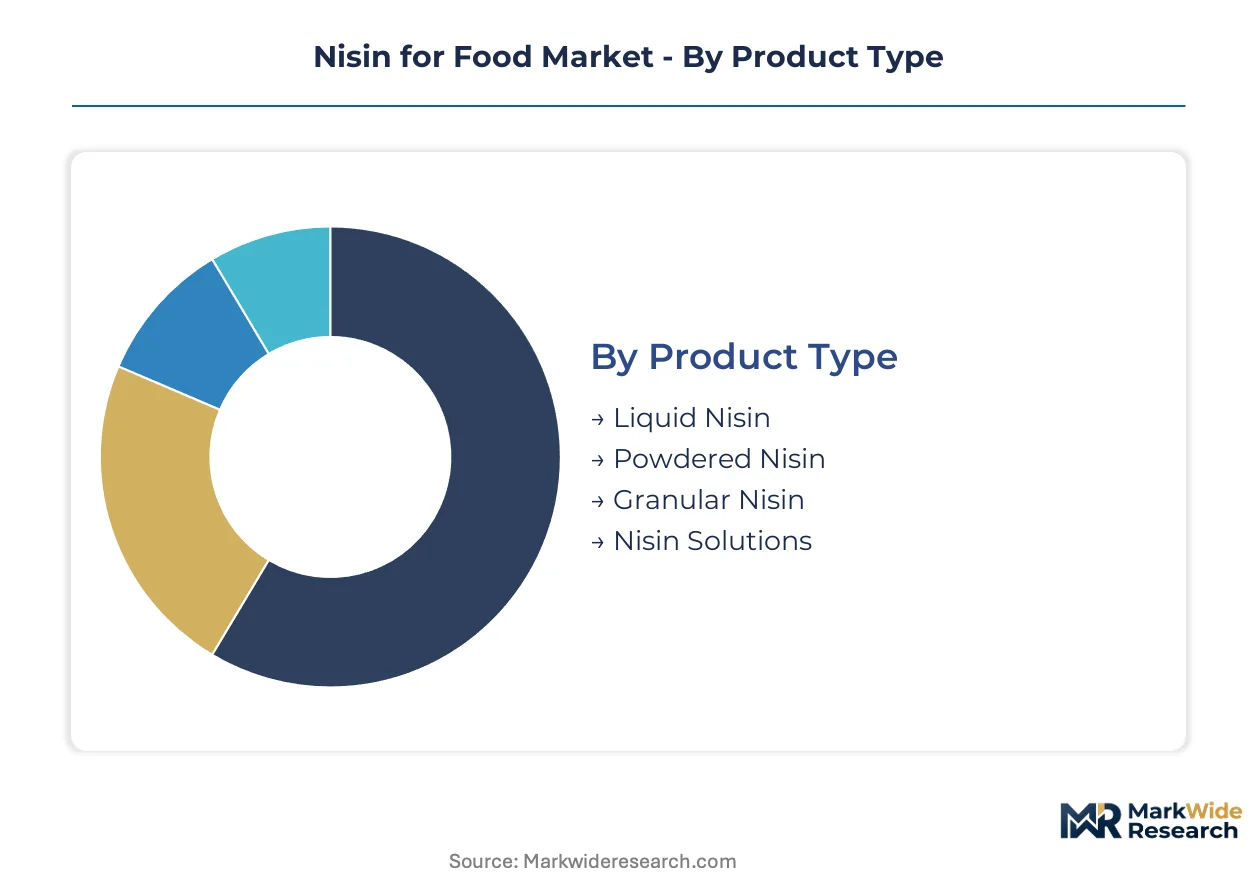
Nisin formulation geometry and delivery format determine thermal stability, dosing precision, and supply chain economics for food processors. Segment boundaries reflect divergent technical requirements across heat-intensive pasteurization lines versus ambient-temperature meat curing operations.
Product Type:
Procurement decisions hinge on solubility profiles and handling infrastructure at processing facilities.
- Powdered Nisin:Spray-dried peptide concentrate offers formulation flexibility across industrial bakeries and meat plants where dry blending integrates with existing seasoning systems. European cured meat processors favor this format for its extended ambient stability during distribution.
- Liquid Nisin:Aqueous solutions enable precise dosing in beverage pasteurization lines where automated injection systems reduce waste. German and Dutch dairy conglomerates are expanding captive storage capacity for this format in flavored milk operations.
- Granular Nisin:Free-flowing agglomerated particles suit high-throughput seasoning drums in snack and processed meat applications where dust control matters.
- Nisin Solutions:Pre-diluted concentrates target small-batch processors lacking in-house formulation expertise, common in regional bakery cooperatives.
Powdered nisin leads on scale; liquid nisin gains share fastest in high-temperature processing environments.
Application:
Spoilage thresholds and pH constraints divide addressable markets by commodity value chain.
- Dairy Products:Cheese and flavored milk supply chains command premium formulation economics due to stringent microbial thresholds in extended cold distribution. EFSA-positive opinions on natural preservatives have accelerated nisin adoption in Dutch Gouda and Italian Provolone aging protocols.
- Meat Processing:Ready-to-eat cured products face reformulation deadlines as EFSA tightens benzoate and sorbate safety reviews. German and Italian processors are advancing nisin deployment ahead of scheduled additive restrictions.
- Beverages:Neutral-pH oat and almond milk analogues in California and Nordic markets test nisin where traditional acidification is unsuitable.
- Bakery Products:Extended-shelf-life bread and refrigerated pasta applications favor nisin-natamycin synergistic protocols for clean-label positioning.
Dairy leads on margin capture; meat processing climbs fastest on regulatory displacement of synthetic alternatives.
Distribution Channel:
Volume scale and technical service intensity shape channel selection for nisin procurement.
- Wholesale Distribution:Industrial ingredient distributors consolidate procurement for mid-tier meat and dairy processors across European food manufacturing clusters.
- Direct Sales:Koninklijke DSM NV and GALACTIC SA/NV maintain technical sales teams for large accounts requiring fermentation strain documentation and regulatory dossier support.
- Online Retail:E-procurement platforms capture small-batch food artisans and regional bakery cooperatives in China and India.
- Supermarkets:Limited penetration; specialty retail channels for consumer-facing probiotic and preservation ingredient kits.
Wholesale distribution leads on volume; direct sales deepens on technical specification complexity.
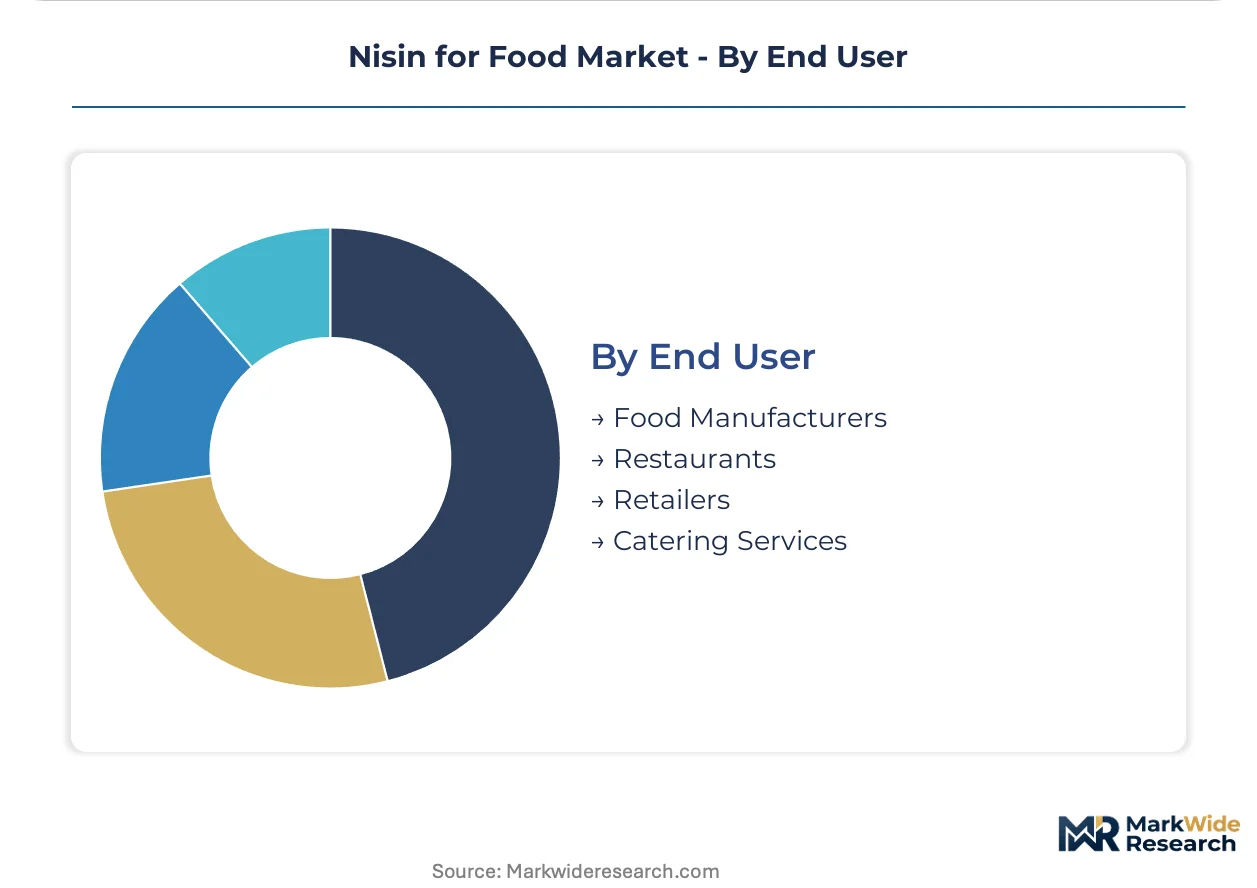
End User:
Formulation expertise and regulatory compliance burden differentiate buyer sophistication tiers.
- Food Manufacturers:Industrial processors in Shandong and Jiangsu provinces leverage expanded SAMR manufacturing licenses for domestic nisin production.
- Restaurants:Central kitchen operations in chain foodservice test nisin for sous-vide and cook-chill applications.
- Retailers:Private-label technical teams in Netherlands and Denmark specify clean-label thresholds that disqualify chemical preservatives in shelf-stable deli meats.
- Catering Services:Institutional foodservice contractors adopt nisin for extended-hold buffet applications where temperature abuse risk concentrates.
Food manufacturers lead on procurement scale; retailers drive fastest specification tightening through sustainability scorecards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nisin fermentation technology originated in British dairy science laboratories during the early twentieth century, with industrial-scale production consolidating in Dutch and Belgian biotech corridors by the 1980s. Contemporary demand geography reflects this heritage while shifting toward Asia-Pacific manufacturing centers.
Netherlands
Dutch dairy conglomerates command the deepest nisin integration in European cheese aging protocols, particularly for Gouda and Edam varieties requiring extended cold distribution. EFSA's clean-label mandates under EU food additive regulations are accelerating synthetic preservative displacement across Rotterdam and Eindhoven processing clusters. DSM's fermentation infrastructure in Delft and Venlo sustains supply security for continental dairy clients facing reformulation deadlines.
Germany
German meat processors in Bavaria and North Rhine-Westphalia are advancing nisin deployment in ready-to-eat cured products ahead of EFSA's tightened benzoate safety reviews. The EU F-Gas Regulation is elevating fermentation-derived antimicrobials' cost-competitiveness against chemical alternatives in Munich and Stuttgart manufacturing zones. Private-label technical teams at Aldi and Lidl headquarters now specify clean-label thresholds that disqualify traditional preservatives.
China
Shandong and Jiangsu provinces concentrate domestic nisin manufacturing capacity as SAMR expands permitted applications in flavored beverages and bakery. National food safety standards under NMPA coordination are progressively aligning with CODEX specifications, unlocking manufacturing licenses for biotech suppliers in Qingdao and Nanjing. Oat milk processors in Shanghai and Beijing are testing nisin for spoilage control in neutral-pH beverages.
India
FSSAI's harmonization with CODEX natural preservative standards is accelerating nisin approval timelines for paneer and processed meat categories in Maharashtra and Gujarat. Domestic dairy cooperatives in Anand and Pune are piloting fermentation-derived preservation for extended shelf-life milk distribution. Regulatory convergence is attracting technical partnerships between European strain banks and Indian bioprocess engineering firms.
United States
FDA GRAS status and USDA FSIS compliance frameworks govern nisin deployment in meat and poultry matrices across Chicago and Omaha processing corridors. California oat and almond milk processors are testing the peptide for spoilage control where traditional acidification is unsuitable. GRAS dossier navigation for novel beverage applications remains complex, extending time-to-market for plant-based categories beyond typical food additive pathways.
Nisin for Food Market Competitive Landscape
The competitive structure tilts toward fermentation specialists with captive strain banks and regulatory dossier expertise. Three tiers operate: multinational life-science conglomerates with diversified biotech portfolios, mid-cap fermentation houses focused exclusively on lactic acid bacteria derivatives, and regional Chinese biotech suppliers scaling domestic manufacturing licenses. Dominant competitive moves include backward integration into specialized lactic acid bacteria strain development and geographic expansion through SAMR manufacturing license acquisition in Shandong and Jiangsu provinces.
Among European fermentation specialists, Koninklijke DSM NV and GALACTIC SA/NV exemplify the integrated-strain-bank archetype, occupying positions where regulatory documentation and purity grade differentiation anchor client relationships. Within the Chinese supplier tier, Shandong Freda Biotechnology Co., Ltd represents the domestic-scale archetype, sitting within a regulatory environment where SAMR approvals are unlocking manufacturing capacity expansion.
| Leading Market Players |
|---|
| Koninklijke DSM NV |
| GALACTIC SA/NV |
| DuPont de Nemours, Inc. |
| Siveele B.V. |
| Shandong Freda Biotechnology Co., Ltd |
| Cayman Chemical Company, Inc. |
| Zhejiang Silver-Elephant Bioengineering |
| Chihon Biotechnology Co., Ltd |
| Handary S.A. |
| Others |
Pricing and Supply Chain Analysis
Family-owned fermentation specialists in Belgium and the Netherlands anchor supply-side discipline, translating captive strain-bank ownership into pricing power that resists commodity erosion even as Chinese state-backed biotech suppliers expand domestic capacity under SAMR manufacturing licenses.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade purity levels segments buyer access by certification burden and volume commitment. Price differentiation hinges on EFSA dossier completeness and fermentation titer consistency, with pharmaceutical-grade commanding substantial premia for documented strain lineage. Pricing pressure stems from Shandong and Jiangsu capacity additions compressing mid-tier margins. Small-batch artisanal processors exhibit highest price sensitivity; multinational dairy conglomerates prioritize supply security over unit cost.
Supply Chain Analysis
Domestic-content mandates under China's Made in China 2025 biotechnology roadmap are redirecting procurement toward Qingdao and Nanjing manufacturing clusters, reducing European import dependency for domestic food processors. Supply concentrates in the Netherlands, Belgium, and China, with lactose and yeast extract feedstocks drawing from dairy commodity cycles in New Zealand and EU agricultural basins. Single-source vulnerability concentrates in specialized Lactococcus lactis strain banks held by legacy antibiotic producers. Distribution runs through industrial ingredient wholesalers consolidating European procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nisin market functions as a geographic-arbitrage play where EFSA clean-label mandates compress synthetic preservative economics in Europe faster than SAMR approval timelines unlock Chinese domestic manufacturing, creating margin capture windows for fermentation specialists with cross-regional licensing.
For Market Incumbents: Anticipate regulatory divergence between EFSA maximum permitted level reviews and SAMR manufacturing license expansion, defending position through backward integration into specialized lactic acid bacteria strain development and capacity addition in Jiangsu province ahead of domestic demand inflection. GRAS dossier navigation expertise represents the critical lever against emerging Chinese biotech entrants. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian paneer and processed meat applications offers white-space entry where FSSAI-CODEX harmonization lags European regulatory stringency. Target Maharashtra and Gujarat dairy cooperatives with technical partnership proposals leveraging European strain-bank documentation. Position through biopreservation cocktail formulations combining nisin with natamycin for clean-label cheese rind applications. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap fermentation houses with SAMR manufacturing licenses but incomplete EFSA dossier portfolios, offering regulatory-arbitrage upside as clean-label mandates tighten. Long-term viability hinges on 5-10 year displacement of benzoates and sorbates across European meat processing. Watch EFSA re-evaluation timelines for synthetic additive safety reviews as the decisive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Bank Acquisition | Captive Lactococcus lactis genetics secure purity-grade differentiation for EFSA-compliant dairy clients. |
| SAMR Manufacturing License Expansion | Domestic Chinese production eligibility unlocks cost-competitive supply for Asia-Pacific beverage processors. |
| Microencapsulation R&D Partnership | Thermal stability advances enable UHT beverage deployment previously closed to peptide preservatives. |
| Biopreservation Cocktail Formulation | Synergistic natamycin-lysozyme combinations extend addressable markets to Gram-negative contaminated matrices. |
| Direct Sales Technical Team Buildout | In-house regulatory dossier expertise reduces buyer procurement friction for novel application categories. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, dairy procurement leads, regulatory affairs directors at biotech suppliers, and EFSA scientific committee members with secondary validation through FDA GRAS notices, EFSA food additive opinions, SAMR manufacturing license registries, and customs trade data for nisin concentrate imports. Bottom-up facility capacity assessments and top-down demand modeling triangulated volume estimates.
Segment-weighting across product type, application, and distribution channel dimensions structured the analytical framework, with dairy, meat processing, and beverage end-uses receiving distinct spoilage-threshold coefficients. CAGRs derived from regulatory timeline modeling for synthetic additive phase-outs cross-referenced against fermentation capacity expansion announcements. Feedstock cost volatility in lactose and yeast extract markets informed margin sensitivity scenarios.
Caveats apply where EFSA re-evaluation timelines or SAMR approval accelerations could materially shift the outlook, particularly if microencapsulation advances compress the performance gap with chemical preservatives faster than modeled. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
North America Food Stabilizers Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
Latin America Food Enzymes Market
Food Additives and Ingredients
Europe Food Colorants Market
Food Additives and Ingredients
Argentina Food Emulsifiers Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Food Grade Glue Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Caramel Food Colors Market