
 India Essential Oils Market | 2026-2036
India Essential Oils Market Size, Share, and Industry Trends Forecast 2026-2036
India Essential Oils Market Outlook
The India essential oils trade is realigning around a widening gulf between certified organic grades and mass-market solvent-extracted volumes. Veda Oils leverages captive lavender fields in Kashmir to command premium pricing in aromatherapy channels. Khadi Natural anchors its position through government emporium distribution and ayurvedic heritage branding. DBR Exports India competes on bulk peppermint and eucalyptus shipments to European fragrance houses.
Essential oils are hydrophobic, volatile aromatic compounds extracted through steam distillation, cold pressing, or solvent extraction, typically containing terpenes, esters, and phenolic fractions in concentrations that define therapeutic grade versus commercial grade. Their primary commercial purpose spans fragrance formulation, therapeutic application, and natural preservation systems. Lavender oil and tea tree oil occupy the fastest-expanding demand pools, driven by clean-label cosmetics and clinical aromatherapy validation. The Spa & Wellness end-use segment extracts disproportionate margins from certified organic supply chains, while Food & Beverage applications remain constrained by FSSAI batch-testing requirements.
BIS standards for essential oil purity, FSSAI food-grade additive clearances, and state-level AYUSH department licensing collectively determine which processors gain formal market access versus gray-channel operators. CDSCO scrutiny of therapeutic claims on aromatherapy products is tightening label compliance costs for domestic brands. Stakeholders must monitor how export certification alignment with REACH and USDA Organic rules reshapes competitive eligibility for EU and North American buyers.
Market Dynamics
FSSAI's tightened purity standards for food-grade essential oils are compressing unorganized supply channels and forcing capital investment into certified distillation infrastructure. This regulatory pressure is concentrating processing capacity among licensed operators who can absorb batch-testing costs.
Growth Catalysts
- Clean-label cosmetics:Cosmetics manufacturers absorb rising volumes of lavender and tea tree oils for personal care lines, pulling demand toward therapeutic-grade supply chains.
- PLI scheme:India's production-linked incentive scheme for herbal products subsidizes distillation equipment upgrades, accelerating formalization of contract farming networks in Maharashtra and Karnataka.
- Steam distillation modernization:Automated temperature controls and vacuum-assisted extraction improve yield consistency, enabling processors to meet European fragrance house specifications.
Market Restraints
- Input cost volatility:Lavender and chamomile cultivation faces climate-driven yield fluctuations in Kashmir and Himachal Pradesh, compressing margins for fixed-price contract suppliers.
- Regulatory friction:CDSCO scrutiny of therapeutic claims on aromatherapy products tightens label compliance costs, delaying product launches for domestic brands.
- Substitution threat:Synthetic fragrance compounds from petrochemical feedstocks undercut natural oil pricing in mass-market soap and detergent applications.
Strategic Opportunities
- Underpenetrated aromatherapy:Tier-2 cities in Gujarat and Tamil Nadu show latent demand for clinical-grade oils, with wellness chains expanding beyond Mumbai and Bangalore.
- Export certification alignment:USDA Organic and REACH compliance opens EU and North American buyer pools, rewarding processors who invest in traceability systems.
- Spa & Wellness channel:Certified organic supply chains extract disproportionate margins from luxury hotel chains and ayurvedic retreat operators.
Industry Challenges
- Skill gap in chromatography analysis:FSSAI-mandated purity testing requires gas chromatography-mass spectrometry expertise that rural distillation clusters cannot source locally.
- Capex intensity for stainless-steel stills:Food-grade copper and stainless-steel distillation equipment demands upfront investment that unorganized processors cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Essential Oils Market |
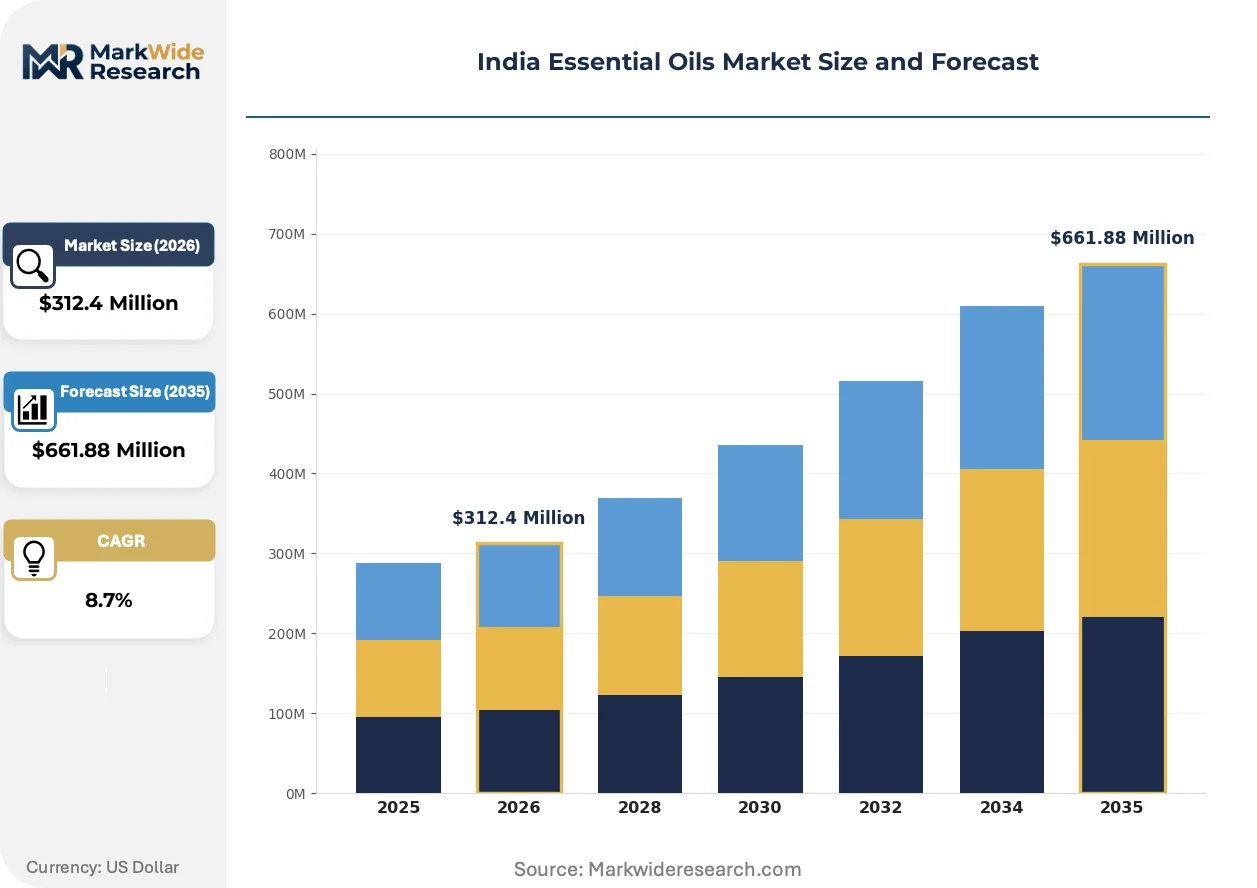
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lavender Oil, Tea Tree Oil, Peppermint Oil, Eucalyptus Oil End Use: Cosmetics, Pharmaceuticals, Food & Beverage, Spa & Wellness Sales Channel: Online, Retail, Direct Sales, Distributors Application: Aromatherapy, Flavoring, Fragrance, Household Cleaning |
| Companies Covered | Veda Oils, Khadi Natural, DBR Exports India, JK Aromatics & Perfumers, Gem Aromatics Limited, Moksha Lifestyle, Aroma Magic, IndiaAroma, Nature's Natural India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Essential Oils Market Strategic Shifts
Extraction technology and certification protocols are reshaping competitive positioning. Processors who integrate quality assurance with captive raw material sourcing gain pricing power in premium channels.
Supercritical CO2 extraction is modularizing downstream processing for high-value terpene recovery. Specialty fragrance houses in Bangalore adopt this technology to isolate specific aromatic fractions. The modular approach compresses batch-to-batch variation, enabling consistent supply to European buyers who reject steam-distilled alternatives.
FSSAI's 2023 notification on solvent residue limits in food-grade oils is forcing reformulation of commercial extraction processes. Processors must validate hexane-free methods or exit the food additive segment. Maharashtra-based distillation clusters are responding by segregating food-grade and cosmetic-grade production lines to isolate compliance costs.
Buyer concentration among contract manufacturers is shortening payment cycles and demanding certificate-of-analysis documentation with every shipment. Small-batch artisanal producers in Uttarakhand cannot absorb this administrative burden, ceding share to organized players with in-house laboratory capacity. The shift is most visible in the export channel, where European buyers now mandate batch-level traceability from farm to finished oil.
India Essential Oils Market Segmentation
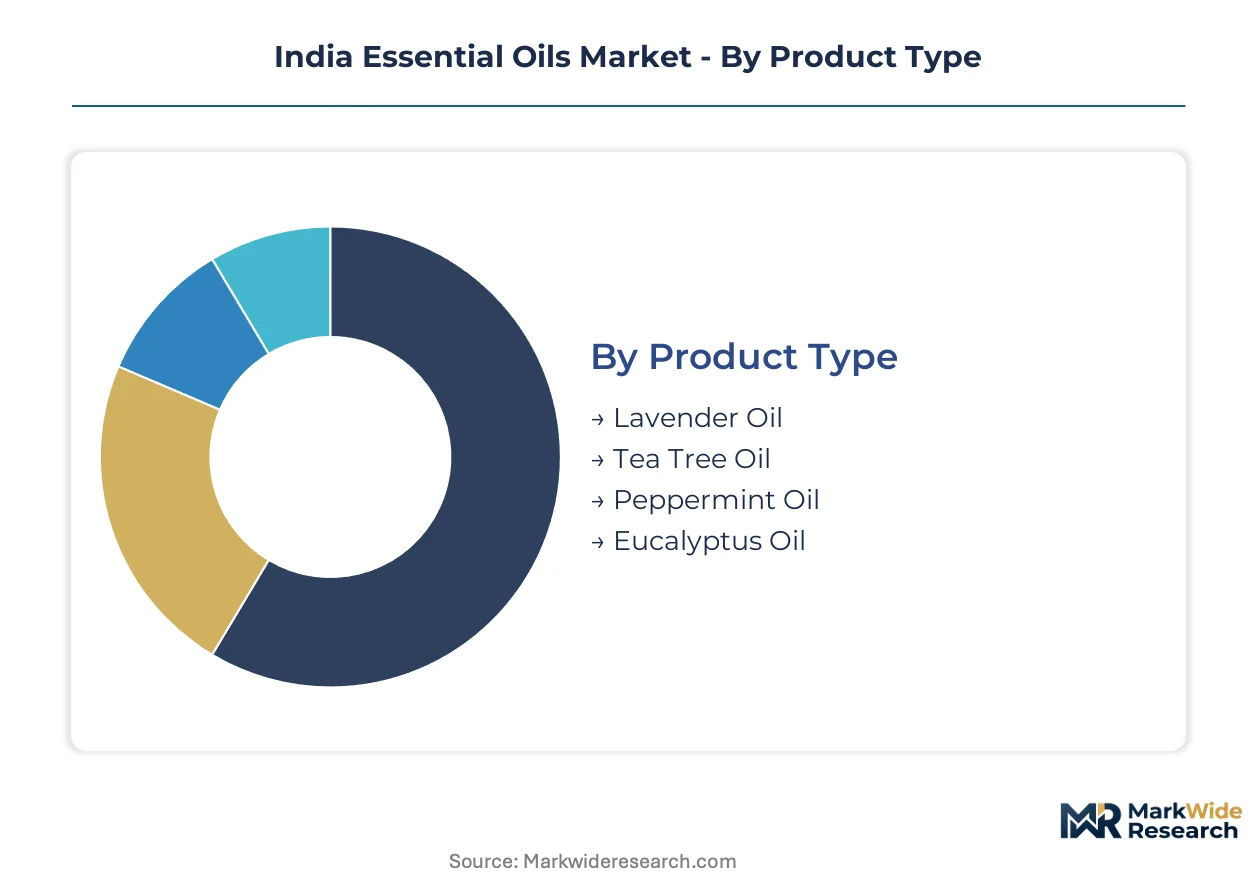
Segmentation in the India essential oils market tracks how extraction methods, purity grades, and certification tiers split demand across incompatible buyer specifications. Processors must align product portfolios with distinct regulatory thresholds governing food-grade, cosmetic-grade, and therapeutic-grade supply chains.
Product Type:
Distillation capacity concentrates around oils with established contract farming networks in Maharashtra and Karnataka, where climate-controlled cultivation secures batch consistency for export buyers.
- Lavender Oil:Steam-distilled floral tops yield linalool and linalyl acetate fractions prized in aromatherapy formulations. Maharashtra processors supply bulk volumes to European fragrance houses, though Kashmir's organic grades command premium positioning in spa channels.
- Tea Tree Oil:Terpinen-4-ol concentration defines therapeutic grade versus commercial grade, with Karnataka distillation clusters feeding clean-label cosmetic manufacturers. FSSAI purity mandates are compressing unorganized supply of food-grade variants.
- Peppermint Oil:Menthol crystallization from Mentha arvensis dominates Bihar and Uttar Pradesh cultivation belts.
- Eucalyptus Oil:Cineole content specifications vary sharply between pharmaceutical and fragrance applications.
Today's leader: Lavender Oil. Tomorrow's challenger: Tea Tree Oil.
End Use:
Margin structures diverge sharply between regulated pharmaceutical channels and discretionary spa applications, with certification costs determining viable market entry.
- Cosmetics:Clean-label personal care lines absorb therapeutic-grade lavender and tea tree oils, with CDSCO cosmetic registration requirements filtering supplier pools. Karnataka-based contract manufacturers drive volume concentration.
- Spa & Wellness:Certified organic supply chains extract disproportionate margins from luxury hotel chains and ayurvedic retreat operators in Kerala and Rajasthan. USDA Organic certification opens export eligibility to North American wellness chains.
- Pharmaceuticals:CDSCO drug master file requirements limit formulation access to GMP-certified distillers.
- Food & Beverage:FSSAI batch-testing mandates constrain additive applications to hexane-free extraction methods.
Cosmetics currently dominates volume; Spa & Wellness climbs the fastest on per-unit margin expansion.
Sales Channel:
Certificate-of-analysis documentation requirements are shortening payment cycles and favoring organized players with in-house laboratory capacity over artisanal producers.
- Distributors:Bulk procurement by European fragrance houses and domestic contract manufacturers flows through Maharashtra-based trading networks with established REACH compliance documentation. Traceability systems separate viable exporters from gray-channel operators.
- Online:Direct-to-consumer aromatherapy brands in Tier-2 Gujarat and Tamil Nadu cities leverage digital channels to bypass traditional retail markups, though CDSCO therapeutic claim scrutiny tightens label compliance costs.
- Direct Sales:Spa chains and hotel procurement teams source certified organic grades through backward integration into contract farming networks.
- Retail:Government emporium distribution anchors ayurvedic heritage positioning for heritage brands.
Distributors maintain volume leadership; Online gains share fastest on geographic expansion beyond Mumbai and Bangalore.
Application:
Extraction technology selection locks processors into incompatible purity tiers, with supercritical CO2 methods isolating high-value terpenes for specialty fragrance houses.
- Aromatherapy:Clinical-grade oils require gas chromatography-mass spectrometry validation that rural Uttarakhand distillation clusters cannot source locally. Bangalore specialty processors adopt modular supercritical CO2 systems to meet European buyer specifications.
- Fragrance:European fragrance houses reject steam-distilled alternatives in favor of vacuum-assisted extraction with automated temperature controls, concentrating viable supply among Maharashtra processors with capital equipment access.
- Flavoring:FSSAI solvent residue limits force hexane-free method validation for food additive eligibility.
- Household Cleaning:Synthetic petrochemical undercutting constrains natural oil penetration in mass-market detergent applications.
Fragrance leads on export value; Aromatherapy shows steepest expansion trajectory on wellness channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's essential oils production vastly outpaces neighboring Bangladesh and Sri Lanka in distillation capacity, yet both smaller markets show accelerating import demand for certified organic grades. Maharashtra and Karnataka together process over half of India's lavender and tea tree volumes. State-level AYUSH department licensing and FSSAI batch-testing mandates are compressing unorganized supply channels across all producing regions.
Maharashtra
Mumbai-based contract manufacturers drive bulk procurement of lavender and peppermint oils for European fragrance houses. The state AYUSH department enforces GMP certification for therapeutic-grade processors, raising entry barriers for rural distillers. Distillation clusters near Nashik and Pune are modernizing stainless-steel still capacity to meet REACH documentation requirements for export eligibility.
Karnataka
Tea tree oil demand from Bangalore's clean-label cosmetic manufacturers is accelerating contract farming networks in the Deccan plateau. State agricultural extension services subsidize organic certification costs under the national PLI scheme for herbal products. Specialty processors in the Bangalore-Tumkur corridor adopt modular supercritical CO2 systems to isolate high-value terpenes for aromatherapy channels.
Kashmir
Captive lavender fields in the Kashmir Valley command premium positioning in domestic spa and wellness channels. The Jammu & Kashmir State Medicinal Plants Board regulates wild harvesting permits for rare aromatic species. Srinagar-based distillers face climate-driven yield compression from erratic snowfall patterns, forcing price volatility in therapeutic-grade supply.
Tamil Nadu
Tier-2 cities including Coimbatore and Madurai show latent demand for clinical-grade oils as wellness chains expand beyond southern metros. The state Food Safety Department enforces FSSAI solvent residue limits that disqualify hexane-extracted volumes from food-grade applications. Artisanal producers in the Nilgiri foothills struggle with gas chromatography-mass spectrometry validation costs, ceding share to organized competitors.
Uttarakhand
Himalayan chamomile and cedarwood distillation clusters serve aromatherapy brands targeting North American wellness markets. The Uttarakhand State AYUSH Directorate mandates CDSCO-aligned labeling for therapeutic claims, tightening compliance costs for small-batch operators. Dehradun-based processors lack local chromatography expertise, forcing outsourcing of certificate-of-analysis documentation to Bangalore laboratories.
India Essential Oils Market Competitive Environment
Top-tier vendors anchor premium therapeutic and certified organic supply chains, while mid-scale processors compete on bulk peppermint and eucalyptus shipments to European buyers. The vendor base stratifies across three archetypes: heritage ayurvedic brands with government emporium distribution, export-oriented distillers with REACH-compliant documentation systems, and direct-to-consumer digital natives targeting Tier-2 wellness markets. Dominant competitive moves include backward integration into contract farming networks and segregation of food-grade versus cosmetic-grade production lines to isolate FSSAI compliance costs.
Within the heritage-brand tier, Khadi Natural exemplifies government emporium anchoring and ayurvedic heritage positioning. Veda Oils represents the captive-sourcing archetype through controlled lavender cultivation in Kashmir. DBR Exports India occupies the bulk-export vector, shipping standardized peppermint and eucalyptus volumes to European fragrance houses. These three patterns illustrate how geographic control, distribution channel selection, and certification investment separate viable competitors from gray-channel operators.
| Leading Market Players |
|---|
| Veda Oils |
| Khadi Natural |
| DBR Exports India |
| JK Aromatics & Perfumers |
| Gem Aromatics Limited |
| Moksha Lifestyle |
| Aroma Magic |
| IndiaAroma |
| Nature's Natural India |
| Others |
Value Chain & Pricing Dynamics
Captive lavender cultivation in Kashmir anchors premium positioning for Veda Oils while compressing procurement risk for aromatherapy-grade supply. This backward integration into contract farming networks simultaneously secures batch consistency for European fragrance houses and shields margin structures from Himachal Pradesh climate volatility.
Pricing Analysis
Capacity additions in Maharashtra and Karnataka are reshaping price floors for steam-distilled lavender and tea tree oils. Three-tier pricing structure across premium therapeutic, standard cosmetic, and economy solvent-extracted levels stratifies the market, with FSSAI food-grade certification commanding substantial premiums over gray-channel alternatives. Pricing pressure stems from synthetic petrochemical fragrance undercutting in mass-market soap applications. Contract manufacturers in Bangalore show least price sensitivity due to clean-label cosmetics pull-through, while unorganized rural distillers face acute margin compression from batch-testing compliance costs.
Supply Chain Analysis
Regional distribution centers in Mumbai and Bangalore operate hub-and-spoke patterns feeding European fragrance houses and domestic cosmetic manufacturers. Geographic supply concentrates in India, with secondary sourcing from Sri Lanka and Bangladesh for certified organic grades. Raw material dependencies rest on lavender floral tops, Mentha arvensis biomass, and eucalyptus leaf feedstock. Single-source vulnerability runs through Kashmir lavender fields exposed to erratic snowfall patterns. Distribution runs through Maharashtra-based trading networks with REACH documentation capabilities, marginalizing artisanal producers lacking certificate-of-analysis capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI's 2023 solvent residue notification compounds demand for hexane-free extraction infrastructure, creating regulatory-driven equipment upgrade cycles across Maharashtra and Karnataka processing clusters.
For Market Incumbents: Hedge against synthetic fragrance substitution by deepening backward integration into organic-certified contract farming networks in Karnataka. Lock in multi-year offtake agreements with Bangalore clean-label cosmetic manufacturers before PLI scheme subsidies attract new distillation capacity. Prioritize segregating food-grade and cosmetic-grade production lines to isolate FSSAI compliance cost exposure. For New Entrants and Emerging Players: Supercritical CO2 extraction modules offer a technology-first wedge into Bangalore-Tumkur specialty fragrance channels where European buyers reject steam-distilled alternatives. Target underpenetrated Tier-2 wellness markets in Coimbatore and Madurai with direct-to-consumer digital positioning. Lead with USDA Organic certification to bypass established distributor gatekeeping in Mumbai bulk procurement channels. For Investors and Strategic Acquirers: Roll-up economics work for distressed stainless-steel still operators in Uttarakhand because CDSCO labeling mandates and chromatography outsourcing costs have compressed small-batch margins below viable thresholds. Five-to-ten-year viability hinges on consolidation into platforms with in-house gas chromatography-mass spectrometry capacity. Watch FSSAI enforcement intensity in Tamil Nadu as the inflection signal for formalization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Captive lavender fields in Kashmir secure premium aromatherapy positioning against climate-driven supply volatility. |
| Supercritical CO2 Extraction Adoption | Modular systems in Bangalore isolate high-value terpene fractions for European fragrance house specifications. |
| Production Line Segregation | Separating food-grade and cosmetic-grade distillation isolates FSSAI hexane-free compliance costs. |
| USDA Organic Certification Investment | Opens North American wellness chain eligibility for Kerala spa and ayurvedic retreat operators. |
| In-House Chromatography Capacity Buildout | Gas chromatography-mass spectrometry expertise shortens certificate-of-analysis turnaround for export shipments. |
Study Parameters
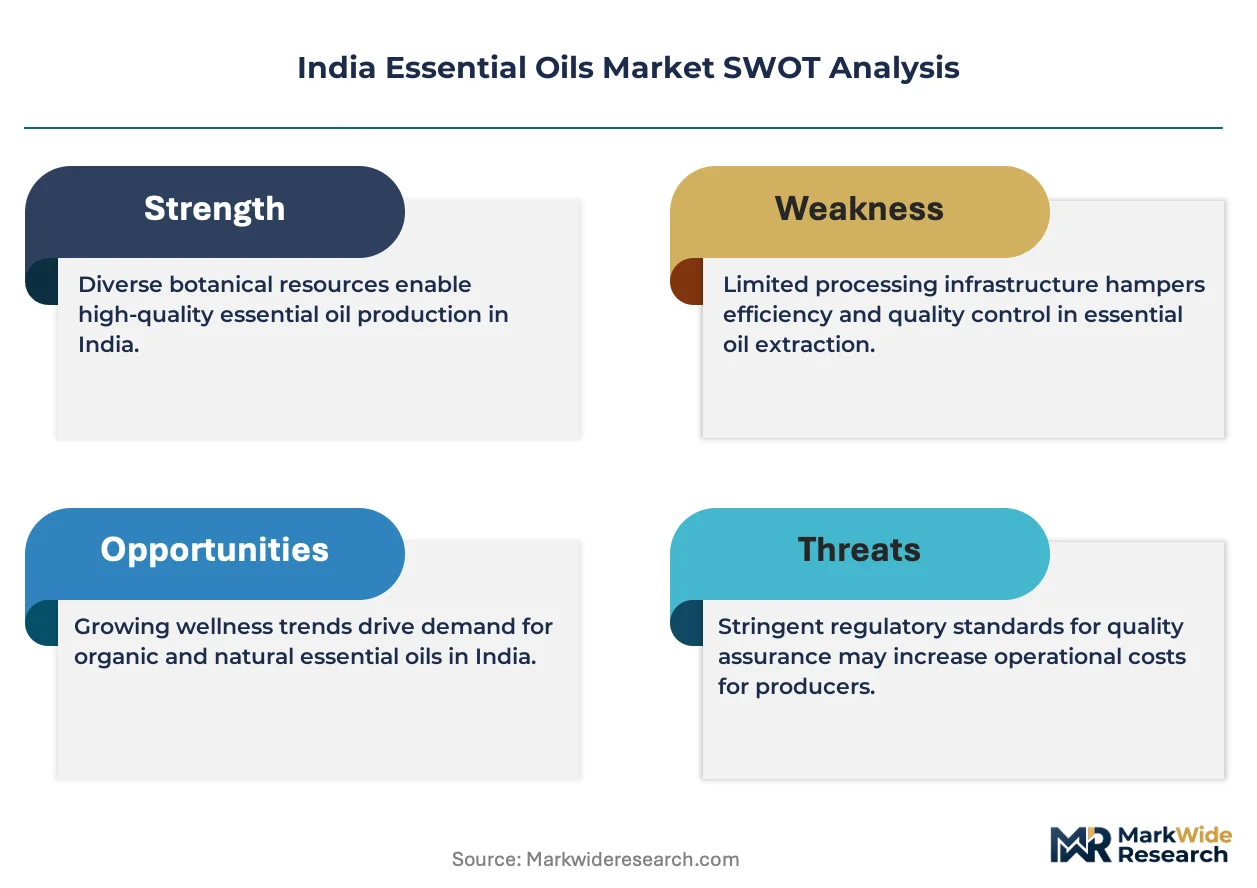
Coverage spans Maharashtra, Karnataka, Kashmir, Tamil Nadu, and Uttarakhand, with primary inputs from each region's distillation clusters. The approach combines primary interviews with plant managers at licensed processors, procurement leads at Bangalore contract manufacturers, AYUSH department licensing officers, and European fragrance house technical buyers with secondary validation. Secondary sources include FSSAI batch-testing notifications, CDSCO therapeutic claim guidelines, BIS purity standards, customs export records, and state-level PLI scheme disbursement data. Bottom-up volume triangulation against top-down value estimates validates segment splits.
Granularity-level modeling tracks extraction method, purity grade, certification tier, end-use application, and sales channel dimensions throughout the forecast period. CAGRs derive from regression analysis against PLI scheme subsidy trajectories and clean-label cosmetics penetration curves. Industry-specific forecast inputs incorporate lavender yield volatility indices for Kashmir and Himachal Pradesh cultivation belts, plus European REACH documentation adoption rates among Maharashtra exporters.
The model holds under sustained FSSAI enforcement intensity and PLI scheme continuity; deviation in CDSCO therapeutic claim scrutiny severity or Kashmir climate patterns would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Europe Deodorants Market
Flavor and Fragrance Chemicals
Carnosic Acid Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Anisic Aldehyde Market
Flavor and Fragrance Chemicals
Estragole Market
Flavor and Fragrance Chemicals
Natural Fragrance Chemicals Market
Flavor and Fragrance Chemicals
Limonene Market
Flavor and Fragrance Chemicals
North America Aroma Chemicals Market
Flavor and Fragrance Chemicals
Nonanal Market
Flavor and Fragrance Chemicals
Asia-Pacific Aroma Chemicals Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
Spearmint Oil Market
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
Essential Oils Market
Flavor and Fragrance Chemicals
Scent Eliminators Market
Flavor and Fragrance Chemicals
Flavors for Pharmaceutical and Healthcare Applications Market