
 Limonene Market | 2026-2036
Limonene Market Size, Share, and Industry Trends Forecast 2026-2036
Limonene Market Outlook
Asset-light toll processing and third-party extraction leasing is narrowing the capital barrier for mid-scale entrants in limonene recovery. Florida Chemical Company leverages its integrated citrus processing infrastructure across Florida to dominate North American feedstock access. Symrise AG sustains European fragrance house demand through specialized cosmetic-grade distillation capabilities. BASF SE anchors industrial-grade supply chains with backward integration into agro-industrial waste sourcing networks.
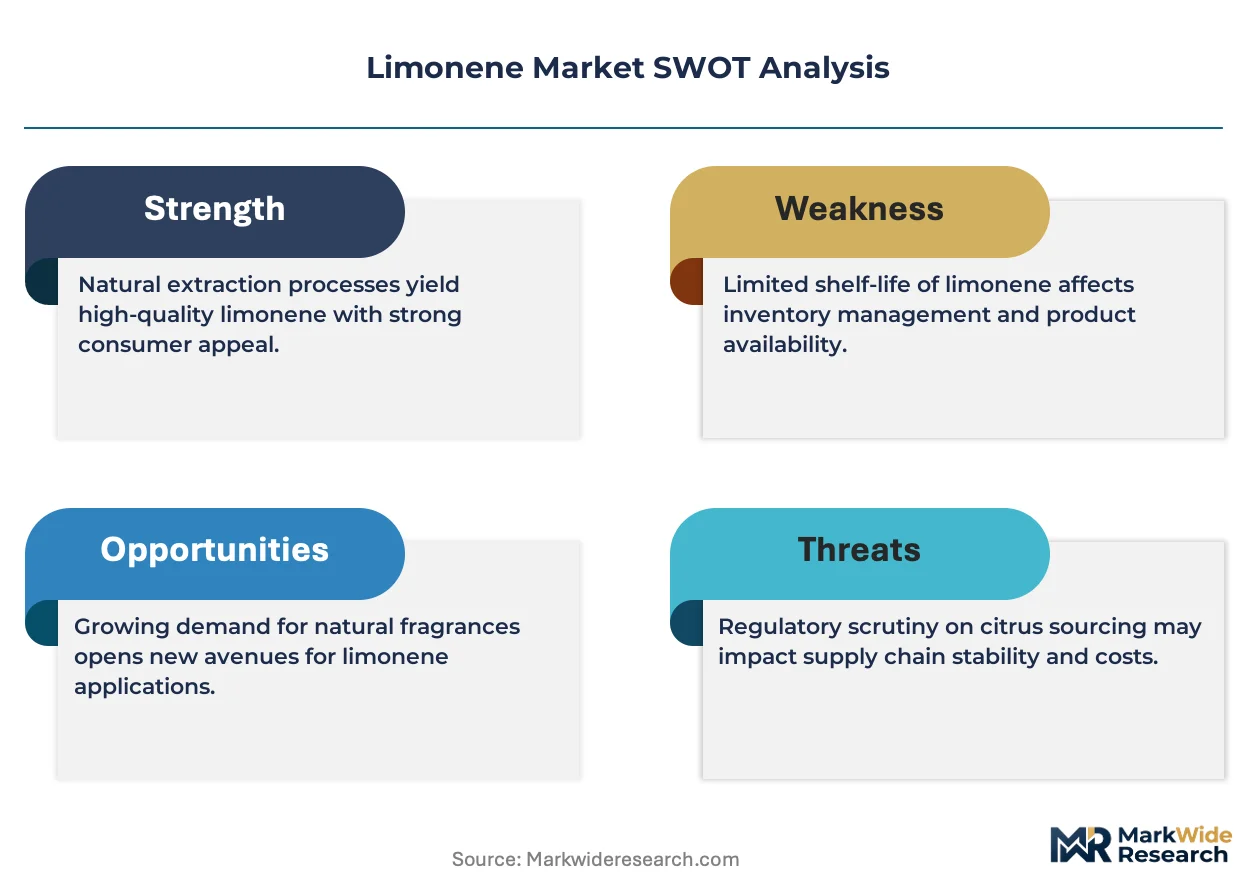
Limonene is a cyclic monoterpene hydrocarbon with the molecular formula C₁₀H₁₆, typically comprising over 90% of citrus peel oil by volume and characterized by a boiling point near 176°C. Manufacturers recover it through cold-pressing or steam distillation of citrus peels for use as a biodegradable solvent, flavoring agent, and fragrance precursor across industrial and consumer formulations. Food Grade limonene commands the largest volume share as beverage and confectionery manufacturers replace synthetic flavor carriers, while Pharmaceutical Grade extraction is expanding fastest due to API solubilization demand. Citrus Peels remain the dominant source category, though Agro-Industrial Waste recovery is gaining traction as processors target lower-cost feedstock arbitrage.
EPA registration requirements for antimicrobial claims and FDA food additive safety standards govern US market access, while REACH registration and EU F-Gas Regulation substitution mandates shape European formulation shifts. These frameworks compel manufacturers to maintain dual certification portfolios and traceable supply chain documentation. Stakeholders must monitor evolving biobased content thresholds in procurement specifications as downstream buyers harden sustainability criteria without regulatory mandate.
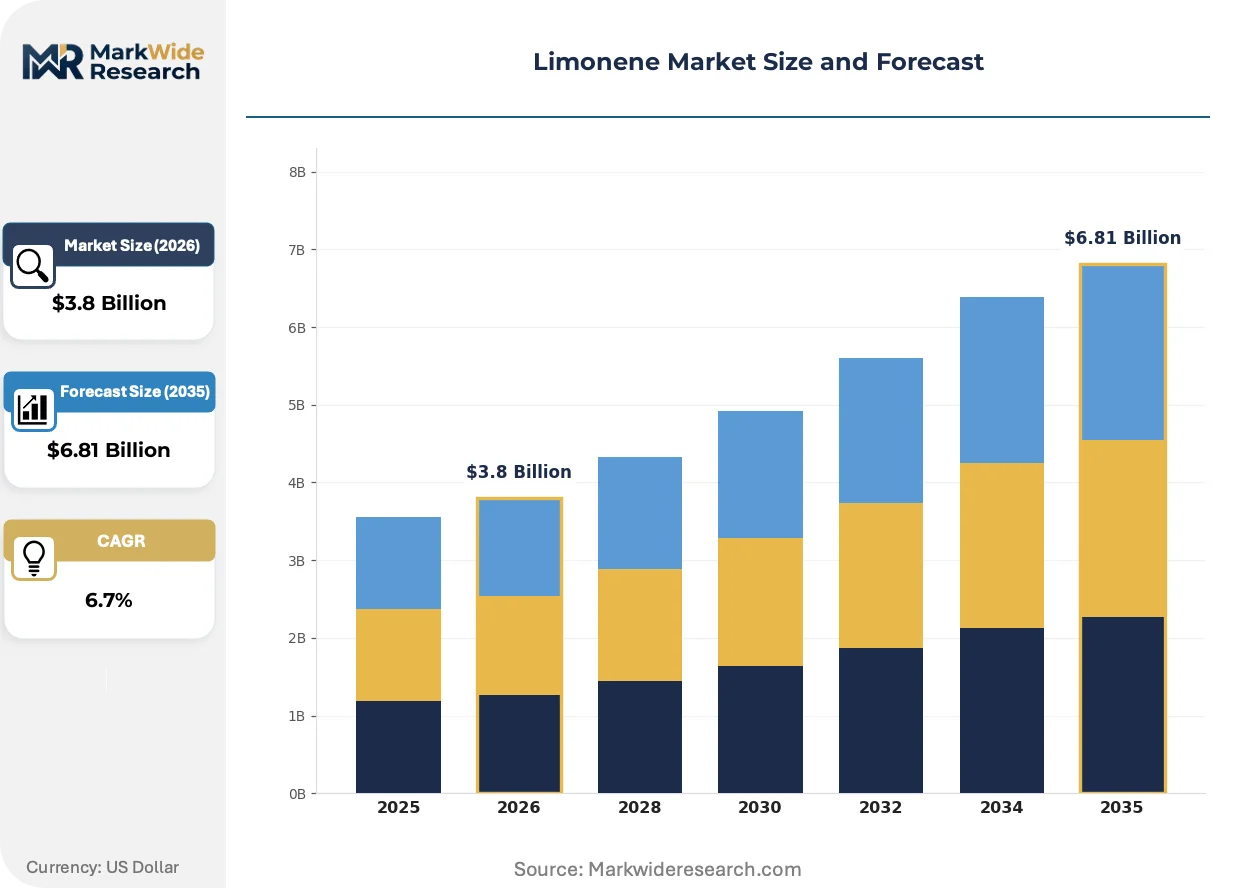
Market Dynamics
The limonene market is being fundamentally restructured by the EU F-Gas Regulation's forced phase-out of synthetic solvents in industrial cleaning and degreasing applications, which has triggered a cascading substitution effect across European manufacturing supply chains.
Growth Catalysts
- EU Green Deal biobased procurement mandates:Public sector purchasing rules now require minimum renewable content thresholds in cleaning and maintenance products, directly expanding limonene offtake for municipal and institutional buyers.
- Pharmaceutical API solubilization:Drug manufacturers are reformulating poorly water-soluble active ingredients using food-grade limonene as a natural co-solvent, bypassing synthetic alternatives facing stricter toxicological scrutiny.
- Brazil-Florida sourcing corridor maturation:Dedicated citrus peel collection infrastructure and toll processing networks have reduced feedstock logistics costs for mid-scale processors entering the market.
Market Restraints
- Feedstock concentration risk:Over 70% of citrus peel supply originates from Brazil and Florida, exposing processors to climate-driven harvest volatility and single-origin disruption.
- REACH registration cost barriers:Full substance registration under EU chemicals law requires six-figure toxicology dossier investments that exclude sub-scale producers from European industrial-grade markets.
- Petroleum-derived terpene price competition:Synthetic pinene and turpentine alternatives maintain cost advantages in price-sensitive industrial solvent applications where biobased certification carries no premium.
Strategic Opportunities
- Agro-industrial waste valorization:Grapefruit, mandarin, and lemon processing residues outside traditional orange peel streams offer untapped feedstock pools in Spain, Italy, and Mexico.
- Cosmetic waterless formulation surge:Solid shampoo and anhydrous skincare brands are adopting limonene as both fragrance carrier and preservation-enhancing solvent, opening premium pricing tiers.
- Carbon border adjustment positioning:EU CBAM implementation is creating first-mover advantages for suppliers with verified lifecycle carbon data against fossil-derived solvent imports.
Industry Challenges
- Dual certification complexity:Manufacturers serving both food and industrial segments must maintain parallel FDA food additive and EPA antimicrobial registration portfolios with incompatible documentation systems.
- Specialized distillation talent scarcity:Cosmetic-grade limonene production requires operators skilled in fractional separation techniques that differ materially from standard essential oil processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Limonene Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Food Additive, Cleaning Products, Fragrances, Pharmaceuticals Source: Citrus Peels, Mint Oil, Agro-Industrial Waste, Others End User: Food & Beverage, Personal Care, Chemical, Pharmaceutical |
| Companies Covered | Florida Chemical Company, Symrise AG, BASF SE, Citrosuco, International Flavors & Fragrances Inc. (IFF), Lemonconcentrate S.L.U., Arora Aromatics Pvt. Ltd., Citrus Oleo, Sucorrico S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Limonene Market Strategic Shifts
Supercritical CO2 extraction technology is compressing the capital recovery timeline for limonene processors while simultaneously enabling pharmaceutical-grade purity specifications that steam distillation cannot achieve. This technological inflection is redrawing competitive boundaries between commodity and specialty suppliers.
Molecular distillation systems capable of separating optical isomers with 99.5%+ enantiomeric purity are rendering obsolete conventional batch stills that produced racemic mixtures unsuitable for chiral pharmaceutical applications. European fragrance houses are retrofitting existing facilities to capture this capability, while Asian processors are leapfrogging directly to modular continuous-flow designs that halve energy intensity.
REACH registration deadlines for existing substances are forcing reformulation decisions across EU industrial cleaning product manufacturers. The 2026 cutoff for full dossier submission has compressed supplier qualification timelines, advantaging processors with pre-registered tonnage bands and documented supply chain traceability. Food-grade limonene suppliers with dual industrial registrations are capturing volume from competitors lacking this regulatory coverage.
Direct contracting between citrus processors and end-use manufacturers is displacing traditional essential oil trader intermediaries in fragrance and flavor procurement. Major personal care brands are establishing multi-year offtake agreements with Florida and São Paulo extraction facilities, securing volume commitments that lock in capacity before harvest season volatility materializes. This pattern is most pronounced in North American and European markets where sustainability audit requirements favor documented single-source relationships.
Limonene Market Segmentation
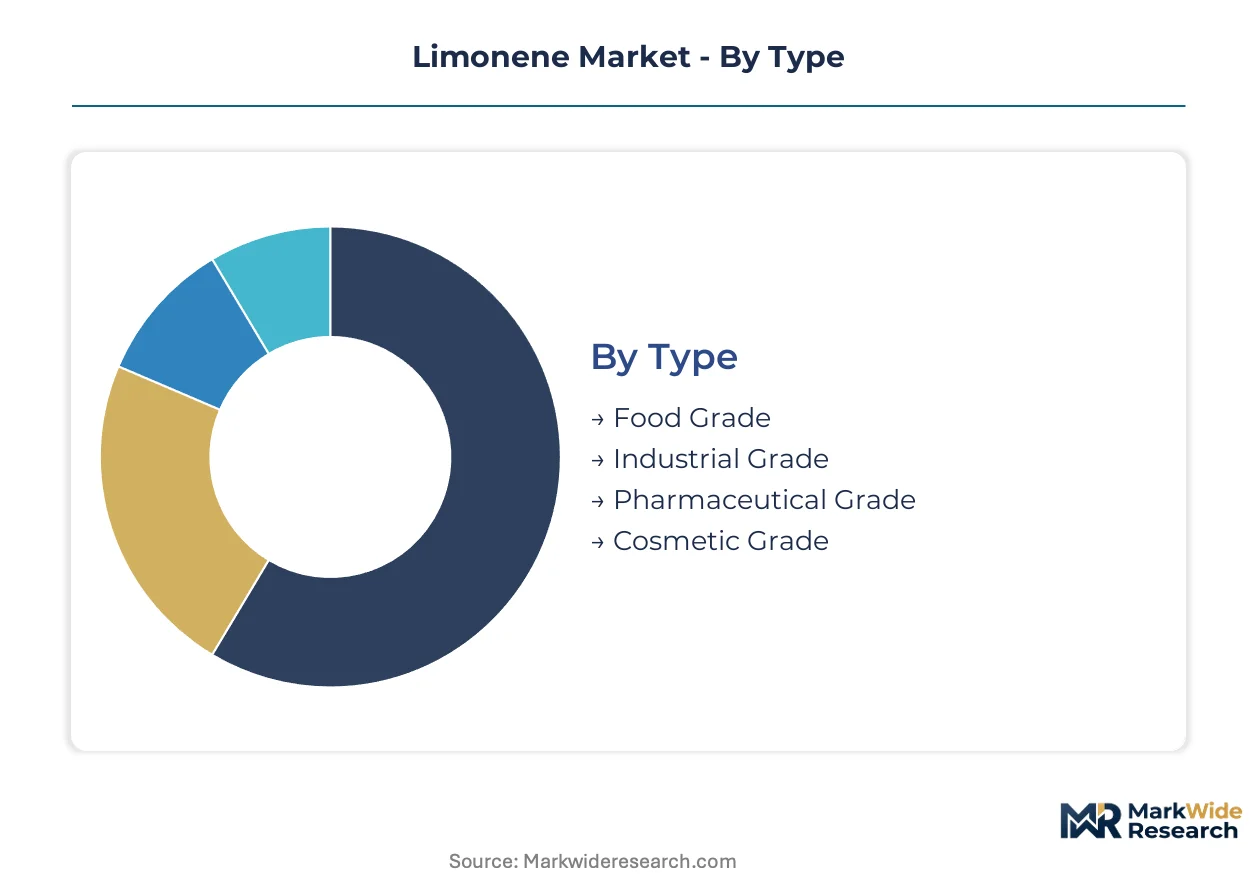
Limonene segmentation reflects divergent purity standards and regulatory pathways that shape manufacturing investment and margin capture. Each grade tier demands distinct distillation infrastructure and certification portfolios, while application mix determines geographic demand concentration and pricing power.
Type:
Cost tier differentiation separates commodity solvent supply from premium pharmaceutical and cosmetic streams requiring specialized fractionation.
- Food Grade:Comprises over 90% citrus peel oil by volume with terpene hydrocarbon purity suitable for FDA food additive standards. Beverage and confectionery manufacturers in the US and EU drive volume offtake as synthetic flavor carriers face substitution pressure.
- Industrial Grade:Lower purity specifications tolerate higher residual aldehyde content for degreasing and adhesive applications. EU F-Gas Regulation mandates are accelerating displacement of petroleum-derived solvents in German and French industrial cleaning supply chains.
- Pharmaceutical Grade:API solubilization applications demand chiral purity and documented supply chain traceability for CDSCO and FDA drug master file submissions.
- Cosmetic Grade:Fragrance house specifications require fractional separation techniques that preserve olfactory profile integrity for European personal care formulations.
Food Grade holds installed capacity. Pharmaceutical Grade is rotating up the share rankings.
Application:
End-use concentration varies by regulatory intensity and sustainability certification requirements across consumer and industrial markets.
- Food Additive:Citrus-derived flavor carriers replace synthetic alternatives in beverage carbonation and confectionery coating applications. REACH-compliant European processors capture premium positioning against turpentine-based competitors.
- Cleaning Products:Biobased solvent demand from EU Green Deal procurement rules expands municipal and institutional offtake for surface degreasing formulations.
- Fragrances:Personal care brands in France and Germany establish direct extraction facility contracts to satisfy sustainability audit requirements.
- Pharmaceuticals:Poorly water-soluble API reformulation using limonene co-solvents bypasses toxicological scrutiny facing synthetic alternatives.
Cleaning Products application is gaining share fastest in Europe. Food Additive maintains volume leadership.
Source:
Feedstock geography determines logistics cost structure and climate exposure for processor margin stability.
- Citrus Peels:Orange peel cold-pressing and steam distillation dominate recovery economics. Brazil and Florida collection infrastructure anchors global supply concentration.
- Mint Oil:Alternative terpene profile from Mentha species offers regional supply diversification for Indian and Chinese processors.
- Agro-Industrial Waste:Grapefruit, mandarin, and lemon processing residues in Spain, Italy, and Mexico enable lower-cost feedstock arbitrage outside traditional orange peel streams.
- Others:Emerging microbial fermentation and synthetic biology pathways remain pre-commercial for cost-competitive terpene production.
Citrus Peels holds installed capacity. Agro-Industrial Waste is rotating up the share rankings.
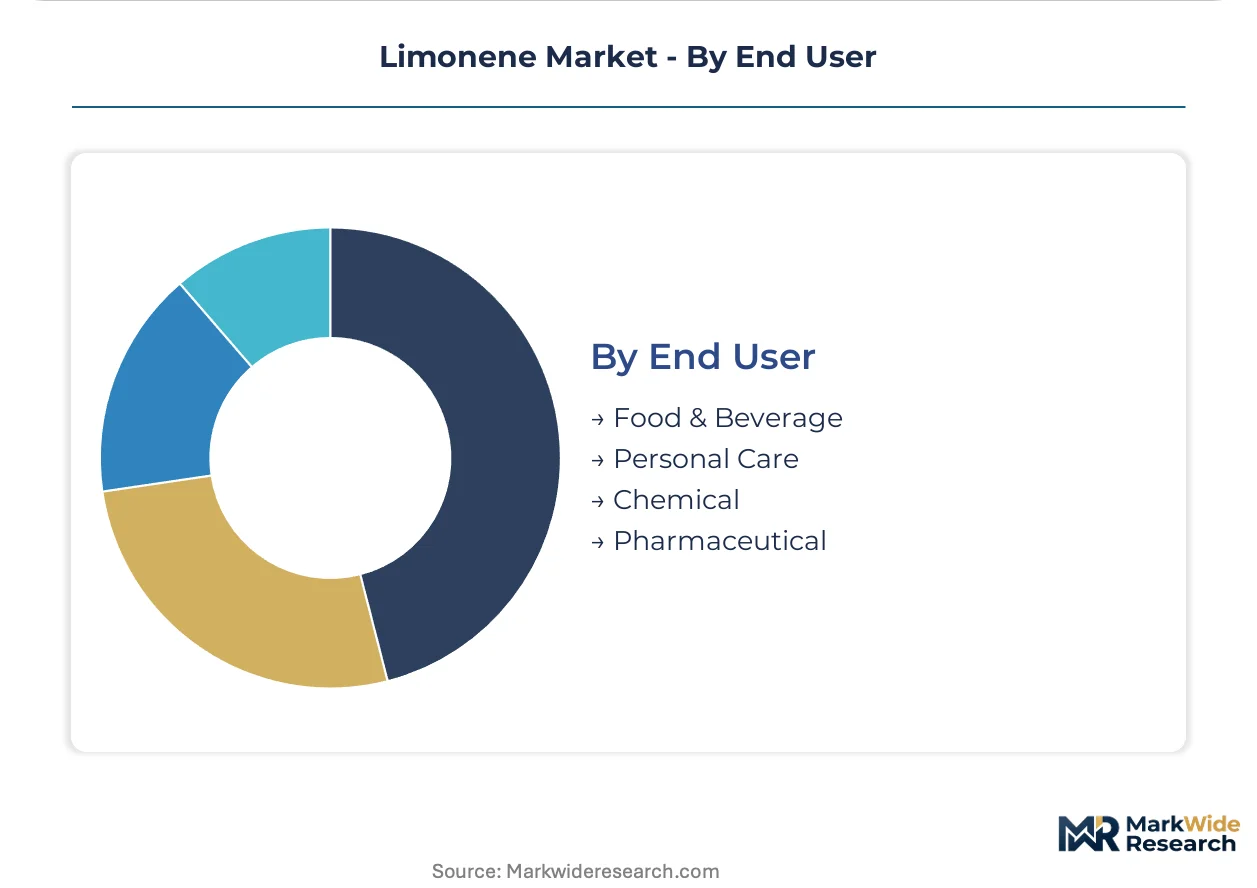
End User:
Customer type dictates certification burden and contract structure, from spot commodity purchasing to multi-year offtake agreements with traceability requirements.
- Food & Beverage:Volume purchasers prioritize FDA food additive compliance and batch consistency for flavor carrier applications across carbonated and packaged goods segments.
- Personal Care:Waterless formulation trends in solid shampoo and anhydrous skincare create premium solvent demand for fragrance carriers with preservation-enhancing properties.
- Chemical:Industrial solvent buyers in EU member states face mandatory biobased content thresholds under public procurement directives.
- Pharmaceutical:Drug manufacturers require dual FDA-CDSCO registration portfolios and documented supply chain traceability for API solubilization applications.
Food & Beverage holds installed capacity. Personal Care is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Limonene trade flows reflect concentrated citrus processing capacity in Brazil and Florida against fragmented demand centers in Europe and Asia. Import-dependent manufacturers in Germany and Japan face elevated logistics exposure to Atlantic hurricane seasons and Brazilian drought cycles. Currency volatility between the Brazilian real and US dollar directly compresses processor margins in São Paulo export corridors.
United States
Florida's integrated citrus processing infrastructure anchors North American feedstock access for cold-pressed and steam-distilled recovery. EPA registration requirements for antimicrobial claims and FDA food additive standards govern dual-grade manufacturing investments. The Lake Wales-Sebring corridor concentrates toll processing facilities serving personal care brands with direct multi-year offtake agreements.
Brazil
São Paulo state generates the dominant share of global orange peel supply through Citrosuco's vertically integrated collection networks. ANVISA pharmaceutical-grade certification and REACH pre-registration portfolios enable European industrial solvent exports. The Araraquara processing cluster houses specialized distillation capacity for fragrance house specifications.
Germany
EU F-Gas Regulation mandates accelerate petroleum solvent substitution in industrial cleaning formulations across Baden-Württemberg manufacturing zones. ECHA REACH registration requirements exclude sub-scale producers from industrial-grade markets. The Ludwigshafen chemical corridor anchors backward integration into agro-industrial waste sourcing networks for cost-competitive supply.
France
Grasse-based fragrance houses drive cosmetic-grade limonene demand through specialized fractional separation requirements for olfactory profile integrity. EU Green Deal biobased procurement thresholds expand municipal cleaning product offtake in Paris and Lyon metropolitan areas. Provençal essential oil distillers are retrofitting molecular separation systems for enantiomeric purity specifications.
India
Maharashtra and Gujarat processors extract limonene from mint oil alternative feedstocks to diversify beyond citrus peel dependence. CDSCO drug master file submissions and FSSAI food safety standards govern pharmaceutical and food-grade dual certification investments. The Mumbai-Pune industrial corridor concentrates API solubilization application development for poorly water-soluble drug reformulation.
Limonene Market Competitive Environment
On the supply side, the industry is bifurcated between integrated citrus processors with captive feedstock access and specialized distillers serving premium fragrance and pharmaceutical grades. Florida and São Paulo infrastructure holders dominate commodity volume, while European fractional separation specialists capture margin in cosmetic and chiral applications. Three archetypes define competitive positioning: integrated agricultural processors, specialty distillation houses, and toll manufacturing operators. Capacity expansion through supercritical CO2 retrofitting and strategic partnerships for REACH registration coverage represent the dominant competitive moves.
Within the integrated processor tier, Florida Chemical Company exemplifies supply-side concentration through citrus infrastructure control, while Citrosuco anchors Brazilian export capacity. Symrise AG occupies a position among European specialty distillation houses serving fragrance specifications. These three represent distinct archetypes—geographic feedstock dominance, vertical agricultural integration, and technical grade specialization—rather than direct substitutes in procurement decisions.
| Leading Market Players |
|---|
| Florida Chemical Company |
| Symrise AG |
| BASF SE |
| Citrosuco |
| International Flavors & Fragrances Inc. (IFF) |
| Lemonconcentrate S.L.U. |
| Arora Aromatics Pvt. Ltd. |
| Citrus Oleo |
| Sucorrico S.A. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European cosmetic-grade fractional distillation is compressing lead times for fragrance house orders while simultaneously elevating pricing power for processors with certified enantiomeric separation capabilities. This utilization asymmetry between commodity solvent supply and specialty grade scarcity shapes how Brazilian and Florida processors allocate peel oil volumes across buyer tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for commodity solvent grades, while fragrance houses and pharmaceutical formulators accept premium-mid-economy pricing differentiation driven by chiral purity certification and documented supply chain traceability. Cost compression in industrial-grade supply is intensifying because synthetic pinene alternatives maintain cost advantages in price-sensitive degreasing applications where biobased certification carries no procurement premium. Food and beverage manufacturers exhibit the highest price sensitivity due to commoditized flavor carrier substitution options, whereas personal care brands with waterless formulation commitments demonstrate the lowest sensitivity as they prioritize olfactory profile integrity over unit cost.
Supply Chain Analysis
Tariff exposure between Brazil and the European Union dominates supply chain risk calculus for São Paulo processors exporting REACH-registered tonnage bands. Feedstock concentration in Brazil and Florida creates single-source vulnerability for Atlantic hurricane seasons and Brazilian drought cycles, while agro-industrial waste recovery in Spain, Italy, and Mexico draws from grapefruit, mandarin, and lemon processing residues to diversify sourcing. Distribution runs through direct multi-year offtake agreements between citrus processors and end-use manufacturers, displacing traditional essential oil trader intermediaries in fragrance and flavor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Toll processing and third-party extraction leasing represent a service-attach opportunity expanding faster than captive distillation capacity buildout, as mid-scale entrants seek asset-light entry without six-figure REACH registration investments.
For Market Incumbents: Build regulatory moats through dual FDA-EPA certification portfolios that exclude sub-scale competitors from food-industrial crossover supply. Deepen backward integration into agro-industrial waste sourcing networks in Spain and Italy to arbitrage lower-cost feedstock outside traditional orange peel streams. Defend against supercritical CO2 technology leapfrogging by retrofitting existing steam distillation facilities for pharmaceutical-grade purity specifications. For New Entrants and Emerging Players: Agro-industrial waste valorization in Mexico and Mediterranean citrus processing regions represents the most penetrable entry point for feedstock cost arbitrage outside Brazil-Florida concentration. Cosmetic waterless formulation supply to solid shampoo and anhydrous skincare brands offers premium pricing tiers with lower certification burden than pharmaceutical applications. Pursue toll manufacturing partnerships with established REACH-registered processors to bypass six-figure toxicology dossier barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across supercritical CO2 extraction retrofitting as modular continuous-flow designs halve energy intensity compared to conventional batch stills. Target acquisition candidates with pre-registered REACH tonnage bands and documented supply chain traceability systems already deployed. Watch for EU F-Gas Regulation enforcement intensity as the signal indicating accelerated petroleum solvent substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Retrofitting | Compresses capital recovery timelines while enabling pharmaceutical-grade purity specifications unattainable through steam distillation. |
| REACH Pre-Registration Coverage | Locks in European industrial-grade market access before dossier submission deadlines exclude sub-scale competitors. |
| Agro-Industrial Waste Sourcing | Opens lower-cost feedstock arbitrage in Spain, Italy, and Mexico outside Brazil-Florida concentration risk. |
| Direct Offtake Agreement Structuring | Satisfies sustainability audit requirements for personal care brands while locking in volume before harvest volatility. |
| Molecular Distillation Capability Addition | Captures premium cosmetic and chiral pharmaceutical margins through 99.5%+ enantiomeric purity separation. |
Study Parameters
Desk research of customs and trade flow databases, ECHA REACH registration filings, and citrus industry association statistics preceded structured interviews with extraction facility plant managers, procurement leads at fragrance houses, downstream chemical OEM solvent buyers, and regulatory affairs specialists at pharmaceutical formulators. Primary intelligence gathered through these stakeholder engagements was cross-validated against secondary sources including ANVISA certification records, FDA food additive petitions, and SEC filings from publicly traded flavor and fragrance houses. Bottom-up capacity modeling across Brazil and Florida processing clusters was triangulated against top-down demand estimates derived from EU F-Gas Regulation substitution mandates and personal care formulation trend analysis.
Forecast assumptions held regulatory enforcement intensity and biobased procurement threshold trajectories fixed across the projection horizon while varying citrus harvest yield scenarios and currency volatility between the Brazilian real and US dollar. Segmentation dimensions modeled include grade tier, end-use application, feedstock source category, and regional production hub. CAGRs were derived from installed capacity utilization rates, announced facility expansions, and documented offtake agreement volumes. Key inputs incorporated EU Green Deal public sector purchasing data and pharmaceutical API solubilization formulation trends.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Atlantic hurricane frequency, or EU carbon border adjustment implementation timelines would shift the trajectory. Forecasts reflect these documented assumptions and should be validated against operating reality as regulatory enforcement patterns and harvest outcomes materialize. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Immortelle Oil Market
Flavor and Fragrance Chemicals
Estragole Market
Flavor and Fragrance Chemicals
Global Terpene Market
Flavor and Fragrance Chemicals
Europe Essential Oils Market
Flavor and Fragrance Chemicals
Citronellol Market
Flavor and Fragrance Chemicals
Cedrol Methyl Ether Market
Flavor and Fragrance Chemicals
Europe Aroma Chemicals Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Camphor Market
Flavor and Fragrance Chemicals
Middle East and Africa Aroma Chemicals Market
Flavor and Fragrance Chemicals
Perillaldehyde Market
Flavor and Fragrance Chemicals
Flavor and Fragrance Market
Flavor and Fragrance Chemicals
Flavors for Pharmaceutical and Healthcare Applications Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
India Essential Oils Market