
 North America Aroma Chemicals Market | 2026-2036
North America Aroma Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aroma Chemicals Market Outlook
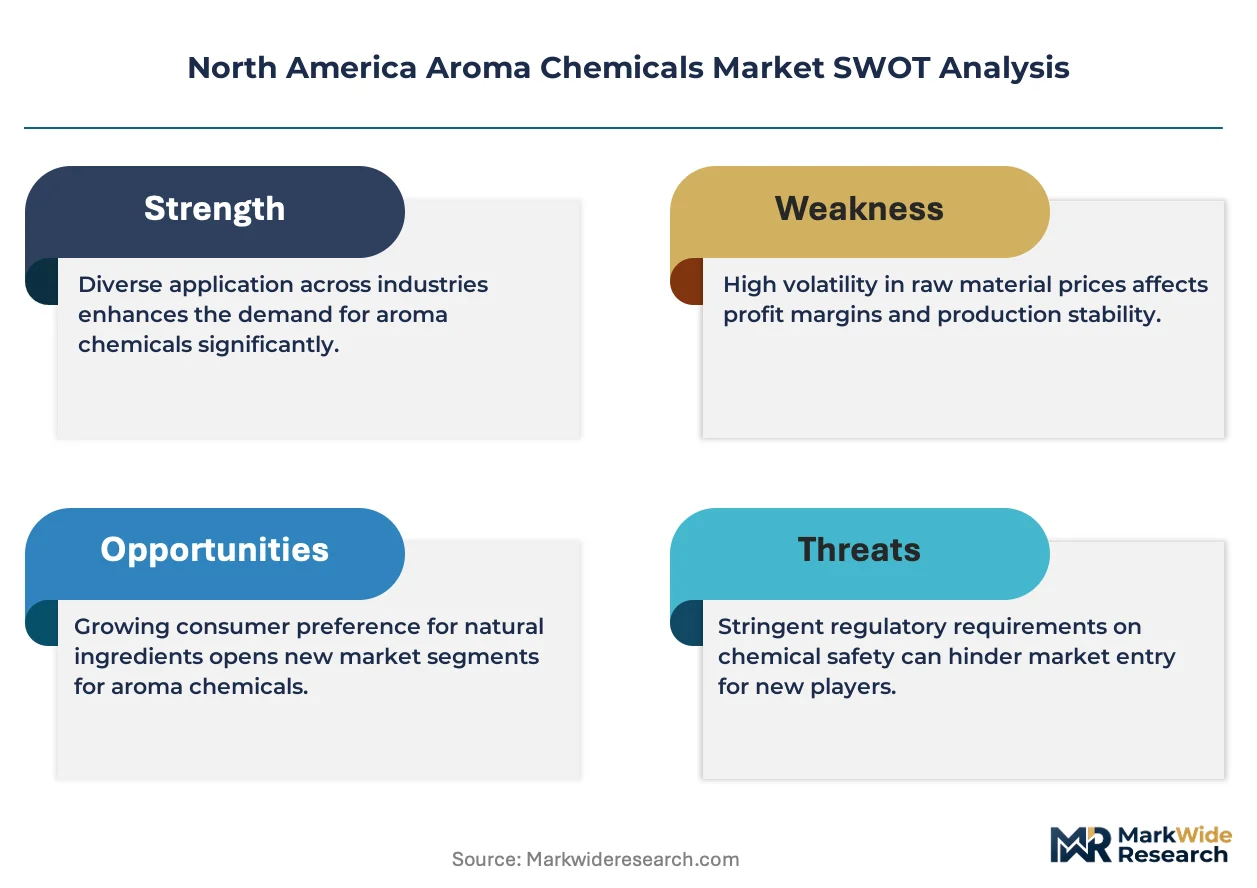
The EPA Safer Choice standard is recalibrating how formulators select aroma molecules across personal care and household applications. Givaudan leverages captive biotechnology capacity to supply fermentation-derived ingredients that meet tightened volatile organic compound thresholds. International Flavors & Fragrances Inc. anchors North American production through integrated manufacturing sites in New Jersey and Kentucky. Symrise AG differentiates its portfolio with region-specific regulatory compliance documentation that accelerates customer approval cycles.
Aroma chemicals are synthetic or naturally derived organic compounds characterized by specific odor thresholds measured in parts per billion, manufactured through fractional distillation, chemical synthesis, or biotechnological conversion of terpenoid precursors to deliver consistent scent profiles across batch production. These compounds serve as the functional backbone in formulated fragrances, flavored food systems, and scented consumer products where olfactory performance must meet precise stability and safety specifications. Esters dominate volume demand in flavor applications due to their fruit-character profiles and broad regulatory acceptance in food contact uses. Terpenes represent the fastest-expanding structural class as biotechnology routes reduce reliance on citrus crop volatility and tropical supply disruptions. The fragrance application segment commands the deepest margin pool, particularly in prestige and niche perfumery where proprietary captive molecules command formulation exclusivity.
The EPA oversees volatile organic compound emissions under the Clean Air Act, while the FDA governs flavor ingredient safety through the FEMA GRAS program and the Food Additives Amendment, collectively constraining which molecules enter food and environmental exposure pathways. California's Department of Toxic Substances Control administers the Safer Consumer Products regulations, creating a state-level compliance overlay that national suppliers must address for market access. OSHA workplace exposure limits for aromatic solvents further shape manufacturing site selection and automation investment across the region. Stakeholders must monitor how biomanufacturing scale-up intersects with evolving GRAS self-determination protocols and state-level chemical disclosure requirements to anticipate which production technologies will secure preferred supplier status.
Market Dynamics
Biomanufacturing scale-up is compressing traditional petrochemical routes as fermentation-derived terpenes achieve cost parity with citrus-extracted feedstocks, forcing incumbent suppliers to reconfigure captive production assets or cede share in high-margin fragrance molecules.
Growth Catalysts
- EPA Safer Choice penetration:Household product formulators across the United States are reformulating to meet volatile organic compound thresholds, expanding addressable demand for biosynthesized alternatives that bypass petroleum-derived precursors.
- Flavor house consolidation:Mega-mergers among packaged food manufacturers in the Northeast corridor are concentrating procurement volumes, rewarding aroma chemical suppliers with integrated regulatory documentation and faster customer approval cycles.
- Precision fermentation maturation:California-based biotechnology infrastructure is converting terpenoid precursors at commercial scale, reducing batch-to-batch variability that historically plagued natural extraction.
Market Restraints
- Citrus crop volatility:Florida and Brazil orange harvest fluctuations transmit directly to limonene and citral pricing, compressing margins for suppliers without captive biotechnology hedges.
- California DTSC overlay:Safer Consumer Products regulations impose state-level chemical disclosure requirements that national suppliers must address for market access, fragmenting compliance costs across multi-state distribution networks.
- GRAS self-determination friction:FDA's evolving interpretation of food additive safety documentation is lengthening approval timelines for novel natural-identical molecules, delaying revenue recognition.
Strategic Opportunities
- Underpenetrated Mexico channel:Flavor and fragrance R&D clusters in Mexico City and Monterrey remain underserved by integrated suppliers, creating first-mover advantages for documentation-ready entrants.
- Clean-label pet nutrition:Premium pet food manufacturers in the Pacific Northwest are adopting human-grade aroma standards, opening a margin-rich application vertical with less price sensitivity than mass-market food.
- Canada PMRA harmonization:Health Canada's pesticide and chemical regulatory alignment with EPA frameworks is reducing dual-registration burdens for cross-border suppliers.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiology and downstream processing expertise concentrates in Boston and San Francisco biotech clusters, forcing aroma suppliers to compete with pharmaceutical wages for skilled operators.
- Legacy equipment retrofit costs:Petrochemical-derived production lines require capital-intensive reconfiguration to handle aqueous fermentation broths, straining mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aroma Chemicals Market |
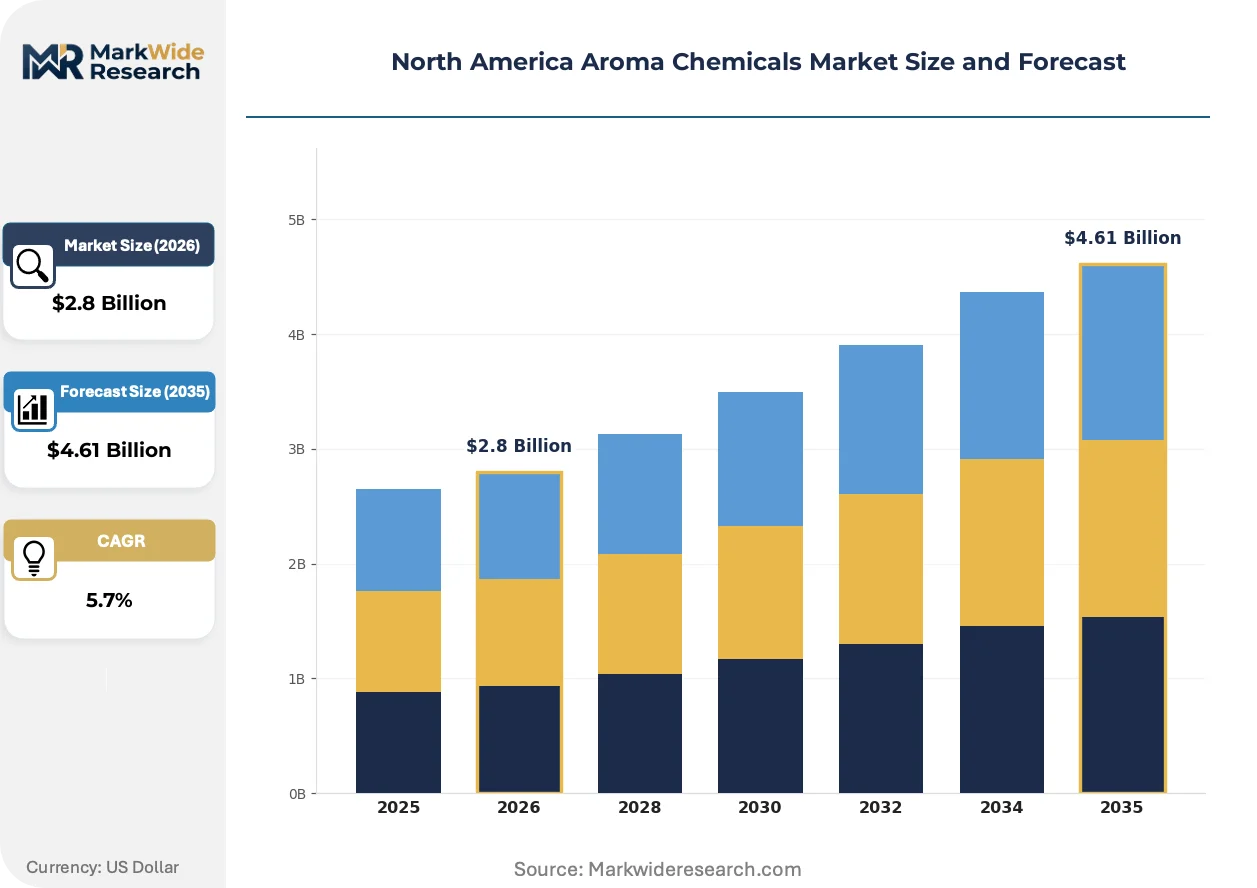
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Esters, Aldehydes, Terpenes, Phenols Application: Fragrances, Flavors, Personal Care, Household Products End User: Food & Beverage, Cosmetics, Household, Pharmaceuticals Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, International Flavors & Fragrances Inc., Symrise AG, Givaudan, Firmenich SA, DSM-firmenich, Takasago International Corporation, Solvay, Bell Flavors & Fragrances, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aroma Chemicals Market Strategic Shifts
Digital process control and biosynthetic pathway engineering are converging to collapse development cycles for novel aroma molecules, compressing the traditional five-year timeline from lab bench to commercial scale.
Continuous chromatography paired with real-time metabolite monitoring is automating quality assurance in fermentation facilities, enabling fragrance houses to certify batch consistency without destructive sampling. Fine fragrance compounders in New York and Los Angeles are adopting these systems fastest, compressing supplier qualification timelines from eighteen months to under six.
California's Department of Toxic Substances Control is expanding Safer Consumer Products candidate chemical lists faster than federal EPA timelines, forcing national suppliers to maintain dual formulation databases. Personal care applications face the steepest compliance burden, with formulators pre-emptively excluding listed substances before official restriction dates.
Buyer concentration among Northeast-based consumer goods conglomerates is compressing supplier negotiation cycles and unbundling technical service from molecule pricing. Procurement teams now demand standalone regulatory documentation packages, displacing the bundled relationship model that historically protected regional distributors. This pattern is most visible in household cleaning, where private-label manufacturers have gained direct sourcing access previously reserved for branded houses.
North America Aroma Chemicals Market Segmentation
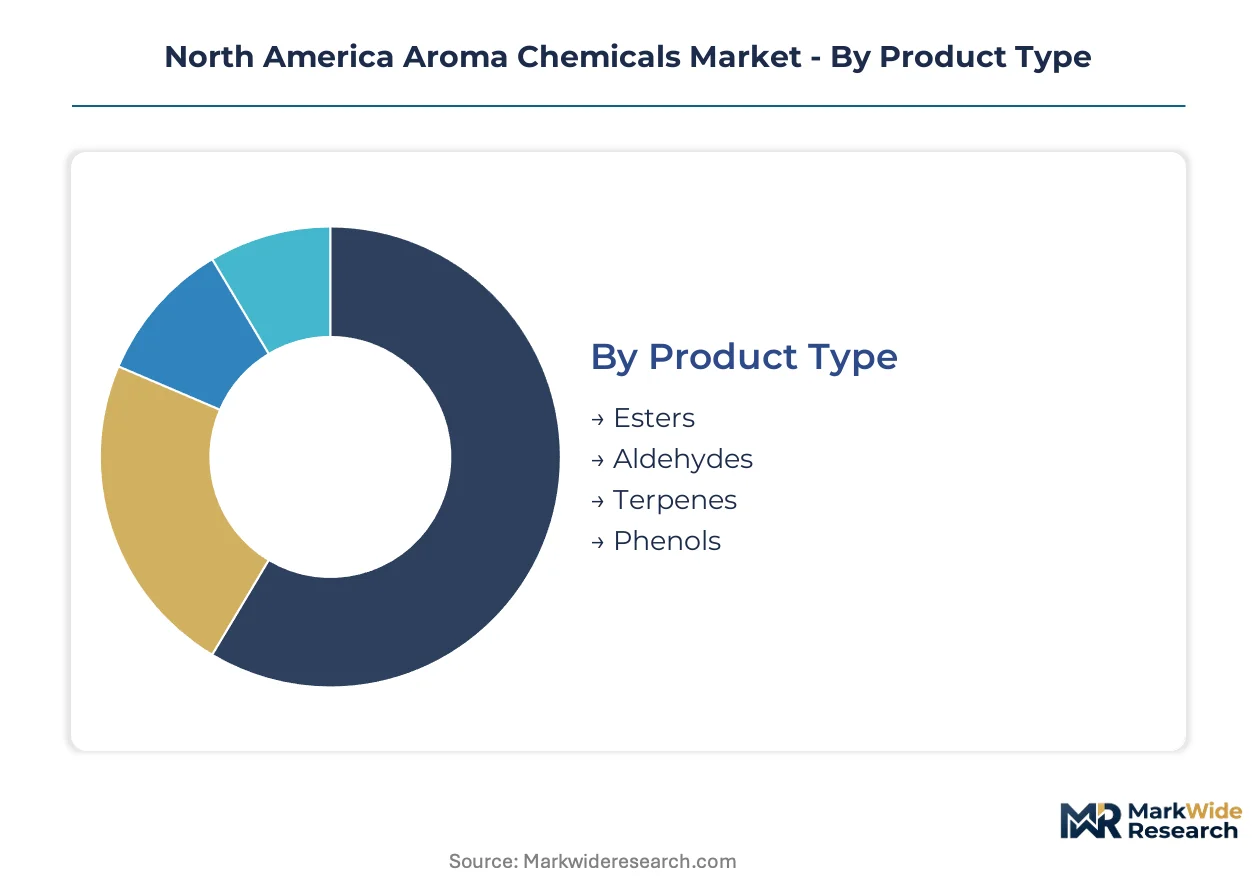
Aroma chemicals serve distinct functional roles across molecular classes and end-use applications, with procurement patterns diverging sharply between high-volume food-grade specifications and low-volume fragrance-grade exclusivity. Understanding these segment boundaries clarifies where suppliers can capture premium pricing versus where scale economics dominate.
Product Type:
Esters command the largest production volumes while terpenes capture the steepest price premiums, creating a bifurcated supply landscape.
- Terpenes:Biosynthesized or extracted cyclic hydrocarbons including limonene, pinene, and citral. California biotechnology clusters are converting terpenoid precursors at commercial scale, reducing dependency on Florida and Brazilian citrus harvest volatility that historically disrupted supply.
- Esters:Carboxylic acid-alcohol condensation products delivering fruit-character profiles. Northeast flavor houses procure these in bulk for processed food applications where regulatory acceptance under FDA FEMA GRAS protocols is well-established.
- Aldehydes:Highly reactive carbonyl compounds requiring stabilized formulations. Demand concentrates in fine fragrance compounding for prestige perfumery.
- Phenols:Aromatic hydroxyl-bearing molecules with antimicrobial properties. Personal care formulators leverage these for dual-function scent and preservation in clean-label positioning.
Mature deployment sits with esters. Newer deployment is concentrated in terpenes.
Application:
Fragrance applications extract the deepest margins per kilogram while household products drive absolute volume throughput.
- Fragrances:Fine and functional perfumery formulations where proprietary captive molecules secure exclusivity. New York and Los Angeles compounders are adopting continuous chromatography systems that compress supplier qualification timelines from eighteen months to under six.
- Flavors:Food-grade aroma integration requiring FEMA GRAS documentation. Northeast corridor procurement consolidation among packaged food manufacturers is concentrating volumes with suppliers offering integrated regulatory packages.
- Personal Care:Skin and hair care scenting subject to California DTSC Safer Consumer Products disclosure requirements. Formulators are pre-emptively excluding listed substances before official restriction dates.
- Household Products:Cleaning and air care applications facing EPA Safer Choice volatile organic compound thresholds. Reformulation demand is expanding addressable market for biosynthesized alternatives.
Margin capture concentrates in fragrances. Volume expansion is accelerating fastest in household products.
End User:
Food and beverage buyers prioritize cost stability while cosmetics houses chase olfactory differentiation.
- Food & Beverage:Processed and packaged goods manufacturers with procurement teams demanding standalone regulatory documentation. The bundled relationship model that protected regional distributors is displacing toward direct sourcing.
- Cosmetics:Prestige and mass beauty brands sourcing through integrated fragrance houses. EPA Safer Choice and California DTSC compliance documentation now gates supplier qualification.
- Household:Private-label and branded cleaning product manufacturers. Northeast-based conglomerates are unbundling technical service from molecule pricing.
- Pharmaceuticals:OTC and prescription products requiring excipient-grade aroma masking. Health Canada PMRA harmonization with EPA frameworks is reducing dual-registration burdens for cross-border suppliers.
Established procurement patterns dominate food and beverage. Emerging specification intensity is concentrated in cosmetics.
Distribution Channel:
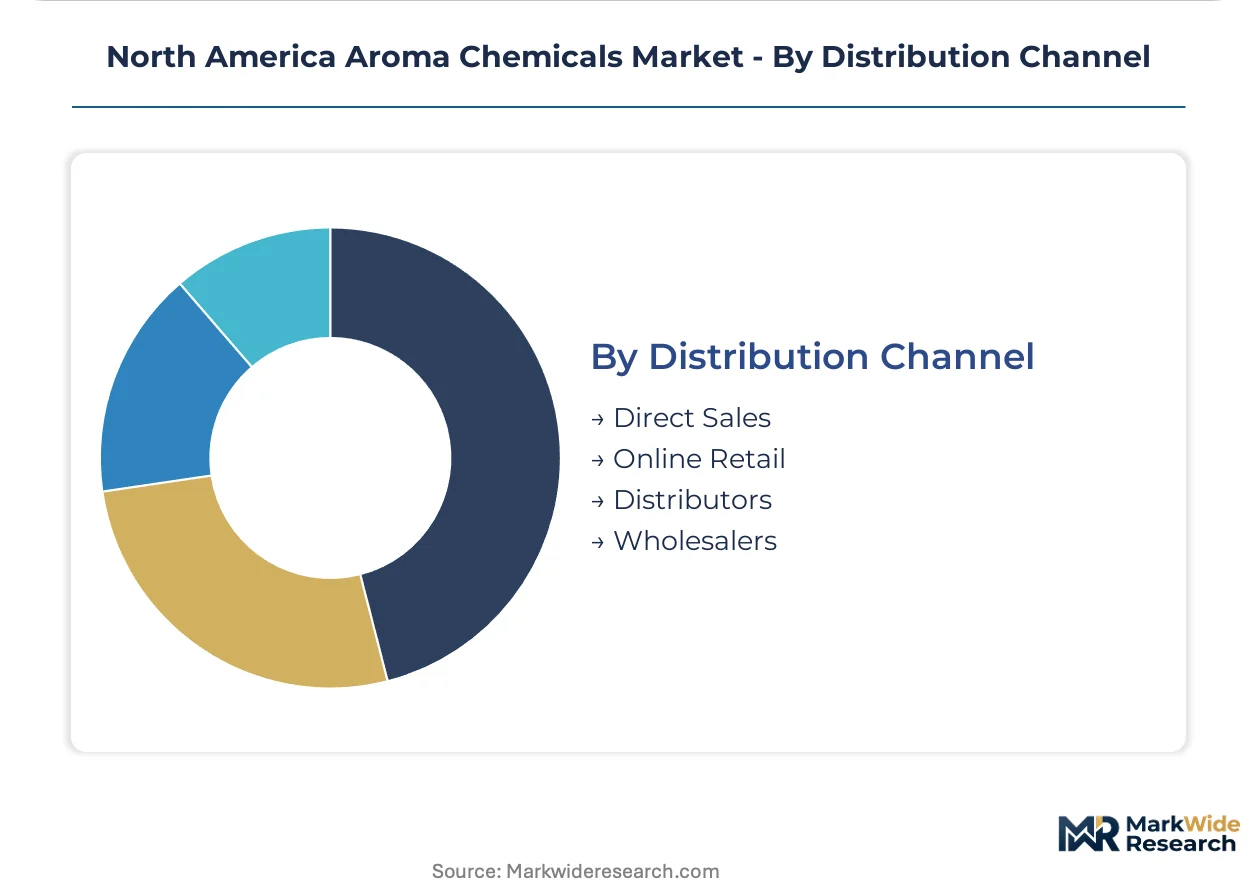
Direct relationships are displacing intermediary layers as buyer concentration increases.
- Direct Sales:Integrated suppliers managing end-to-end regulatory documentation and technical service. Mega-mergers among consumer goods manufacturers are rewarding suppliers with faster customer approval cycles.
- Distributors:Regional inventory and logistics specialists. Their traditional protection is eroding as procurement teams gain direct sourcing access.
- Online Retail:Digital platforms serving small-batch and specialty compounders. Transaction efficiency appeals to niche perfumery and craft food segments.
- Wholesalers:Bulk volume aggregators for standardized commodity grades. Price transparency pressures margins in this channel.
Relationship depth sits with direct sales. Channel experimentation is concentrated in online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York Metro anchors North American aroma chemical demand through its dense concentration of fine fragrance compounders and consumer goods headquarters. The corridor's procurement clusters drive specification intensity across personal care and household applications. Regulatory overlays from EPA and state-level programs reshape supplier qualification requirements throughout the region.
United States
Fine fragrance houses in New York and Los Angeles are compressing supplier qualification timelines through digital process control adoption. EPA Safer Choice thresholds are forcing household product reformulations toward biosynthesized alternatives. The Northeast corridor's packaged food mega-mergers concentrate procurement volumes with documentation-ready suppliers.
California
Precision fermentation infrastructure in California biotechnology clusters is converting terpenoid precursors at commercial scale. The Department of Toxic Substances Control's Safer Consumer Products regulations impose disclosure requirements that national suppliers must address. Los Angeles compounders are adopting continuous chromatography systems fastest, collapsing batch consistency certification from eighteen months to under six.
Canada
Health Canada's PMRA harmonization with EPA frameworks is reducing dual-registration burdens for cross-border aroma chemical suppliers. Ontario-based pharmaceutical excipient manufacturers benefit from aligned volatile organic compound standards. The Pacific Northwest's premium pet food manufacturers are adopting human-grade aroma standards, opening margin-rich verticals.
Mexico
Flavor and fragrance R&D clusters in Mexico City and Monterrey remain underserved by integrated suppliers with full regulatory documentation. Processed food manufacturers in the Bajío Region are consolidating procurement, creating first-mover advantages for entrants with standalone compliance packages. The northern border states' maquiladora networks present channel expansion opportunities for direct sales models.
North America Aroma Chemicals Market Competitive Environment
Premium-margin players sit above commodity-margin players across documentation depth and captive biotechnology capacity. The vendor base organizes into three tiers: integrated global houses with fermentation assets, mid-cap specialists with regional regulatory expertise, and commodity distributors competing on price transparency. Strategic archetypes include captive molecule developers securing formulation exclusivity, compliance-forward suppliers accelerating customer approval cycles, and scale players optimizing legacy petrochemical routes. Dominant competitive moves center on M&A for biotechnology capability and geographic expansion into underpenetrated procurement clusters.
Among Switzerland-based integrated houses, Givaudan and Firmenich SA occupy positions exemplifying captive biotechnology investment. German chemical conglomerate BASF SE anchors the scale-driven tier with commodity-grade volume throughput. International Flavors & Fragrances Inc. represents the documentation-integrated archetype through its Northeast manufacturing footprint and regulatory package bundling. These three entities collectively illustrate how geographic origin and corporate structure map to competitive positioning across premium and standard margin tiers.
| Leading Market Players |
|---|
| BASF SE |
| International Flavors & Fragrances Inc. |
| Symrise AG |
| Givaudan |
| Firmenich SA |
| DSM-firmenich |
| Takasago International Corporation |
| Solvay |
| Bell Flavors & Fragrances |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between fermentation-derived and petrochemical-sourced aroma molecules manifests in parallel supply chain configurations across the United States and Canada. Premium pricing for biosynthesized terpenes reflects California biotechnology cluster proximity and EPA Safer Choice compliance documentation, while commodity esters flow through legacy petrochemical corridors in the Gulf Coast and Northeast.
Pricing Analysis
Value-based pricing anchors on regulatory certification throughput rather than raw material input costs. Three-tier pricing structure across premium fermentation-grade, standard petrochemical-grade, and economy unbranded commodity levels separates suppliers by documentation depth and batch consistency guarantees. Pricing pressure stems from citrus crop volatility transmitting directly to limonene and citral spot markets, compressing margins for extraction-dependent suppliers. Food and beverage procurement teams exhibit highest price sensitivity, while fine fragrance houses prioritize exclusivity over unit economics.
Supply Chain Analysis
Terpenoid feedstock supply rests on biotechnology infrastructure concentration in California, citrus extraction capacity in Florida and Brazil, and petrochemical precursor availability from Gulf Coast refineries. Key inputs include fermentation broth nutrients, citrus peel waste streams, and catalytic reformate fractions. Single-source vulnerability concentrates in Brazilian orange harvests, where climate disruption propagates through global citral availability. Distribution runs through integrated direct sales for premium grades and regional distributors for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where biomanufacturing scale-up costs and regulatory documentation burdens force smaller petrochemical-dependent suppliers toward exit or acquisition.
For Market Incumbents: Hedge citrus supply exposure through captive fermentation capacity in California biotechnology clusters or long-term terpenoid precursor offtake agreements. Reinforce Northeast corridor relationships by unbundling regulatory documentation from molecule pricing to match procurement team demands. Prioritize OSHA workplace exposure limit compliance automation to defend manufacturing site economics against labor cost inflation. For New Entrants and Emerging Players: Begin with Mexico City and Monterrey R&D clusters, where integrated suppliers with full EPA and FDA documentation remain scarce. Target Pacific Northwest premium pet food manufacturers adopting human-grade aroma standards, a vertical with lower price sensitivity and faster qualification cycles. Lead with standalone compliance packages rather than bundled technical service to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing California fermentation assets and established FEMA GRAS dossiers given accelerating EPA Safer Choice mandate expansion. Long-term viability favors suppliers with backward integration into biotechnology feedstocks rather than extraction-dependent models. Watch for FDA GRAS self-determination protocol revisions as an inflection signal for novel natural-identical molecule approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | California biotechnology clusters reduce dependency on Florida citrus harvest volatility. |
| Regulatory Documentation Investment | Standalone FEMA GRAS and EPA Safer Choice packages accelerate Northeast procurement cycles. |
| Backward Integration into Feedstocks | In-house terpenoid precursor production insulates margins from petrochemical commodity swings. |
| Geographic Expansion into Mexico | Monterrey and Mexico City R&D clusters remain underserved by documentation-ready suppliers. |
| Continuous Chromatography Adoption | Los Angeles and New York compounders compress supplier qualification timelines through automated quality assurance. |
Study Parameters
Document review covered FDA FEMA GRAS registrations, EPA Safer Choice certified product listings, California DTSC Safer Consumer Products candidate chemical databases, and SEC 10-K filings from integrated fragrance houses, complemented by interviews with plant managers at biotechnology fermentation facilities, procurement leads at Northeast packaged food manufacturers, technical R&D directors at fine fragrance compounders, and distribution channel partners across the United States and Canada. Bottom-up volume estimates triangulated against top-down market sizing from customs trade data and ACC industry reports.
Historical shipment data cross-referenced against panel input from commercial operations executives grounded the analytical framework across the projection horizon. Segmentation dimensions modeled include molecular class, application vertical, grade tier, end-use industry, and regional production hub. CAGRs derived from slope analysis of normalized volume trends, incorporating biotechnology capacity buildout schedules and regulatory mandate implementation timelines as industry-specific forecast inputs.
Underlying measurement precision varies by segment; fermentation-derived terpenes and EPA Safer Choice certified products carry tighter precision than commodity ester grades subject to petrochemical feedstock volatility. Forecasts reflect assumptions regarding regulatory interpretation stability and biotechnology scale-up execution rates. A small set of named triggers—FDA GRAS protocol revisions, California DTSC candidate list expansion, and Brazilian citrus harvest disruption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Deodorization Systems Market
Flavor and Fragrance Chemicals
Global Natural Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
India Aroma Chemicals Market
Flavor and Fragrance Chemicals
Natural Aroma Chemicals Market
Flavor and Fragrance Chemicals
Asia-Pacific Aroma Chemicals Market
Flavor and Fragrance Chemicals
Dihydrocitronellol Market
Flavor and Fragrance Chemicals
Carnosic Acid Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Anethole Market
Flavor and Fragrance Chemicals
Ethyl Vanillin Market
Flavor and Fragrance Chemicals
Neryl Acetate Market
Flavor and Fragrance Chemicals
Anisic Aldehyde Market
Flavor and Fragrance Chemicals
Middle East and Africa Deodorants Market
Flavor and Fragrance Chemicals
Global Bio Vanillin Market
Flavor and Fragrance Chemicals
Citronellol Market
Flavor and Fragrance Chemicals
Nonanal Market