
 Carnosic Acid Market | 2026-2036
Carnosic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Carnosic Acid Market Outlook
China is narrowing its historical supply deficit in high-purity carnosic acid through expanded rosemary cultivation and extraction infrastructure in Shandong and Sichuan provinces. Kemin Industries leverages vertical integration from raw rosemary sourcing to standardized extract production, sustaining quality consistency across pharmaceutical-grade batches. FLAVEX Naturextrakte anchors European supply with its German extraction facility, while Geneham Pharmaceutical dominates domestic Chinese distribution through direct relationships with nutraceutical compounders.
Carnosic acid is a diterpene compound extracted primarily from rosemary leaves, typically standardized to 5-90% purity depending on end-use requirements, and functions as a potent lipid-soluble antioxidant that interrupts free radical chain reactions in oils and biological systems. Natural carnosic acid extracts command premium positioning in food preservation applications where clean-label requirements exclude synthetic alternatives, while carnosic acid derivatives represent the fastest-expanding category as modified molecular structures enhance bioavailability for nutraceutical encapsulation. Pharmaceutical-grade powder forms currently capture the deepest margin pools due to stringent certification overhead and limited qualified suppliers.
EFSA establishes maximum residue limits and botanical identity specifications that govern carnosic acid entry into European food and supplement channels, while China's NMPA and SAMR enforce dual registration requirements for imported extracts used in domestic pharmaceutical and health food products. FDA GRAS self-affirmation pathways shape US market access timelines for novel rosemary extract formulations. Stakeholders must monitor evolving purity standards across jurisdictions and pre-position extraction capacity ahead of anticipated tightening of contaminant thresholds for botanical actives.
Market Dynamics
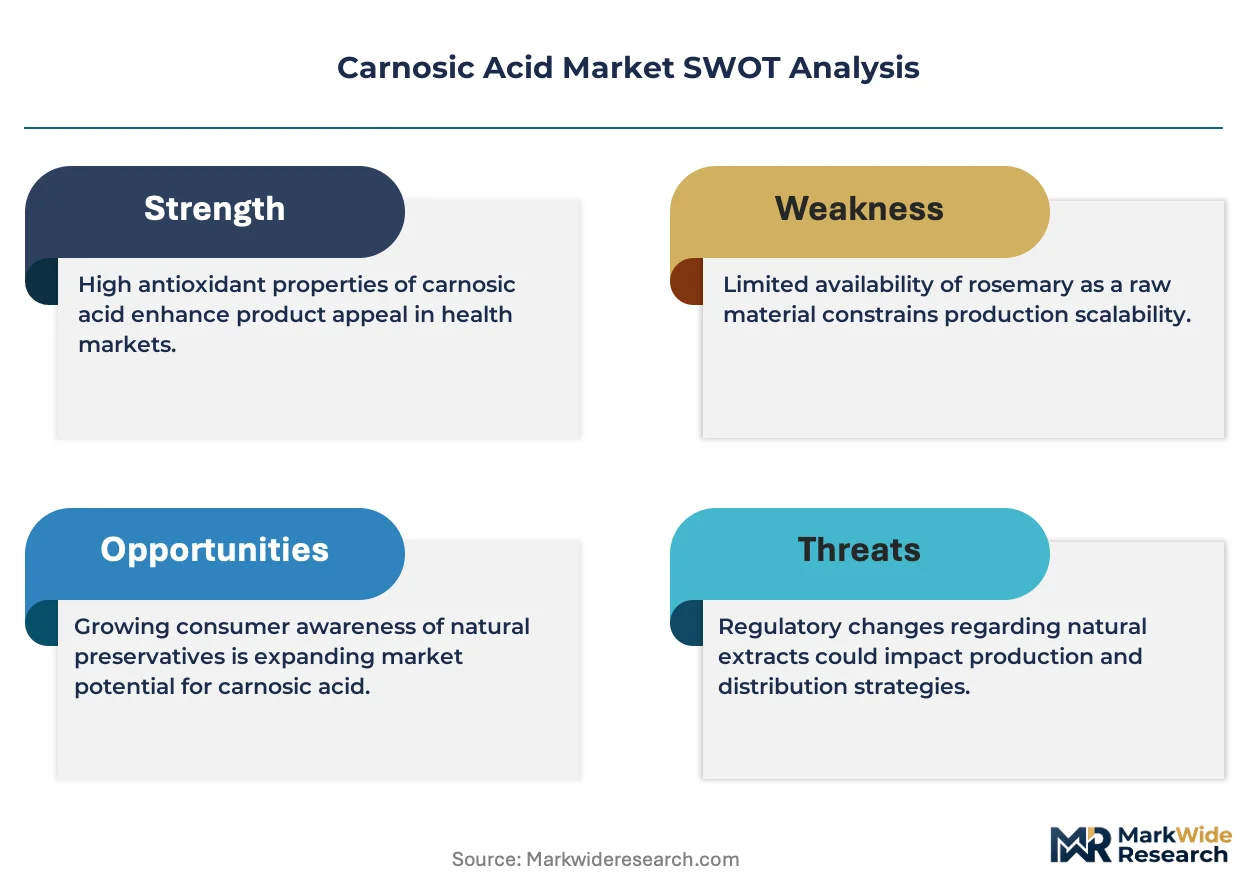
Clean-label mandates across food and nutraceutical channels are compressing synthetic antioxidant share, forcing extractors to scale pharmaceutical-grade carnosic acid capacity ahead of tightening EFSA and FDA contaminant thresholds.
Growth Catalysts
- EFSA purity thresholds:Tightening residue limits for botanical extracts entering European food channels are disqualifying lower-grade suppliers and consolidating procurement around certified extractors.
- Rosemary cultivation expansion:Shandong and Sichuan provinces in China are adding extraction infrastructure to narrow historical supply deficits in high-purity material.
- Lipid-soluble antioxidant demand:Shelf-stable nutraceutical formulations require carnosic acid's free radical interruption capability, pulling volume from synthetic BHA and BHT substitutes.
Market Restraints
- Raw material concentration:Rosemary leaf supply clusters in Mediterranean and Chinese growing regions, exposing processors to climate-driven harvest volatility and input cost spikes.
- Dual registration friction:China's NMPA and SAMR impose parallel requirements for imported extracts used in pharmaceutical and health food products, extending market access timelines.
- Synthetic price competition:Petroleum-derived antioxidants maintain cost advantages in commodity food preservation, limiting carnosic acid penetration in price-sensitive applications.
Strategic Opportunities
- Modified molecular derivatives:Esterified and microencapsulated carnosic acid structures are opening bioavailability-optimized nutraceutical applications beyond standard extract formats.
- Direct-to-compounder distribution:Bypassing traditional ingredient distributors through technical sales relationships with nutraceutical formulators is capturing margin and specification control.
- Pharmaceutical-grade certification:Limited qualified suppliers for USP-grade powder create premium positioning for extractors investing in GMP-compliant isolation infrastructure.
Industry Challenges
- Analytical method standardization:Inconsistent HPLC and GC-MS protocols across laboratories complicate batch certification and cross-border shipment acceptance.
- Specialized extraction talent:Supercritical CO₂ and molecular distillation operation requires skilled technicians scarce in emerging production regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carnosic Acid Market |
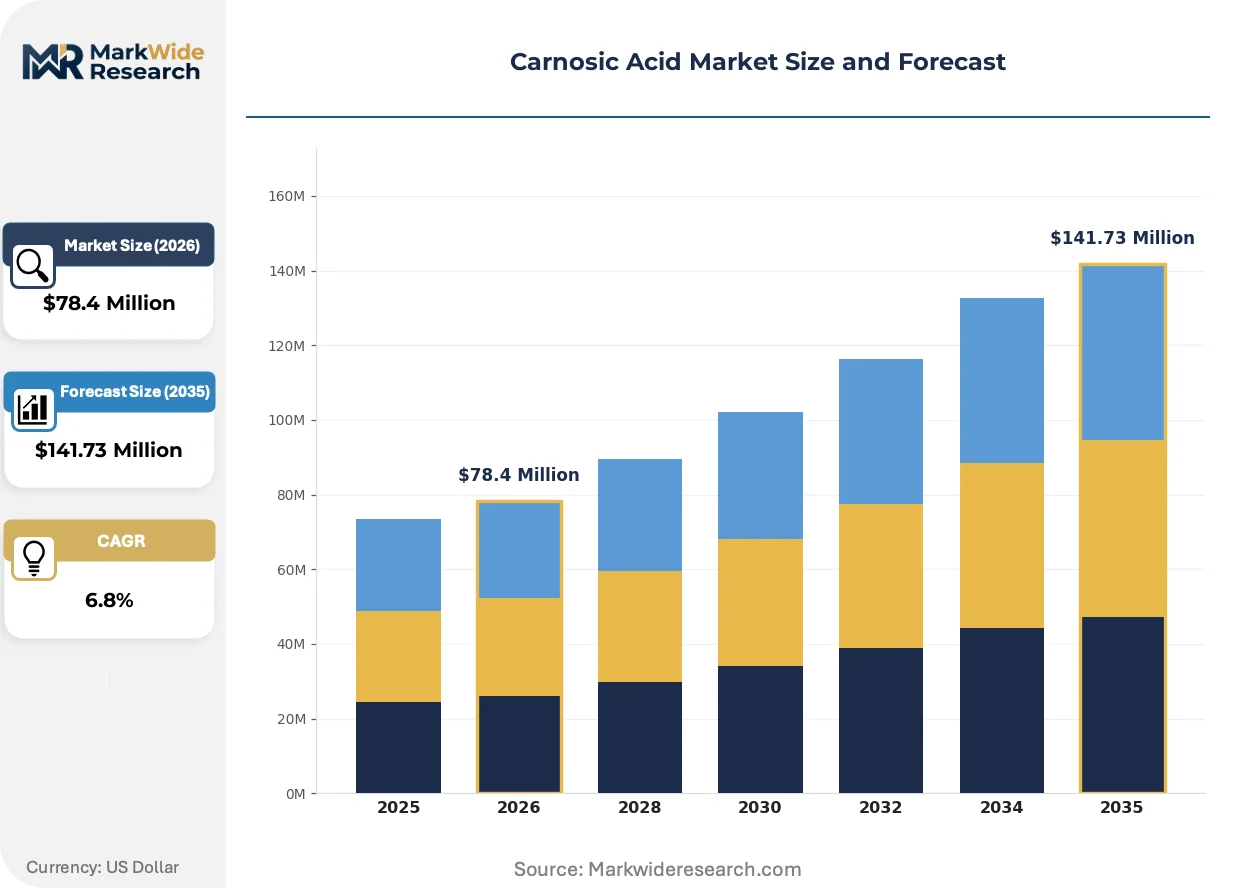
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Carnosic Acid, Synthetic Carnosic Acid, Carnosic Acid Extract, Carnosic Acid Derivatives Application: Food Preservation, Nutraceuticals, Pharmaceutical Products, Personal Care Form: Powder, Liquid, Capsule, Tablets End User: Food Industry, Healthcare, Cosmetics, Animal Feed |
| Companies Covered | Frutarom (IFF), Monteloeder, Naturex (Givaudan), Danisco (DuPont), Kemin Industries, FLAVEX Naturextrakte, Nexira, Geneham Pharmaceutical, Kalsec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carnosic Acid Market Strategic Shifts
Extraction technology convergence with advanced purification methods is compressing cost structures for high-purity material while regulatory chemistry is forcing contaminant detection to sub-ppm thresholds.
Supercritical CO₂ extraction is hybridizing with molecular distillation to isolate carnosic acid at 90%+ purity without thermal degradation. Nutraceutical compounders in North America and Western Europe are adopting this hybrid output for encapsulation-grade material. The technology is compressing the cost gap between food-grade and pharmaceutical-grade specifications.
REACH and EFSA are tightening botanical identity verification and pesticide residue limits for rosemary extracts entering European food and supplement channels. Extractors must now submit full analytical profiles with each shipment, raising compliance overhead. Pharmaceutical-grade suppliers with in-house testing laboratories are absorbing this burden more efficiently than trading houses.
Compounders are consolidating supplier relationships around vertically integrated extractors offering specification guarantees and batch-to-batch consistency. Direct technical partnerships are displacing spot-market purchasing through distributors. This pattern concentrates procurement volume with German and Chinese producers maintaining captive cultivation and extraction assets.
Carnosic Acid Market Segmentation
Carnosic acid procurement patterns diverge sharply across purity grades and end-use specifications. Extractors must configure production lines differently for food-grade versus pharmaceutical-grade batches, while form factor choices determine distribution channel economics.
Product Type:
Cost tier stratification in carnosic acid sourcing reflects purification complexity and certification overhead.
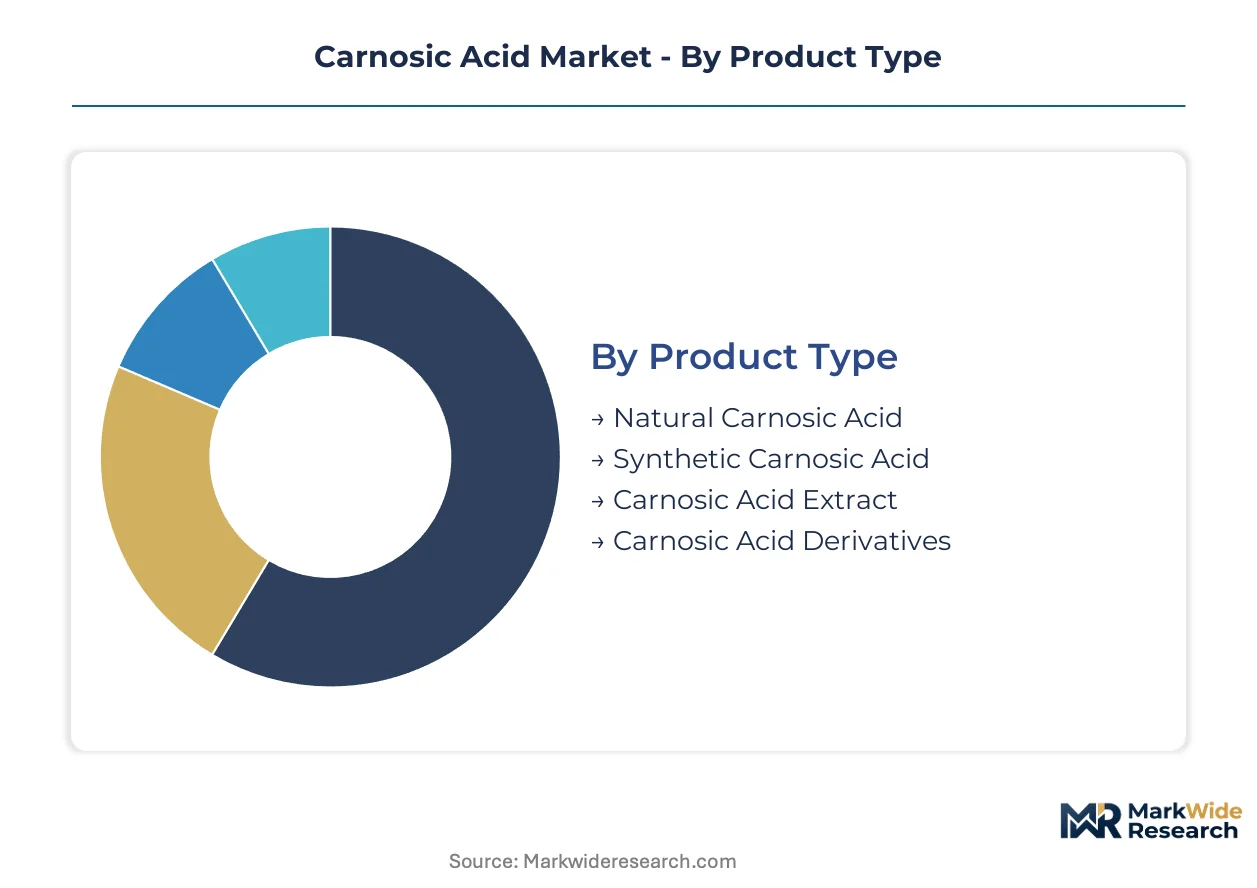
- Natural Carnosic Acid:Rosemary leaf extracts standardized to 5-60% purity dominate food preservation procurement in Europe and North America. EFSA residue limits and FDA GRAS requirements disqualify uncertified suppliers, consolidating volume around German and Chinese extractors with in-house HPLC laboratories.
- Carnosic Acid Derivatives:Esterified and microencapsulated molecular structures enhance bioavailability for nutraceutical encapsulation. Modified forms are climbing the fastest as compounders in the United States and Japan seek differentiated positioning in shelf-stable supplement formulations.
- Synthetic Carnosic Acid:Petrochemical-derived alternatives maintain cost advantages in commodity applications where clean-label requirements do not apply.
- Carnosic Acid Extract:Crude rosemary oleoresins serve regional food processors with less stringent purity thresholds.
Natural carnosic acid holds installed capacity. Carnosic acid derivatives are rotating up the share rankings.
Application:
End-use specifications determine margin capture and regulatory pathway complexity.
- Nutraceuticals:Lipid-soluble antioxidant demand from capsule and soft-gel manufacturers pulls high-purity powder volumes. Shandong extractors are scaling refined output to serve domestic Chinese compounders and export markets simultaneously.
- Food Preservation:Clean-label mandates across European retail channels are compressing synthetic BHA and BHT share. Natural carnosic acid penetration concentrates in premium edible oil and snack applications where EFSA-compliant certification is non-negotiable.
- Pharmaceutical Products:USP-grade material requires GMP-compliant isolation infrastructure with limited qualified suppliers.
- Personal Care:Topical antioxidant formulations in Korean and French cosmetics channels utilize lower-concentration liquid extracts.
Food preservation commands volume throughput. Nutraceuticals is expanding most quickly.
Form:
Physical configuration dictates logistics economics and customer handling requirements.
- Powder:Pharmaceutical-grade powder captures the deepest margin pools due to stringent certification overhead and limited qualified suppliers. German and Chinese GMP facilities dominate batch-to-batch consistency for encapsulation-grade material.
- Liquid:Oleoresin formats serve food manufacturers requiring direct oil-soluble integration without reconstitution steps.
- Capsule:Pre-formulated dosage forms bypass compounder processing for direct-to-consumer nutraceutical brands.
- Tablets:Compressed formats appeal to mass-market supplement channels with cost-sensitive positioning.
Powder maintains specification leadership. Liquid is gaining share in food processing integration.
End User:
Customer type determines contract structure and technical service intensity.
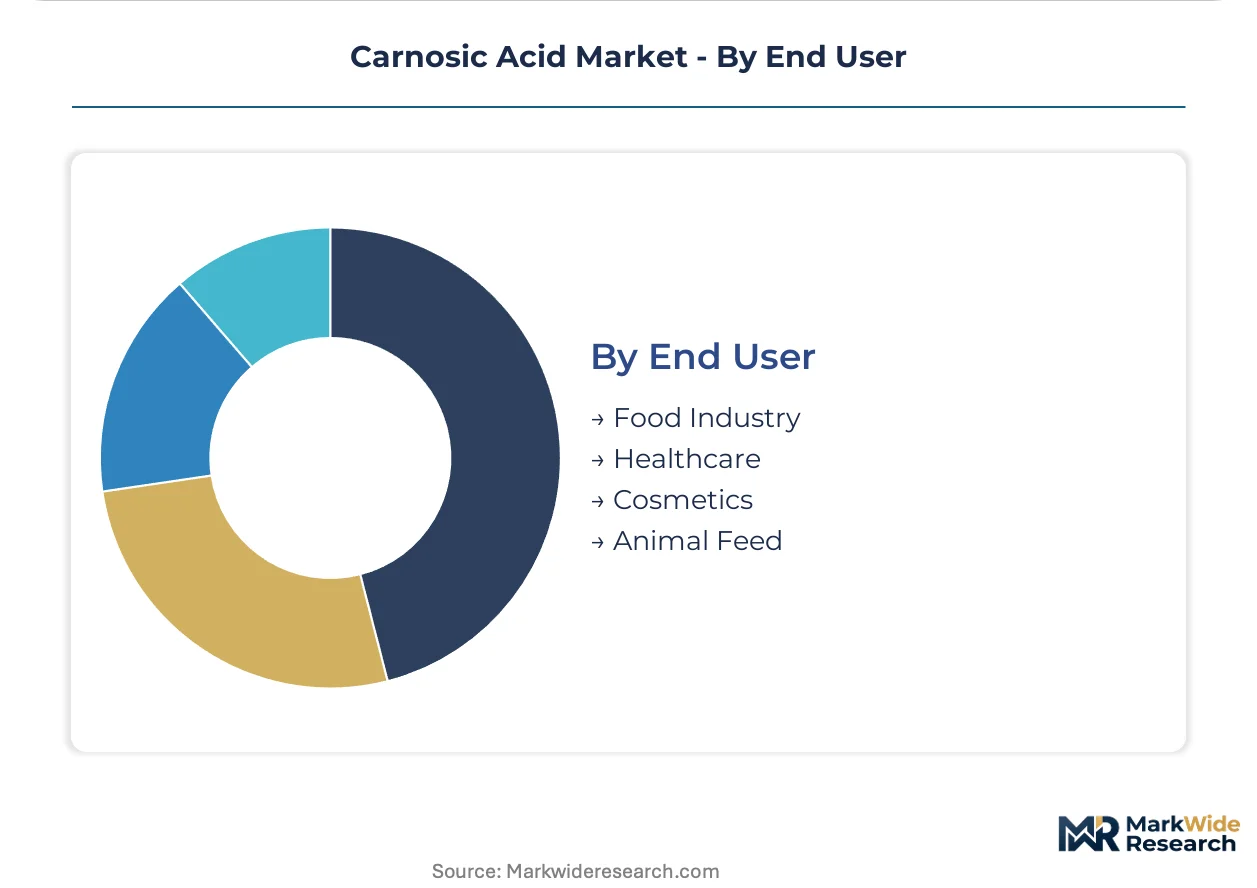
- Food Industry:Multinational edible oil processors and snack manufacturers in Italy and the United States specify EFSA-compliant extracts with full analytical profiles per shipment.
- Healthcare:Pharmaceutical manufacturers require USP-grade powder with validated HPLC methods and contaminant detection to sub-ppm thresholds.
- Cosmetics:French and Korean formulators source liquid extracts for topical antioxidant claims in premium skincare positioning.
- Animal Feed:Pet food and livestock supplement producers in Brazil and Thailand utilize lower-purity extracts for oxidation stability in rendered fats.
Food industry anchors procurement volume. Healthcare is steepening its growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes carnosic acid primarily for nutraceutical encapsulation and export refining, while European buyers concentrate procurement in food preservation channels demanding EFSA-compliant certification. The United States splits demand between GRAS-affirmed food applications and pharmaceutical-grade powder for supplement manufacturing.
China
Domestic nutraceutical compounders in Shandong and Sichuan provinces are scaling refined carnosic acid output for captive use and export markets. SAMR and NMPA enforce dual registration requirements for imported extracts, extending market access timelines for foreign suppliers. Extraction infrastructure clusters in Jinan and Chengdu are narrowing historical supply deficits in high-purity material.
Germany
Food manufacturers specify EFSA-compliant rosemary extracts with full analytical profiles for premium edible oil and snack applications. REACH frameworks mandate botanical identity verification and sub-ppm contaminant detection thresholds. FLAVEX Naturextrakte anchors European supply from its German extraction facility, serving compounders across France and Italy.
United States
Supplement brands source lipid-soluble antioxidants for shelf-stable soft-gel formulations, displacing synthetic BHA and BHT alternatives. FDA GRAS self-affirmation pathways shape market access timelines for novel rosemary extract formulations. Kemin Industries maintains vertical control from raw rosemary sourcing to standardized extract production for pharmaceutical-grade batches.
France
Cosmetics formulators in Paris and Lyon utilize lower-concentration liquid carnosic acid extracts for topical antioxidant claims in premium skincare. ANSM enforces purity specifications for botanical actives entering dermal applications. Regional procurement concentrates through technical partnerships with German and Chinese extractors offering specification guarantees.
Japan
Health food manufacturers demand microencapsulated carnosic acid derivatives for bioavailability-optimized supplement formulations. PMDA and METI govern import registration for novel botanical extracts used in functional food products. Tokyo-based compounders consolidate supplier relationships around vertically integrated extractors with captive cultivation assets.
Carnosic Acid Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three strata: vertically integrated extractors with captive rosemary cultivation, specialized botanical houses with regional certification expertise, and diversified flavor houses leveraging existing antioxidant portfolios. Consolidation pressures favor extractors with in-house HPLC laboratories and GMP-compliant isolation infrastructure. Strategic moves center on backward integration into rosemary farming and direct technical partnerships with nutraceutical compounders.
Among vertically integrated specialists, Kemin Industries exemplifies the captive supply model spanning raw material sourcing to pharmaceutical-grade batch production. FLAVEX Naturextrakte occupies a position within the European certification-focused tier, anchoring regional supply through German extraction assets. Geneham Pharmaceutical represents the domestic Chinese distribution archetype, leveraging direct relationships with local nutraceutical compounders to capture specification control and margin.
| Leading Market Players |
|---|
| Frutarom (IFF) |
| Monteloeder |
| Naturex (Givaudan) |
| Danisco (DuPont) |
| Kemin Industries |
| FLAVEX Naturextrakte |
| Nexira |
| Geneham Pharmaceutical |
| Kalsec |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Chinese pharmaceutical-grade extraction infrastructure is compressing supplier margins while amplifying pricing power for German and US facilities with certified GMP lines. This utilization asymmetry forces buyers into longer contract commitments and tiered procurement strategies that discriminate by purity threshold.
Pricing Analysis
Long-term offtake contracts dominate procurement for pharmaceutical-grade powder, locking in volume commitments from nutraceutical compounders seeking batch-to-batch consistency. Three-tier pricing structure across premium, standard, and economy levels separates USP-certified pharmaceutical batches from food-grade extracts and crude oleoresins. Pricing pressure stems from synthetic antioxidant competition in commodity food applications where clean-label requirements do not apply. Animal feed processors exhibit highest price sensitivity, while pharmaceutical manufacturers absorb premium positioning for certified material.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts rosemary extract flows, forcing compounders to dual-source from German and domestic facilities. Raw material supply draws from rosemary cultivation clusters in Shandong province, Mediterranean growing regions, and Sichuan extraction infrastructure. Supercritical CO₂ equipment and molecular distillation units constitute critical input dependencies with limited qualified vendors. Single-source vulnerability concentrates in high-purity isolation technology. Distribution runs through direct technical sales relationships with nutraceutical formulators, bypassing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carnosic acid sits in early-cycle expansion as clean-label mandates displace synthetic antioxidants across European and North American food channels. EFSA and FDA purity tightening accelerates procurement consolidation around certified extractors with captive cultivation assets.
For Market Incumbents: Build certification moats through GMP-compliant isolation infrastructure and in-house HPLC laboratories that absorb rising analytical overhead. Expand extraction capacity in Shandong province to capture Chinese domestic demand growth while defending against synthetic price competition in commodity tiers. Lock in long-term rosemary supply contracts ahead of climate-driven harvest volatility. For New Entrants and Emerging Players: Establish a beachhead in microencapsulated carnosic acid derivatives for Japanese and US nutraceutical compounders seeking bioavailability-optimized formulations. Target animal feed oxidation stability applications in Brazil and Thailand where purity thresholds remain permissive and synthetic alternatives face regulatory pressure. Lead with technical sales partnerships rather than distributor relationships to capture specification control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated extractors with captive rosemary cultivation and pharmaceutical-grade certification. Five-to-ten-year viability favors facilities with backward integration into farming assets and direct compounder relationships. Monitor EFSA contaminant threshold announcements as the critical inflection signal for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rosemary Cultivation | Captive supply from Shandong and Sichuan plantations secures raw material consistency against climate volatility. |
| GMP-Compliant Isolation Infrastructure Investment | Pharmaceutical-grade certification opens USP powder margins inaccessible to food-grade competitors. |
| Direct-to-Compounder Technical Partnerships | Bypassing distributors captures margin and specification control with nutraceutical formulators in North America. |
| Microencapsulation Capability Development | Bioavailability-optimized derivatives command premium positioning in Japanese functional food channels. |
| Long-Term Supply Agreements with Edible Oil Processors | EFSA-compliant certification locks in European food preservation volume against synthetic competition. |
Study Parameters
Cross-validation between extraction facility operating data and customs trade records anchors the qualitative findings on supply concentration. Primary interviews with supercritical CO₂ equipment technicians, nutraceutical procurement managers, rosemary cultivation cooperatives, and EFSA regulatory consultants combined with secondary validation from REACH registration databases, NMPA filing records, and FDA GRAS affirmation notices. Bottom-up capacity modeling and top-down demand estimation triangulate volume outputs.
Calibration against historical purity-grade pricing spreads and extraction yield data refines the analytical framework across the projection horizon. Segmentation dimensions include purity tier, application end-use, physical form factor, and regional regulatory cluster. CAGRs derive from fitted growth curves incorporating EFSA threshold implementation timelines and Chinese domestic nutraceutical expansion rates. Rosemary harvest yield volatility and synthetic antioxidant price cycles constitute industry-specific forecast inputs.
Stress conditions across raw material concentration limits, regulatory purity tightening velocity, and synthetic substitute pricing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on certification adoption curves and cultivation expansion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Middle East and Africa Aroma Chemicals Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Camphor Market
Flavor and Fragrance Chemicals
Limonene Market
Flavor and Fragrance Chemicals
Alpha Ionone Market
Flavor and Fragrance Chemicals
Herbal Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Anethole Market
Flavor and Fragrance Chemicals
Global Terpene Market
Flavor and Fragrance Chemicals
3-Methyl Valeric Acid Market
Flavor and Fragrance Chemicals
Fragrance Fixatives Market
Flavor and Fragrance Chemicals
Anisole Market
Flavor and Fragrance Chemicals
Linalool Market
Flavor and Fragrance Chemicals
Sage Essential Oil Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Natural Fragrance Chemicals Market