
 Spearmint Oil Market | 2026-2036
Spearmint Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Spearmint Oil Market Outlook
Steam distillation automation is fragmenting traditional batch-processing economics across spearmint oil supply chains. Robertet Group leverages captive cultivation in France to sustain pharmaceutical-grade consistency. Ultra International B.V. anchors European aromatherapy distribution through specialty channel control. AOS Products Pvt. Ltd. dominates Indian bulk exports with backward integration into contract farming networks across the Indo-Gangetic plain.
Spearmint oil is a volatile essential oil obtained from Mentha spicata, typically containing 50-70% carvone and 10-20% limonene by composition, produced via steam distillation of flowering tops for flavoring, fragrance, and therapeutic applications. Essential oils command premium pricing in pharmaceutical and aromatherapy end uses where carvone concentration thresholds determine therapeutic efficacy. Extracts and concentrates compete on cost in food and beverage applications where flavor intensity per unit volume drives procurement decisions. Crude oils occupy commodity positioning for industrial fragrance blending and intermediate refining.
FDA GRAS self-affirmation requirements and EPA pesticide residue limits shape import eligibility for US-bound shipments, while EMA monograph standards and REACH registration obligations govern European pharmaceutical and cosmetic access. India's BIS certification for essential oil purity and FSSAI food additive approvals create compliance layering for domestic and export-oriented processors. Stakeholders must monitor regulatory divergence between pharmaceutical-grade and food-grade specifications as classification decisions determine testing burdens and market access pathways.
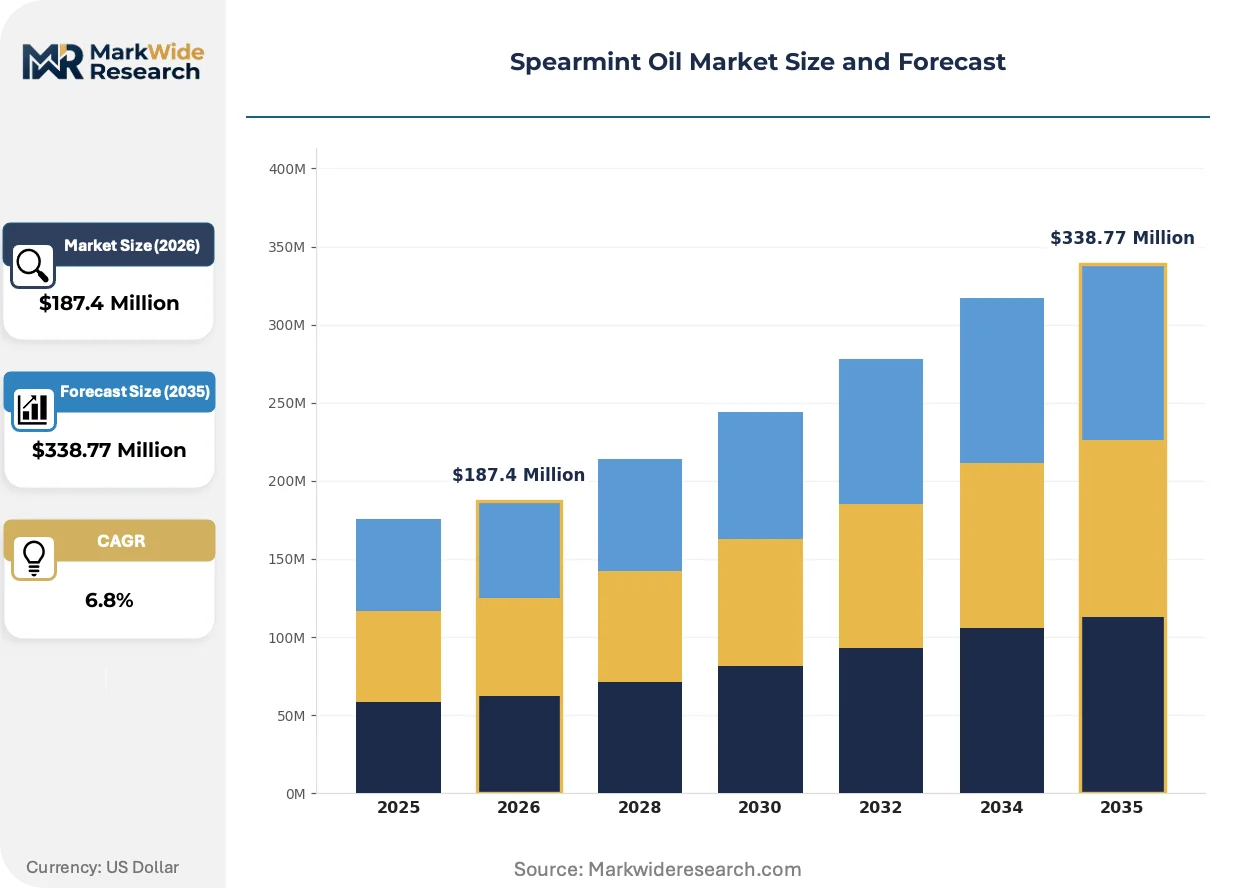
Market Dynamics
Steam distillation automation is fragmenting traditional batch-processing economics across spearmint oil supply chains, compressing margins for legacy processors while rewarding capital-intensive operators with pharmaceutical-grade certification capabilities.
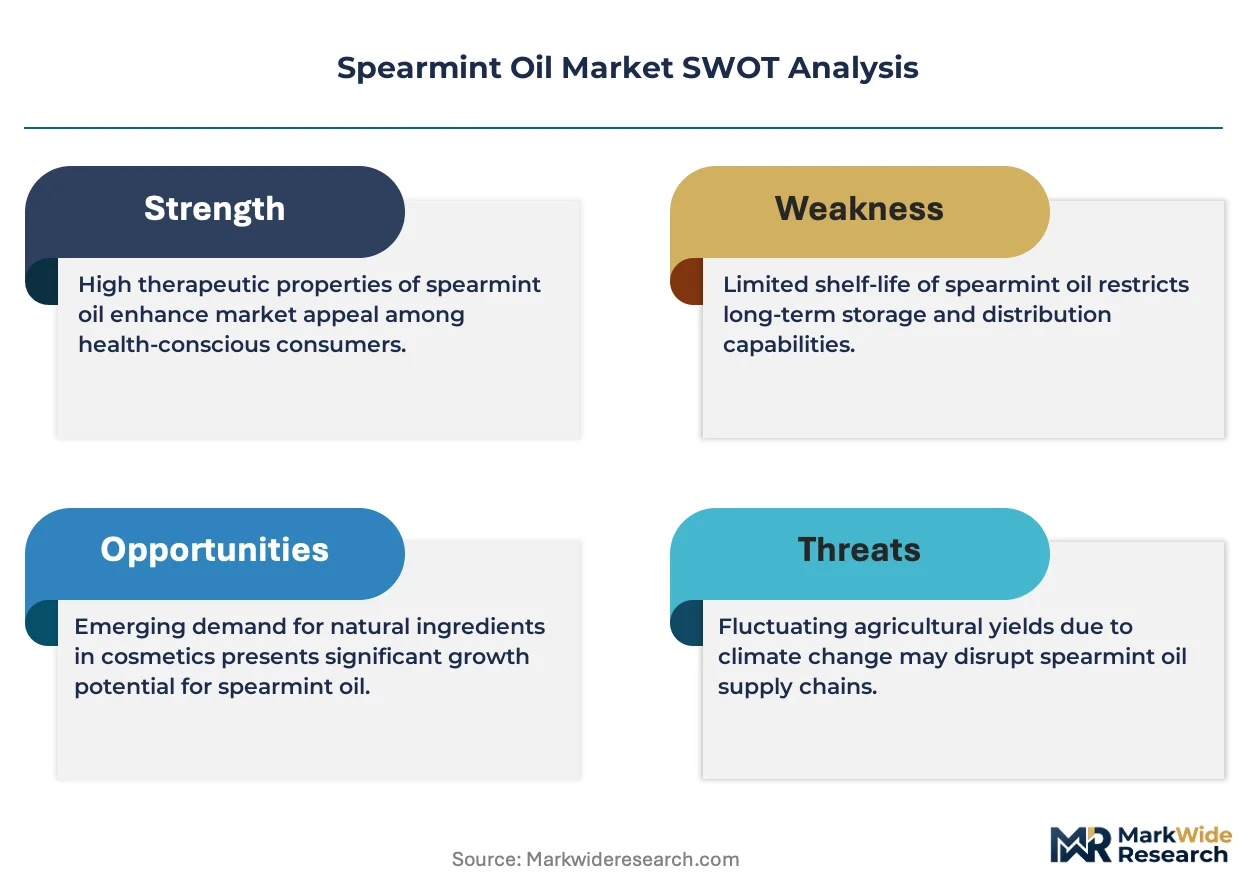
Growth Catalysts
- Pharmaceutical formulators:Enteric-coated digestive health products are expanding spearmint oil incorporation as carvone concentration thresholds demonstrate therapeutic efficacy in irritable bowel syndrome applications.
- REACH compliance tightening:ECHA purity benchmarks for food-grade and therapeutic-grade batches are filtering out substandard suppliers and consolidating demand around certified European processors.
- Contract farming networks:Uttar Pradesh and Madhya Pradesh distillation clusters are securing captive raw material flows through backward integration into menthol-aromatics belt cultivation.
Market Restraints
- Input cost volatility:Mentha spicata biomass prices fluctuate with monsoon-dependent yields across the Indo-Gangetic plain, squeezing processor margins during drought cycles.
- Supply concentration risk:India's dominance in bulk distillation creates single-geography dependency for global pharmaceutical and flavor houses.
- Substitution threat:Synthetic carvone from petrochemical feedstocks competes on cost in industrial fragrance blending where therapeutic claims are absent.
Strategic Opportunities
- Underpenetrated therapeutic applications:Stress-relief and sleep-aid formulations in North American nutraceutical channels represent expansion white space beyond digestive health.
- Regulatory tailwind:FDA GRAS self-affirmation pathway revisions are streamlining food additive approvals for compliant Indian exporters.
- Technology convergence:Near-infrared spectroscopy paired with blockchain traceability is digitizing batch certification for pharmaceutical buyers demanding provenance documentation.
Industry Challenges
- Certification timeline compression:BIS essential oil purity testing backlogs in India delay export shipments, forcing processors to maintain costly inventory buffers.
- Capex intensity:Automated steam distillation systems require substantial capital deployment that excludes smallholder-integrated processors from pharmaceutical-grade supply tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spearmint Oil Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Essential Oils, Extracts, Crude Oils Application: Food & Beverages, Cosmetics, Pharmaceuticals, Aromatherapy Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Food Manufacturers, Cosmetic Companies, Healthcare Providers, Retail Consumers |
| Companies Covered | AOS Products Pvt. Ltd., Ultra International B.V., Berje Inc., doTERRA International, Young Living Essential Oils, Biolandes, Synthite Industries Ltd., Robertet Group, Arora Aromatics Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spearmint Oil Market Strategic Shifts
Digital traceability infrastructure and regulatory harmonization pressures are converging to reshape competitive positioning across spearmint oil value chains, favoring operators with integrated quality assurance capabilities.
Near-infrared spectroscopy deployed at distillation facilities is digitizing real-time carvone and limonene quantification. Pharmaceutical formulators in Germany and Switzerland are mandating this specification data for batch release. The technology is digitizing quality assurance workflows that previously required centralized laboratory testing, compressing certification cycles from weeks to hours.
EMA monograph standards for herbal medicinal products are tightening residual solvent limits for spearmint oil destined for European therapeutic markets. French and Italian fragrance houses are reformulating product lines to preempt compliance gaps. Aromatherapy distributors are shifting procurement toward REACH-registered suppliers with documented supply chain controls.
Direct contracting between pharmaceutical manufacturers and Indian distillation clusters is displacing traditional broker-mediated spot purchasing. Large North American nutraceutical brands are establishing multi-year offtake agreements with Uttar Pradesh processors. This pattern concentrates volume among backward-integrated operators with captive cultivation and BIS-certified laboratory infrastructure.
Spearmint Oil Market Segmentation
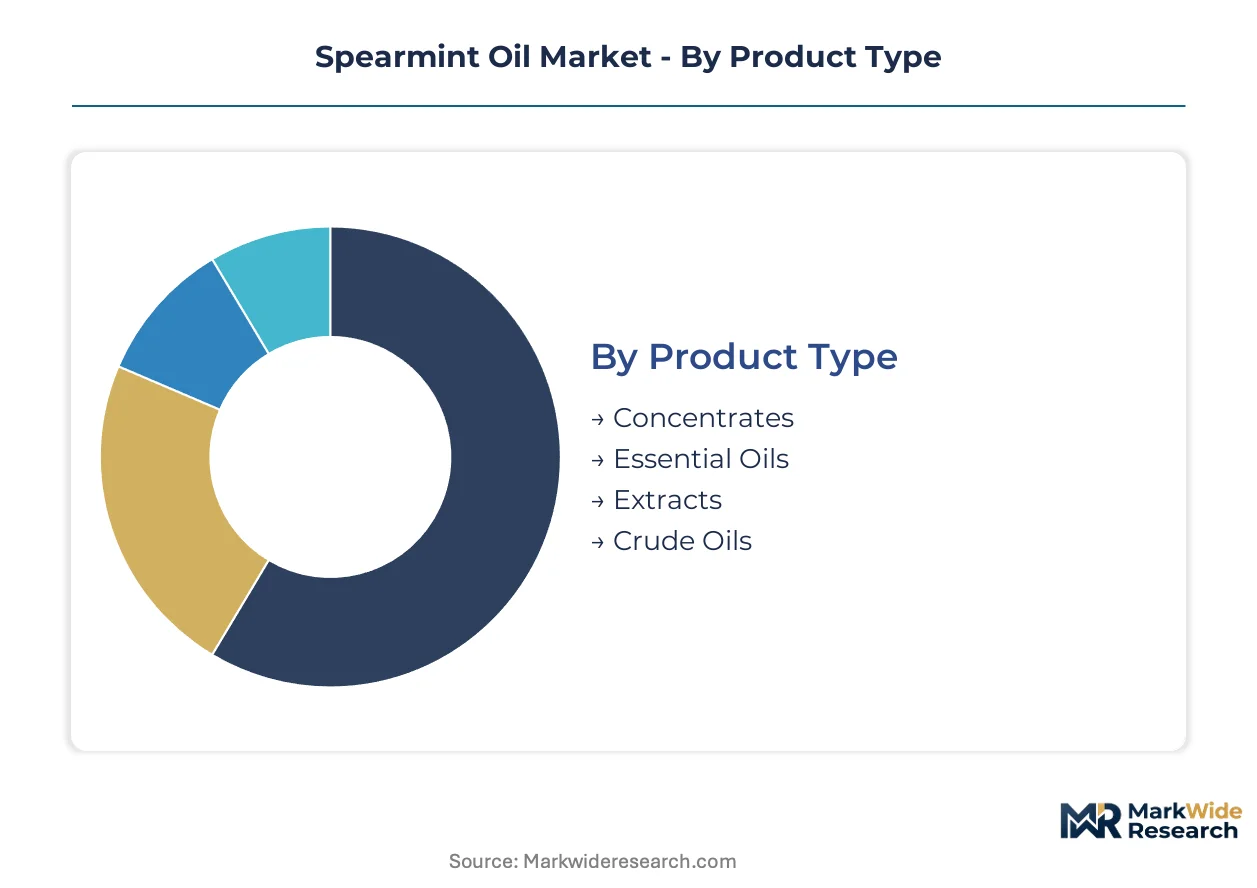
Spearmint oil procurement patterns diverge sharply across product grades and end-use specifications, with pharmaceutical buyers demanding certificate-of-analysis documentation while food processors prioritize cost-per-unit-flavor intensity. Understanding these segment boundaries clarifies why automated distillation investments concentrate in certain tiers while legacy batch processors retreat to commodity positioning.
Product Type:
Essential oils turn inventory fastest through pharmaceutical and aromatherapy channels where batch-specific carvone certificates drive just-in-time procurement, while crude oils sit longest as industrial buyers accumulate bulk positions during seasonal harvest windows.
- Essential Oils:Steam-distilled fractions containing 50-70% carvone and 10-20% limonene command premium positioning in therapeutic applications where EMA monograph compliance is mandatory. German pharmaceutical formulators and Swiss aromatherapy distributors concentrate procurement here, with carvone concentration thresholds determining batch eligibility for irritable bowel syndrome formulations.
- Crude Oils:Unrefined distillation outputs serve industrial fragrance blending and intermediate refining operations where synthetic carvone from petrochemical feedstocks exerts substitution pressure. These batches move through broker-mediated spot markets with minimal certification documentation, compressing margins for processors lacking downstream refining capabilities.
- Concentrates:High-potency formulations deliver flavor intensity per unit volume for food and beverage applications where procurement decisions hinge on cost efficiency metrics.
- Extracts:Solvent-based or cold-pressed alternatives compete on price in cosmetic formulations where volatile oil stability is less critical than in therapeutic uses.
Essential oils dominate installed base value. Crude oils are where expansion concentrates among cost-sensitive industrial fragrance houses.
Application:
Pharmaceutical applications extract the highest margin per kilogram through therapeutic-grade certification requirements, while food and beverage volumes scale through formulation flexibility and lower regulatory testing burdens.
- Pharmaceuticals:Enteric-coated digestive health products represent the fastest-climbing demand segment as carvone concentration thresholds demonstrate efficacy in irritable bowel syndrome applications. FDA GRAS self-affirmation and EMA monograph compliance create dual-certification requirements that filter supplier pools to REACH-registered processors with captive laboratory infrastructure.
- Food & Beverages:Flavor intensity per unit volume drives procurement across confectionery, chewing gum, and oral care formulations where FSSAI approvals in India and FDA food additive clearances in the United States create compliance layering. Contract farming networks in Uttar Pradesh and Madhya Pradesh supply distillation clusters with raw material cost advantages.
- Cosmetics:Fragrance incorporation and topical formulations demand stability-optimized extracts where shelf-life performance outweighs volatile oil concentration metrics.
- Aromatherapy:Specialty channel distribution through European wellness retailers prioritizes provenance documentation and organic certification over chemical specification alone.
Food and beverages anchor volume throughput. Pharmaceuticals command the steepest expansion trajectory as therapeutic validation deepens.
Distribution Channel:
Wholesale channels move the largest absolute tonnage through multi-year offtake agreements, while online retail fragments purchasing into smaller lot sizes with accelerated fulfillment expectations.
- Wholesale:Direct contracting between North American nutraceutical brands and Indian distillation clusters is displacing traditional broker intermediation, concentrating volume among backward-integrated operators with BIS-certified laboratory infrastructure and captive cultivation across the Indo-Gangetic plain.
- Specialty Stores:European aromatherapy distributors anchor procurement through Ultra International B.V. and comparable channel controllers who mandate REACH registration and documented supply chain controls.
- Online Retail:E-commerce penetration in wellness and DIY cosmetic segments is expanding lot-size fragmentation, with near-infrared spectroscopy and blockchain traceability emerging as competitive differentiators for direct-to-consumer pharmaceutical-grade positioning.
- Supermarkets:Mass-market food and beverage applications move through conventional retail procurement with price-sensitive volume contracting.
Wholesale channels dominate institutional procurement. Online retail is gaining share fastest among wellness-oriented retail consumers.
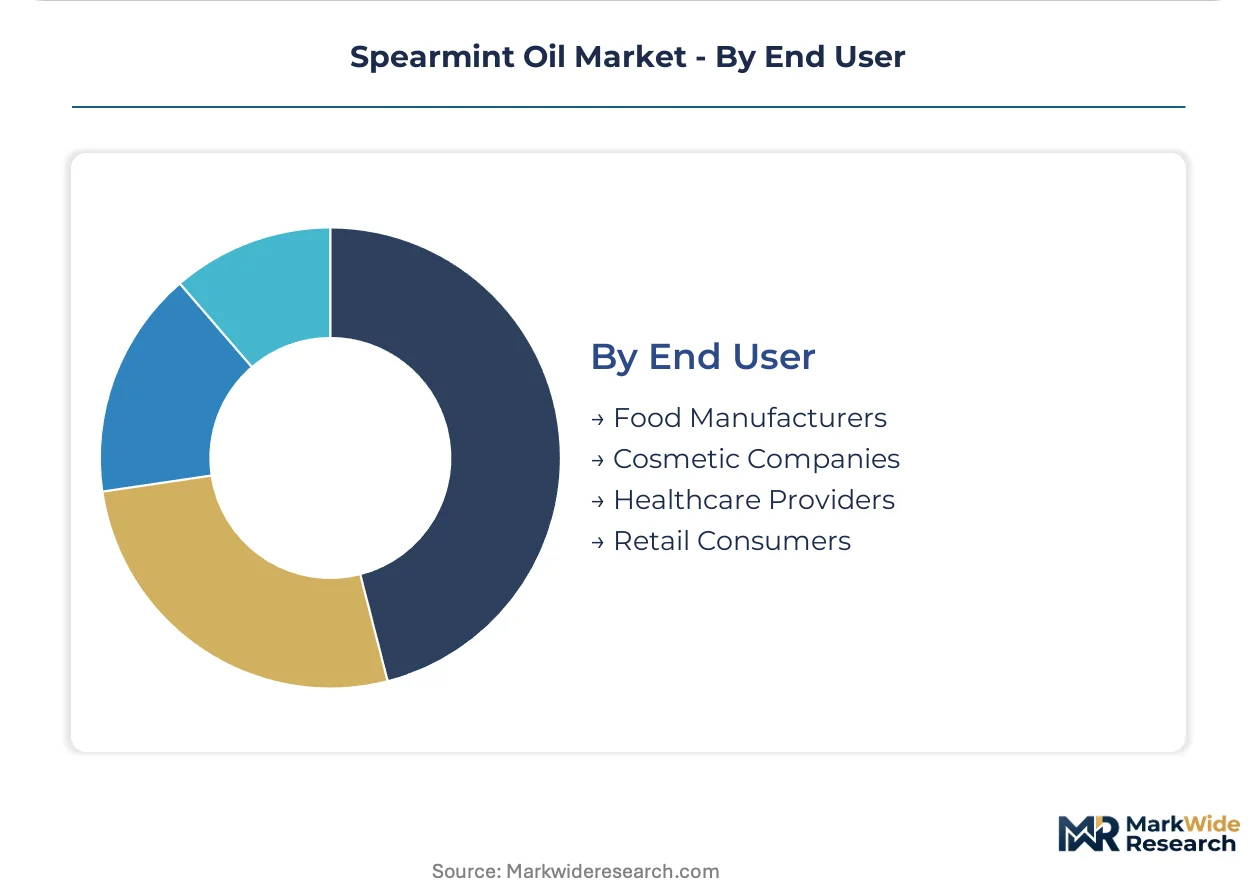
End User:
Healthcare providers impose the most stringent documentation requirements through therapeutic-grade specifications, while retail consumers drive fragmentation through channel proliferation and information asymmetry.
- Healthcare Providers:Hospital systems and specialty pharmacy networks in Germany and Switzerland mandate real-time carvone quantification data from near-infrared spectroscopy deployments, compressing certification cycles from weeks to hours and excluding smallholder-integrated processors lacking capital-intensive automation.
- Food Manufacturers:Global flavor houses and regional confectionery processors balance cost efficiency with FSSAI and FDA compliance, with procurement shifting toward contract farming networks that secure monsoon-dependent yield stability.
- Cosmetic Companies:French and Italian fragrance houses reformulate product lines to preempt EMA residual solvent limit tightening, shifting sourcing toward REACH-registered suppliers.
- Retail Consumers:Direct purchasing through wellness channels and e-commerce platforms prioritizes organic certification and provenance storytelling over chemical specification transparency.
Food manufacturers anchor baseline demand. Healthcare providers are where specification intensity and margin extraction concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian distillation clusters export bulk spearmint oil to pharmaceutical formulators in Germany and Switzerland, while French fragrance houses source captive cultivation outputs for therapeutic-grade consistency. Trade flows concentrate around REACH-registered processors with backward integration into menthol-aromatics belt farming networks.
India
Uttar Pradesh and Madhya Pradesh contract farming networks supply distillation clusters with Mentha spicata biomass for global pharmaceutical and flavor house procurement. FSSAI food additive approvals and BIS essential oil purity certification create compliance layering for export-oriented processors. Kanpur and Lucknow distillation hubs are automating steam distillation systems to meet carvone concentration thresholds for European therapeutic markets.
Germany
Pharmaceutical formulators in Frankfurt and Munich mandate near-infrared spectroscopy data for batch release of enteric-coated digestive health products. EMA monograph standards for herbal medicinal products filter supplier pools to REACH-registered processors with documented supply chain controls. Bavarian distribution networks are consolidating procurement around multi-year offtake agreements with Indian distillation clusters.
United States
North American nutraceutical brands in New Jersey and California establish direct contracting relationships with Uttar Pradesh processors to bypass traditional broker intermediation. FDA GRAS self-affirmation requirements and EPA pesticide residue limits shape import eligibility for therapeutic-grade and food-grade shipments. Chicago and Los Angeles distribution hubs are digitizing traceability infrastructure to compress certification cycles.
France
Robertet Group leverages captive cultivation in Grasse to sustain pharmaceutical-grade consistency for European fragrance and therapeutic markets. ANSM and ECHA purity benchmarks for food-grade and therapeutic-grade batches are tightening residual solvent limits ahead of EMA regulatory revisions. Provence-Alpes-Côte d'Azur fragrance houses are reformulating product lines to preempt compliance gaps in aromatherapy distribution.
Switzerland
Swissmedic standards and Swiss aromatherapy distributors anchor specialty channel procurement through Ultra International B.V. and comparable channel controllers mandating REACH registration. Basel and Zurich pharmaceutical networks require real-time carvone quantification for irritable bowel syndrome formulation eligibility. Geneva-based wellness retailers are shifting sourcing toward organic-certified suppliers with blockchain traceability documentation.
Spearmint Oil Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply tiers, with automated distillation capabilities separating pharmaceutical-grade operators from commodity-positioned legacy processors. The vendor base clusters around three strategic archetypes: backward-integrated Indian bulk exporters with contract farming networks, European fragrance houses with captive cultivation assets, and North American direct-to-consumer wellness brands with digital traceability infrastructure. Dominant competitive moves include multi-year offtake agreements displacing spot purchasing, and near-infrared spectroscopy deployment compressing certification timelines from weeks to hours.
Within the backward-integrated bulk export tier, AOS Products Pvt. Ltd. and Arora Aromatics Pvt. Ltd. represent Indian processors with Uttar Pradesh and Madhya Pradesh contract farming exposure. Ultra International B.V. occupies a position among European channel controllers anchoring aromatherapy distribution through REACH-registered supply chain mandates. Robertet Group exemplifies the captive cultivation archetype with French agricultural assets sustaining pharmaceutical-grade consistency for therapeutic and fragrance applications.
| Leading Market Players |
|---|
| AOS Products Pvt. Ltd. |
| Ultra International B.V. |
| Berje Inc. |
| doTERRA International |
| Young Living Essential Oils |
| Biolandes |
| Synthite Industries Ltd. |
| Robertet Group |
| Arora Aromatics Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Uttar Pradesh and Madhya Pradesh distillation clusters concentrate Mentha spicata biomass supply for global pharmaceutical and flavor houses, anchoring margin capture downstream among REACH-registered processors with automated certification capabilities. This upstream concentration funnels pricing power toward backward-integrated operators while squeezing legacy batch processors into commodity crude oil tiers.
Pricing Analysis
Automated steam distillation systems command premium positioning against legacy batch equipment, with pharmaceutical-grade essential oils pricing at substantial spreads over crude oils sold into industrial fragrance blending. Price differentiation rests on carvone concentration certification and EMA monograph compliance, with German and Swiss pharmaceutical formulators least sensitive to unit cost. Pricing pressure intensifies in crude oil tiers where synthetic carvone from petrochemical feedstocks exerts substitution pressure, while food-grade concentrates face FSSAI compliance cost layering without corresponding price recovery.
Supply Chain Analysis
Single-geography dependency on Indian menthol-aromatics belt cultivation creates supply chain risk from monsoon-dependent yield volatility across the Indo-Gangetic plain. Raw material flows draw from contract farming networks in Uttar Pradesh and Madhya Pradesh, with Mentha spicata biomass and steam distillation equipment as critical inputs. Distribution runs through direct contracting between North American nutraceutical brands and Indian processors, displacing traditional broker intermediation and concentrating volume among BIS-certified operators with captive laboratory infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain traceability and near-infrared spectroscopy are converging to create platform-economics dynamics in spearmint oil certification, with interoperability between Indian distillation data and European pharmaceutical buyer systems reshaping competitive access.
For Market Incumbents: Build regulatory certification moats through captive BIS laboratory infrastructure and REACH registration maintenance. AOS Products Pvt. Ltd. and comparable backward-integrated processors should deepen upstream control over contract farming networks to defend against synthetic carvone substitution in industrial tiers. Priority investment targets automated distillation systems that compress certification cycles from weeks to hours for German and Swiss pharmaceutical formulators.
For New Entrants and Emerging Players: North American stress-relief and sleep-aid nutraceutical channels represent underpenetrated white space beyond established digestive health applications. New entrants should target direct-to-consumer wellness platforms with organic-certified positioning and provenance storytelling, leveraging e-commerce fragmentation to bypass wholesale channel concentration. Go-to-market execution should emphasize blockchain traceability documentation as a competitive differentiator.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed Indian processors lacking pharmaceutical-grade automation but holding established contract farming networks. Long-term viability hinges on capital deployment for near-infrared spectroscopy integration and EMA compliance infrastructure. The signal to watch is FDA GRAS self-affirmation pathway streamlining for compliant exporters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Captive Mentha spicata supply secures raw material cost advantages against monsoon volatility. |
| Near-Infrared Spectroscopy Deployment | Real-time carvone quantification compresses certification cycles for German pharmaceutical buyers. |
| REACH Registration Completion | EMA monograph compliance filters supplier pools to registered processors with documented controls. |
| Direct-to-Consumer Channel Launch | E-commerce wellness platforms fragment purchasing toward organic-certified provenance positioning. |
| Blockchain Traceability Implementation | Digitized batch certification meets Swiss aromatherapy distributor documentation mandates. |
Study Parameters
Desk research of customs trade data, FSSAI regulatory filings, and EMA herbal medicinal product monographs preceded structured interviews with distillation plant managers, pharmaceutical procurement leads at German formulators, Indian contract farming network coordinators, and European aromatherapy channel controllers. Primary fieldwork across Uttar Pradesh and Madhya Pradesh distillation clusters validated secondary estimates of automated versus batch-processing capacity splits. Bottom-up volume triangulation from processor output data converged with top-down demand aggregation across pharmaceutical, food, and aromatherapy end uses.
Forecast assumptions held regulatory stringency trajectories constant across the projection horizon, with EMA residual solvent limits and FDA GRAS requirements modeled at current enforcement intensity. Segmentation dimensions included product grade tier, application category, distribution channel structure, and regional regulatory cluster. CAGRs derived from logistic growth curve fitting to historical volume data, with pharmaceutical-grade essential oil expansion rates calibrated against irritable bowel syndrome formulation pipeline disclosures. Input variables incorporated Mentha spicata yield sensitivity to Indo-Gangetic plain precipitation patterns.
The forecast holds incumbent behavior within observed patterns; aggressive automation investment by legacy batch processors or rapid synthetic carvone cost reduction would shift volume and pricing outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
United States Aroma Chemicals Market
Flavor and Fragrance Chemicals
Peel Oil Market
Flavor and Fragrance Chemicals
North America Aroma Chemicals Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Bio-Based Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Flavor and Fragrance Market
Flavor and Fragrance Chemicals
Fragrance Fixatives Market
Flavor and Fragrance Chemicals
Europe Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Global Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Deodorization Systems Market
Flavor and Fragrance Chemicals
Global Natural Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Middle East and Africa Aroma Chemicals Market
Flavor and Fragrance Chemicals
Camphor Market
Flavor and Fragrance Chemicals
Semiochemicals Market