
 Essential Oils Market | 2026-2036
Essential Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Essential Oils Market Analysis
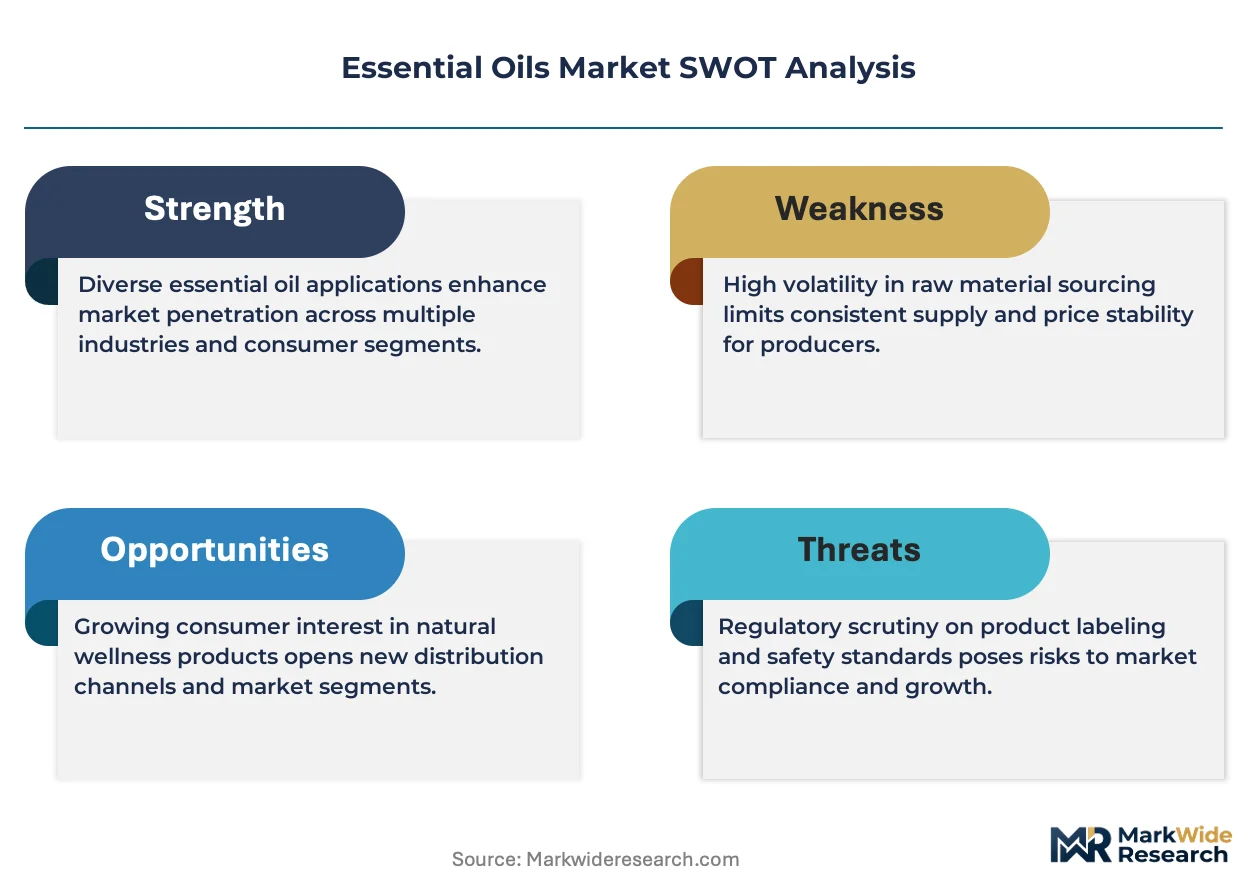
Pharmaceutical formulators is unwinding the historical dominance of perfumery houses as the primary volume buyer in the essential oils trade. Givaudan leverages captive botanical sourcing across multiple continents to secure raw material consistency. Robertet SA anchors its position through deep specialization in jasmine and rose absolutes from Grasse. Symrise competes by controlling extraction technology for high-purity terpene isolates.
Essential oils are volatile aromatic compounds extracted from plant material through steam distillation, cold pressing, or solvent extraction, with terpene profiles and specific gravity serving as critical quality benchmarks; these oils function as active ingredients in therapeutic, flavoring, and fragrance applications. Single oils command the largest revenue pool due to their use as pharmaceutical-grade raw materials, while CO2 extracts represent the fastest-growing product type because supercritical extraction preserves heat-sensitive bioactives for nutraceutical use. Aromatherapy applications retain mature volume, but food and beverage grade oils capture expanding margin pools as clean-label flavoring demand intensifies.
REACH in Europe mandates full toxicological dossiers for imported botanical extracts, while the FDA's GRAS notification process governs food-grade oil approvals in the United States; India's FSSAI has tightened pesticide residue limits for oils entering the packaged food channel. ISO 4720 standards provide the analytical backbone for international trade arbitration on oil authenticity. Stakeholders must monitor regulatory divergence between pharmaceutical-grade and cosmetic-grade purity thresholds as classification decisions reshape addressable market boundaries.
Market Dynamics
Pharmaceutical formulators now outpace perfumery houses as volume buyers, tightening purity benchmarks through REACH compliance in Europe and FDA GRAS determinations in the United States while cultivation clusters deepen in France, India, and the United States.
Growth Catalysts
- REACH toxicological dossiers:Europe's full disclosure mandates for imported botanical extracts are filtering out adulterated supply, concentrating demand on verified producers with analytical capabilities.
- Clean-label flavoring:Food and beverage manufacturers are substituting synthetic additives with food-grade essential oils, expanding margin pools beyond traditional aromatherapy applications.
- Supercritical CO2 extraction:This technology preserves heat-sensitive bioactives for nutraceutical formulations, unlocking pharmaceutical-grade applications that steam distillation cannot address.
Market Restraints
- Climate-dependent raw material costs:Lavender, tea tree, and citrus crops face yield volatility from drought cycles in Mediterranean and subtropical growing zones, compressing processor margins.
- Grasse jasmine and rose concentration:Premium absolutes rely on a narrow geographic band in southern France, creating single-source vulnerability for high-end fragrance houses.
- Synthetic terpene substitution:Laboratory-produced limonene and linalool undercut natural oil pricing in industrial fragrance and cleaning product formulations.
Strategic Opportunities
- Indian packaged food channel:FSSAI pesticide residue enforcement is disqualifying informal suppliers, creating entry space for certified exporters with traceable supply chains.
- Nutraceutical encapsulation:Liposomal and nanoemulsion delivery systems are expanding bioavailability claims for essential oil supplements in functional food applications.
- CE marking harmonization:Convergence of cosmetic and pharmaceutical-grade standards in Europe is enabling dual-use certification that unlocks cross-segment sales.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography-mass spectrometry interpretation for terpene profiling requires specialized talent that distillation facilities struggle to retain.
- ISO 4720 certification timelines:Authenticity arbitration standards demand multi-year analytical libraries that small-batch producers cannot finance.
- Legacy steam distillation retrofit:Converting conventional stills for organic certification compliance requires capital outlays that family-owned operations defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Essential Oils Market |
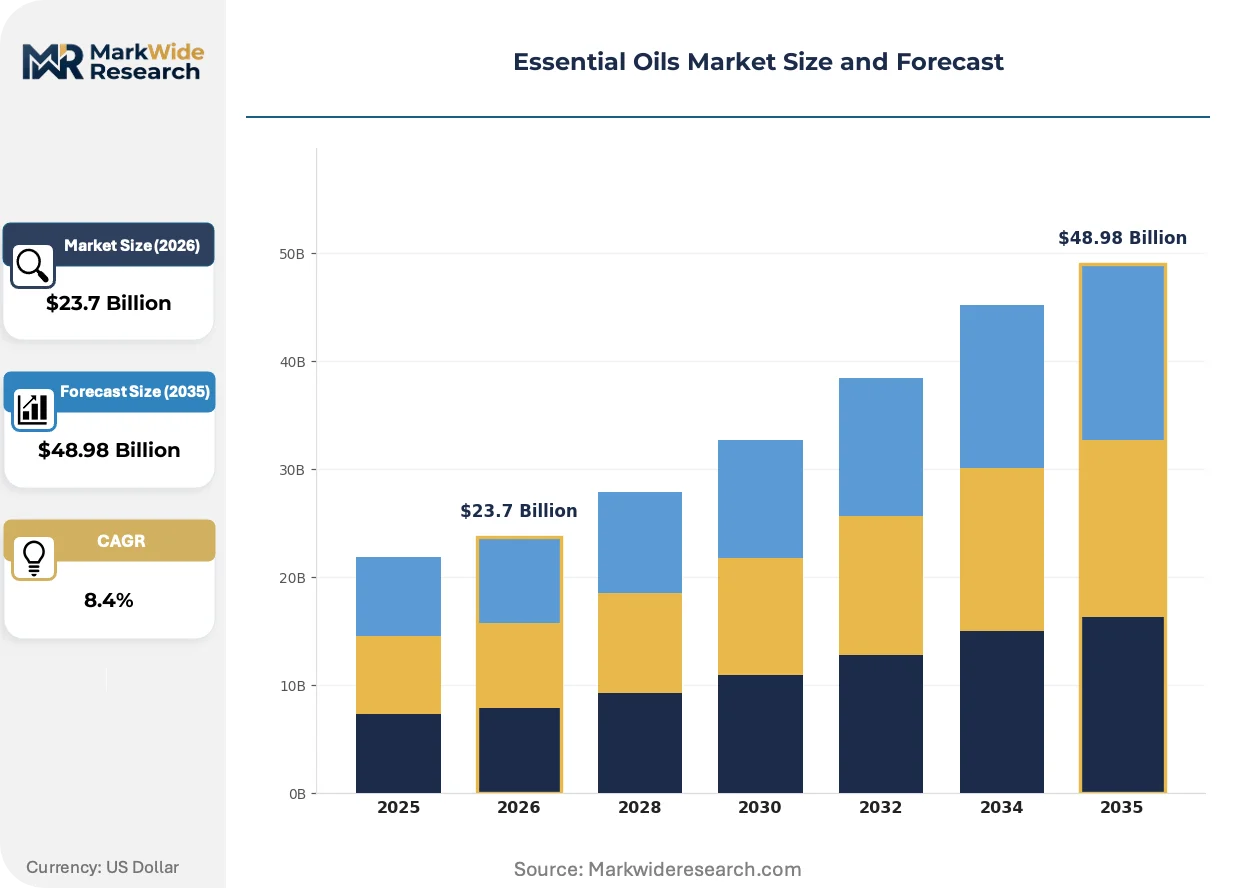
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Oils, Blends, Absolutes, CO2 Extracts Application: Aromatherapy, Personal Care, Food & Beverage, Cleaning Products Delivery Mode: Topical, Inhalation, Diffusers, Oral End User: Retail Consumers, Spa & Wellness Centers, Food Manufacturers, Pharmaceuticals |
| Companies Covered | doTERRA, Young Living Essential Oils, Givaudan, Symrise, International Flavors & Fragrances Inc., Robertet SA, Sensient Technologies Corporation, MANE, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Essential Oils Market Emerging Trajectories
Extraction technology and regulatory classification are actively restructuring competitive advantage, separating producers with pharmaceutical-grade capabilities from commodity fragrance suppliers.
Supercritical CO2 extraction is bifurcating the market between heat-sensitive bioactive preservation and conventional steam-distilled output. Nutraceutical formulators are adopting CO2 extracts at accelerated pace for omega-fatty acid and antioxidant retention. This technology is compressing margins for traditional distillers while enabling premium pricing for certified clean-label supply.
REACH substance registration is tightening toxicological disclosure requirements for botanical imports into Europe. Full dossier preparation costs are excluding small-scale exporters from the pharmaceutical channel. Indian and Moroccan suppliers are responding by consolidating through third-party testing laboratories to share compliance burdens.
Buyer concentration among pharmaceutical formulators is shortening qualification cycles for new oil suppliers. Direct procurement contracts are displacing traditional broker networks for high-volume terpene isolates. This pattern is most visible in United States generic drug manufacturing, where API producers now audit distillation facilities directly rather than relying on trader certifications.
Essential Oils Market Segmentation
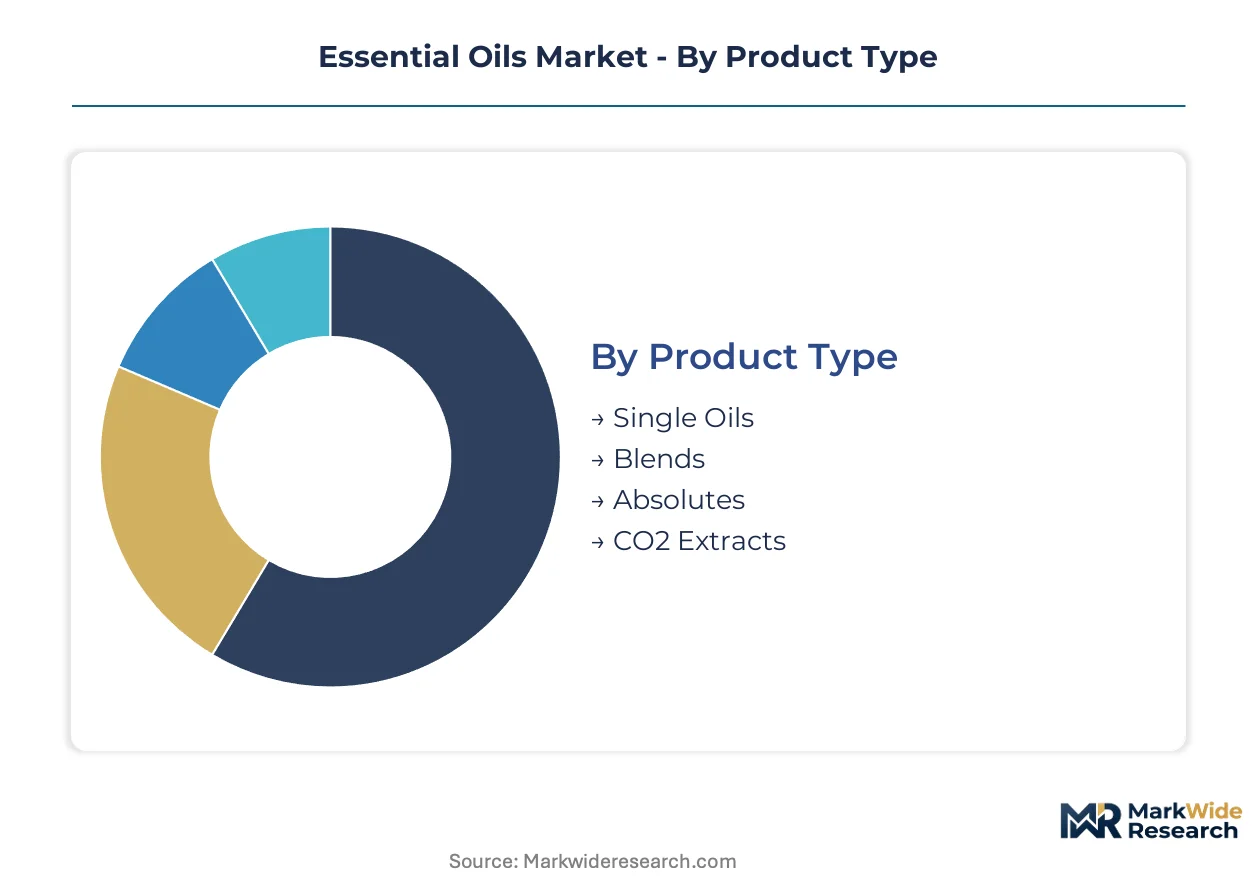
Essential oils segmentation reflects divergent purity thresholds across regulatory channels. Pharmaceutical-grade specifications, cosmetic-grade tolerances, and food-grade safety benchmarks each demand distinct analytical dossiers and extraction protocols.
Product Type:
REACH dossier requirements in Europe and FDA GRAS determinations in the United States split this category into pharmaceutical-track and fragrance-track supply chains.
- Single Oils:Distilled or cold-pressed essences from single botanical species with defined terpene profiles and specific gravity ranges. Pharmaceutical formulators in the United States source single oils for API manufacturing, tightening certificate-of-analysis requirements beyond cosmetic-grade tolerances.
- CO2 Extracts:Supercritical carbon dioxide extraction preserves heat-sensitive bioactives that steam distillation degrades. Nutraceutical manufacturers in Germany and Switzerland adopt CO2 extracts for omega-fatty acid retention, commanding premium pricing over conventional distillates.
- Blends:Proprietary combinations of multiple single oils formulated for specific therapeutic or fragrance profiles.
- Absolutes:Solvent-extracted aromatic concentrates from delicate flowers such as jasmine and rose, primarily serving high-end fragrance houses in France.
Single oils handle the majority of throughput; CO2 extracts are climbing the fastest on share.
Application:
Margin structures vary sharply across end-use channels, with food-grade certification commanding the steepest compliance premiums.
- Food & Beverage:Clean-label flavoring applications substitute synthetic additives with GRAS-notified essential oils. Beverage manufacturers in India face FSSAI pesticide residue limits that disqualify informal suppliers, concentrating demand on certified exporters with traceable cultivation chains.
- Aromatherapy:Diffuser and massage applications represent mature volume with established ISO 4720 authenticity standards. Spa chains in France and the United States source certified organic oils, though price compression from synthetic terpene alternatives limits margin expansion.
- Personal Care:Cosmetic formulations incorporate essential oils for fragrance and claimed therapeutic benefits.
- Cleaning Products:Industrial and household formulations utilize citrus and pine oils for antimicrobial positioning and natural marketing claims.
Aromatherapy handles the majority of throughput; food and beverage applications are expanding most quickly on share.
Delivery Mode:
Route of administration determines regulatory jurisdiction and toxicological testing burden.
- Oral:Capsule, softgel, and emulsion formats for nutraceutical absorption. Liposomal delivery systems in United States functional food applications expand bioavailability claims, requiring novel excipient approvals.
- Topical:Dermal application through carrier oil formulations for massage and skincare.
- Inhalation:Direct respiratory exposure through personal inhalers and steam applications.
- Diffusers:Ultrasonic and nebulizing devices for ambient aromatic dispersion.
Topical formats handle the majority of throughput; oral delivery is gaining share fastest.
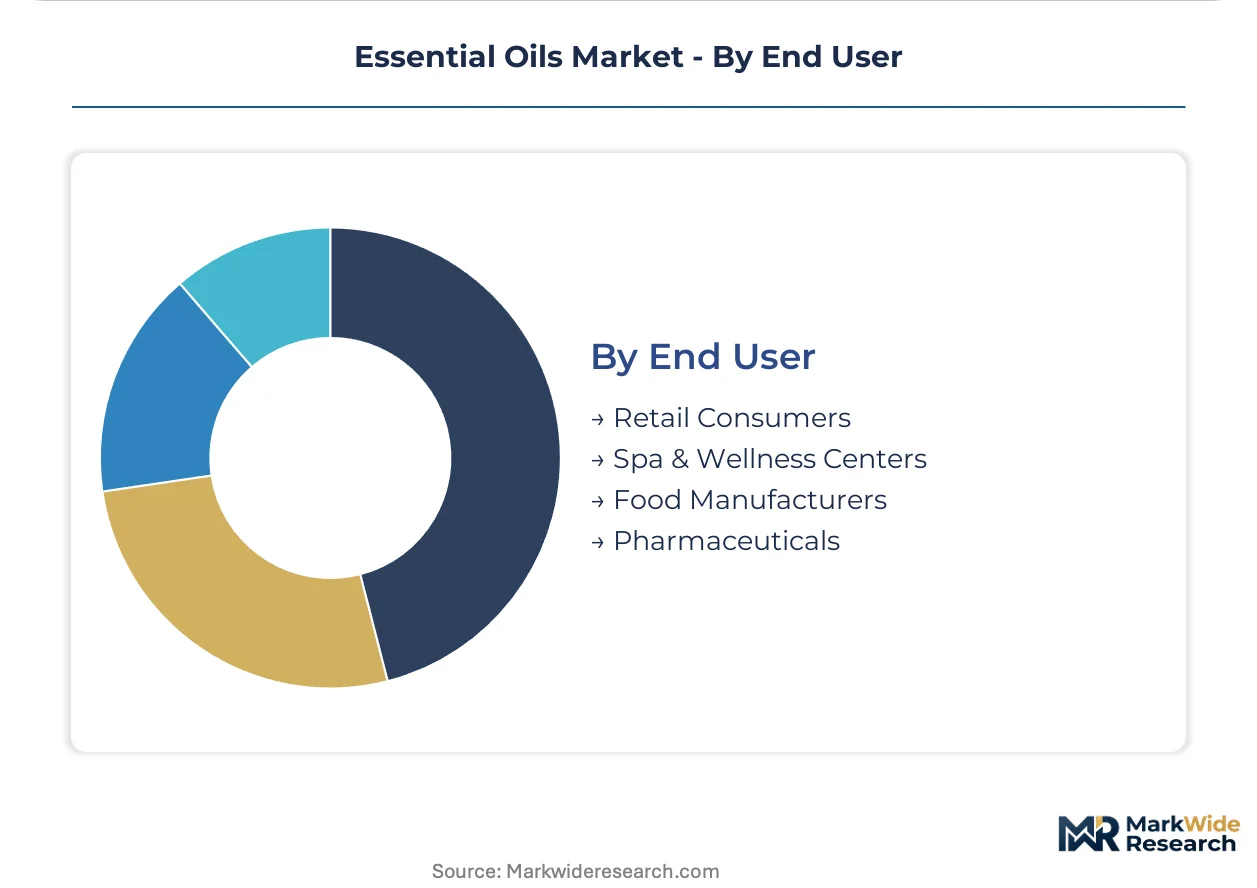
End User:
Procurement sophistication separates institutional buyers from retail channels, with direct auditing replacing broker networks.
- Pharmaceuticals:API manufacturers and finished dose formulators source terpene isolates under direct facility audit protocols. Generic drug producers in the United States now qualify distillation operations personally rather than relying on trader certifications, shortening supplier onboarding cycles.
- Food Manufacturers:Packaged goods producers integrate essential oils for natural flavoring claims.
- Spa & Wellness Centers:Service providers purchase bulk oils for treatment applications.
- Retail Consumers:Individual purchasers through e-commerce and specialty retail channels.
Retail consumers handle the majority of throughput; pharmaceutical buyers are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulators in the United States, France, and India now drive faster procurement cycles than traditional fragrance houses, tightening purity benchmarks through direct facility audits and traceable cultivation requirements.
United States
Generic drug manufacturers source terpene isolates under shortened supplier qualification cycles. FDA GRAS determinations govern food-grade oil approvals, creating compliance premiums for clean-label flavoring applications. Cultivation clusters in California and Florida deepen distillation infrastructure for citrus and mint oils.
France
High-end fragrance houses anchor demand for jasmine and rose absolutes from Grasse. ANSM cosmetic-grade standards intersect with REACH substance registration, raising toxicological disclosure costs for imported botanicals. The Provence-Alpes-Côte d'Azur region concentrates solvent-extraction expertise for delicate flower essences.
India
Packaged food manufacturers substitute synthetic additives with certified essential oils for export markets. FSSAI pesticide residue limits disqualify informal suppliers, concentrating demand on traceable cultivation chains. Maharashtra and Karnataka deepen organic certification infrastructure for mint, lemongrass, and spice oils.
Germany
Nutraceutical formulators adopt CO2 extracts for omega-fatty acid retention in functional food applications. ECHA REACH dossier mandates filter out adulterated supply, favoring producers with gas chromatography-mass spectrometry capabilities. Bavaria hosts supercritical extraction technology providers serving pharmaceutical-grade channels.
Switzerland
Swissmedic pharmaceutical-grade standards enable dual-use certification for cosmetic and therapeutic applications. Precision flavoring houses source terpene isolates under direct audit protocols rather than broker networks. The Basel region concentrates encapsulation technology for liposomal essential oil delivery systems.
Essential Oils Market Vendor Landscape
Player mix skews toward integrated botanical specialists with captive sourcing and analytical capabilities. The vendor base separates into three tiers: multinational flavor houses with global extraction networks, regional distillers with organic certification, and direct-to-consumer wellness brands with subscription distribution. Consolidation concentrates among fragrance-track suppliers seeking pharmaceutical-grade capabilities, while fragmentation persists in aromatherapy retail. Competitive moves center on backward integration into cultivation and third-party laboratory partnerships for REACH dossier preparation.
Within the integrated specialist tier, Givaudan and Robertet SA exemplify divergent sourcing strategies. Givaudan leverages captive botanical operations across multiple continents to secure raw material consistency for high-volume terpene isolates. Robertet SA anchors its market position through deep specialization in jasmine and rose absolutes from Grasse, occupying a position at the premium fragrance intersection. Symrise sits within the technology-driven segment, representing competitive positioning through extraction expertise for heat-sensitive bioactives.
| Leading Market Players |
|---|
| doTERRA |
| Young Living Essential Oils |
| Givaudan |
| Symrise |
| International Flavors & Fragrances Inc. |
| Robertet SA |
| Sensient Technologies Corporation |
| MANE |
| Cargill, Incorporated |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between pharmaceutical formulators and distillation facilities lock in multi-year supply access while anchoring price visibility against volatile lavender and citrus crop yields. These arrangements concentrate procurement power among API manufacturers in the United States and Germany, squeezing margin flexibility for family-owned distillers in France and India.
Pricing Analysis
Cost-plus contracts with agricultural commodity indexation dominate raw material sourcing for bulk terpene isolates. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and food-grade certification levels reflects compliance burden differentials, with FDA GRAS and REACH dossier preparation costs compressing margins at the premium tier. Price erosion runs through commodity fragrance channels as synthetic terpene alternatives undercut natural oil pricing. Food manufacturers in India exhibit highest price sensitivity due to FSSAI enforcement costs, while Swiss nutraceutical formulators accept premium positioning for CO2 extract bioavailability claims.
Supply Chain Analysis
France and India anchor cultivation clusters for jasmine, rose, mint, and lemongrass oils, while the United States deepens citrus and peppermint distillation infrastructure in California and Florida. Processor operations draw from climate-dependent botanical inputs, specialized solvent-extraction equipment, and gas chromatography-mass spectrometry testing capabilities. Single-source vulnerability concentrates in Grasse for premium absolutes, exposing fragrance houses to geographic disruption. Distribution runs through direct procurement contracts displacing traditional broker networks, with pharmaceutical buyers auditing facilities personally rather than relying on trader certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pharmaceutical formulators and generic drug manufacturers, fragmenting traditional fragrance house dominance and shortening supplier qualification cycles across the essential oils trade.
For Market Incumbents: Compound analytical capabilities through captive gas chromatography-mass spectrometry laboratories to defend against REACH dossier preparation cost escalation. Secure backward integration into organic-certified cultivation clusters in Maharashtra and Karnataka to lock in traceable supply chains as FSSAI pesticide enforcement intensifies. Channel control through direct procurement contracts with United States API manufacturers replaces broker network dependency. For New Entrants and Emerging Players: Anchor in the Indian packaged food channel where FSSAI certification requirements disqualify informal suppliers, creating white-space entry for traceable exporters. Target nutraceutical encapsulation partnerships with German and Swiss formulators seeking liposomal delivery system suppliers. Pursue third-party testing laboratory joint ventures to share REACH compliance burdens among small-batch producers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated specialists with captive botanical sourcing and multi-segment certification capabilities. Five-to-ten year viability favors distillation operations with pharmaceutical-grade infrastructure and direct pharmaceutical buyer relationships. Watch for inflection signals in CE marking harmonization enabling dual-use cosmetic-pharmaceutical certification that unlocks cross-segment sales expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive organic-certified supply chains in India and France secure raw material consistency against climate volatility. |
| Supercritical CO2 Extraction Capacity Addition | Bavaria-based technology providers enable pharmaceutical-grade bioactive preservation for German nutraceutical formulators. |
| Third-Party Testing Laboratory Partnership | Moroccan and Indian suppliers share REACH toxicological dossier preparation costs to maintain European market access. |
| Direct Procurement Contract Expansion | United States generic drug manufacturers shorten supplier onboarding through personal facility audits replacing trader certifications. |
| Dual-Use Certification Investment | CE marking harmonization across cosmetic and pharmaceutical grades unlocks cross-segment sales in European markets. |
Methodological Framework
A standing panel of distillation facility operators, pharmaceutical procurement managers, fragrance house sourcing directors, and FSSAI compliance officers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from ECHA substance registration databases, FDA GRAS notification filings, ISO 4720 analytical standards documentation, and customs trade flow records. Bottom-up capacity assessments at cultivation clusters in France, India, and the United States triangulated against top-down demand modeling across pharmaceutical, food-grade, and aromatherapy channels.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, application channel, delivery mode, and end-user procurement sophistication. CAGRs were derived from regression analysis of historical price-volume relationships and forward-looking regulatory compliance cost trajectories. Forecast inputs incorporated climate yield volatility patterns for Mediterranean and subtropical growing zones alongside supercritical extraction technology adoption curves in nutraceutical formulations.
Material uncertainties — regulatory divergence between pharmaceutical-grade and cosmetic-grade purity thresholds, synthetic terpene substitution acceleration, and drought cycle frequency in key cultivation zones — sit outside the modeled envelope. Forecasts reflect assumptions about REACH dossier cost trajectories and FSSAI enforcement intensity that could revise projections if regulatory timelines shift. Recalibration cycles align with material shifts in ECHA substance registration requirements and FDA GRAS determination precedents.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Fragrance Fixatives Market
Flavor and Fragrance Chemicals
Europe Essential Oils Market
Flavor and Fragrance Chemicals
Natural Fragrance Chemicals Market
Flavor and Fragrance Chemicals
Essential Oil Blends Market
Flavor and Fragrance Chemicals
3-Methyl Valeric Acid Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Neryl Acetate Market
Flavor and Fragrance Chemicals
Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Global Natural Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Dihydrocitronellol Market
Flavor and Fragrance Chemicals
Linalool Market
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
Global Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Fragrance Wax Melts Market