
 Peppermint Leaf Powder Market | 2026-2036
Peppermint Leaf Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Peppermint Leaf Powder Market Analytics
Pharmaceutical formulators is bifurcating demand away from traditional food-grade buyers as enteric coating and irritable bowel syndrome therapeutics require higher-purity botanical inputs. Mountain Rose Herbs Inc. leverages its vertically integrated organic supply chain to command premium positioning in certified ingredient channels. Saipro Biotech Private Limited anchors its competitive stance through concentrated freeze-dried output tailored to nutraceutical encapsulation. Varmora Foods Pvt. Ltd. competes on scale, operating bulk conventional milling infrastructure that serves mass-market tea and confectionery manufacturers.
Peppermint leaf powder consists of dried Mentha piperita leaves ground to particle sizes typically ranging from 40 to 80 mesh, retaining 1.0–2.5% essential oil content by weight for standard grades and up to 3.5% for premium pharmaceutical lots; manufacturers employ cryogenic or ambient milling followed by steam treatment to stabilize volatile compounds for flavor and therapeutic applications. Organic product type commands the widest margin pool as certification costs and crop rotation requirements constrain supply expansion, while freeze-dried formats capture accelerating demand from functional beverage startups seeking solubility advantages over conventional air-dried material. Dietary supplements application leads volume absorption through capsule and tablet demand, though cosmetics application registers the fastest trajectory as Korean and French formulators incorporate peppermint powder into scalp and oral care lines.
USDA organic standards enforce lot traceability and prohibited substance screening that shapes supplier qualification timelines for North American market access, while EFSA novel food assessments govern European incorporation into fortified products. India's FSSAI and CDSCO maintain parallel quality benchmarks for domestic ayurvedic and pharmaceutical use, creating dual compliance burdens for exporters. Stakeholders must monitor evolving pesticide maximum residue limits across importing jurisdictions and pre-position solvent-free extraction partnerships before regulatory deadlines compress sourcing flexibility.
Market Dynamics
Pharmaceutical formulators are diverting procurement toward enteric-coated formulations requiring higher-purity peppermint leaf powder, compressing traditional food-grade supply channels and rewiring supplier qualification timelines around certification tiers.
Growth Catalysts
- Enteric Coating Demand:Pharmaceutical manufacturers require peppermint leaf powder with elevated essential oil retention for irritable bowel syndrome therapeutics, pulling supply away from confectionery buyers.
- USDA Organic Certification:Tightening traceability standards for botanical raw materials are locking in premium pricing for certified suppliers who meet lot-level documentation requirements.
- Contract Farming Networks:India's organized cultivation clusters supply bulk dried leaf to European extractors, anchoring volume concentration in Madhya Pradesh and Uttar Pradesh growing belts.
Market Restraints
- Input Cost Volatility:Mentha piperita essential oil prices fluctuate with monsoon patterns and pest pressure, squeezing margin predictability for air-dried powder processors.
- Supply Concentration Risk:European pharmaceutical formulators depend on Indian bulk leaf exports, exposing procurement to FSSAI export clearance delays and DGFT phytosanitary holdups.
- Technical Limitation:Ambient milling degrades volatile compound stability below pharmaceutical thresholds, forcing capital-intensive cryogenic infrastructure investments.
Strategic Opportunities
- Functional Beverage Startups:Freeze-dried peppermint powder offers solubility advantages over conventional air-dried material, opening formulation partnerships with ready-to-drink tea innovators.
- Cosmetics Application Expansion:Korean and French formulators are incorporating peppermint powder into scalp and oral care lines, creating demand for micronized particle grades below 60 mesh.
- EFSA Novel Food Pathway:European fortification approvals for botanical ingredients in fortified foods create first-mover positioning for suppliers completing safety dossiers.
Industry Challenges
- Certification Timeline Compression:USDA organic lot traceability requirements and EFSA novel food assessments run in parallel, stretching supplier compliance teams across dual documentation tracks.
- Cryogenic Milling Capex Intensity:Pharmaceutical-grade volatile retention requires in-house liquid nitrogen infrastructure, blocking mid-scale entrants from premium segment participation.
- Pesticide Residue Screening:Evolving maximum residue limits across importing jurisdictions demand pre-positioned solvent-free extraction partnerships before regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peppermint Leaf Powder Market |
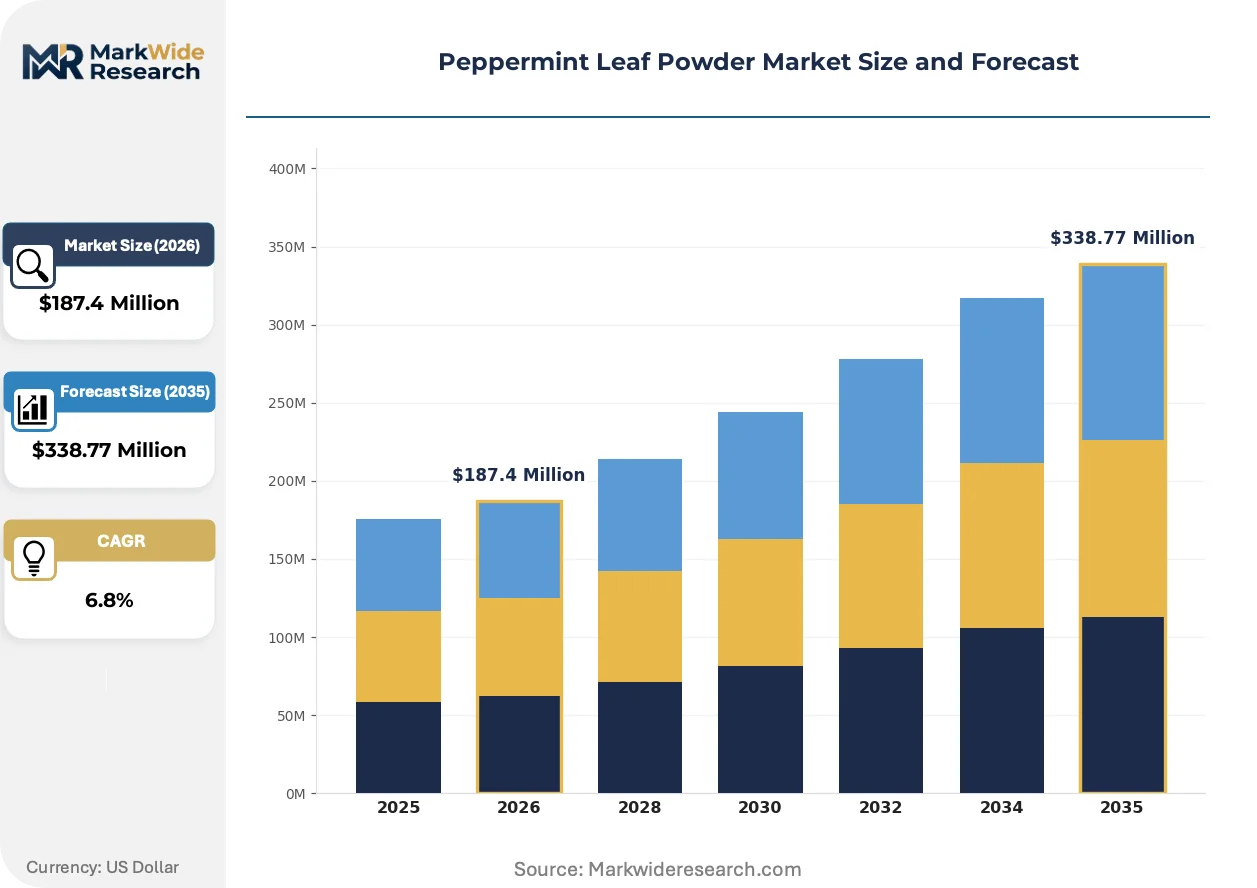
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Freeze-Dried, Raw Application: Food & Beverage, Cosmetics, Pharmaceuticals, Dietary Supplements End User: Food Manufacturers, Cosmetic Companies, Retailers, Health Practitioners Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Mountain Rose Herbs Inc., Adams Fairacre Farms, Austral Herbs Pty Ltd., The Green Labs LLC, Saipro Biotech Private Limited, Varmora Foods Pvt. Ltd., SM Heena Industries, PentaPure Foods, National Food ‘n’ species, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peppermint Leaf Powder Market Evolving Landscape
Processing technology and certification protocols are restructuring competitive positioning in peppermint leaf powder, with freeze-drying and cryogenic milling compressing traditional air-dried supply chains while regulatory divergence fragments market access pathways.
Cryogenic milling systems using liquid nitrogen cooling are preserving essential oil content above pharmaceutical thresholds. Dietary supplement contract manufacturers in North America and Western Europe are retrofitting ambient facilities at accelerated pace. This capital shift is miniaturizing the addressable market for conventional air-dried grades while concentrating volume in certified cryogenic channels.
EFSA novel food assessments for botanical fortification are tightening safety dossier requirements for peppermint incorporation into fortified products. European food manufacturers face extended approval timelines that compress formulation flexibility. Freeze-dried powder suppliers with completed toxicology packages are capturing preferred supplier status ahead of pending regulatory deadlines.
Direct procurement from contract farming networks is displacing layered trader intermediaries for pharmaceutical-grade material. Nutraceutical encapsulators in Germany and France are establishing annual offtake agreements with Indian organic cooperatives. This channel consolidation is most visible in certified organic supply chains where lot traceability requirements render traditional spot-market purchasing structurally inadequate.
Peppermint Leaf Powder Market Segmentation
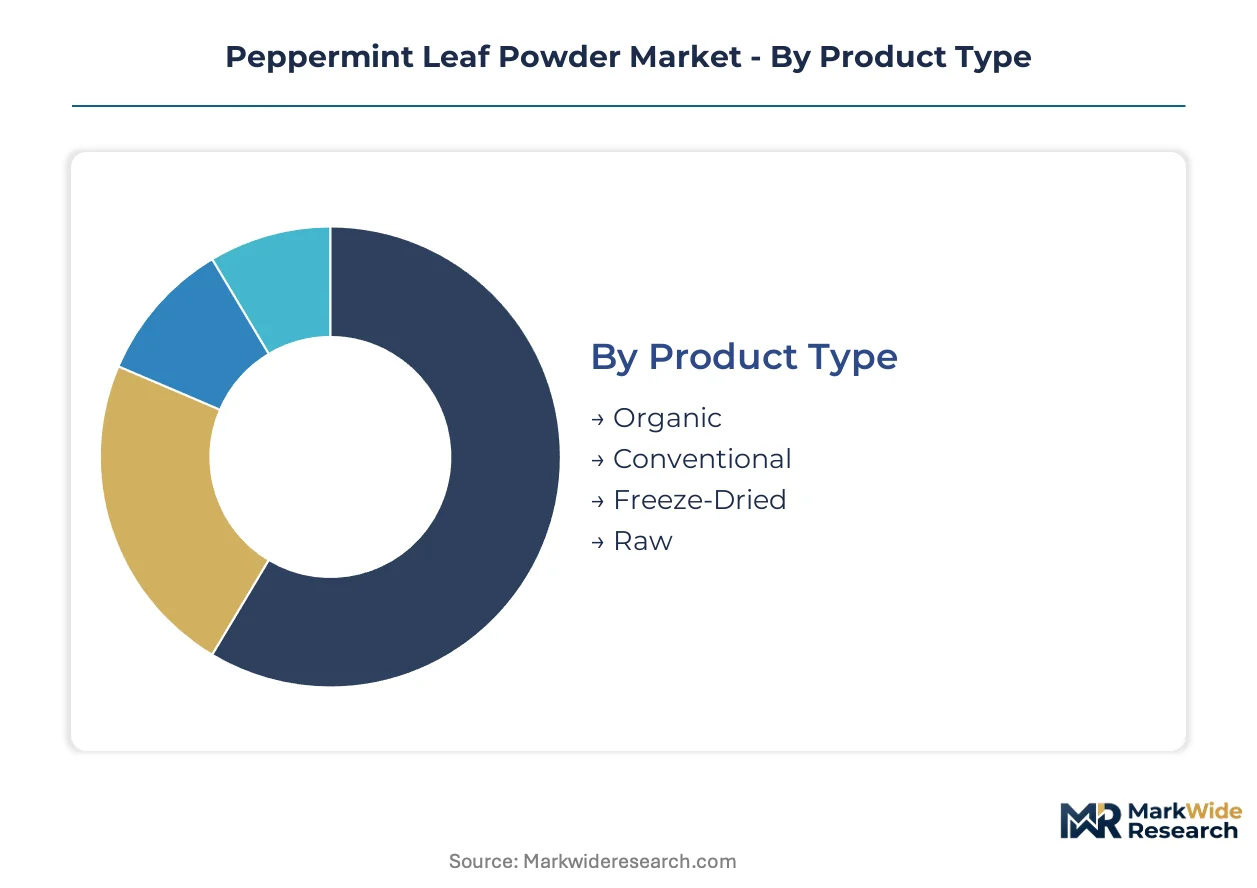
Peppermint leaf powder procurement splits sharply across certification tiers and processing methods, with pharmaceutical and nutraceutical buyers commanding premium specifications that conventional food-grade channels cannot satisfy. Segmentation discipline reveals where capital deployment and compliance investments yield sustainable margin capture.
Product Type:
Margin pools concentrate in certified organic and freeze-dried formats where supply constraints and technical barriers protect pricing power against commodity-grade competition.
- Organic:USDA certification mandates lot-level traceability and prohibited substance screening that extends supplier qualification timelines. German and French nutraceutical encapsulators now require annual offtake agreements with Indian organic cooperatives in Madhya Pradesh to secure pipeline visibility ahead of EFSA novel food deadlines.
- Freeze-Dried:Sublimation processing preserves essential oil content above 3.0% while delivering solubility advantages for functional beverage formulations. Ready-to-drink tea startups in South Korea and California are retrofitting procurement specifications to exclude conventional air-dried material entirely.
- Conventional:Ambient milling infrastructure serves mass-market tea and confectionery manufacturers at scale, though margin compression from volatile Mentha piperita oil prices limits reinvestment capacity.
- Raw:Unprocessed dried leaf moves through trader intermediaries to European extractors seeking solvent-free extraction partnerships for pharmaceutical-grade downstream processing.
The dominant share belongs to Conventional, while Freeze-Dried is closing the gap fastest.
Application:
Volume absorption patterns diverge between mature food channels and emerging therapeutic uses, with cosmetics formulators driving specification upgrades that ripple upstream to milling technology decisions.
- Dietary Supplements:Capsule and tablet demand anchors volume absorption through North American contract manufacturers. CDSCO-aligned Indian exporters face dual compliance burdens from FSSAI domestic benchmarks and FDA import alerts on pesticide residue screening.
- Cosmetics:Korean scalp care and French oral care lines incorporate micronized grades below 60 mesh, forcing particle size specifications that ambient milling cannot achieve. ANSM and KBA cosmetic safety assessments are tightening botanical ingredient documentation requirements.
- Pharmaceuticals:Enteric-coated irritable bowel syndrome therapeutics require cryogenic-milled powder with essential oil retention above pharmaceutical thresholds, concentrating procurement among vertically integrated suppliers with in-house liquid nitrogen infrastructure.
- Food & Beverage:Confectionery and tea applications absorb residual conventional supply as pharmaceutical formulators divert higher-purity material, compressing traditional food-grade channels.
Dietary Supplements commands the largest volume position, though Cosmetics exhibits the steepest expansion trajectory.
End User:
Customer sophistication tiers determine pricing realization, with health practitioners and cosmetic companies accepting certification premiums that food manufacturers resist.
- Cosmetic Companies:Korean and French formulators specify micronized particle grades and completed toxicology packages, capturing preferred supplier status ahead of regulatory deadlines through direct procurement from Indian organic cooperatives.
- Health Practitioners:Ayurvedic and integrative medicine channels in India and Germany absorb premium organic powder for therapeutic protocols, requiring lot traceability that spot-market purchasing cannot satisfy.
- Food Manufacturers:Mass-market tea and confectionery producers prioritize scale economics over certification tiers, exposing them to supply volatility when pharmaceutical buyers divert higher-purity material.
- Retailers:Private label sourcing teams are consolidating supplier bases to reduce qualification overhead, favoring multi-category botanical vendors with existing USDA organic certifications.
Food Manufacturers retains the volume lead, while Cosmetic Companies are gaining share fastest on specification premiums.
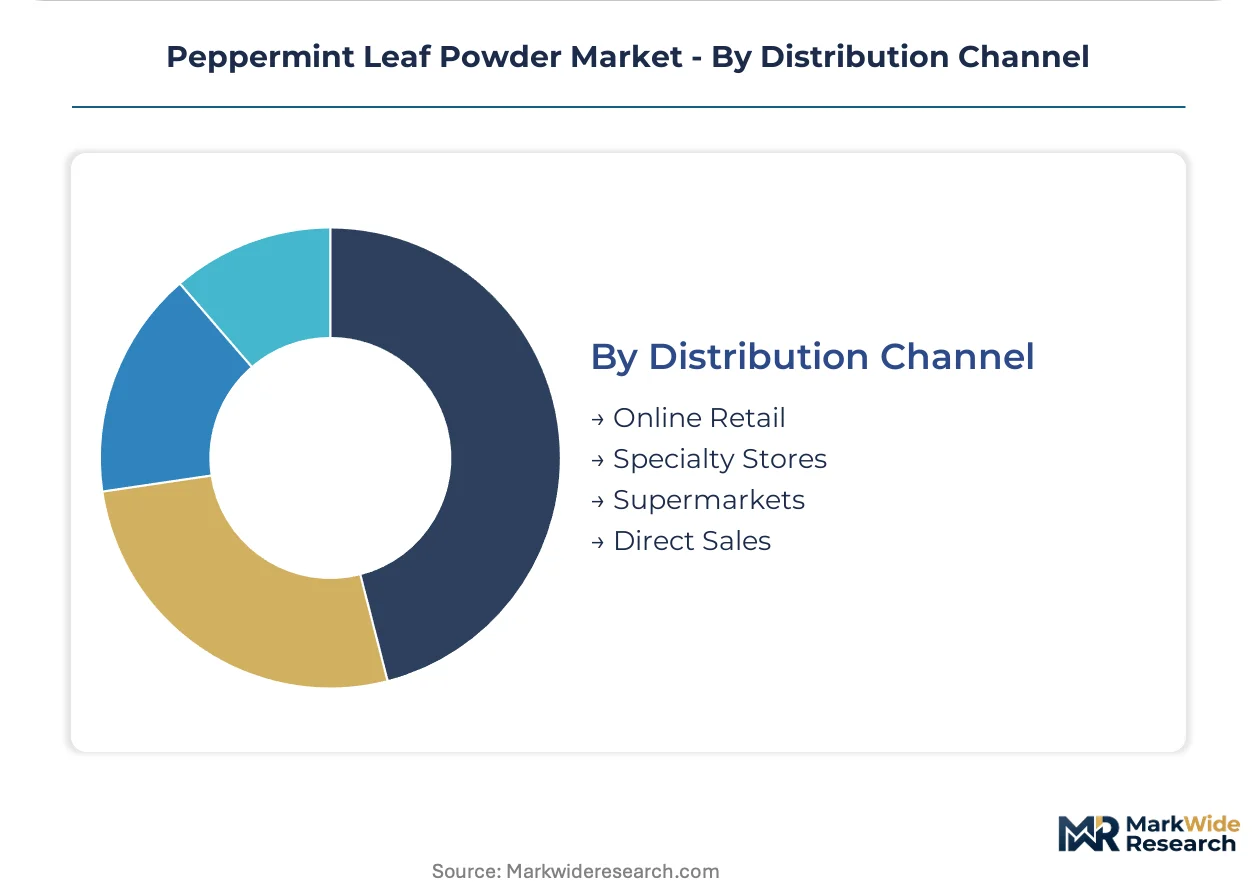
Distribution Channel:
Channel economics favor direct relationships for pharmaceutical-grade material, while fragmented retail channels struggle with traceability documentation burdens.
- Direct Sales:Annual offtake agreements between German nutraceutical encapsulators and Indian contract farming networks displace layered trader intermediaries, concentrating certified organic volume in transparent procurement channels.
- Online Retail:Functional beverage startups source freeze-dried powder through specialized botanical marketplaces that aggregate small-batch suppliers, though lot consistency remains a qualification barrier.
- Specialty Stores:Ayurvedic and natural health retailers in India and Europe stock organic grades for practitioner and consumer segments, requiring FSSAI or EFSA-aligned labeling compliance.
- Supermarkets:Mass-market retail chains absorb conventional grades for private label tea lines, with procurement teams prioritizing cost stability over certification depth.
Direct Sales holds the dominant position for premium tiers, while Online Retail is expanding most quickly among emerging brand entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulators in Germany and France command premium organic supply through direct procurement from Indian contract farming networks, while functional beverage startups in South Korea and California drive freeze-dried specification upgrades.
United States
Dietary supplement contract manufacturers in North America absorb the largest volume of certified organic powder for capsule and tablet production. FDA import alerts on pesticide residue screening force Indian exporters to pre-position solvent-free extraction partnerships before shipment. The Pacific Northwest hosts vertically integrated botanical suppliers with in-house cryogenic milling infrastructure serving pharmaceutical-grade demand.
Germany
Nutraceutical encapsulators in Germany require annual offtake agreements with Madhya Pradesh organic cooperatives to secure pipeline visibility ahead of EFSA novel food deadlines. EFSA botanical fortification assessments tighten safety dossier requirements for peppermint incorporation into fortified products. The Bavaria region concentrates contract manufacturing capacity for enteric-coated therapeutics demanding essential oil retention above pharmaceutical thresholds.
India
CDSCO-aligned exporters face dual compliance burdens from FSSAI domestic benchmarks and FDA import requirements for ayurvedic and pharmaceutical applications. The PLI scheme for botanical processing incentivizes cryogenic infrastructure investments in Uttar Pradesh growing belts. Madhya Pradesh contract farming networks supply bulk dried leaf to European extractors through organized cultivation clusters.
South Korea
Functional beverage startups in Seoul retrofit procurement specifications to exclude conventional air-dried material in favor of freeze-dried solubility advantages. MFDS cosmetic safety assessments tighten botanical ingredient documentation for scalp care formulations incorporating micronized peppermint powder. The Seoul Capital Area concentrates ready-to-drink tea innovation labs driving particle grade specification upgrades.
France
ANSM cosmetic safety assessments govern botanical incorporation into oral care lines requiring completed toxicology packages ahead of regulatory deadlines. French formulators specify micronized grades below 60 mesh for scalp care applications that ambient milling cannot achieve. The Provence-Alpes-Côte d'Azur region hosts natural cosmetics clusters sourcing directly from Indian organic cooperatives to bypass layered trader intermediaries.
Peppermint Leaf Powder Market Competitive Landscape
Player mix skews toward vertically integrated organic specialists and scale-driven conventional millers, with mid-scale cryogenic operators occupying a narrowing middle tier. Market structure concentrates premium procurement among suppliers with in-house liquid nitrogen infrastructure, while commodity-grade channels fragment across ambient milling operations. Three archetypes dominate: certified organic cooperatives with lot traceability systems, freeze-dried technology specialists serving functional beverage formulation, and bulk conventional processors competing on throughput economics. Competitive moves center on backward integration into contract farming networks and technology licensing partnerships for cryogenic stabilization systems.
Within the certified organic tier, Mountain Rose Herbs Inc. and Saipro Biotech Private Limited exemplify vertically integrated positioning through captive supply chain control over botanical raw materials. Varmora Foods Pvt. Ltd. occupies a position at the scale-driven end of conventional milling infrastructure. Among India-based processors, SM Heena Industries and PentaPure Foods represent mid-scale operators navigating capital intensity barriers to pharmaceutical-grade participation. The Green Labs LLC anchors North American supply chain visibility for nutraceutical contract manufacturers requiring USDA-certified lot documentation.
| Leading Market Players |
|---|
| Mountain Rose Herbs Inc. |
| Adams Fairacre Farms |
| Austral Herbs Pty Ltd. |
| The Green Labs LLC |
| Saipro Biotech Private Limited |
| Varmora Foods Pvt. Ltd. |
| SM Heena Industries |
| PentaPure Foods |
| National Food 'n' species |
| Others |
Value Network & Pricing Analysis
Cryogenic milling capacity utilization in Uttar Pradesh and Madhya Pradesh determines price floors across certification tiers, with underinvestment in liquid nitrogen infrastructure compressing margins for pharmaceutical-grade output while conventional air-dried channels face volatile Mentha piperita oil cost pass-through.
Pricing Analysis
Cost-plus contracts with Mentha piperita essential oil indexation dominate procurement between Indian contract farming networks and European pharmaceutical formulators. Three-tier pricing structure across organic certified, conventional air-dried, and freeze-dried pharmaceutical grades reflects essential oil retention differentials and certification depth. Cost compression in conventional channels intensifies because pharmaceutical buyers divert higher-purity material, while food manufacturers exhibit greatest price sensitivity and German nutraceutical encapsulators accept premium positioning for lot-traceable organic supply.
Supply Chain Analysis
Port congestion on Nhava Sheva-Jawaharlal Nehru trade lanes and container availability constraints inflate inbound logistics costs for European extractors sourcing from Indian bulk leaf exporters. Supply concentrates in Madhya Pradesh and Uttar Pradesh growing belts, with downstream processing drawing from Mentha piperita dried leaf, liquid nitrogen cryogenic infrastructure, and steam stabilization equipment. Single-source vulnerability from FSSAI export clearance delays and DGFT phytosanitary holdups threatens pipeline continuity. Distribution runs through direct annual offtake agreements displacing layered trader intermediaries for certified organic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peppermint leaf powder procurement is approaching a platform-economics inflection as EFSA novel food dossier completion and USDA organic lot traceability systems create interoperability barriers between qualified and unqualified supplier networks.
For Market Incumbents: Consolidate backward integration into Madhya Pradesh contract farming cooperatives to secure captive organic supply ahead of tightening FSSAI traceability mandates. Expand in-house cryogenic milling capacity to defend pharmaceutical-grade margin pools against ambient-milling competitors facing essential oil degradation thresholds. Lock multi-year offtake agreements with German and French nutraceutical encapsulators before EFSA novel food deadlines compress sourcing flexibility.
For New Entrants and Emerging Players: Anchor in freeze-dried solubility advantages for South Korean and California functional beverage startups seeking to exclude conventional air-dried material from procurement specifications. Target micronized particle grades below 60 mesh for Korean scalp care and French oral care cosmetics applications where ambient milling cannot achieve specification. Pursue direct marketplace aggregation models that bundle small-batch organic suppliers for online retail channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated organic cooperatives with completed EFSA toxicology packages and annual offtake agreements with European encapsulators. Long-term viability over the next decade rests on certification depth and cryogenic infrastructure ownership rather than scale economics alone. Monitor CDSCO-FSSAI regulatory harmonization progress as the critical inflection signal for Indian export pipeline reliability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Infrastructure Investment | In-house liquid nitrogen milling preserves essential oil retention above pharmaceutical thresholds for IBS therapeutics. |
| Backward Integration into Contract Farming | Direct procurement from Madhya Pradesh organic cooperatives satisfies USDA lot traceability and EFSA novel food documentation. |
| Freeze-Dried Capacity Expansion | Sublimation processing captures functional beverage demand from Seoul and California startups requiring solubility advantages. |
| EFSA Novel Food Dossier Completion | Completed toxicology packages secure preferred supplier status ahead of European botanical fortification regulatory deadlines. |
| Micronized Particle Grade Development | Below-60-mesh specifications unlock Korean scalp care and French oral care cosmetics applications inaccessible to ambient milling. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FSSAI export clearance records, EFSA novel food submission databases, and USDA organic certification registries. Primary interviews engaged botanical procurement managers at German nutraceutical encapsulators, cryogenic milling operators in Uttar Pradesh, and cosmetic formulators in Seoul and Provence-Alpes-Côte d'Azur. Secondary validation drew from CDSCO pharmaceutical export alerts, DGFT phytosanitary holdup notifications, and customs trade data on Mentha piperita dried leaf movements. Bottom-up volume estimates from individual processing facility capacities triangulate against top-down demand absorption by application segment.
Segmentation dimensions modeled include certification tier, processing method, application category, and end-user sophistication level across the analysis window. CAGRs derive from elasticity-adjusted demand projections incorporating pharmaceutical formulator procurement shifts and functional beverage startup formulation trends. Industry-specific forecast inputs encompass monsoon pattern impacts on Mentha piperita essential oil yields and cryogenic infrastructure deployment timelines under India's PLI scheme for botanical processing.
Decision-makers should treat outputs as directional under assumptions of sustained EFSA novel food assessment timelines and stable FSSAI-DGFT export clearance protocols; material deviation in regulatory processing speed or pesticide maximum residue limit stringency would warrant model refresh. Recalibration cycles align with material shifts in CDSCO-FSSAI harmonization progress and EFSA botanical fortification precedent decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Flower Extract Market
Extracts
Cassia Seed Extract Market
Extracts
Frankincense Oil Market
Extracts
White Willow Bark Extract Market
Extracts
Extracts and Distillates Market
Extracts
Natural Morocco Argan Oil Market
Extracts
Gum Turpentine Oil Market
Extracts
Global Aphrodisiac Powder Market
Extracts
Nootkatone Market
Extracts
Medicinal Plant Extracts Market
Extracts
Helichrysum Oil Market
Extracts
Saffron Extract Market
Extracts
Passion Flower Extracts Market
Extracts
Lavender Oil Market
Extracts
Europe Mineral Turpentine Market
Extracts
Glycerol Extracts Market