
 Natural Fragrance Chemicals Market | 2026-2036
Natural Fragrance Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Fragrance Chemicals Market Foresight
Asset-light contract manufacturing and third-party bioprocessing partnerships is reconfiguring capital requirements for new entrants in natural fragrance chemicals. Givaudan leverages its integrated botanical supply chain from Grasse to secure rare raw materials. Symrise anchors its competitiveness through fermentation-derived molecules that reduce agricultural volatility. Firmenich specializes in captive jasmine and rose extraction programs that differentiate its premium offerings.
Natural fragrance chemicals comprise volatile aromatic compounds extracted or biotechnologically derived from plant, animal, or microbial sources, typically containing terpenoids, phenylpropanoids, and aliphatic compounds that deliver olfactory character at concentrations measured in parts per million. These substances serve primarily to scent consumer products while meeting clean-label and allergen-disclosure requirements across cosmetics and household applications. Essential oils maintain the largest volume share within product-type segments due to established distillation infrastructure and broad regulatory acceptance, though absolutes command superior margins in luxury perfumery where solvent-extracted materials deliver olfactory complexity unattainable through steam distillation. Cosmetics and personal care applications absorb the majority of value within the application dimension, while food and beverages represents the fastest-expanding demand pool as natural flavor regulations tighten across multiple jurisdictions.
REACH registration through ECHA governs chemical safety documentation for European fragrance ingredient suppliers, while FDA oversight under the Fair Packaging and Labeling Act mandates ingredient disclosure for cosmetic products in the United States. ISO 9235 provides the definitional boundary between natural and synthetic origin claims, directly shaping product development investments and marketing compliance costs. Stakeholders must monitor evolving biotech-derived ingredient classifications under these frameworks, as regulatory ambiguity around fermentation-based naturals threatens to redraw competitive boundaries between extraction-dependent and biosynthesis-led supply models.
Market Dynamics
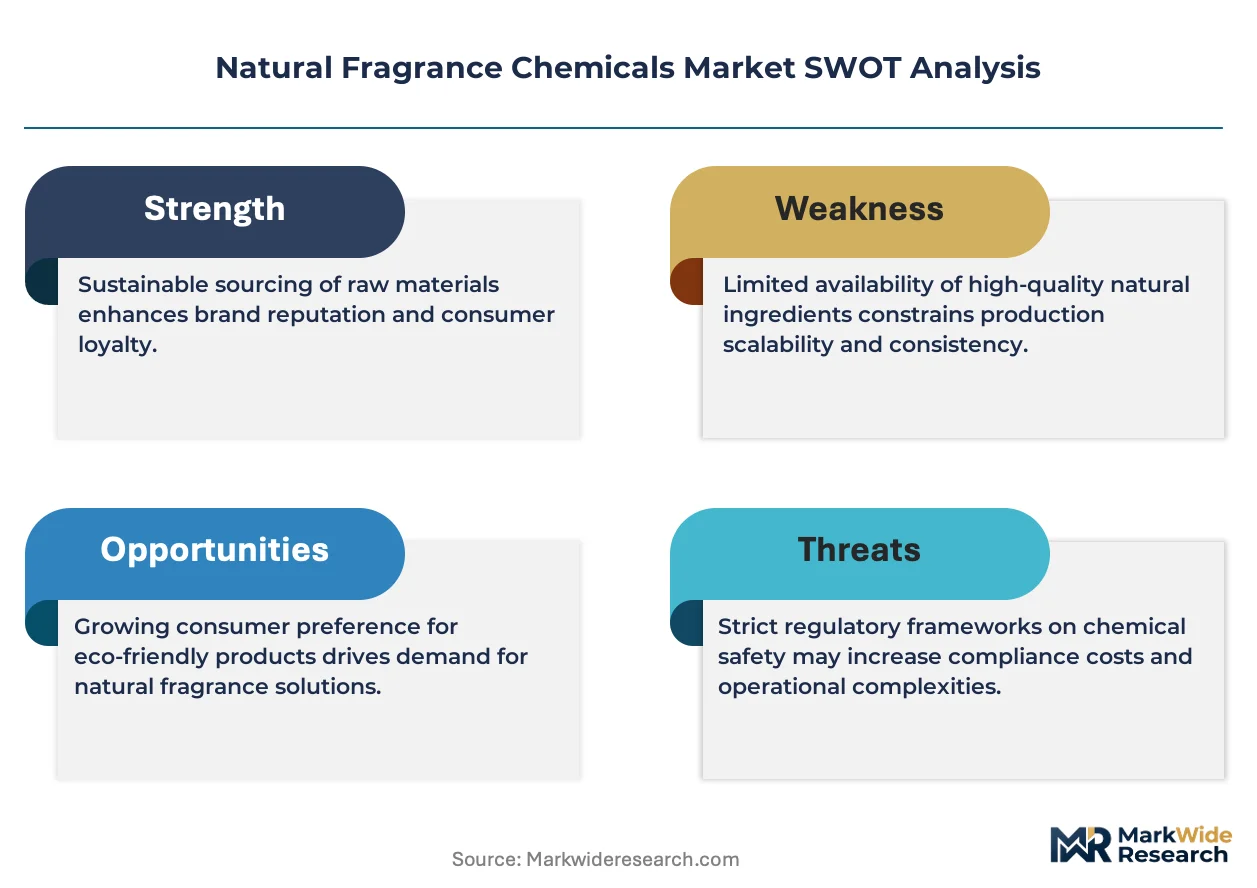
Bioprocessing scale-up is compressing capital requirements for natural fragrance production while REACH compliance and ISO 9235 certification standards are tightening definitional boundaries between natural and synthetic origin claims.
Growth Catalysts
- REACH registration mandates:ECHA documentation requirements for chemical safety are accelerating supplier consolidation toward compliant botanical extractors in France and Switzerland.
- Fermentation-derived molecules:Microbial biosynthesis is reducing agricultural feedstock volatility for terpenoid and phenylpropanoid production.
- Clean-label cosmetics procurement:Premium personal care brands in the United States are expanding plant-derived scent compound sourcing to meet allergen-disclosure requirements.
Market Restraints
- Jasmine and rose agricultural concentration:Captive extraction programs depend on harvests from specific Mediterranean and North African growing regions.
- ISO 9235 definitional friction:Regulatory ambiguity around fermentation-based naturals creates compliance cost uncertainty for biotech-derived ingredient classifications.
- Solvent extraction cost structure:Absolutes production requires petroleum-derived solvents whose price volatility compresses margins in luxury perfumery segments.
Strategic Opportunities
- Food and beverage regulatory tailwinds:Natural flavor regulations tightening across multiple jurisdictions are expanding addressable demand beyond cosmetics applications.
- Asset-light contract manufacturing:Third-party bioprocessing partnerships enable new entrants to bypass distillation infrastructure investments.
- Household product channel expansion:Clean-label requirements are penetrating home care segments previously dominated by synthetic fragrance formulations.
Industry Challenges
- Bioprocessing talent scarcity:Fermentation scale-up expertise remains concentrated among specialized flavor and fragrance houses with captive R&D facilities.
- Dual certification timelines:Suppliers must simultaneously navigate ECHA REACH documentation and FDA Fair Packaging and Labeling Act disclosure mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Fragrance Chemicals Market |
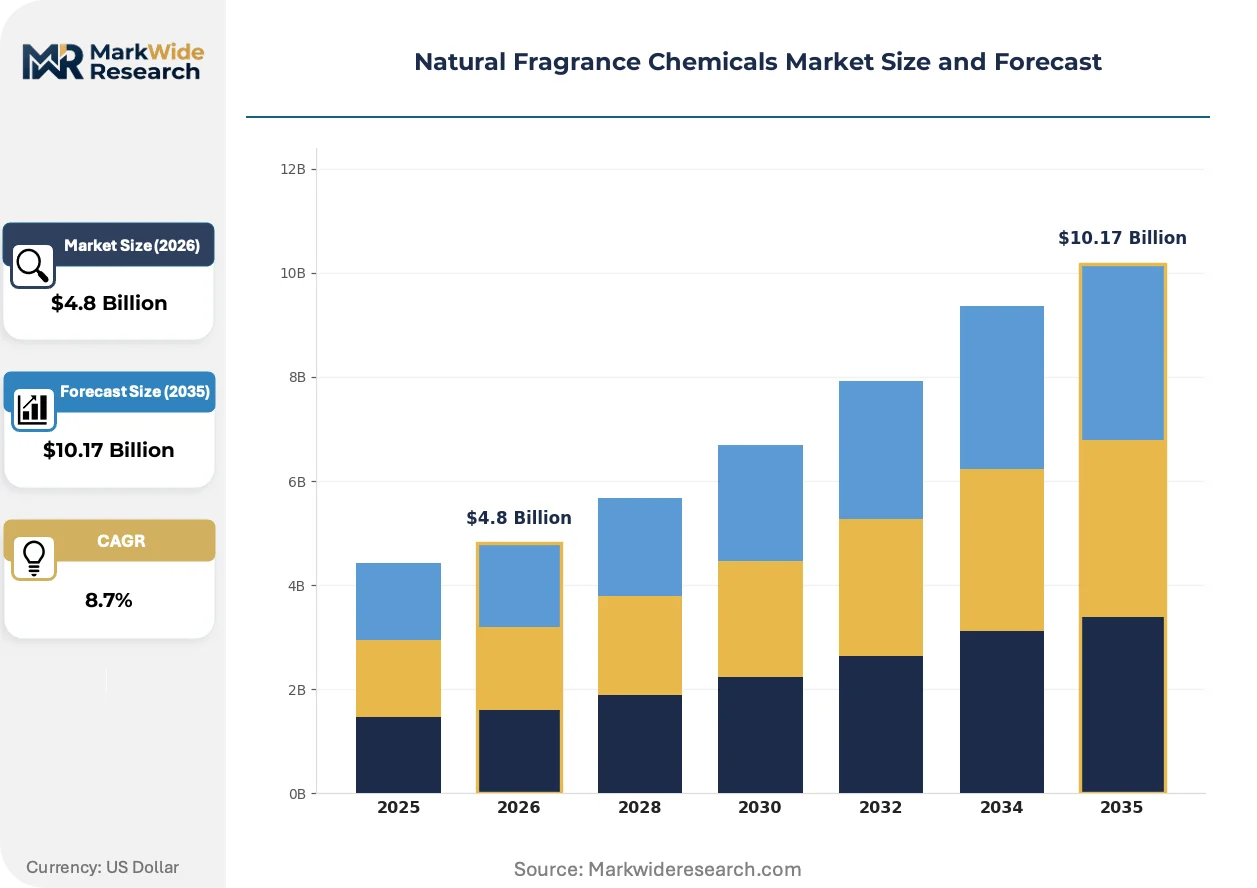
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Absolutes, Extracts, Resins Application: Cosmetics, Personal Care, Household Products, Food & Beverages Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Manufacturers, Retailers, Wholesalers, Brand Owners |
| Companies Covered | Givaudan, Symrise, International Flavors & Fragrances, Firmenich, Takasago International Corporation, Sensient Technologies Corporation, BASF, Robertet, Mane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Fragrance Chemicals Market Shifts & Advancements
Precision fermentation and enzymatic biotransformation are rewriting extraction economics while regulatory frameworks struggle to classify novel production pathways.
Cell-culture derived aromatic compounds are hybridizing traditional botanical supply chains with industrial biotechnology. Luxury perfumers in Grasse and Geneva are piloting these materials to secure rare molecules independent of harvest cycles. This convergence is hybridizing competitive boundaries between extraction-dependent suppliers and biosynthesis-led entrants.
ECHA is clarifying registration requirements for biotechnology-derived fragrance ingredients under evolving REACH guidance. The agency's interpretive documents are forcing reformulation investments among suppliers marketing fermentation outputs as natural. European fragrance houses with integrated botanical programs are responding by dual-tracking extraction and biosynthesis capabilities.
Buyer concentration among premium cosmetics houses is compressing supplier negotiation leverage. Direct procurement relationships are displacing traditional distributor intermediaries for high-volume essential oil contracts. This pattern is most visible in United States and French markets where flavor and fragrance houses maintain concentrated production facilities.
Natural Fragrance Chemicals Market Segmentation
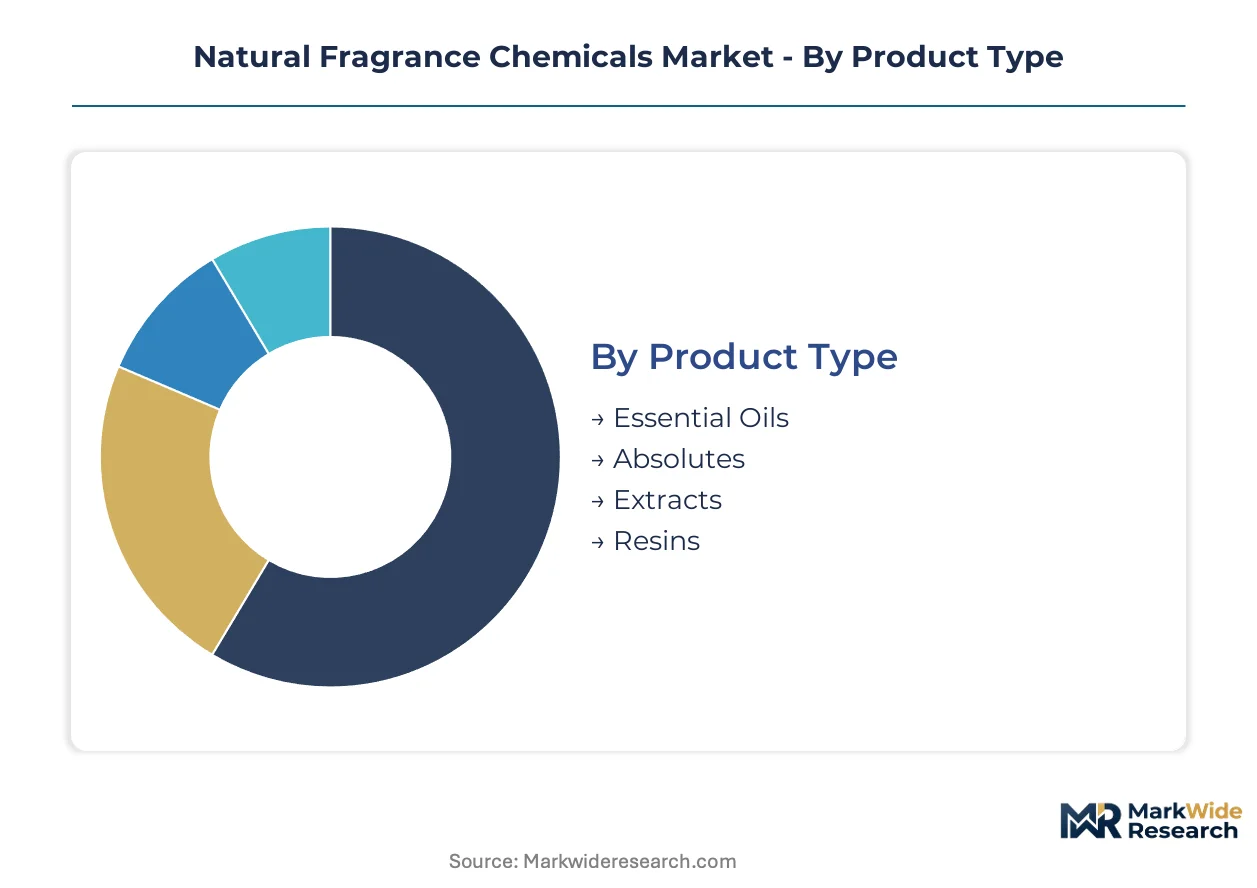
Segmentation in natural fragrance chemicals reveals divergent margin structures across extraction methods and end-use channels. Each dimension carries distinct regulatory footprints and capital intensity requirements that reshape competitive positioning.
Product Type:
Mature distillation infrastructure dominates volume, while emerging biotechnologies are capturing premium positioning through supply security guarantees.
- Essential Oils:Steam-distilled volatile compounds from botanical feedstocks, standardized by ISO 9235 for natural origin claims. Demand concentrates in mass-market cosmetics from French and United States brands seeking REACH-compliant documentation for high-volume formulations.
- Absolutes:Solvent-extracted aromatic materials delivering olfactory complexity for luxury perfumery. Production clusters around Grasse extraction facilities serving Geneva-based fragrance houses, though petroleum-derived solvent costs compress margins during energy price spikes.
- Extracts:Maceration and enfleurage-derived compounds preserving delicate floral notes. Supercritical CO2 extraction is gaining adoption in Swiss R&D facilities for residue-free outputs.
- Resins:Oleoresinous secretions from tree bark and plant wounds, historically concentrated in Mediterranean harvesting cooperatives. Supply volatility from climate stress in North African growing regions is accelerating fermentation-based substitution research.
Essential oils retain volume leadership; absolutes hold the steepest expansion curve.
Application:
Cosmetics procurement absorbs the majority of value, yet food and beverage regulatory tailwinds are redrawing demand geography.
- Cosmetics:Foundation, color cosmetics, and skincare formulations requiring allergen-disclosure compliance under FDA Fair Packaging and Labeling Act mandates. United States premium brands are expanding direct procurement from Grasse-based extraction houses.
- Personal Care:Haircare and body wash applications where clean-label positioning commands shelf space in United States specialty retail. Sodium lauryl sulfate-free formulations are driving essential oil substitution for synthetic masking agents.
- Household Products:Surface cleaners and air care previously dominated by petrochemical fragrances. ECHA REACH registration requirements are filtering non-compliant suppliers from European supermarket private-label programs.
- Food & Beverages:Natural flavor regulations tightening across multiple jurisdictions are expanding addressable demand beyond traditional cosmetics channels. Fermentation-derived molecules are securing novel food approvals in Swiss and French regulatory pathways.
Cosmetics commands value concentration; food and beverages is climbing the fastest.
Distribution Channel:
Channel selection reflects buyer scale and certification documentation requirements rather than pure cost optimization.
- Online Retail:E-commerce platforms serving small-batch cosmetic formulators and indie perfumers. United States-based marketplaces are expanding ISO 9235-certified product filtering tools.
- Specialty Stores:Grasse and Geneva fragrance ingredient boutiques offering technical consultation for boutique perfumers. Staff expertise in REACH documentation differentiates from commodity distributors.
- Supermarkets:Mass-market essential oil lines for household product applications. Private-label buyers in French retail chains are consolidating supplier bases toward ECHA-registered extractors.
- Direct Sales:Long-term contracts between extraction houses and fragrance houses with captive R&D facilities. Givaudan, Symrise, and Firmenich procurement teams negotiate directly for jasmine and rose absolutes.
Direct sales retains contract value leadership; online retail is gaining share fastest.
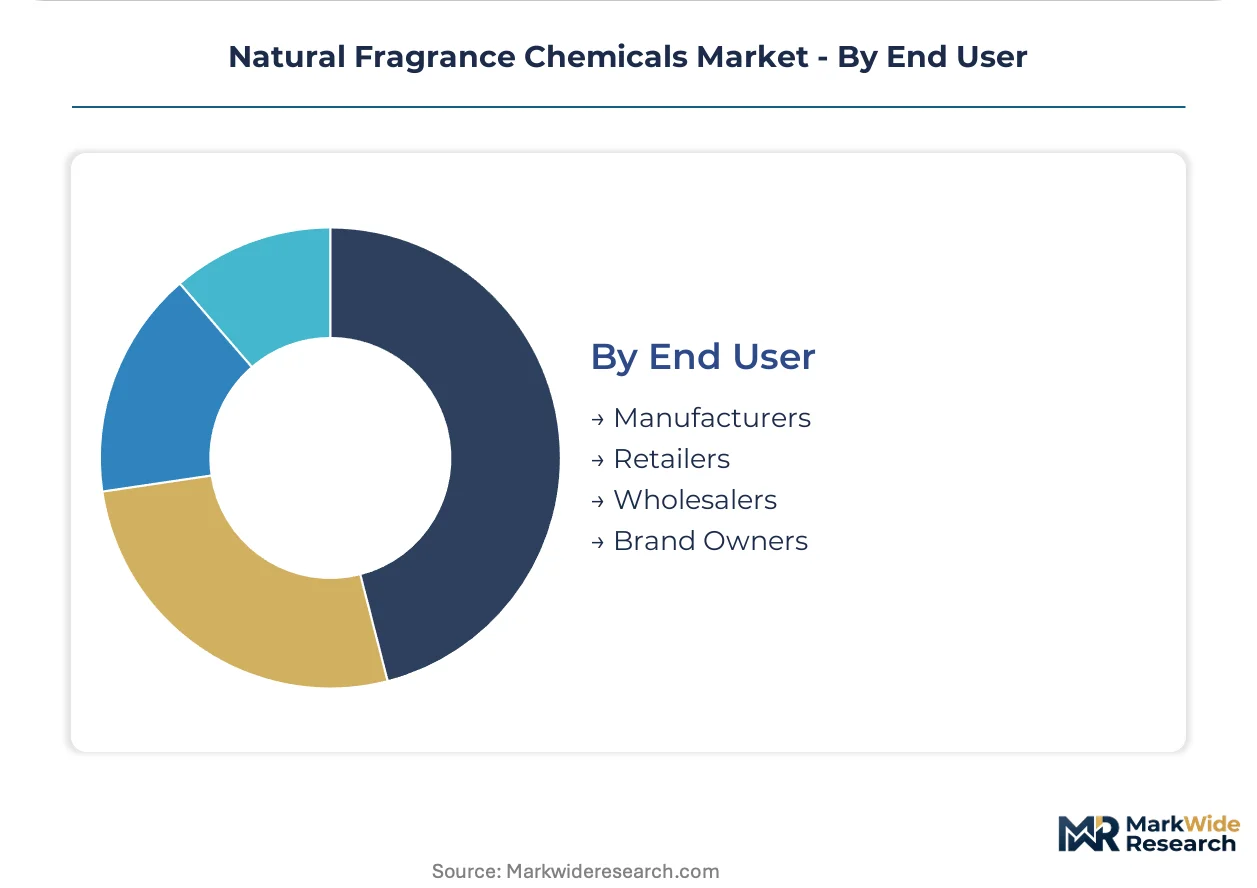
End User:
Buyer concentration among integrated fragrance houses is compressing negotiation leverage for independent extractors.
- Manufacturers:Cosmetic and household product formulators requiring documented supply chain transparency. French manufacturers face dual pressure from REACH registration costs and clean-label marketing requirements.
- Retailers:United States specialty beauty chains and European pharmacy networks developing private-label natural fragrance lines. Buyer power is consolidating around ISO 9235 certification as a non-negotiable threshold.
- Wholesalers:Traditional intermediaries facing margin compression as direct procurement displaces their role in high-volume essential oil transactions.
- Brand Owners:Premium cosmetics houses in France and the United States building captive botanical supply relationships. Investment in Grasse-area extraction partnerships secures rare raw material access independent of spot markets.
Manufacturers retain volume leadership; brand owners hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium cosmetics houses in France and the United States command procurement leverage through direct sourcing relationships, while Swiss and German regulatory frameworks reshape competitive access across European extraction networks.
United States
Clean-label cosmetics brands in New York and Los Angeles are expanding plant-derived scent compound sourcing to meet FDA Fair Packaging and Labeling Act disclosure mandates. The agency's allergen-labeling requirements are filtering non-compliant suppliers from premium personal care channels. New Jersey-based flavor and fragrance R&D facilities are piloting fermentation-derived molecules to reduce agricultural feedstock dependence.
France
Grasse extraction houses serve Geneva-based fragrance formulators with jasmine and rose absolutes for luxury perfumery applications. ANSM oversight of cosmetic ingredient safety is tightening documentation requirements for botanical supply chains. Provence-Alpes-Côte d'Azur growing cooperatives are consolidating harvest volumes to secure contract leverage against integrated fragrance houses.
Switzerland
Swissmedic certification requirements for cosmetic ingredient safety are accelerating supplier consolidation toward compliant extractors in Geneva and Basel. ISO 9235 definitional standards shape natural-origin marketing claims across European export markets. Zurich-area bioprocessing facilities are scaling precision fermentation for terpenoid production independent of Mediterranean harvest cycles.
Germany
Mass-market household product manufacturers in North Rhine-Westphalia are substituting synthetic fragrances with REACH-registered essential oils for supermarket private-label programs. ECHA documentation mandates are raising compliance costs for non-registered botanical suppliers. Bavaria-based cosmetic formulators are developing direct procurement relationships with Grasse extraction houses to bypass distributor intermediaries.
India
Specialty cosmetics manufacturers in Maharashtra and Gujarat are importing ISO 9235-certified essential oils for clean-label personal care formulations targeting domestic premium retail. BIS standards for natural fragrance quality are evolving toward alignment with European certification frameworks. Karnataka-based bioprocessing startups are partnering with Swiss fragrance houses for fermentation technology licensing.
Natural Fragrance Chemicals Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. Integrated fragrance houses with captive R&D and extraction capabilities occupy premium negotiating positions against independent botanical suppliers. Three archetypes dominate: vertically integrated multinationals with Grasse-to-Geneva supply chains, fermentation-technology specialists reducing agricultural volatility, and regional extraction houses serving boutique perfumers. Competitive moves center on backward integration into rare raw material sourcing and strategic partnerships with bioprocessing technology providers.
Among Swiss-anchored integrated houses, Givaudan and Firmenich exemplify the captive supply archetype through controlled botanical programs. Symrise represents the biosynthesis-led competitive vector with fermentation-derived molecule capabilities. These three occupy positions that independent extractors cannot replicate without equivalent capital intensity and regulatory certification depth.
| Leading Market Players |
|---|
| Givaudan |
| Symrise |
| International Flavors & Fragrances |
| Firmenich |
| Takasago International Corporation |
| Sensient Technologies Corporation |
| BASF |
| Robertet |
| Mane |
| Others |
Supply & Pricing Matrix
Petroleum-derived solvent price volatility determines both margin compression in absolutes production and the geographic clustering of extraction facilities around Grasse and Geneva. REACH registration costs filter non-compliant suppliers from European procurement channels, widening price spreads between certified and uncertified botanical inputs.
Pricing Analysis
Cost-plus contracts with petroleum-indexed solvent clauses dominate absolutes procurement between Grasse extraction houses and Geneva-based fragrance formulators. Price differentiation rests on ISO 9235 certification grade and volume scale, with premium tiers commanding substantial markups for documented natural-origin claims. Pricing pressure stems from energy cost spikes in solvent-dependent extraction, compressing margins for luxury perfumery suppliers. Mass-market essential oil buyers exhibit highest price sensitivity, while captive jasmine and rose programs show inelastic demand from integrated fragrance houses.
Supply Chain Analysis
Export-control restrictions on fermentation bioreactor technology limit bioprocessing scale-up partnerships outside established Swiss and French R&D corridors. Raw material flows draw from jasmine harvests in Egypt and Morocco, rose petals from Turkey and Bulgaria, and terpenoid feedstocks from Mediterranean citrus cooperatives. Single-source vulnerability concentrates in Mediterranean floral harvests exposed to climate stress. Distribution runs through direct procurement contracts between extraction houses and integrated fragrance houses, bypassing traditional wholesale intermediaries for high-volume essential oil transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated fragrance houses with captive R&D facilities, fragmenting negotiation leverage for independent botanical suppliers. Direct procurement relationships now displace distributor intermediaries for jasmine and rose absolutes.
For Market Incumbents: Pre-empt fermentation-based substitution threats by dual-tracking extraction and biosynthesis capabilities in Swiss R&D facilities. Secure backward integration into Provence-Alpes-Côte d'Azur growing cooperatives before harvest consolidation accelerates. ECHA's evolving biotechnology guidance represents the critical regulatory lever requiring parallel documentation investments. For New Entrants and Emerging Players: Establish a beachhead in food and beverage natural flavor applications where regulatory tailwinds expand addressable demand beyond cosmetics saturation. Target Indian specialty cosmetics manufacturers seeking ISO 9235-certified imports for domestic premium retail. Asset-light contract manufacturing partnerships with third-party bioprocessors enable bypass of distillation infrastructure capital requirements. For Investors and Strategic Acquirers: ECHA clarification on fermentation-derived ingredient classifications reshapes the acquisition landscape toward suppliers with dual certification capabilities. Long-term viability centers on biotechnology-extraction hybrid models with documented regulatory pathways. The signal to monitor is novel food approval velocity for fermentation-derived molecules in Swiss and French regulatory channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Botanical Supply | Captive jasmine and rose programs in Grasse secure raw material access independent of spot market volatility. |
| Precision Fermentation Scale-Up | Swiss bioprocessing facilities reduce agricultural feedstock dependence for terpenoid and phenylpropanoid production. |
| Dual Certification Investment | Simultaneous ECHA REACH and FDA Fair Packaging compliance opens transatlantic procurement channels for extraction houses. |
| Food and Beverage Channel Expansion | Natural flavor regulatory tightening across multiple jurisdictions diversifies revenue beyond cosmetics applications. |
| Direct Procurement Relationship Development | Long-term contracts with integrated fragrance houses displace distributor intermediaries and stabilize volume commitments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA registration databases, SEC 10-K filings from listed fragrance houses, and customs trade data for essential oil imports. Interviews with extraction house technical directors, procurement leads at Givaudan and Symrise, Swissmedic regulatory affairs officers, and Grasse growing cooperative managers informed supply chain and compliance assessments. Secondary validation drew from ISO 9235 certification registries, ANSM cosmetic ingredient safety filings, and botanical harvest statistics from Mediterranean agricultural cooperatives. Bottom-up volume modeling triangulated against top-down market sizing from fragrance house revenue disclosures.
Forecast inputs span essential oils, absolutes, extracts, and resins across cosmetics, personal care, household products, and food and beverage applications, with geographic granularity at country level for France, Switzerland, United States, Germany, and India. CAGRs were derived from regression analysis against historical volume trajectories and projected regulatory compliance cost impacts. Industry-specific inputs include ECHA biotechnology guidance evolution timelines and FDA allergen-disclosure enforcement patterns.
Stress conditions across petroleum price volatility, Mediterranean harvest yield variance, and REACH registration fee escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory clarity timelines and fermentation technology licensing velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Europe Aroma Chemicals Market
Flavor and Fragrance Chemicals
Natural Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
North America Aroma Chemicals Market
Flavor and Fragrance Chemicals
Global Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Semiochemicals Market
Flavor and Fragrance Chemicals
Middle East and Africa Deodorants Market
Flavor and Fragrance Chemicals
Encapsulated Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Sensory Modifiers Market
Flavor and Fragrance Chemicals
United States Aroma Chemicals Market
Flavor and Fragrance Chemicals
Smoke Ingredients Market
Flavor and Fragrance Chemicals
Global Bio Vanillin Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Estragole Market