
 Global Anti-Aging Market | 2026-2036
Global Anti-Aging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Aging Market Analysis
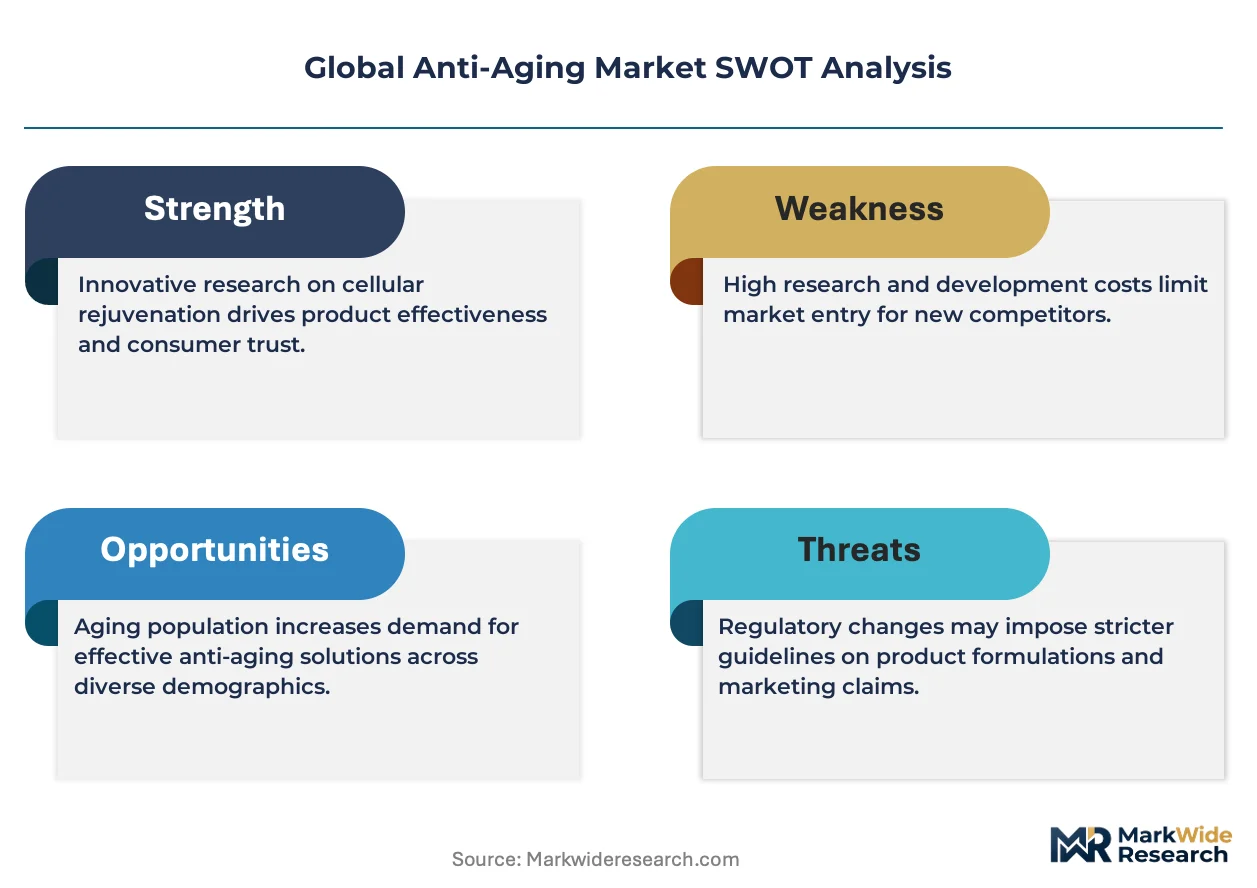
Med-spa and dermatology clinic demand is restructuring the professional channel as consumers shift from over-the-counter routines to supervised protocols. L'Oréal S.A. leverages its dermatological science division to anchor clinical credibility. Beiersdorf AG sustains R&D intensity around niacinamide formulations. Shiseido Company competes through biotech-derived ingredient platforms.
Anti-aging encompasses topical, ingestible, and device-based interventions designed to retard visible skin aging, improve dermal matrix integrity, or restore cellular metabolic function through mechanisms including collagen stimulation, antioxidant neutralization, and controlled epidermal resurfacing. Skincare commands the largest revenue pool due to repeat purchase frequency and formulation premiumization, while devices represent the fastest-expanding margin segment as clinic-based energy treatments gain protocol standardization. LED Therapy and laser treatments within the technology dimension attract capital allocation because hardware lock-in generates recurring consumable revenue.
The FDA oversees cosmetic-drug distinction and claims enforcement in the United States, while the EU MDR and REACH framework govern ingredient safety and medical device classification across European markets. Japan's PMDA maintains stringent documentation requirements for quasi-drug anti-aging claims, elevating compliance costs for new entrants. Stakeholders must monitor regulatory divergence between cosmetic and medical device pathways as peptide and growth-factor formulations blur traditional category boundaries.
Market Dynamics
Med-spa protocol standardization is compressing margins for standalone clinics while concentrating purchasing power among multi-site dermatology networks. The FDA's cosmetic-drug boundary enforcement is forcing reformulation cycles that favor established R&D infrastructure.
Growth Catalysts
- Preventative maintenance protocols:South Korea's medical aesthetics corridor normalizes early intervention regimens among consumers under 35, expanding addressable patient lifetime value.
- EU MDR pathway clarity:The framework's medical device classification guidance reduces regulatory ambiguity for peptide-based topicals, accelerating commercialization timelines.
- Energy device hardware lock-in:LED therapy platforms generate recurring consumable revenue streams that improve clinic cash flow predictability and vendor retention rates.
Market Restraints
- Peptide raw material concentration:Contract manufacturers in China supply over 60% of active pharmaceutical-grade peptides, creating single-source vulnerability for Western formulators.
- Clinical trial cost inflation:Japan's PMDA quasi-drug documentation requirements demand extended safety dossiers that elevate barrier-to-entry costs for novel ingredient claims.
- At-home device substitution:Consumer-grade microcurrent and LED masks capture maintenance-phase patients who would otherwise return for professional treatments.
Strategic Opportunities
- Brazil's underserved middle-class segment:ANVISA's streamlined cosmetic registration pathway enables faster market access than US or EU equivalents for mid-tier positioning.
- Biometric personalization convergence:Integration of skin microbiome analysis with AI-driven formulation matching creates protocol stickiness and data moats.
- Subscription channel infrastructure:Direct-to-consumer replenishment models bypass retail margin extraction while capturing longitudinal patient data.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in encapsulation technologies for unstable actives commands premium compensation that squeezes mid-tier brand economics.
- Legacy clinic management software:Patient record systems lack interoperability with emerging teledermatology platforms, complicating hybrid care model deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Aging Market |
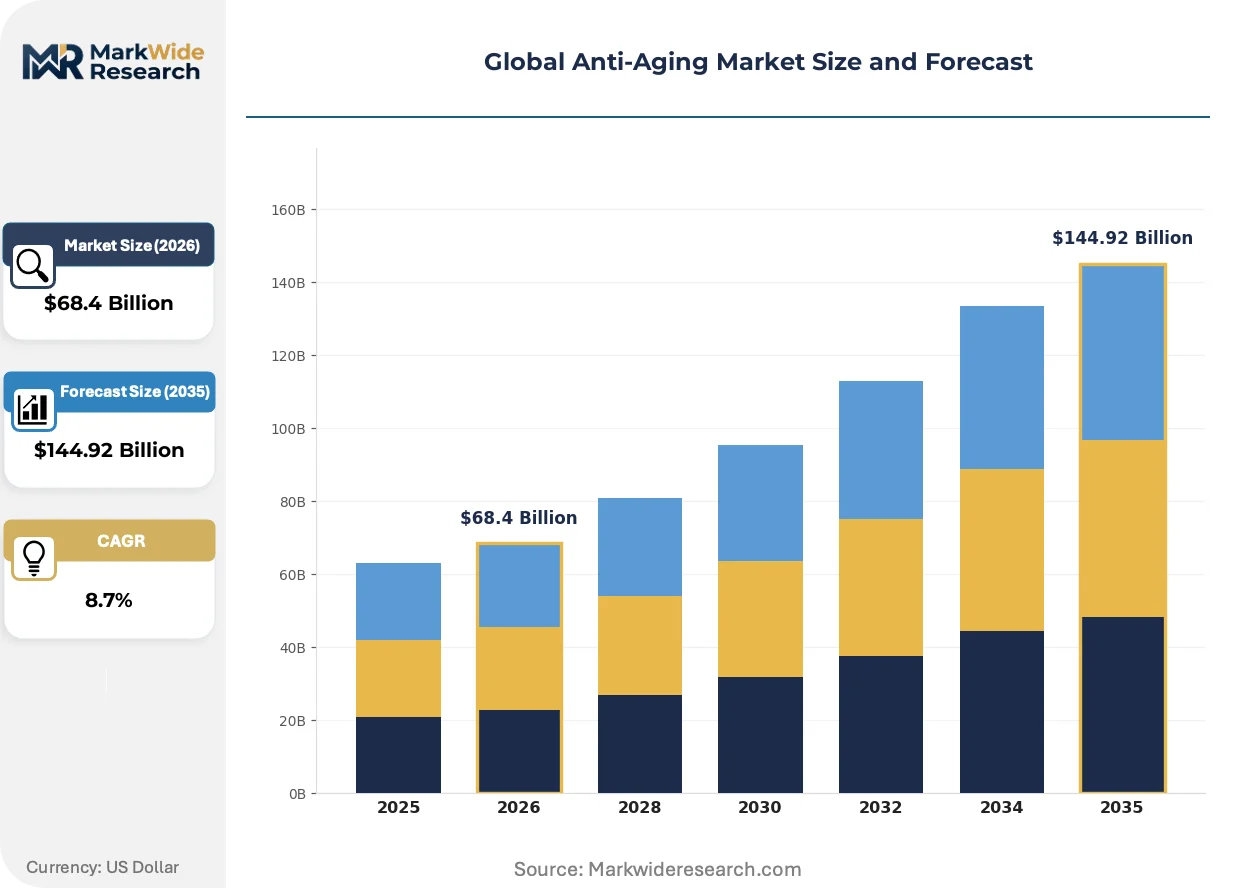
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Supplements, Devices End User: Women, Men, Dermatologists, Spa Professionals Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Department Stores Technology: Laser Treatments, Chemical Peels, Microdermabrasion, LED Therapy |
| Companies Covered | L'Oréal S.A., The Estée Lauder Companies Inc., Procter & Gamble Co., Unilever PLC, Beiersdorf AG, Shiseido Company, Johnson & Johnson, Coty Inc., Amorepacific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Aging Market Emerging Trajectories
Biotechnology-derived ingredient platforms are displacing traditional botanical extracts as the primary basis for clinical credibility claims. The competitive frontier has shifted from marketing narrative to mechanistic proof-of-action documentation.
Exosome-based delivery systems are consolidating position as the preferred vector for growth factor and peptide penetration enhancement. Dermatology networks in Seoul and Los Angeles are adopting these platforms for protocol differentiation. The technology is consolidating supplier power among a handful of cell-culture biotechnology firms with GMP-grade manufacturing capabilities.
REACH authorization requirements for novel cosmetic ingredients are tightening substance safety dossier standards across European markets. Formulators must now submit extended toxicological profiles that extend development timelines by 18-24 months. Small and mid-sized brands are responding by licensing proven ingredient platforms rather than developing proprietary molecules.
Patients are compressing decision cycles by researching practitioner credentials and device specifications before initial consultation. The traditional clinic channel is losing gatekeeper status to Instagram and TikTok-driven discovery. This behavioral shift is most pronounced in Saudi Arabia and the UAE, where influencer dermatologists command appointment waitlists exceeding eight weeks.
Global Anti-Aging Market Segmentation
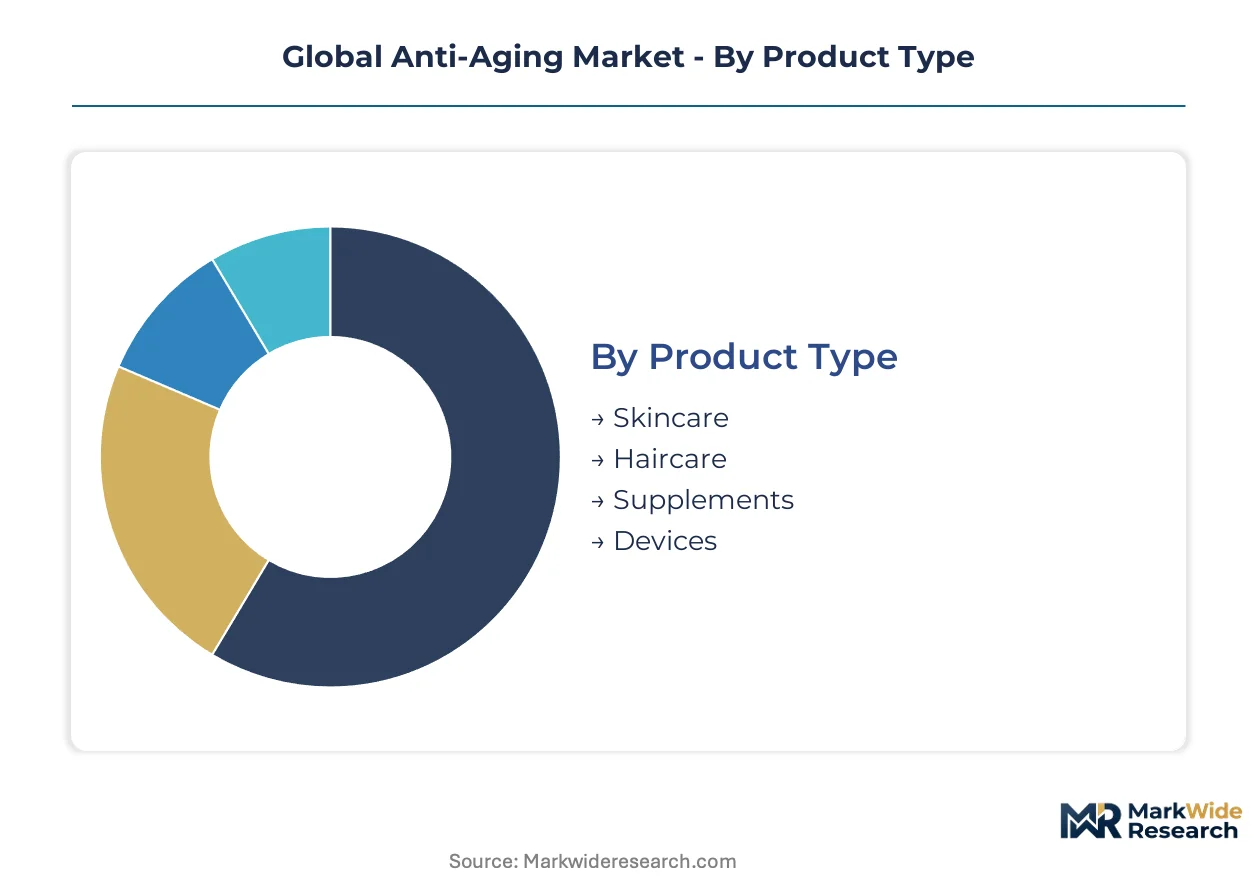
Anti-aging market segmentation reveals divergent capital requirements across intervention modalities. Product development cycles, regulatory pathways, and channel infrastructure investments vary dramatically by category, dictating competitive entry strategies.
Product Type:
Capital intensity peaks in device manufacturing where FDA and EU MDR compliance demands specialized cleanroom facilities and extended clinical validation timelines. Formulation chemistry requires lower fixed asset deployment but carries recurring R&D burn for active ingredient stability testing.
- Skincare:Topical formulations leveraging retinoids, peptides, and antioxidant complexes dominate repeat purchase economics. Demand concentrates in South Korea's medical aesthetics corridor where dermatology clinics prescribe maintenance protocols alongside professional treatments.
- Devices:Energy-based systems including laser, radiofrequency, and ultrasound platforms require substantial upfront tooling investment and service infrastructure. Dermatology networks in Los Angeles and Seoul are standardizing hardware protocols to lock in recurring consumable revenue.
- Supplements:Ingestible collagen and NAD+ precursors face stricter claims substantiation under Japan's PMDA quasi-drug framework.
- Haircare:Scalp-focused anti-aging treatments integrate peptide delivery with follicle stimulation technologies.
Skincare absorbs the bulk of installed capacity; Devices are expanding most quickly.
End User:
Customer acquisition costs diverge sharply between supervised clinical channels and direct-to-consumer targeting. Professional gatekeepers command premium pricing power but require specialized sales force deployment and training infrastructure investment.
- Women:The core demographic driving preventative maintenance adoption, particularly in the 35-50 age bracket where collagen depletion accelerates. Clinics in Dubai and Riyadh report eight-week appointment waitlists for influencer dermatologist consultations.
- Dermatologists:Professional prescribers anchor clinical credibility and protocol standardization. Multi-site networks in Germany and the United States are consolidating purchasing power through group procurement organizations.
- Men:Emerging segment with distinct formulation preferences for simplified routines and discreet packaging.
- Spa Professionals:Med-spa technicians operate under physician supervision with narrower scope of practice than board-certified dermatologists.
Women generate the majority of current revenue; Dermatologists are gaining share fastest as supervised protocols displace over-the-counter routines.
Distribution Channel:
Channel economics reflect margin extraction layers and data capture capabilities. Direct relationships enable longitudinal patient tracking that feeds personalization algorithms and subscription retention.
- Online Retail:Direct-to-consumer platforms bypass retail margin extraction while capturing biometric data through skin assessment tools. Subscription replenishment models improve lifetime value predictability.
- Specialty Stores:Sephora and Ulta Beauty locations provide tactile sampling environments for premium skincare launches. Staff training investments differentiate experiential retail from transactional e-commerce.
- Pharmacies:CVS and Walgreens leverage pharmacist trust for clinical-positioned anti-aging brands with quasi-drug status.
- Department Stores:Nordstrom and Neiman Marcus maintain prestige positioning through exclusive launches and beauty advisor consultations.
Online Retail captures the steepest volume growth trajectory; Specialty Stores retain margin leadership in premium tiers.
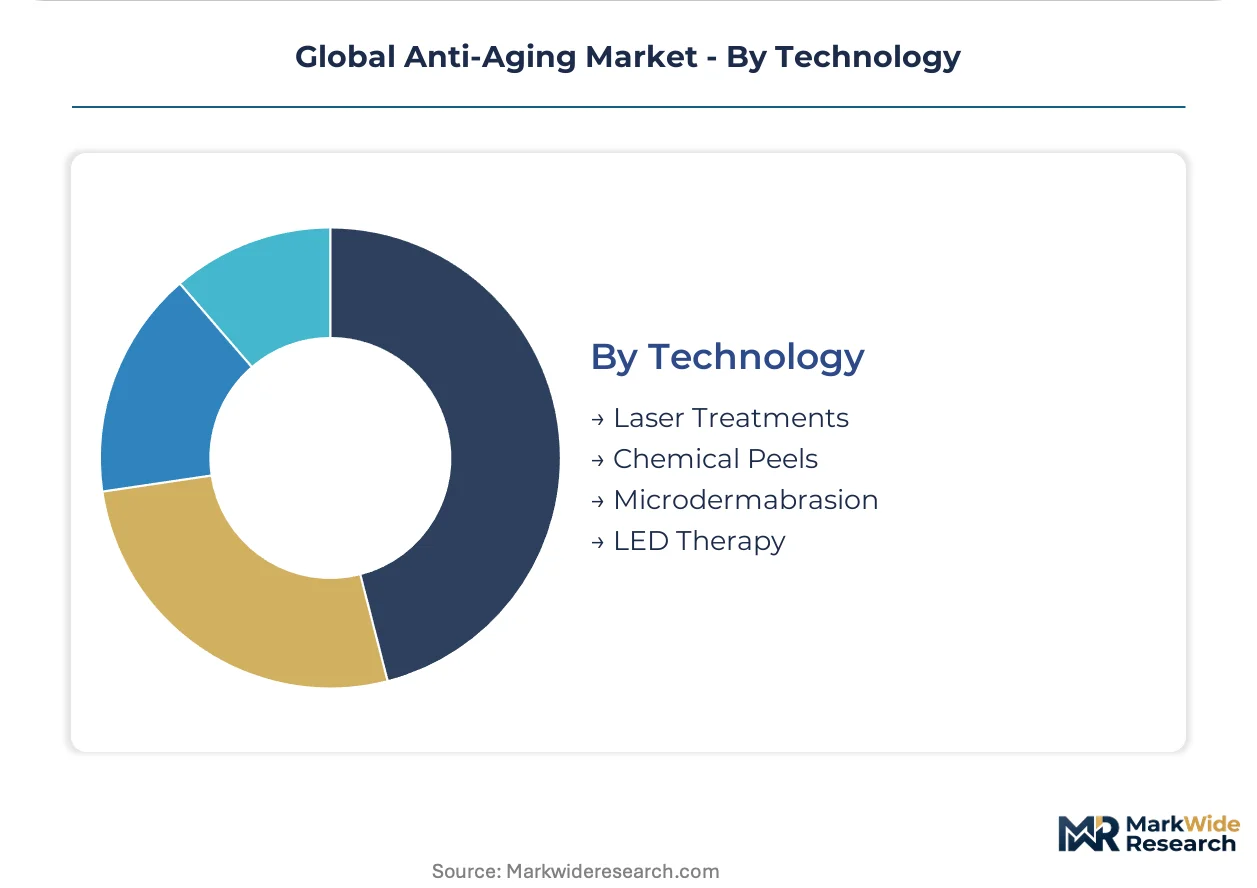
Technology:
Hardware platforms generate recurring revenue through disposable tips, calibration services, and software licensing. Treatment protocol IP creates stickier customer relationships than commodity device sales.
- LED Therapy:Non-invasive photobiomodulation using specific wavelength combinations to stimulate collagen and reduce inflammation. Seoul-based clinic chains are adopting multi-modal platforms that combine LED with microcurrent for protocol differentiation.
- Laser Treatments:Ablative and non-ablative fractional systems deliver controlled thermal injury for dermal remodeling. Equipment manufacturers in Israel and Germany dominate high-power medical-grade system supply.
- Chemical Peels:Acid-based exfoliation protocols ranging from superficial glycolic applications to deep phenol resurfacing.
- Microdermabrasion:Mechanical exfoliation using crystal or diamond-tip abrasion for epidermal renewal.
Laser Treatments command the highest equipment investment per installation; LED Therapy is climbing the fastest as at-home device substitution pressures professional maintenance pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of active pharmaceutical-grade peptides concentrates in Chinese contract facilities, while consumption clusters in high-income urban corridors across South Korea, the United States, and Germany. This geographic split shapes regulatory compliance investments and supply chain risk profiles for Western formulators.
United States
Los Angeles and New York dermatology networks drive demand for energy-based device protocols and exosome delivery systems. The FDA enforces cosmetic-drug boundary distinctions through active claims surveillance, forcing reformulation cycles for peptide-based topicals. Miami and Dallas med-spa chains are consolidating into multi-site purchasing organizations that compress vendor margins.
South Korea
Seoul's medical aesthetics corridor normalizes preventative maintenance regimens among consumers under 35, expanding addressable patient lifetime value. The MFDS maintains stringent documentation for quasi-drug anti-aging claims, elevating compliance costs for novel ingredient introductions. Gangnam district clinics command eight-week appointment waitlists for influencer dermatologist consultations.
Germany
Baden-Württemberg and Bavaria host precision manufacturing clusters for laser and radiofrequency device components. The EU MDR framework provides medical device classification clarity for peptide-based formulations, reducing regulatory ambiguity for commercialization timelines. Frankfurt and Munich dermatology networks are standardizing LED therapy protocols to lock in recurring consumable revenue streams.
Japan
Tokyo and Osaka anchor demand for ingestible collagen and NAD+ precursor supplements with clinical-positioned claims. The PMDA demands extended safety dossiers for quasi-drug anti-aging documentation, inflating barrier-to-entry costs for new ingredient platforms. Kanto region clinics integrate skin microbiome analysis with AI-driven formulation matching for protocol differentiation.
Brazil
São Paulo and Rio de Janeiro middle-class segments represent underserved demand for mid-tier anti-aging positioning. ANVISA operates a streamlined cosmetic registration pathway that enables faster market access than US or EU equivalents. Southeast Brazil distributors are building direct-to-consumer replenishment infrastructure to bypass retail margin extraction.
Global Anti-Aging Market Vendor Landscape
Top-tier vendors anchor clinical credibility through dermatological science divisions, while mid-tier players compete on ingredient platform licensing and speed-to-market execution. The vendor base stratifies across three tiers: multinational conglomerates with captive R&D infrastructure, regional specialists with biotech-derived ingredient platforms, and private-label contract manufacturers serving clinic networks. Strategic archetypes include science-driven credibility builders, device-hardware integrators, and direct-to-consumer data capturers. Competitive moves concentrate on M&A for peptide synthesis capabilities and strategic partnerships with Seoul-based clinic chains for protocol co-development.
Among French-headquartered conglomerates, L'Oréal S.A. exemplifies the science-driven archetype through its dermatological science division. German-based Beiersdorf AG and Japanese-listed Shiseido Company occupy positions within the regional specialist tier, each leveraging distinct geographic proximity to key regulatory and demand clusters. These three entities represent contrasting approaches to clinical credibility construction in a market where mechanistic proof-of-action documentation displaces marketing narrative.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Estée Lauder Companies Inc. |
| Procter & Gamble Co. |
| Unilever PLC |
| Beiersdorf AG |
| Shiseido Company |
| Johnson & Johnson |
| Coty Inc. |
| Amorepacific Corporation |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up dermatology networks in Los Angeles and Seoul are consolidating purchasing power through group procurement organizations, compressing vendor margins while enforcing standardized protocol pricing across multi-site clinic footprints.
Pricing Analysis
Margin tightening in professional energy devices reflects hardware commoditization as LED therapy platforms proliferate across German and South Korean clinic chains. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade laser systems from professional LED arrays and consumer-grade home devices. Cost-down pressure on consumable tips accelerates because dermatology networks demand volume rebates for exclusive supplier contracts. Med-spa technicians exhibit highest price sensitivity; Seoul's Gangnam district clinics show lowest sensitivity due to patient waitlist premiums.
Supply Chain Analysis
Returns and refurbishment flows for laser handpieces and LED arrays create secondary equipment markets that undercut new hardware pricing in Brazil and Southeast Asia. Active pharmaceutical-grade peptide synthesis concentrates in Chinese contract facilities, while precision laser component manufacturing clusters in Germany and Israel. Formulation chemistry draws from niacinamide bulk producers in India and antioxidant compound specialists in Switzerland. Single-source vulnerability pervades peptide raw materials, with over sixty percent of clinical-grade supply originating from Yangtze River Delta contract manufacturers. Distribution runs through dermatology network group purchasing organizations in North America and direct clinic relationships in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around multi-site dermatology networks, with FDA cosmetic-drug boundary enforcement and EU MDR documentation requirements forcing smaller formulators toward licensing deals or exit.
For Market Incumbents: To counter at-home device substitution capturing maintenance-phase patients, L'Oréal S.A. and Beiersdorf AG should deepen backward integration into peptide synthesis capabilities while locking exclusive supplier contracts with Seoul-based clinic chains for protocol co-development. For New Entrants and Emerging Players: Direct-to-consumer skin microbiome assessment platforms offer the most penetrable entry vector, targeting Brazil's underserved middle-class segments through ANVISA's streamlined registration pathway and subscription replenishment models that bypass retail margin extraction. For Investors and Strategic Acquirers: FDA warning letters targeting unsubstantiated peptide claims are the leading indicator that regulatory compliance capabilities will separate viable acquisition targets from distressed assets, with GMP-grade exosome manufacturing infrastructure representing the priority target archetype over the coming decade.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Synthesis Acquisition | Captures captive supply of active pharmaceutical-grade ingredients for clinical credibility. |
| Seoul Clinic Chain Partnership | Locks protocol standardization and recurring consumable revenue in the medical aesthetics corridor. |
| EU MDR Certification Pathway | Reduces regulatory ambiguity for peptide-based topicals entering German dermatology networks. |
| Direct-to-Consumer Microbiome Platform | Generates longitudinal patient data moats for AI-driven formulation personalization. |
| Brazil ANVISA Registration | Enables faster market access than FDA or EU equivalents for mid-tier positioning. |
Methodological Framework
FDA 510(k) filings, EU MDR technical documentation, and MFDS quasi-drug registration records formed the secondary backbone, supplemented by primary interviews with dermatology clinic procurement directors, formulation chemistry R&D leads, medical device regulatory affairs specialists, and group purchasing organization contract managers. Bottom-up revenue triangulation across skincare, device, and supplement segments was cross-validated against top-down market sizing from trade customs data and dermatology network capital expenditure disclosures.
Historical trendline analysis of clinic protocol adoption rates and ingredient platform licensing velocity informed growth trajectory modeling across the projection horizon. Segmentation dimensions included intervention modality, distribution channel infrastructure, end-user demographic, and technology platform type. CAGRs were derived from fitted growth curves incorporating peptide raw material cost trajectories and regulatory approval timeline distributions.
The model holds under stable FDA-EU regulatory divergence; deviation in PMDA documentation requirement inflation or Chinese peptide export restriction triggers would shift forecast boundaries. Practitioners should monitor MFDS quasi-drug claim enforcement and at-home device efficacy studies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Global Scar Removal Treatment Market
Skincare
Germany Skincare Product Market
Skincare
Ampoule Cream Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Skin Bioactive Market
Skincare
Ultrasound Skin Cleaners Market
Skincare
United Kingdom Skincare Market
Skincare
Africa Cosmeceutical Market
Skincare
Cosmeceutical Ingredients Market
Skincare
Dermal Regeneration Market
Skincare
India Skin Care Products Market
Skincare
Personalized Skin Care Products Market
Skincare
Global Healthcare Wipes Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Skincare Serums Market
Skincare
Skin Care Emulsion Market