
 Global IoT in Banking and Financial Services Market | 2026-2036
Global IoT in Banking and Financial Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT in Banking and Financial Services Market Outlook
Subscription-based API management is recalibrating how financial institutions procure IoT capabilities, shifting capital expenditure into recurring operational contracts. Microsoft Corporation leverages its Azure IoT stack to anchor cloud-native banking infrastructure across North American and European deployments. SAP specializes in ERP-integrated risk analytics that connect branch sensors to core banking systems. IBM Corporation competes through Watson IoT platforms that emphasize predictive maintenance for ATM fleets and vault monitoring networks.
IoT in banking and financial services encompasses sensor networks, edge gateways, and cloud analytics platforms that collect real-time data from ATMs, branches, vaults, and payment terminals to enable automated monitoring, predictive maintenance, and fraud detection. These systems typically operate on sub-100 millisecond latency thresholds for transaction validation and incorporate AES-256 encryption for data-in-transit between edge devices and centralized analytics engines. Fraud detection services command premium pricing due to regulatory mandates and quantifiable loss prevention, while mobile banking integration represents the fastest-expanding segment as smartphone-tethered IoT authentication displaces physical token systems. Retail banks constitute the dominant end-user category by deployment volume, though investment firms are emerging as high-margin clients demanding bespoke sensor analytics for trading floor environmental controls and secure document logistics.
The EU AI Act and GDPR impose algorithmic transparency and data minimization requirements on IoT systems processing biometric or behavioral data in European financial services. The SEC's cybersecurity disclosure rules and FFIEC examination guidelines in the United States mandate incident reporting timelines that compress IoT security architecture refresh cycles. India's RBI digital payment security framework and BIS device certification standards create compliance gateways for foreign platform vendors entering the domestic market. Stakeholders must monitor divergence between EU prescriptive AI regulation and US principles-based oversight, as this split will fragment R&D roadmaps and certification costs for multi-jurisdiction deployments.
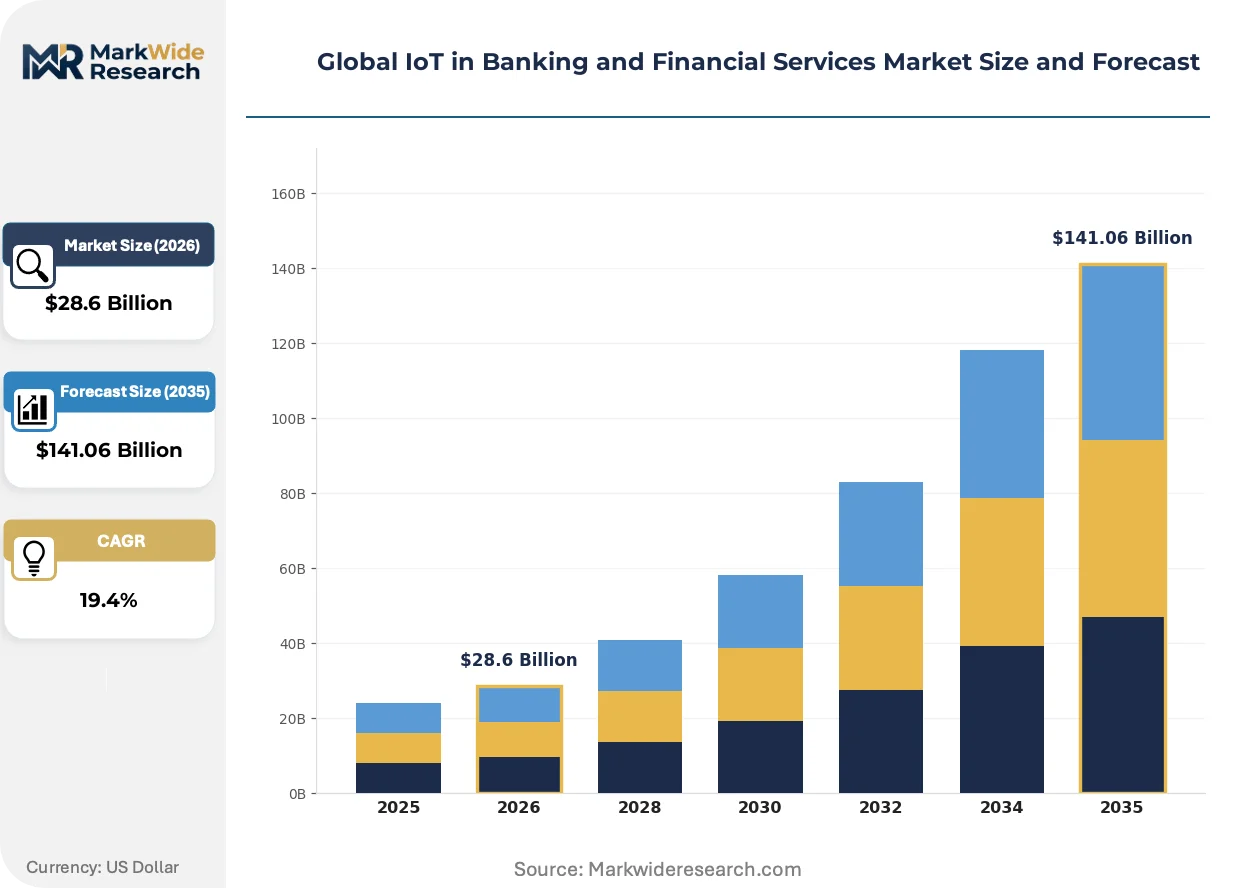
Market Dynamics
Subscription-based API procurement is compressing capital deployment cycles across retail banking and investment services, converting multi-year infrastructure projects into recurring operational expenditures that accelerate vendor switching.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European financial institutions must deploy explainable IoT analytics for biometric authentication, creating procurement urgency for compliant sensor platforms.
- India's RBI digital payment security framework:Device certification requirements for foreign vendors are accelerating domestic production partnerships and localized gateway deployments.
- Real-time ATM monitoring:Predictive maintenance networks are reducing cash replenishment costs and hardware downtime across high-volume branch networks in the United States and Germany.
Market Restraints
- GDPR data minimization compliance:Behavioral data collection from branch sensors requires costly architecture redesigns and limits cross-border analytics pooling.
- Edge hardware supply concentration:Semiconductor fabrication for sub-100 millisecond latency gateways remains concentrated in East Asian foundries, exposing deployment timelines to geopolitical disruption.
- AES-256 encryption overhead:Computational requirements for data-in-transit security increase edge device power consumption and thermal management costs.
Strategic Opportunities
- Investment firm trading floor analytics:Environmental controls and secure document logistics represent high-margin bespoke sensor deployments with limited vendor competition.
- Smartphone-tethered authentication:Mobile banking integration is displacing physical token systems, opening API licensing revenue streams for platform vendors.
- FFIEC examination guidelines:Compressed incident reporting timelines in the United States are forcing security architecture refreshes that favor cloud-native IoT stacks over on-premise legacy systems.
Industry Challenges
- Legacy core banking integration:SOAP-based mainframe protocols require costly middleware development to ingest RESTful sensor data streams from modern IoT platforms.
- Cross-jurisdiction certification divergence:The split between EU prescriptive AI regulation and US principles-based oversight fragments R&D roadmaps and multiplies compliance costs for vendors serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT in Banking and Financial Services Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $141.06 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fraud Detection, Mobile Banking, Customer Analytics, Risk Management Solution: Cloud Solutions, On-Premise Solutions, Integrated Platforms, API Management End User: Retail Banks, Investment Firms, Credit Unions, Insurance Providers Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing |
| Companies Covered | Oracle Corporation, Accenture, IBM Corporation, KORE Wireless, Capgemini, Microsoft Corporation, SAP, InHand Networks, Cisco Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT in Banking and Financial Services Market Strategic Shifts
Edge-native fraud detection architectures are compressing transaction validation windows below 50 milliseconds, eliminating round-trip latency to centralized cloud analytics and enabling real-time payment authorization at scale.
Tokenized biometric authentication is overtaking physical security dongles and SMS-based two-factor systems across retail banking deployments. German and Indian institutions are piloting palm-vein and behavioral gait recognition at ATM networks, eliminating card-present fraud vectors while reducing customer authentication friction. This shift is overtaking legacy authentication hardware vendors and forcing API-first security platform consolidation.
The EU AI Act's risk-based classification system for biometric processing is mandating algorithmic audit trails and human-in-the-loop overrides for high-risk IoT deployments. European banks must now document training data provenance and model drift metrics for branch sensor networks handling customer identification. Investment firms with trading floor environmental monitoring are accelerating procurement of explainable anomaly detection systems to preempt regulatory examination findings.
Consolidated vendor relationships are displacing point-solution procurement as financial institutions seek single-platform coverage for ATM fleets, branch sensors, and payment terminals. United States regional banks are bundling predictive maintenance, fraud analytics, and compliance reporting under unified cloud contracts with tier-one platform providers. This concentration favors vendors with pre-integrated ERP connectors and native regulatory reporting modules over specialized sensor hardware manufacturers.
Global IoT in Banking and Financial Services Market Segmentation
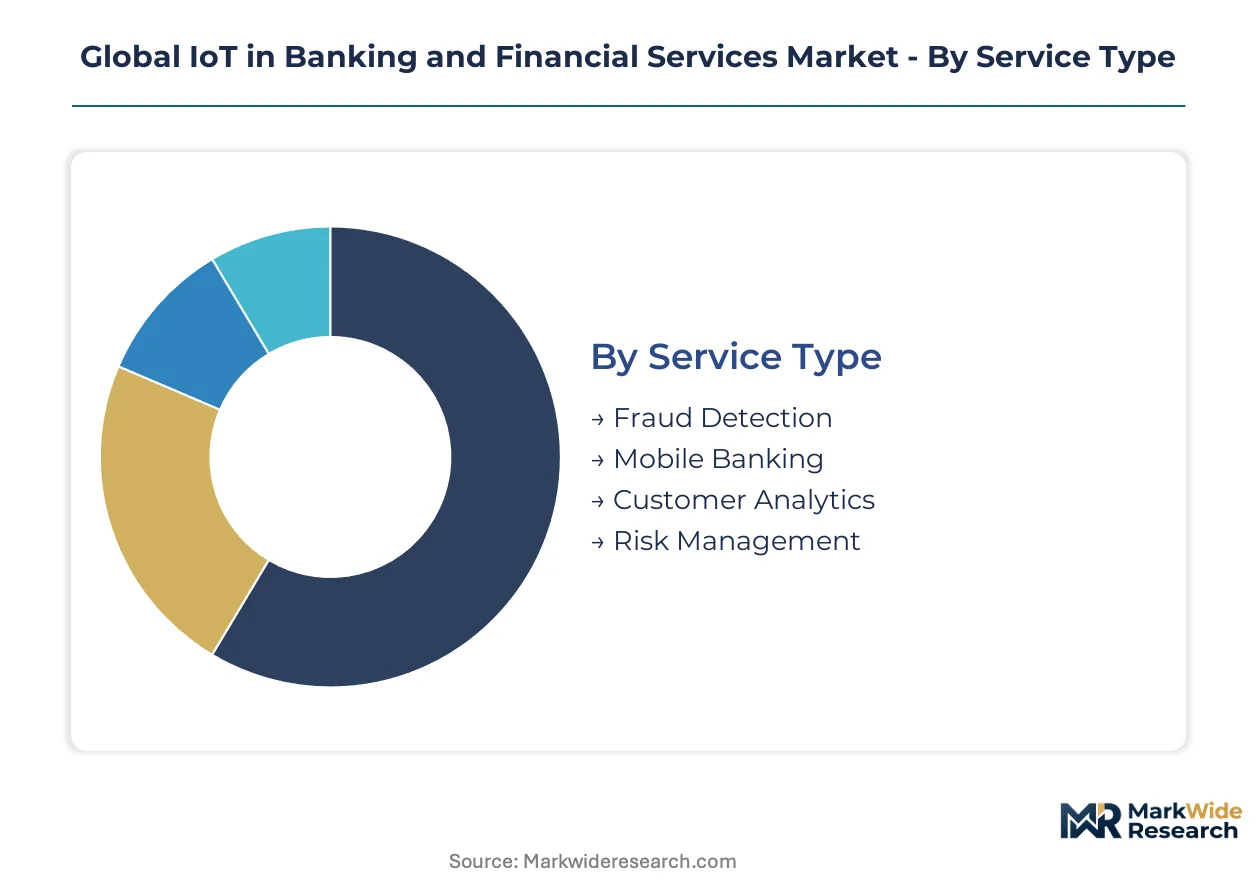
IoT deployment patterns in banking diverge sharply by capital intensity and regulatory exposure. Segmentation reveals where sensor infrastructure concentrates versus where API-first architectures are displacing legacy hardware.
Service Type:
Fraud detection commands the heaviest upfront sensor deployment costs, while mobile banking integration shifts expenditure toward recurring API licensing.
- Fraud Detection:Real-time biometric authentication systems process palm-vein and behavioral gait data at sub-50 millisecond latency. United States retail banks are consolidating procurement under unified cloud contracts to meet SEC cybersecurity disclosure timelines.
- Mobile Banking:Smartphone-tethered IoT authentication eliminates physical token infrastructure, converting capital expenditure into per-transaction API fees. German institutions are piloting this at scale to reduce card-present fraud vectors.
- Customer Analytics:Branch sensor networks tracking behavioral patterns face GDPR data minimization constraints in European deployments.
- Risk Management:ERP-integrated sensor analytics connect vault monitoring to core banking systems, requiring middleware investment for SOAP-based mainframe protocols.
Most installed capacity flows through Fraud Detection. Expansion is steepest in Mobile Banking.
Solution:
Deployment models split between capital-heavy on-premise vault monitoring and operationalized cloud-native stacks.
- Cloud Solutions:Azure IoT and Watson platforms anchor North American banking infrastructure, compressing incident reporting timelines under FFIEC guidelines. Subscription pricing converts multi-year projects into recurring contracts that accelerate vendor switching.
- API Management:Tokenized biometric authentication is displacing legacy security dongles across Indian retail banking under RBI digital payment security frameworks.
- On-Premise Solutions:Remains concentrated in high-security vault monitoring where AES-256 encryption overhead demands dedicated thermal management.
- Integrated Platforms:Single-vendor contracts bundling ATM fleets, branch sensors, and payment terminals are displacing point-solution procurement among United States regional banks.
Cloud Solutions carry the largest cumulative deployment value. API Management is climbing the fastest as authentication hardware phases out.
End User:
Retail banks dominate deployment volume, while investment firms concentrate spending in bespoke high-margin sensor analytics.
- Retail Banks:ATM fleet monitoring and branch sensor networks constitute the bulk of global IoT endpoints, with predictive maintenance reducing cash replenishment costs across high-volume networks in Germany and the United States.
- Investment Firms:Trading floor environmental controls and secure document logistics command premium pricing with limited vendor competition, driven by explainable anomaly detection requirements under EU AI Act audit mandates.
- Credit Unions:Smaller-scale deployments favor hybrid cloud architectures to balance compliance costs against capital constraints.
- Insurance Providers:Claims verification sensor networks are emerging as a secondary demand cluster, particularly in Indian motor and property lines.
Retail Banks absorb the majority of installed base. Investment Firms are gaining share fastest due to regulatory-driven procurement urgency.
Deployment:
Latency requirements and data sovereignty rules fragment architecture choices across geographies.
- Edge Computing:Sub-100 millisecond transaction validation demands localized processing, though semiconductor fabrication concentration in East Asian foundries exposes deployment timelines to geopolitical disruption.
- Hybrid Cloud:Balances real-time ATM monitoring with centralized compliance reporting, dominating European deployments navigating GDPR cross-border analytics restrictions.
- Private Cloud:Concentrated in investment firm trading floors where algorithmic audit trails for biometric processing are mandatory under EU AI Act risk classifications.
- Public Cloud:Cost-optimized tier for non-sensitive customer analytics, though AES-256 encryption overhead increases power consumption and thermal management costs.
Hybrid Cloud carries the broadest current footprint. Edge Computing is expanding most quickly as fraud detection architectures compress below 50 millisecond validation windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing IoT platform development toward jurisdictions with clearer compliance frameworks and lower certification friction. The divergence between EU prescriptive AI mandates and US principles-based oversight is fragmenting vendor R&D roadmaps and concentrating production partnerships in markets with harmonized standards.
United States
Real-time ATM monitoring networks and predictive maintenance systems are expanding across retail banking infrastructure. The SEC's cybersecurity disclosure rules and FFIEC examination guidelines compress incident reporting timelines and accelerate cloud-native IoT procurement. New York and Chicago financial districts host dense concentrations of edge gateway deployments for sub-100 millisecond transaction validation.
Germany
Palm-vein biometric authentication pilots at ATM networks are displacing card-present fraud vectors while reducing customer friction. The EU AI Act and GDPR impose algorithmic transparency and data minimization requirements on sensor networks processing behavioral data. Frankfurt's banking cluster drives demand for explainable anomaly detection systems that preempt regulatory examination findings.
India
Smartphone-tethered IoT authentication is scaling rapidly as RBI digital payment security frameworks mandate device certification for foreign vendors. Domestic production partnerships are accelerating localized gateway deployments to satisfy BIS standards. Mumbai and Bangalore financial hubs concentrate API-first security platform adoption among retail banks.
United Kingdom
Hybrid cloud architectures dominate as institutions balance real-time monitoring with GDPR cross-border analytics restrictions. The Financial Conduct Authority's operational resilience requirements are forcing security architecture refreshes that favor consolidated vendor relationships. London's investment banking corridor commands bespoke sensor analytics for trading floor environmental controls.
Japan
ERP-integrated risk analytics are connecting branch sensors to core banking systems under METI digital transformation guidelines. Tokenized biometric authentication is overtaking legacy security dongles at metropolitan ATM networks. Tokyo and Osaka financial districts concentrate demand for middleware solutions bridging SOAP-based mainframe protocols with RESTful sensor streams.
Global IoT in Banking and Financial Services Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with cloud-native platform vendors consolidating procurement under unified contracts while hardware specialists retain position in high-security vault monitoring. The vendor landscape tiers between global technology conglomerates with pre-integrated ERP connectors and regional specialists with localized certification expertise. Two strategic archetypes dominate: subscription-based API management platforms and edge-native fraud detection architects. Competitive positioning hinges on M&A activity to acquire middleware capabilities and strategic partnerships with domestic system integrators for jurisdiction-specific compliance.
Within the cloud-platform tier, Microsoft Corporation and IBM Corporation anchor North American and European banking infrastructure deployments. SAP occupies a position among ERP-integrated specialists connecting branch sensors to core banking systems. These three exemplify the consolidation trajectory as regional banks bundle predictive maintenance, fraud analytics, and compliance reporting under single-vendor contracts.
| Leading Market Players |
|---|
| Oracle Corporation |
| Accenture |
| IBM Corporation |
| KORE Wireless |
| Capgemini |
| Microsoft Corporation |
| SAP |
| InHand Networks |
| Cisco Systems, Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive cloud infrastructure integration anchors both supply positioning and pricing power for IoT platform vendors serving financial institutions. Microsoft Azure and IBM Watson deployments in North American banking compress procurement timelines while extracting recurring subscription premiums that displace capital-heavy on-premise vault monitoring systems.
Pricing Analysis
Direct-to-OEM discount structures dominate cloud-native IoT procurement, with tiered pricing separating premium fraud-detection bundles from standard ATM monitoring tiers. Price differentiation rests on AES-256 encryption certification levels and API call volume commitments. Cost compression in standard-tier branch sensor deployments is intensifying because semiconductor supply constraints force gateway hardware premiums. Credit unions exhibit highest price sensitivity due to capital constraints, while investment firms accept premium positioning for bespoke trading floor analytics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for sub-100 millisecond latency semiconductor fabrication, exposing edge gateway deployment timelines to geopolitical disruption. Raw material dependencies include advanced node silicon wafers, thermal management components, and AES-256 encryption chipsets. Tariff exposure runs through East Asian foundry concentration against US and EU banking demand centers. Distribution runs through tier-one cloud platform vendors with pre-integrated ERP connectors rather than specialized hardware manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in fraud-detection premium tiers as subscription-based API management displaces capital expenditure models and compresses vendor switching costs for financial institutions.
For Market Incumbents: Anticipate consolidation pressure from ERP-integrated specialists acquiring middleware capabilities to bridge SOAP-based mainframe protocols. Defensive moves require deepening captive cloud infrastructure in Frankfurt and Mumbai financial hubs while pre-certifying platforms under RBI digital payment security frameworks and EU AI Act algorithmic transparency mandates. Channel control through domestic system integrator partnerships represents the critical lever against emerging API-first entrants. For New Entrants and Emerging Players: Regional credit unions in the United States represent an underserved buyer archetype with limited vendor competition and compliance-driven procurement urgency. White-space targets include hybrid cloud architectures balancing real-time ATM monitoring against capital constraints, plus explainable anomaly detection systems for investment firm trading floors. A channel partnership route through banking technology consultants accelerates credibility without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for middleware specialists bridging legacy core banking systems to RESTful sensor streams because SOAP protocol translation remains a capability scarcity with limited vendor competition. Long-term viability favors acquisition targets with pre-integrated regulatory reporting modules and jurisdiction-specific certification expertise spanning GDPR, SEC cybersecurity disclosure rules, and RBI frameworks. The signal to watch is compressed FFIEC examination timelines forcing regional banks toward consolidated single-vendor contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure IoT and Watson deployments anchor North American banking infrastructure under unified cloud contracts. |
| Regulatory Certification Investment | EU AI Act algorithmic transparency mandates create procurement urgency for explainable biometric authentication systems. |
| Strategic Partnership | Domestic system integrator alliances in India satisfy BIS device certification requirements for foreign vendors. |
| Acquisition of Specialist Firm | Middleware capabilities bridging SOAP mainframe protocols to RESTful sensor streams command scarcity premiums. |
| Geographic Expansion | Frankfurt and Mumbai financial hubs concentrate demand for ERP-integrated risk analytics and palm-vein authentication pilots. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with IoT platform architects, banking technology procurement officers, regulatory compliance leads, and edge gateway manufacturing specialists. Secondary validation draws from SEC cybersecurity disclosure filings, RBI digital payment security framework documentation, EU AI Act implementation guidance, FFIEC examination guidelines, and hyperscaler banking vertical capex disclosures. Bottom-up sensor deployment tallies triangulate against top-down financial institution IT spending surveys.
Granularity-level modeling operates at service type, solution architecture, end-user institution category, and deployment topology dimensions across the projection horizon. CAGRs derive from segment-specific adoption curves weighted by regulatory mandate enforcement timelines and cloud infrastructure penetration rates. Forecast inputs incorporate edge computing latency requirements, AES-256 encryption hardware cost trajectories, and subscription pricing conversion rates from capital expenditure baselines.
Underlying measurement precision varies by segment; mobile banking integration and fraud detection carry tighter precision than emerging insurance claims verification applications. Forecasts reflect documented assumptions about regulatory enforcement consistency, semiconductor supply normalization, and cross-border data pooling permissions under GDPR. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Europe Machine Learning in Banking Market
Banking
Embedded Banking Market
Banking
US Investment Banking Market
Banking
Data Analytics in Banking Market
Banking
Australia Data Analytics in Banking Market
Banking
Latin America Neo Banking Services Market
Banking
E-Banking Market
Banking
Global Chatbot for Banking Market
Banking
APAC Banking-As-A-Service Market
Banking
Smart Banking Solutions Market
Banking
Open Banking Market
Banking
Banking Smart Cards Market
Banking
Investment Banking and Trading Services Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
Payment Bank Solutions Market
Banking
Onsite and Offsite Atms Market