
 Global Virtualization Software Market | 2026-2036
Global Virtualization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtualization Software Market Foresight
Container-to-virtual-machine convergence is reconfiguring how enterprises architect hybrid workloads, blending Kubernetes orchestration with legacy hypervisor estates. Broadcom VMware leverages its installed base to sustain enterprise renewals across on-premises and cloud-connected deployments. Red Hat anchors open-source virtualization through its KVM-based stack, competing directly with proprietary alternatives in regulated industries. Microsoft differentiates by embedding virtualization into Azure Stack and Windows Server, extending its operating-system dominance into infrastructure abstraction.
Virtualization software creates logical compute, storage, and network resources abstracted from physical hardware through hypervisors, container runtimes, and software-defined controllers, typically operating with sub-5-millisecond latency targets for real-time workload migration. Its primary purpose is maximizing hardware utilization while enabling elastic scaling and disaster recovery across distributed environments. Server virtualization retains the largest revenue pool as enterprises maintain x86 consolidation programs, though network virtualization is expanding fastest where telcos rebuild core infrastructure for 5G slicing and edge distribution. Desktop virtualization carries thinner margins except in government and BFSI contracts where data-sovereignty requirements mandate on-premises VDI deployment.
The US Federal Risk and Authorization Management Program (FedRAMP) and the EU Cybersecurity Act shape procurement criteria for virtualization platforms handling sensitive workloads, forcing vendors to certify under Common Criteria or sovereign cloud frameworks. China's MIIT mandates GB-standard compliance for virtualization deployed in critical information infrastructure, restricting cross-border data flows through certified domestic hypervisor stacks. ISO/IEC 27001 and the NIST Cybersecurity Framework further govern how providers architect multi-tenant isolation and encryption key management. Stakeholders must monitor divergent sovereignty requirements as jurisdictions fragment certification regimes and demand geographically bounded control planes.
Market Dynamics
Container-to-virtual-machine convergence is reconfiguring enterprise infrastructure procurement, forcing vendors to unify Kubernetes orchestration with legacy hypervisor estates under single control planes. Financial services firms and automotive OEMs are consolidating vendor relationships around software-defined stacks that span on-premises and edge deployments.
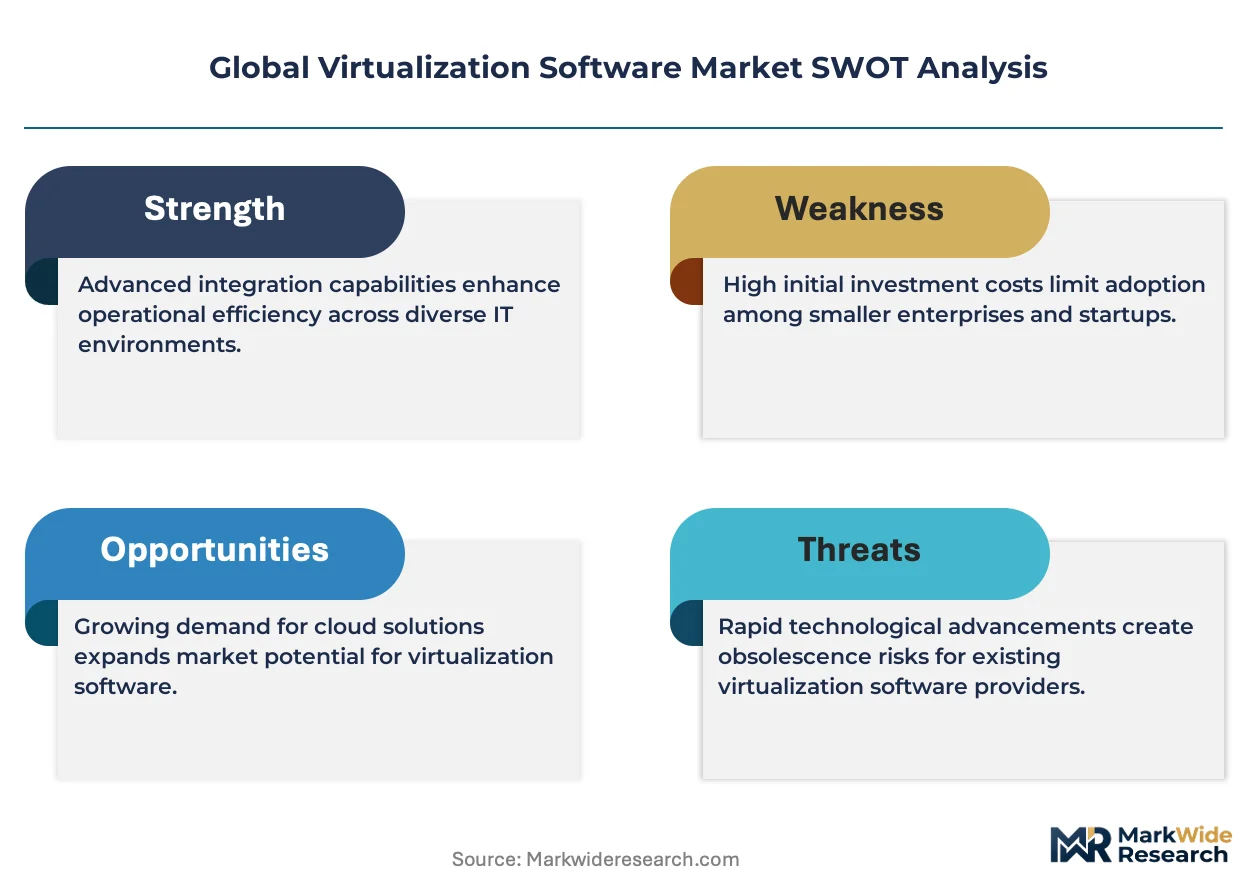
Growth Catalysts
- EU AI Act operational resilience mandates:Critical digital infrastructure providers must deploy certified virtualization platforms with automated failover capabilities, accelerating replacement of legacy hypervisor estates.
- Industrial automation consolidation:German automotive OEMs are unifying factory-floor and enterprise data center workloads through software-defined infrastructure, compressing procurement cycles for integrated stacks.
- 5G network slicing architectures:Telecommunications operators are rebuilding core infrastructure with network function virtualization to support edge-distributed workloads and sub-10-millisecond latency requirements.
Market Restraints
- Proprietary licensing cost structures:Enterprise renewals for commercial hypervisor stacks consume 18-25% of infrastructure budgets, constraining migration to modern orchestration platforms.
- Cross-border data flow restrictions:China's MIIT GB-standard compliance mandates domestic hypervisor certification, fragmenting vendor economies of scale across sovereign cloud deployments.
- Skill scarcity in hybrid orchestration:Organizations lack personnel proficient in both legacy VMware administration and Kubernetes cluster management, slowing consolidation projects.
Strategic Opportunities
- India's data center expansion:The country's PLI scheme for electronics manufacturing is attracting hyperscale construction, creating demand for software-defined infrastructure with local support capabilities.
- Confidential computing integration:Hardware-based trusted execution environments are converging with virtualization layers to secure multi-tenant AI training workloads in regulated industries.
- FedRAMP-authorized sovereign clouds:US federal procurement pathways are opening for domestic cloud providers offering certified virtualization platforms with geographically bounded control planes.
Industry Challenges
- Common Criteria certification timelines:Vendors face 12-18 month evaluation periods for high-assurance security certifications required by defense and intelligence agencies.
- Legacy workload migration complexity:Mainframe and bare-metal applications resist containerization, forcing expensive refactoring or persistent VM hosting alongside modern orchestration.
- Multi-cloud interoperability gaps:Proprietary APIs across AWS, Azure, and Google Cloud complicate unified management of distributed virtualization estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtualization Software Market |
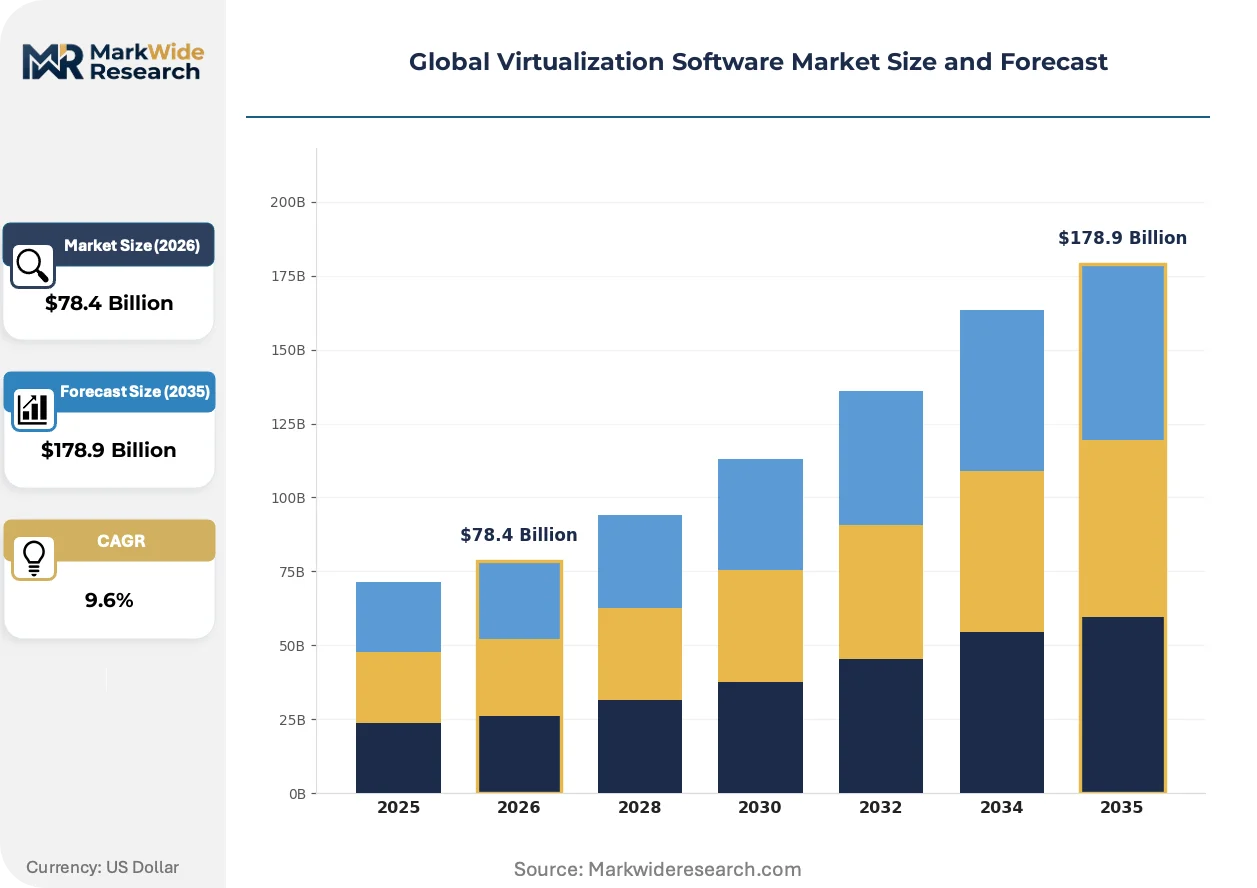
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $178.9 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Server Virtualization, Desktop Virtualization, Application Virtualization, Network Virtualization, Storage Virtualization, Data Virtualization Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-premises, Hosted, Managed Services End User Industry: BFSI, Telecommunications, Government Agencies, Education Institutions, Media & Entertainment, Manufacturing License Type: Perpetual License, Subscription License, Freemium, Open Source, Pay-as-you-go, Enterprise License |
| Companies Covered | Omnissa, Red Hat, Broadcom VMware, Oracle, Google, Microsoft, IBM, Scale Computing, Citrix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtualization Software Market Shifts & Advancements
Virtualization architectures are fragmenting across three simultaneous evolution paths: hypervisor abstraction, container-native platforms, and confidential computing integration. Vendors must now engineer for workload portability across all three without sacrificing security isolation or operational simplicity.
Kubernetes is hybridizing with traditional hypervisor estates through unified control planes that manage both container pods and virtual machines from single orchestration layers. Financial services firms in Frankfurt and Singapore are deploying these converged stacks to consolidate legacy Windows Server workloads alongside cloud-native microservices. This architectural fusion is compressing vendor margins as enterprises demand single-vendor accountability for mixed estates.
The EU NIS2 Directive is mandating operational resilience testing for critical infrastructure operators, requiring virtualization platforms to demonstrate automated recovery within four hours of cyber incidents. German energy utilities and Dutch water management authorities are procuring only certified platforms with built-in disaster orchestration. Vendors are reengineering control plane architectures to satisfy these continuity requirements ahead of enforcement deadlines.
Consumption-based licensing is displacing perpetual enterprise agreements as hyperscale cloud providers penetrate on-premises infrastructure. Brazilian manufacturing conglomerates and Saudi healthcare networks are adopting pay-per-use models for software-defined compute and storage. This shift concentrates purchasing power with CIOs who can demonstrate variable cost alignment to workload volatility rather than capital efficiency metrics.
Global Virtualization Software Market Segmentation
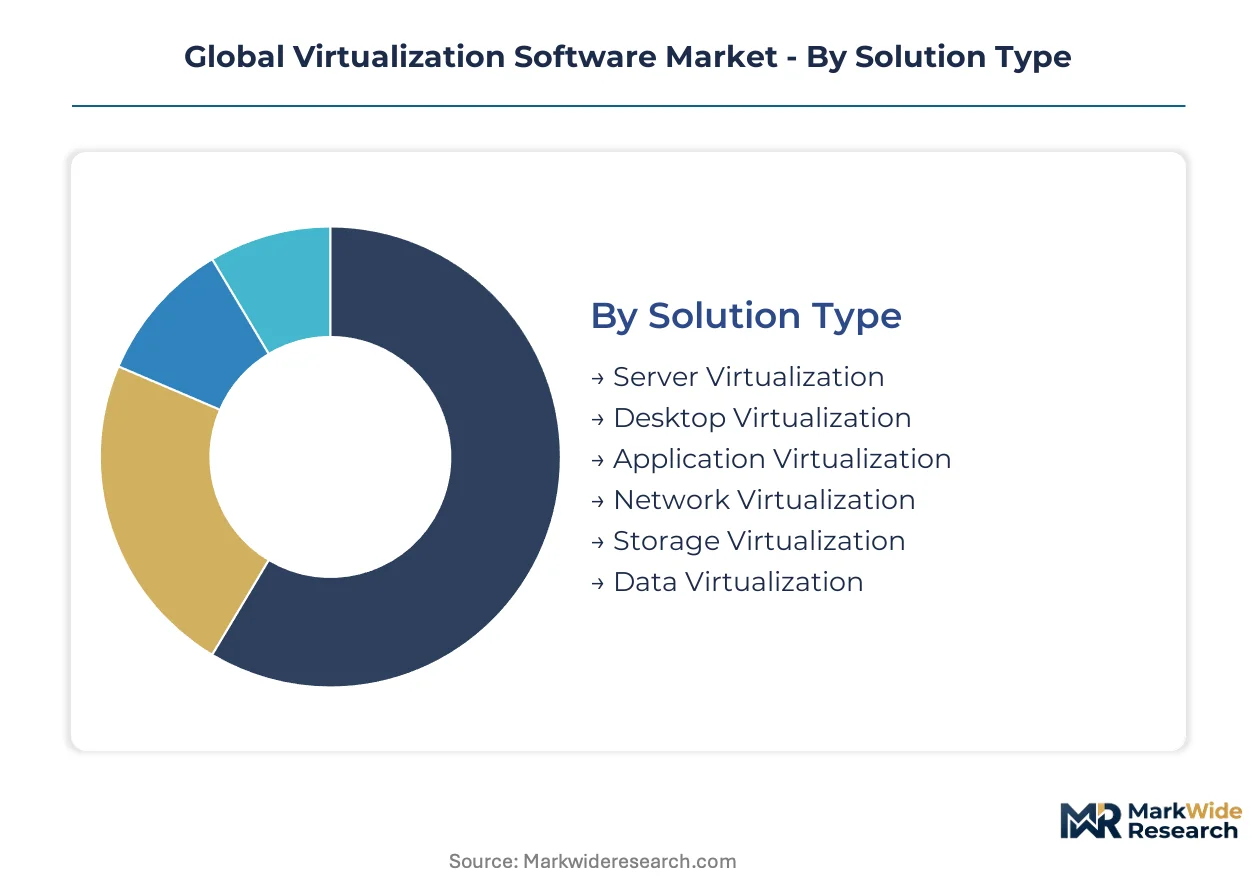
Virtualization software procurement patterns diverge sharply across deployment contexts, with cycle times ranging from multi-year enterprise agreements to monthly consumption-based contracts. Understanding these segment dynamics reveals where vendor margins concentrate and where replacement technologies gain traction fastest.
Solution Type:
Server virtualization commands the longest replacement cycles at seven to ten years, while network virtualization refreshes every three to four years as telcos rebuild for 5G slicing.
- Server Virtualization:Hypervisor abstraction of x86 compute resources remains the foundational layer for data center consolidation. German automotive OEMs and financial services firms in Frankfurt sustain this segment through legacy workload hosting and disaster recovery mandates under EU NIS2 Directive requirements.
- Network Virtualization:Software-defined networking and network function virtualization enable dynamic traffic engineering across distributed infrastructure. Telecommunications operators in India and Brazil are deploying these stacks to support edge-distributed 5G workloads with sub-10-millisecond latency targets.
- Desktop Virtualization:Virtual desktop infrastructure delivers centralized endpoint management for regulated industries. Government agencies in the US and BFSI contracts in Singapore drive demand where data sovereignty requires on-premises VDI deployment.
- Application Virtualization:Container and application streaming technologies decouple software from underlying operating systems. Manufacturing facilities in Saudi Arabia use these tools to standardize legacy industrial control applications across heterogeneous hardware.
- Storage Virtualization:Abstraction layers pool physical storage into logical volumes for simplified management. Healthcare networks in Brazil are consolidating storage tiers through software-defined controllers to reduce capital expenditure.
- Data Virtualization:Federated query engines provide unified access across distributed data sources without physical consolidation. Energy utilities in the Netherlands deploy these platforms to integrate operational technology and enterprise data lakes.
Server virtualization anchors the volume base while network virtualization gains share at the steepest rate.
Deployment Model:
Cost tiers separate capital-intensive on-premises installations from variable operating expenditures, with hybrid cloud capturing mid-budget deployments seeking workload portability.
- On-premises:Self-managed infrastructure within enterprise data centers delivers maximum control over security configurations. Defense agencies and intelligence organizations in the US require FedRAMP-authorized on-premises virtualization for classified workloads.
- Hybrid Cloud:Unified management across private infrastructure and public cloud resources enables workload mobility. Financial services firms in Singapore and manufacturing conglomerates in Germany are standardizing on hybrid architectures to satisfy data residency requirements.
- Public Cloud:Shared multi-tenant infrastructure delivered by hyperscale providers eliminates capital expenditure. Indian startups and media companies in Brazil are defaulting to public cloud virtualization for rapid scaling without facility investment.
- Private Cloud:Single-tenant cloud infrastructure dedicated to one organization combines control with service delivery models. Saudi healthcare networks and UAE government entities procure private cloud virtualization to satisfy sovereign data requirements.
- Hosted:Third-party data center providers manage physical infrastructure while customers retain software control. Education institutions in Australia and small enterprises in South Korea leverage hosted virtualization to access enterprise-grade capabilities.
- Managed Services:Full operational outsourcing of virtualization infrastructure to specialized providers. Telecommunications operators in Brazil are offloading complex Kubernetes-hypervisor convergence to managed service partners.
On-premises deployment retains the largest installed base though hybrid cloud is climbing the fastest as enterprises navigate sovereignty requirements.
End User Industry:
Application maturity varies dramatically, with telecommunications and BFSI running production-grade container-hypervisor convergence while education lags in legacy virtualization.
- BFSI:Banking, financial services, and insurance institutions demand certified platforms with automated failover for trading and core banking systems. Singaporean banks and German insurers are consolidating vendor relationships around software-defined stacks spanning on-premises and edge.
- Telecommunications:Network operators require virtualization for 5G core, radio access network disaggregation, and edge computing. Indian and Brazilian telcos are rebuilding infrastructure with network function virtualization to support network slicing and low-latency services.
- Government Agencies:Public sector entities mandate certified platforms with sovereign control planes and geographic data boundaries. US federal agencies procure only FedRAMP-authorized virtualization, while Chinese government bodies require MIIT GB-standard compliance.
- Manufacturing:Industrial automation and automotive production lines converge factory-floor and enterprise workloads. German automotive OEMs are unifying operational technology and information technology through software-defined infrastructure.
- Education Institutions:Universities and school districts deploy desktop virtualization for standardized lab environments and remote learning. Australian and South Korean institutions are migrating from legacy VDI to cloud-native virtual desktop solutions.
- Media & Entertainment:Content production and distribution workflows require high-performance graphics virtualization and elastic rendering capacity. Post-production houses in the US and game developers in Japan leverage GPU virtualization for distributed creative teams.
BFSI contributes the largest revenue pool while telecommunications is expanding most quickly through 5G infrastructure investment.
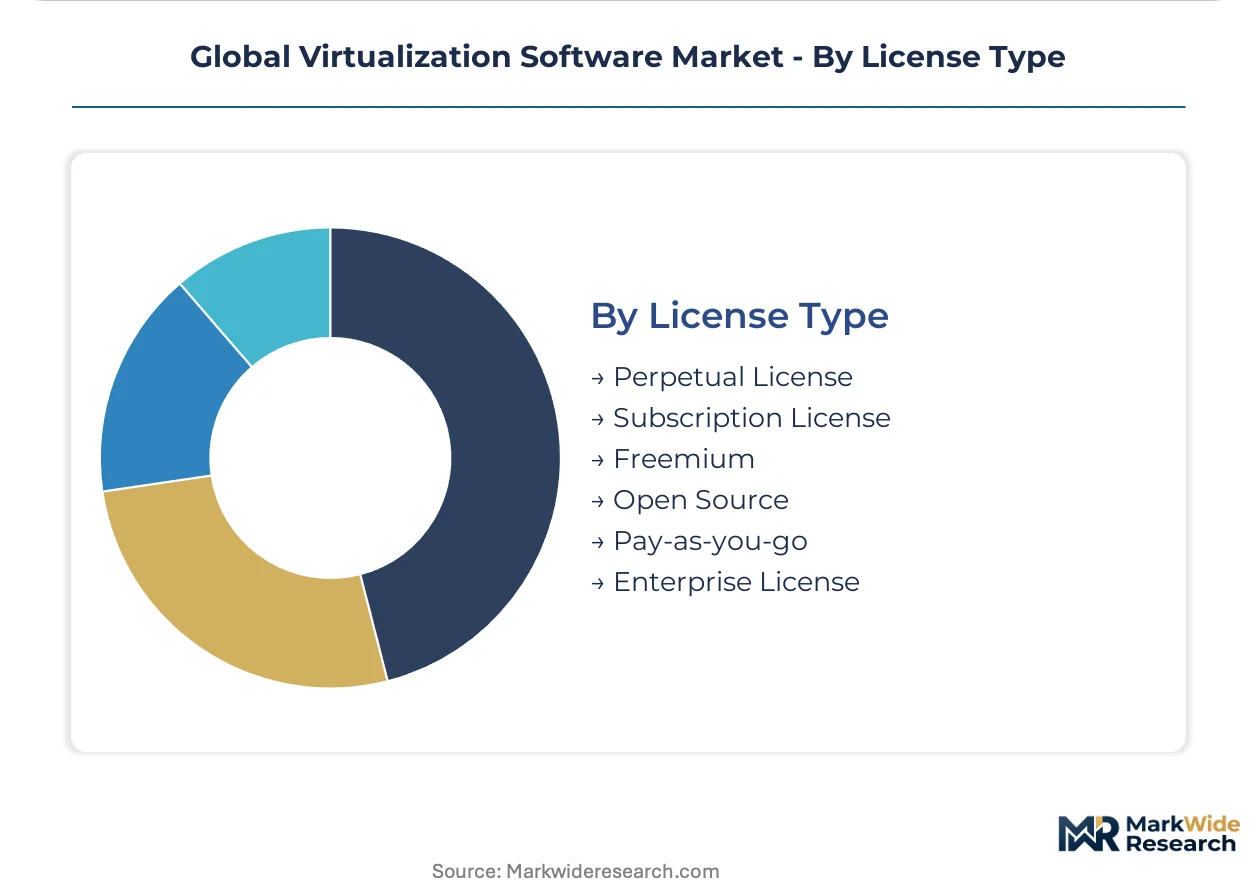
License Type:
Customer procurement sophistication separates enterprise procurement teams negotiating perpetual agreements from development teams consuming pay-as-you-go resources.
- Enterprise License:Comprehensive agreements covering unlimited or high-volume deployment across organizational units. Multinational manufacturers in Germany and healthcare systems in Saudi Arabia standardize on enterprise licensing for predictable budgeting.
- Subscription License:Time-bound access with regular payments and continuous update entitlements. Mid-market BFSI firms in Singapore and technology companies in India prefer subscription models for operational expenditure alignment.
- Perpetual License:One-time purchase with optional maintenance renewals for long-term infrastructure. Government agencies in the US and defense contractors favor perpetual licenses for multi-year program stability.
- Pay-as-you-go:Consumption-based billing tied to actual resource utilization. Brazilian manufacturers and Indian e-commerce platforms adopt pay-as-you-go licensing for workload volatility.
- Open Source:Community-developed platforms with no licensing fees and optional commercial support. Technology startups in Europe and research institutions in Australia build on KVM and Xen without proprietary constraints.
- Freemium:Limited-feature free tiers with paid upgrades for production capabilities. Individual developers and small education institutions in South Korea evaluate freemium offerings before enterprise commitment.
Enterprise license structures dominate current revenue though subscription and pay-as-you-go models are gaining share fastest as cloud consumption patterns penetrate on-premises infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services firms and automotive OEMs concentrate procurement authority in Germany, while telecommunications operators in India and Brazil drive network virtualization investment. Sovereign cloud requirements fragment vendor economics across jurisdictions with divergent certification regimes.
United States
Defense agencies and intelligence organizations demand FedRAMP-authorized platforms for classified workloads. The Federal Risk and Authorization Management Program shapes procurement criteria for sensitive infrastructure. Northern Virginia data center clusters host the largest concentration of certified virtualization deployments serving federal contracts.
Germany
Automotive OEMs and industrial automation firms consolidate factory-floor and enterprise workloads through software-defined infrastructure. The EU NIS2 Directive mandates operational resilience testing with automated recovery within four hours. Frankfurt financial services clusters deploy converged Kubernetes-hypervisor stacks to satisfy continuity requirements.
China
Critical information infrastructure operators must deploy MIIT GB-standard certified domestic hypervisor stacks. The Ministry of Industry and Information Technology restricts cross-border data flows through certification mandates. Beijing and Shanghai technology corridors concentrate state-backed cloud providers building sovereign control planes.
India
Telecommunications operators rebuild core infrastructure with network function virtualization to support 5G slicing and edge distribution. The Production Linked Incentive scheme for electronics manufacturing attracts hyperscale data center construction. Mumbai and Bangalore clusters drive demand for software-defined infrastructure with local support capabilities.
Brazil
Manufacturing conglomerates and telecommunications operators adopt consumption-based licensing for software-defined compute and storage. ANVISA compliance requirements shape healthcare network procurement for patient data isolation. São Paulo industrial corridors consolidate vendor relationships around pay-per-use infrastructure models.
Global Virtualization Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The market structure concentrates around incumbent platform vendors with installed base leverage, open-source challengers, and cloud-native entrants. Strategic archetypes include hypervisor incumbents defending renewal streams, Kubernetes-native platforms capturing cloud migration, and sovereign cloud specialists addressing data residency mandates. Competitive moves center on unified control plane development and consumption-based licensing transitions.
Within the incumbent tier, Broadcom VMware and Microsoft exemplify platform vendors leveraging operating-system dominance and enterprise relationships. Red Hat occupies a position as the anchor open-source alternative through its KVM-based stack. These three represent the primary competitive anchors around which procurement decisions consolidate in regulated industries.
| Leading Market Players |
|---|
| Omnissa |
| Red Hat |
| Broadcom VMware |
| Oracle |
| Microsoft |
| IBM |
| Scale Computing |
| Citrix |
| Others |
Supply & Pricing Matrix
Regulatory chokepoint exposure through divergent sovereign certification regimes determines both pricing tier spreads and supply chain shape across virtualization software procurement. Buyers in Germany, China, and the United States face fragmented compliance costs that compress margins at the standard tier while inflating premiums for certified platforms.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate enterprise virtualization procurement, particularly for hardware-integrated licensing. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized sovereign clouds from commodity public cloud instances and open-source alternatives. Price differentiation hinges on certification grade and geographic delivery cost, with EU NIS2-compliant platforms commanding substantial premiums. Pricing pressure stems from hyperscale cloud providers penetrating on-premises infrastructure with consumption-based models. Mid-market manufacturing conglomerates in Brazil exhibit highest price sensitivity, while defense agencies in the United States demonstrate lowest sensitivity due to mandated security requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates virtualization software supply chain risk through semiconductor component dependencies. Hardware manufacturing concentrates in Taiwan, South Korea, and the United States, with control plane development anchored in India and Ireland. Raw material dependencies include advanced silicon wafers, specialized memory modules, and trusted platform modules for confidential computing. Single-source vulnerability persists for domestic hypervisor certification in China under MIIT GB-standard mandates. Distribution runs through direct enterprise sales teams, hyperscale cloud marketplaces, and regional systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around German automotive OEMs and financial services firms consolidating vendor relationships, compressing supplier margins and demanding single-accountability contracts.
For Market Incumbents: Insulate renewal streams by embedding virtualization deeper into sovereign cloud frameworks with FedRAMP and EU NIS2 pre-certification. Kubernetes-native platforms threaten hypervisor incumbents through converged orchestration; backward integration into confidential computing hardware partnerships secures differentiation. Channel control through managed service provider certification programs locks in enterprise procurement pathways. For New Entrants and Emerging Players: India's data center construction corridors present underpenetration for software-defined infrastructure with local support capabilities. Brazilian manufacturing and telecommunications sectors offer white-space for consumption-based licensing models absent legacy entanglement. Target sovereign cloud specialists in Saudi Arabia and UAE seeking MIIT-equivalent domestic certification through partnership with regional systems integrators. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with installed base leverage and certification moats. Long-term viability centers on unified control plane capabilities spanning Kubernetes and hypervisor estates. Acquisition targets should demonstrate FedRAMP authorization progress or EU NIS2 pre-compliance. Watch for hyperscale cloud providers achieving on-premises hardware certification as inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Integration | Hardware-based trusted execution environments secure multi-tenant AI training for BFSI clients under EU AI Act mandates. |
| Sovereign Cloud Certification | FedRAMP authorization opens federal procurement pathways for domestic providers with geographically bounded control planes. |
| Kubernetes-Hypervisor Convergence | Unified control planes capture hybrid workload demand from Frankfurt financial services consolidating legacy and cloud-native estates. |
| Consumption-Based Licensing Transition | Pay-per-use models align with Brazilian manufacturing volatility while concentrating purchasing power with cost-optimization-focused CIOs. |
| Regional Support Capability Buildout | Local engineering presence satisfies India's PLI-linked data center demand and accelerates telco 5G infrastructure deployment cycles. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with virtualization platform engineering leads, enterprise IT procurement officers, channel partner technical directors, and sovereign cloud operations specialists; and secondary validation against SEC filings from hyperscale providers, hyperscaler capex disclosures, EU regulatory enforcement documentation, and certification authority databases. Bottom-up sizing of deployment volumes triangulated with top-down market expenditure estimates across solution type, deployment model, and end-user industry segments.
Forecast inputs incorporated virtualization penetration rates across on-premises, hybrid cloud, and public cloud deployment models, with segmentation by organization size, vertical regulatory intensity, and regional adoption patterns. CAGRs were derived through trend extrapolation of historical infrastructure refresh cycles and forward projection of 5G network slicing investment, EU NIS2 compliance deadlines, and confidential computing hardware availability. Industry-specific inputs included telecommunications operator NFV deployment timelines and automotive OEM software-defined infrastructure consolidation schedules.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting data center financing costs or semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timing and certification pathway completion rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Europe Application Modernization Services Market
Software & Services
Software-Defined Machine Market
Software & Services
US Digital Marketing Software Market
Software & Services
Global Reporting Software Market
Software & Services
Lead Management Software Market
Software & Services
US Software Consulting Market
Software & Services
Global Internal Communications Software Market
Software & Services
Multivariate Testing Software Market
Software & Services
Medical E-Commerce Software Market
Software & Services
Asia-Pacific Printing Software Market
Software & Services
Generative Design Software Market
Software & Services
Global Mobile Application Market
Software & Services
Global Web Scraper Software Market
Software & Services
Cursor Reviewer Market
Software & Services
Trading Software Market
Software & Services
Sales Intelligence Software Market