
 Image Analysis Software Market | 2026-2036
Image Analysis Software Market Size, Share, and Industry Trends Forecast 2026-2036
Image Analysis Software Market Outlook
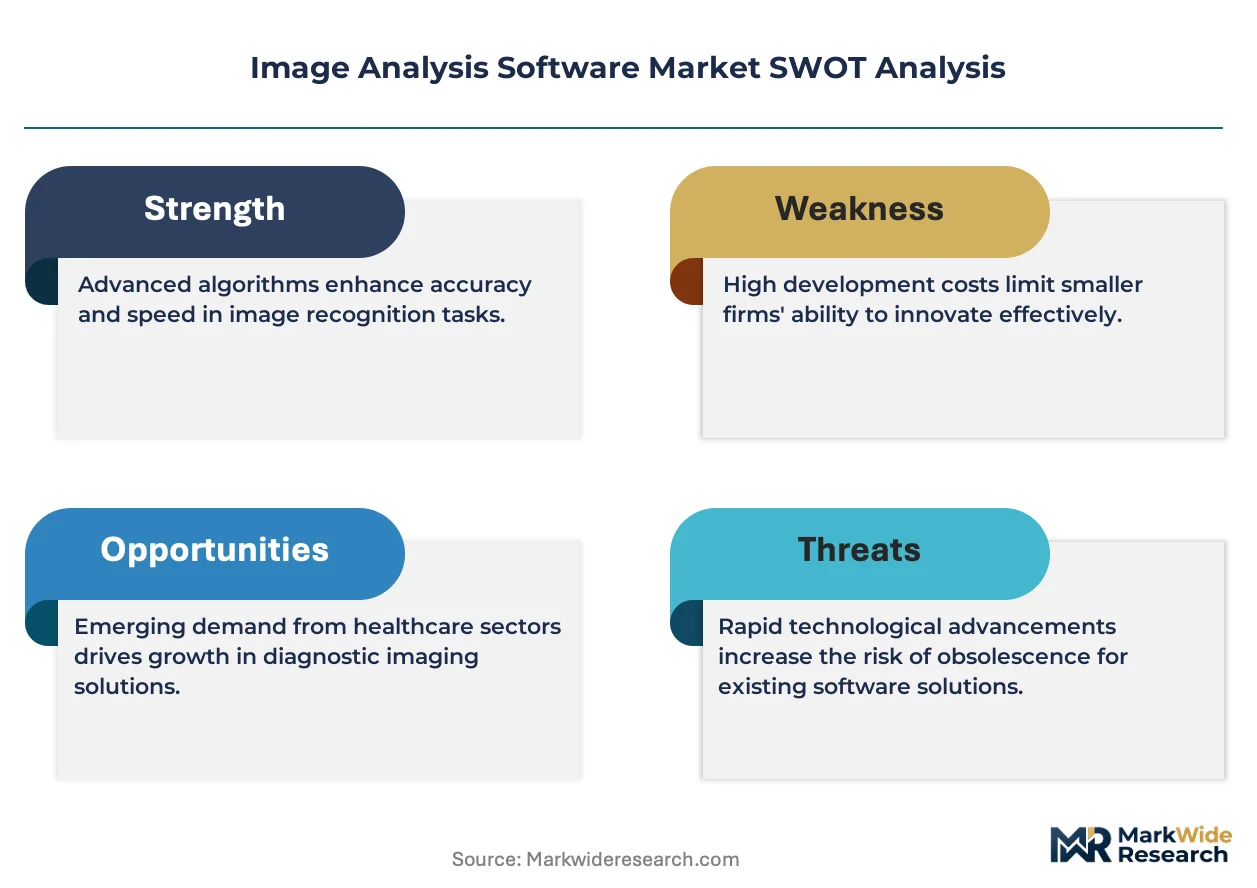
Modular subscription packaging is realigning how healthcare providers and research institutions evaluate image analysis platforms. GE HealthCare Technologies Inc. leverages its installed base of imaging hardware to bundle software modules at point-of-sale. Syte anchors its growth in visual AI for retail, competing on speed-to-deployment against heavier enterprise suites. Quibim specializes in quantitative imaging biomarkers for clinical trials, occupying a narrow but defensible niche in pharmaceutical research workflows.
Image analysis software encompasses computational platforms that process, quantify, and interpret visual data through algorithmic pipelines, typically operating on pixel matrices with spatial resolutions from micrometers in microscopy to sub-millimeter in computed tomography. These systems serve industrial and commercial purposes spanning automated defect detection in manufacturing lines, pathological tissue classification, and real-time object tracking in surveillance networks. Cloud-based solutions now capture expanding share as hospitals and research consortia shift storage and inference workloads away from on-premise servers, while deep learning architectures displace classical image processing algorithms in accuracy-critical applications such as oncology screening and semiconductor wafer inspection. Manufacturing firms represent a fast-growing end user cohort as vision-based quality control replaces manual inspection stations across automotive and electronics assembly plants.
FDA software-as-a-medical-device frameworks enforce clinical validation thresholds that filter entrants lacking prospective study data, while EU MDR and CE marking requirements impose post-market surveillance obligations on diagnostic imaging software distributed in Europe. HIPAA security provisions in the United States constrain cloud architecture choices for healthcare providers, pushing vendors toward hybrid deployments with on-premise de-identification layers. Stakeholders must monitor evolving FDA guidance on adaptive AI algorithms, as continuous-learning systems challenge traditional locked-model approval pathways and force recalibration of compliance investments.

Market Dynamics
FDA premarket review pathways for software as a medical device are tightening validation requirements, forcing vendors to restructure R&D budgets toward prospective clinical studies and locked-model documentation rather than adaptive algorithm development.
Growth Catalysts
- AI-augmented diagnostic platforms:Healthcare providers in diagnostic radiology are expanding procurement of platforms that automate lesion detection and quantification. Deep learning architectures now outperform classical algorithms in accuracy-critical oncology screening applications.
- EU MDR post-market surveillance:CE marking requirements for diagnostic imaging software impose ongoing safety monitoring obligations that favor established vendors with compliance infrastructure. This regulatory clarity reduces buyer uncertainty in European hospital procurement.
- Manufacturing vision systems:Automotive and electronics assembly plants are replacing manual inspection stations with automated defect detection pipelines. Pixel-level analysis at micrometer resolution enables real-time quality control without production line interruption.
Market Restraints
- Cloud architecture constraints:HIPAA security provisions in the United States constrain healthcare providers to hybrid deployments with on-premise de-identification layers. This limits pure SaaS penetration and elevates infrastructure costs.
- GPU supply concentration:Inference workload acceleration depends on specialized semiconductor fabrication concentrated in Taiwan and South Korea. Geopolitical friction or foundry capacity constraints disrupt hardware refresh cycles.
- Classical algorithm displacement lag:Legacy installed bases in semiconductor wafer inspection and microscopy retain validated workflows that resist deep learning migration without extensive requalification studies.
Strategic Opportunities
- Pharmaceutical research biomarkers:Quantitative imaging biomarkers for clinical trials represent underpenetrated white space. Vendors can anchor growth in pharmaceutical sponsor workflows rather than competing directly in saturated hospital IT budgets.
- Retail visual AI deployment:Speed-to-deployment advantages in visual search and inventory analytics enable faster penetration against heavier enterprise suites. Modular packaging reduces buyer evaluation friction.
- Adaptive AI guidance preparation:FDA evolving guidance on continuous-learning systems creates first-mover advantage for vendors pre-positioning locked-model alternatives. Early compliance investment separates viable entrants from filtered applicants.
Industry Challenges
- Prospective study data requirements:Clinical validation thresholds for software as a medical device demand multi-site trials that compress R&D timelines and elevate capital intensity for algorithm developers.
- Interoperability with PACS infrastructure:Integration complexity with legacy picture archiving and communication systems delays deployment in hospital environments. DICOM standard variations across vendor implementations fragment connectivity protocols.
- Cross-border data governance:Divergent de-identification standards between HIPAA, GDPR, and Japan's Act on Protection of Personal Information complicate multi-tenant cloud architectures. Engineering resources fragment across jurisdiction-specific compliance layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Image Analysis Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Imaging, 3D Imaging, Cloud-Based Solutions, Integrated Systems Application: Medical Imaging, Quality Control, Security Surveillance, Life Sciences Technology: Machine Learning, Computer Vision, Image Processing Algorithms, Deep Learning End User: Healthcare Providers, Research Institutions, Manufacturing Firms, Government Agencies |
| Companies Covered | Quibim, Syte, GE HealthCare Technologies Inc., Chudovo, Heuritech, Carestream Health Inc., Imagga Technologies, Kiktronik, Trax Retail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Image Analysis Software Market Strategic Shifts
Deep learning architectures are compressing development cycles for accuracy-critical applications while regulatory frameworks struggle to pace validation requirements for continuously evolving algorithms.
Foundation models pretrained on multimodal imaging corpora are expanding into specialized diagnostic tasks with minimal fine-tuning data requirements. Community hospitals and regional clinics lacking extensive annotated datasets are adopting these models to match academic medical center performance benchmarks. This capability diffusion is expanding into pathology and ophthalmology screening workflows previously dominated by centralized reference laboratories.
EU MDR and CE marking requirements are reshaping competitive positioning for diagnostic imaging software distributed in Europe. Post-market surveillance obligations now mandate systematic safety monitoring that elevates ongoing compliance costs. Vendors targeting Germany, France, and the Netherlands are restructuring quality management systems to accommodate notified body audit intensification and vigilance reporting automation.
Hospital digitization budgets are rotating toward modular subscription packaging that decouples software procurement from capital-intensive hardware replacement cycles. Buyers in the United States, Germany, and Japan now evaluate platforms on annual operating expenditure metrics rather than total cost of ownership over depreciation periods. This preference shift favors vendors with API-first architectures that integrate with existing imaging hardware rather than bundled replacement propositions.
Image Analysis Software Market Segmentation
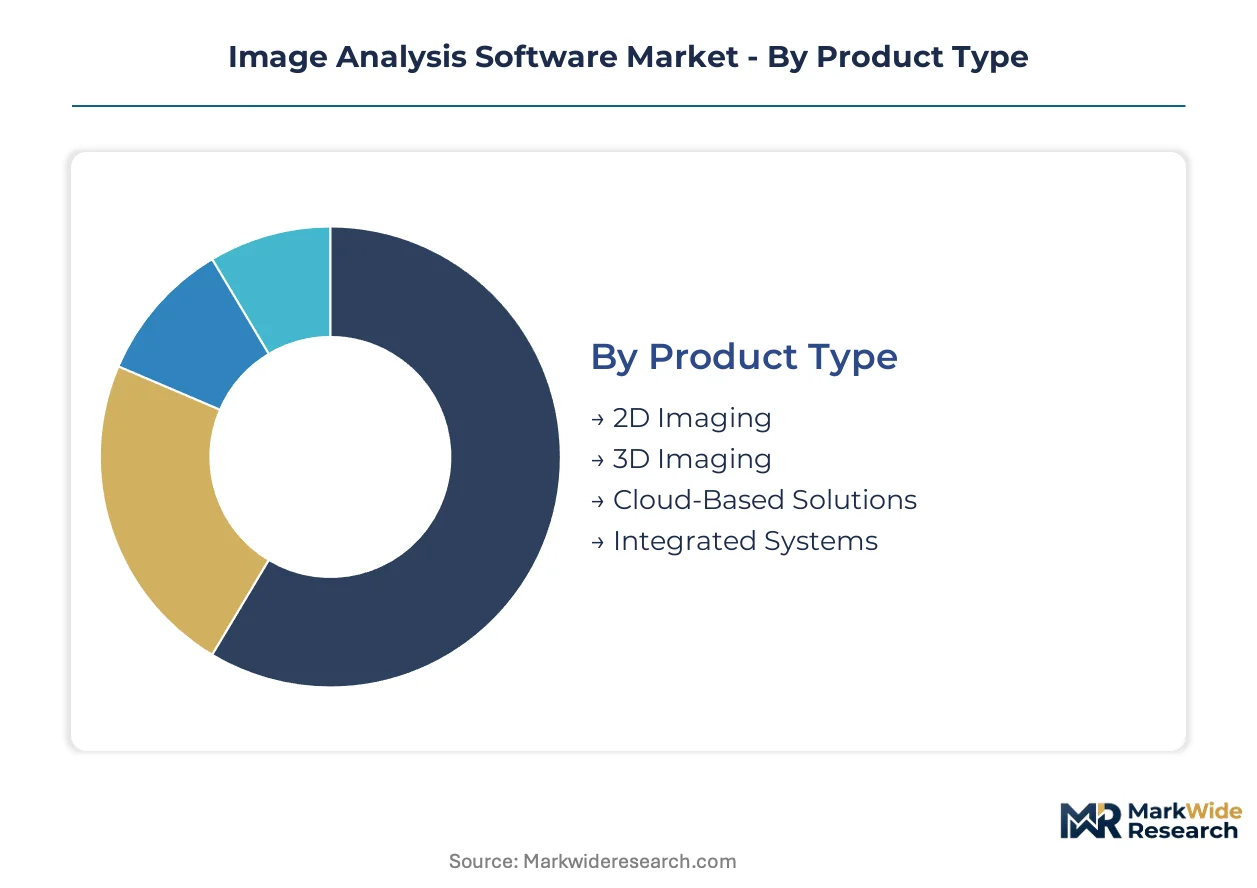
Segmentation in image analysis software reveals how procurement priorities diverge across technical architectures, use cases, and compliance requirements. Buyers evaluate platforms through fundamentally different lenses depending on whether they prioritize diagnostic accuracy, manufacturing throughput, or research reproducibility.
Product Type:
Buyers differentiate primarily by infrastructure commitment and data sovereignty requirements rather than feature depth alone.
- Cloud-Based Solutions:Multi-tenant architectures enable elastic compute scaling for inference workloads without capital expenditure on GPU clusters. Hospital systems in the United States favor hybrid deployments with on-premise de-identification layers to satisfy HIPAA security provisions while retaining cloud elasticity for non-PHI processing.
- 3D Imaging:Volumetric reconstruction pipelines process pixel matrices across spatial resolutions from sub-millimeter CT slices to micrometer-scale microscopy stacks. Demand concentrates in diagnostic radiology departments automating lesion detection and quantification in oncology screening workflows.
- 2D Imaging:Classical pixel analysis retains dominance in high-throughput manufacturing inspection where validated workflows resist deep learning migration without extensive requalification studies.
- Integrated Systems:Bundled hardware-software propositions appeal to capital budget holders replacing legacy imaging infrastructure in synchronized procurement cycles.
Volume sits with 2D Imaging in manufacturing quality control; growth tilts toward Cloud-Based Solutions as research consortia shift storage and inference workloads away from on-premise servers.
Application:
Regulatory validation thresholds filter entrants differently across use cases, with medical applications demanding prospective clinical study data that elevates capital intensity.
- Medical Imaging:FDA software-as-a-medical-device frameworks enforce locked-model documentation requirements that compress R&D timelines for algorithm developers. Deep learning architectures now outperform classical algorithms in accuracy-critical oncology screening applications across academic medical centers and community hospitals.
- Quality Control:Automotive and electronics assembly plants replace manual inspection stations with automated defect detection pipelines operating at micrometer resolution without production line interruption. Vision-based systems capture expanding share as pixel-level analysis enables real-time throughput monitoring.
- Life Sciences:Quantitative imaging biomarkers for clinical trials occupy a narrow but defensible niche in pharmaceutical research workflows, anchoring vendor growth in sponsor budgets rather than saturated hospital IT allocations.
- Security Surveillance:Real-time object tracking networks process streaming visual data across distributed camera infrastructure, with procurement driven by government digitization programs and critical facility protection mandates.
Revenue concentrates in Medical Imaging; expansion accelerates most quickly in Quality Control as manufacturing firms displace manual inspection stations.
Technology:
Architecture selection determines retraining frequency, interpretability requirements, and regulatory pathway complexity for algorithm developers.
- Deep Learning:Foundation models pretrained on multimodal imaging corpora expand into specialized diagnostic tasks with minimal fine-tuning data requirements. Community hospitals lacking extensive annotated datasets adopt these architectures to match academic medical center performance benchmarks in pathology and ophthalmology screening.
- Machine Learning:Classical statistical approaches retain installed base in semiconductor wafer inspection where validated workflows demand extensive requalification studies before algorithm substitution.
- Computer Vision:Edge-optimized inference pipelines enable real-time processing in surveillance networks and manufacturing lines with constrained latency tolerances.
- Image Processing Algorithms:Traditional pixel manipulation techniques persist in microscopy applications requiring deterministic, reproducible transformations for research publication standards.
Deployment volume favors Image Processing Algorithms in legacy research infrastructure; capability investment flows toward Deep Learning as FDA guidance on adaptive AI algorithms forces recalibration of compliance investments.
End User:
Budget cycles and procurement authority structures fragment demand across capital expenditure holders and operating expenditure optimizers.
- Healthcare Providers:Hospital digitization budgets in the United States, Germany, and Japan rotate toward modular subscription packaging that decouples software procurement from hardware replacement cycles. Buyers evaluate platforms on annual operating expenditure metrics rather than total cost of ownership across depreciation periods.
- Manufacturing Firms:Vision-based quality control investments accelerate across automotive and electronics assembly plants as automated defect detection replaces manual inspection stations.
- Research Institutions:Pharmaceutical sponsors and academic consortia drive demand for quantitative imaging biomarkers in clinical trial workflows, with procurement concentrated in contract research organization partnerships.
- Government Agencies:Public sector digitization programs fund security surveillance infrastructure and regulatory imaging standardization initiatives across national healthcare systems.
Procurement volume rests with Healthcare Providers; momentum gathers fastest among Manufacturing Firms as production line automation priorities displace legacy quality assurance staffing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States while diagnostic deployment spreads across Germany and Japan. Consumption patterns diverge as hospital digitization budgets rotate toward modular subscriptions in mature markets. Manufacturing quality control adoption accelerates in industrial clusters across East Asia and Central Europe.
United States
FDA software-as-a-medical-device frameworks enforce locked-model documentation requirements that compress R&D timelines for algorithm developers. HIPAA security provisions constrain cloud architecture choices, pushing vendors toward hybrid deployments with on-premise de-identification layers. Hospital systems in Boston and the San Francisco Bay Area anchor procurement of AI-augmented diagnostic platforms for oncology screening workflows.
Germany
EU MDR post-market surveillance obligations reshape competitive positioning for diagnostic imaging software distributed across European hospital networks. CE marking requirements mandate systematic safety monitoring that elevates ongoing compliance costs for vendors. Industrial automation firms in Bavaria and Baden-Württemberg deploy vision-based quality control systems across automotive assembly lines.
Japan
METI digital health initiatives accelerate hospital digitization budgets toward modular subscription packaging that decouples software from hardware replacement cycles. PMDA regulatory pathways for software medical devices impose validation thresholds similar to FDA frameworks. Tokyo and Osaka medical centers lead procurement of deep learning architectures for pathology and ophthalmology screening.
China
NMPA medical device approval pathways for AI diagnostic software tighten clinical validation requirements as domestic algorithm developers expand market presence. MIIT industrial internet programs fund vision system deployment across electronics manufacturing clusters. Shenzhen and Shanghai anchor production of semiconductor inspection equipment while Beijing hospitals pilot foundation models for radiology workflows.
South Korea
MFDS regulatory frameworks for software medical devices align with international validation standards while domestic GPU fabrication capacity supports inference workload acceleration. Government smart factory initiatives subsidize automated defect detection deployment across display panel and semiconductor production lines. Seoul Capital Area and Busan-Ulsan industrial zones concentrate manufacturing vision system adoption.
Image Analysis Software Market Competitive Environment
The competitive structure tilts toward diversified technology conglomerates with installed imaging hardware bases. Consolidation pressures intensify as FDA validation requirements elevate capital barriers for standalone algorithm developers. Three archetypes dominate: imaging hardware incumbents bundling software modules, vertical AI specialists targeting narrow diagnostic niches, and retail visual AI deployers competing on speed-to-implementation. M&A activity concentrates on acquiring locked-model documentation portfolios and regulatory submission expertise.
Within the hardware-bundling tier, GE HealthCare Technologies Inc. exemplifies installed-base leverage strategies. Among vertical specialists, Quibim occupies a position in quantitative imaging biomarkers for pharmaceutical research workflows. On the retail deployment vector, Syte anchors speed-to-deployment advantages against heavier enterprise suites.
| Leading Market Players |
|---|
| Quibim |
| Syte |
| GE HealthCare Technologies Inc. |
| Chudovo |
| Heuritech |
| Carestream Health Inc. |
| Imagga Technologies |
| Kiktronik |
| Trax Retail |
| Others |
Value Chain & Pricing Dynamics
Academic medical centers and pharmaceutical sponsors anchor procurement of FDA-validated image analysis platforms, locking in value-based pricing tiers that decouple software licensing from underlying GPU hardware refresh cycles. Cloud deployment elasticity competes against locked-model compliance premiums as buyers weigh operating expenditure flexibility against regulatory submission costs.
Pricing Analysis
Margin tightening in mid-tier SaaS subscriptions reflects GPU supply concentration in Taiwan and South Korea driving infrastructure cost passthrough. Pricing stratifies across FDA-cleared diagnostic modules, CE-marked European variants, and non-clinical research tiers. Cost-down pressure on perpetual licensing accelerates because hospital digitization budgets rotate toward annual subscription metrics. Manufacturing quality control buyers exhibit highest price sensitivity; pharmaceutical sponsors demonstrate lowest sensitivity due to clinical trial reproducibility requirements.
Supply Chain Analysis
Refurbished imaging hardware and remanufactured GPU clusters flow through secondary markets serving research institutions with constrained capital budgets. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States. Inference acceleration hardware draws from specialized foundry capacity, NAND memory supply, and precision optics for microscopy systems. Single-source vulnerability in advanced node GPU production disrupts hardware refresh timelines. Distribution runs through direct enterprise sales for healthcare providers and OEM channel partnerships for manufacturing integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU foundry capacity constraints prop pricing power for vendors with pre-allocated semiconductor supply, creating a supply-constrained market structure favoring incumbents with hardware bundling capabilities.
For Market Incumbents: Deploy locked-model documentation portfolios as defensive moats against adaptive AI entrants lacking prospective clinical study data. Acquire regulatory submission expertise in EU MDR notified body relationships to accelerate CE marking pathways. Consolidate quality management systems to absorb post-market surveillance cost elevation. For New Entrants and Emerging Players: Edge-optimized inference pipelines offer technology-first wedge into manufacturing vision systems where validated classical algorithms resist displacement. Target pharmaceutical research biomarkers as the most penetrable white space, anchoring growth in sponsor workflows rather than saturated hospital IT budgets. Pursue API-first modular packaging to reduce buyer evaluation friction against bundled enterprise suites. For Investors and Strategic Acquirers: The window for entry favors vertical AI specialists with locked-model FDA submissions and pharmaceutical research workflow integration. Long-term viability hinges on compliance infrastructure scalability across adaptive AI guidance evolution. Monitor FDA premarket review pathway tightening as inflection indicator for acquisition target filtering.| Strategic Initiative | Industry Significance |
|---|---|
| Locked-Model FDA Submission | CE marking and FDA clearance separate viable diagnostic vendors from filtered applicants in oncology screening workflows. |
| Pharmaceutical Research Partnership | Quantitative imaging biomarker integration anchors vendor growth in clinical trial sponsor budgets beyond hospital IT constraints. |
| GPU Supply Agreement | Foundry capacity allocation secures inference hardware refresh cycles against Taiwan and South Korea concentration risk. |
| Hybrid Cloud Architecture Deployment | On-premise de-identification layers satisfy HIPAA provisions while retaining cloud elasticity for non-PHI processing workloads. |
| Foundation Model Fine-Tuning Platform | Pretrained multimodal corpora enable community hospital performance matching with minimal annotated dataset requirements. |
Study Parameters
SEC filings, FDA 510(k) clearance databases, and hospital procurement contract records formed the secondary backbone, supplemented by primary interviews with diagnostic radiology department heads, pharmaceutical clinical operations directors, biomedical engineering procurement committees, and medical device regulatory affairs leads. Bottom-up and top-down triangulation validated segment sizing across deployment models and end-use verticals.
Bottom-up modeling aggregated individual vendor revenue streams across cloud-based, on-premise, and hybrid infrastructure commitments, while top-down analysis calibrated against healthcare IT expenditure surveys and manufacturing automation investment indices. Segmentation dimensions spanned product architecture, clinical versus non-clinical application, deep learning versus classical algorithm technology, and healthcare provider versus manufacturing firm end-user categories. CAGRs derived from regression analysis of historical procurement velocity and regulatory approval throughput.
Several conditions sit outside the modeled scope, including adaptive AI algorithm guidance not yet finalized by FDA, geopolitical disruption to Taiwan semiconductor fabrication, and divergent de-identification standard harmonization across HIPAA, GDPR, and Japan's APPI. Forecasts reflect assumptions of stable regulatory pathway timelines and continued GPU supply chain functionality. Practitioners should monitor FDA premarket review tightening, EU MDR notified body audit intensification, and foundry capacity allocation shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
3D Animation Production Software Market
Software & Services
DevOps Market
Software & Services
Communication Software Market
Software & Services
Co-Browsing Software Market
Software & Services
Equipment Management Software Market
Software & Services
Manufacturing Quoting and Estimating Software Market
Software & Services
Small Business Marketing Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Global Brand Management Software Market
Software & Services
Quick Service Restaurants (QSR) IT Market
Software & Services
User Retention Software Market
Software & Services
Global Content Management Systems (CMS) Market
Software & Services
Real-Time Voice Changing Software Market
Software & Services
Load Balancing Software Market
Software & Services
Global Plumbing Software Market
Software & Services
MEP Software Market