
 Co-Browsing Software Market | 2026-2036
Co-Browsing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Co-Browsing Software Market Insights
ISO 27001 certification is bifurcating the competitive landscape into audit-ready enterprise vendors and smaller providers serving mid-market buyers. Surfly leverages its banking-grade security architecture to sustain long-term contracts with European financial institutions. TeamViewer anchors its position through broad remote-access integration that extends co-browsing into unified endpoint management. Zendesk competes by embedding co-browsing natively within its service platform, reducing friction for existing helpdesk customers.
Co-browsing software enables simultaneous, agent-guided navigation of web applications where one party controls or annotates a shared browser session in real time, typically operating through JavaScript injection or browser extension protocols with pixel-streaming fallback for compatibility. The technology serves commercial purposes by reducing resolution times in complex service interactions where screen description alone proves inadequate. Cloud-based deployment leads among segments as organizations prioritize elastic scaling and reduced infrastructure overhead over self-hosted alternatives. The banking end-user segment commands premium pricing due to compliance requirements, while integrated chat functionality within feature sets captures expanding share as vendors bundle synchronous communication tools.
FCC guidelines on consumer data protection and HIPAA requirements for healthcare communications shape product development priorities across the United States market, compelling session recording and encryption capabilities. GDPR and the EU AI Act impose parallel constraints on European deployments, particularly around automated decision-making transparency in AI-assisted co-browsing scenarios. Stakeholders must monitor evolving cross-border data localization mandates that could fragment cloud delivery architectures and force region-specific infrastructure investments.
Market Dynamics
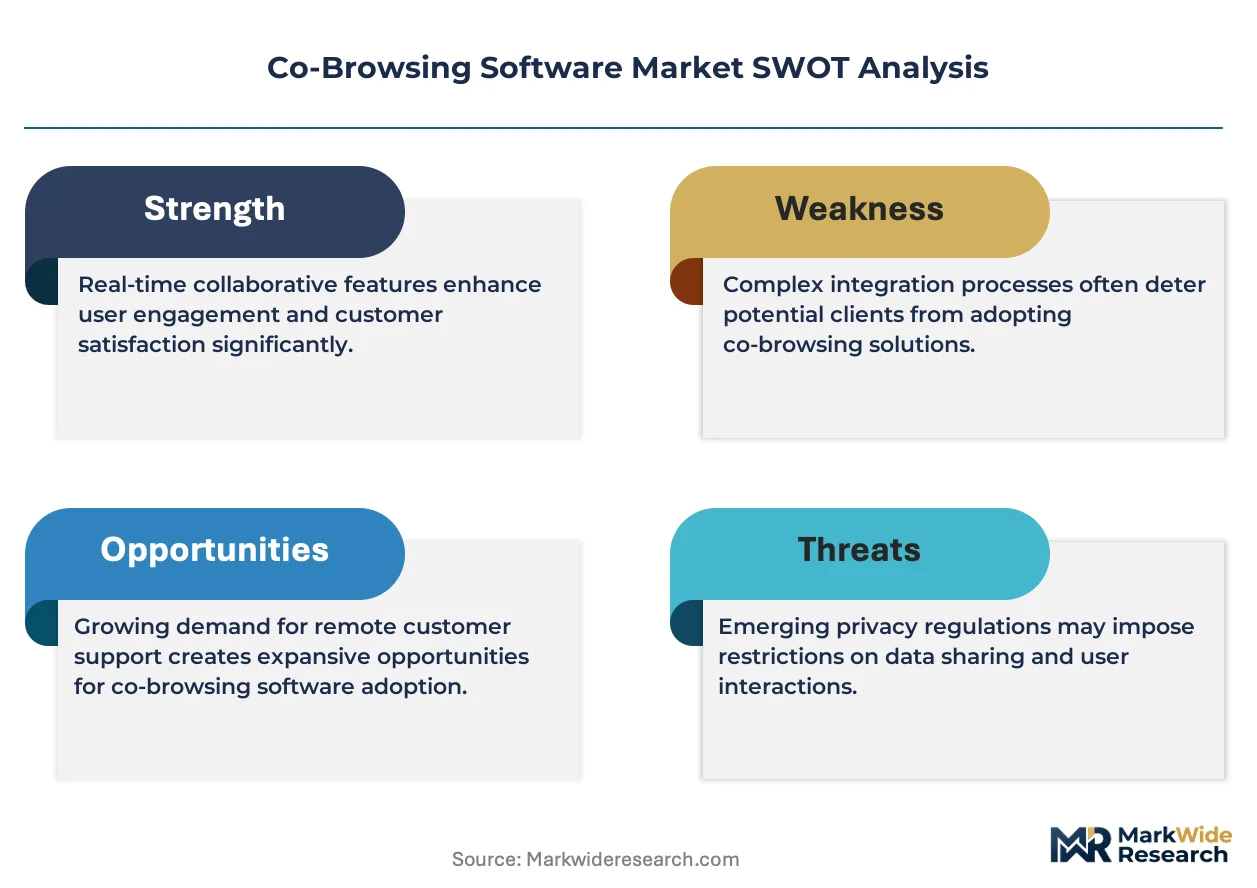
ISO 27001 certification requirements are compressing vendor margins while locking in enterprise banking contracts, forcing architectural investments that smaller providers cannot absorb. This bifurcation between audit-ready and mid-market suppliers defines competitive positioning.
Growth Catalysts
- GDPR and EU AI Act mandates:European financial institutions require consent-managed session architectures, creating procurement pull for compliant vendors.
- Healthcare HIPAA obligations:US providers need encrypted session recording for telehealth guidance, expanding addressable market for secure co-browsing platforms.
- Cloud-native deployment elasticity:Organizations prioritize JavaScript-injection protocols over self-hosted infrastructure to reduce fixed overhead.
Market Restraints
- Input cost concentration:Specialized TLS 1.3 certificate providers and regional cloud infrastructure vendors command pricing power in European deployments.
- Technical fallback limitations:Pixel-streaming protocols for legacy browser compatibility introduce latency that degrades real-time annotation precision.
- Regulatory fragmentation:Cross-border data localization mandates between Germany, France, and UK jurisdictions force redundant infrastructure provisioning.
Strategic Opportunities
- Underpenetrated German mid-market:Mittelstand manufacturers lack dedicated customer success tooling, presenting white space for scaled-down co-browsing solutions.
- AI-assisted annotation convergence:Natural language processing overlays on shared sessions enable automated troubleshooting suggestions during agent-guided navigation.
- US FCC consumer protection tailwinds:Strengthened disclosure requirements for digital financial services create compliance-driven upgrade cycles.
Industry Challenges
- Cybersecurity certification timelines:ISO 27001 and SOC 2 Type II audit cycles extend 12-18 months, delaying market entry for new entrants.
- Legacy CRM integration complexity:On-premise Salesforce and Microsoft Dynamics instances require custom API development for seamless session handoff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Co-Browsing Software Market |
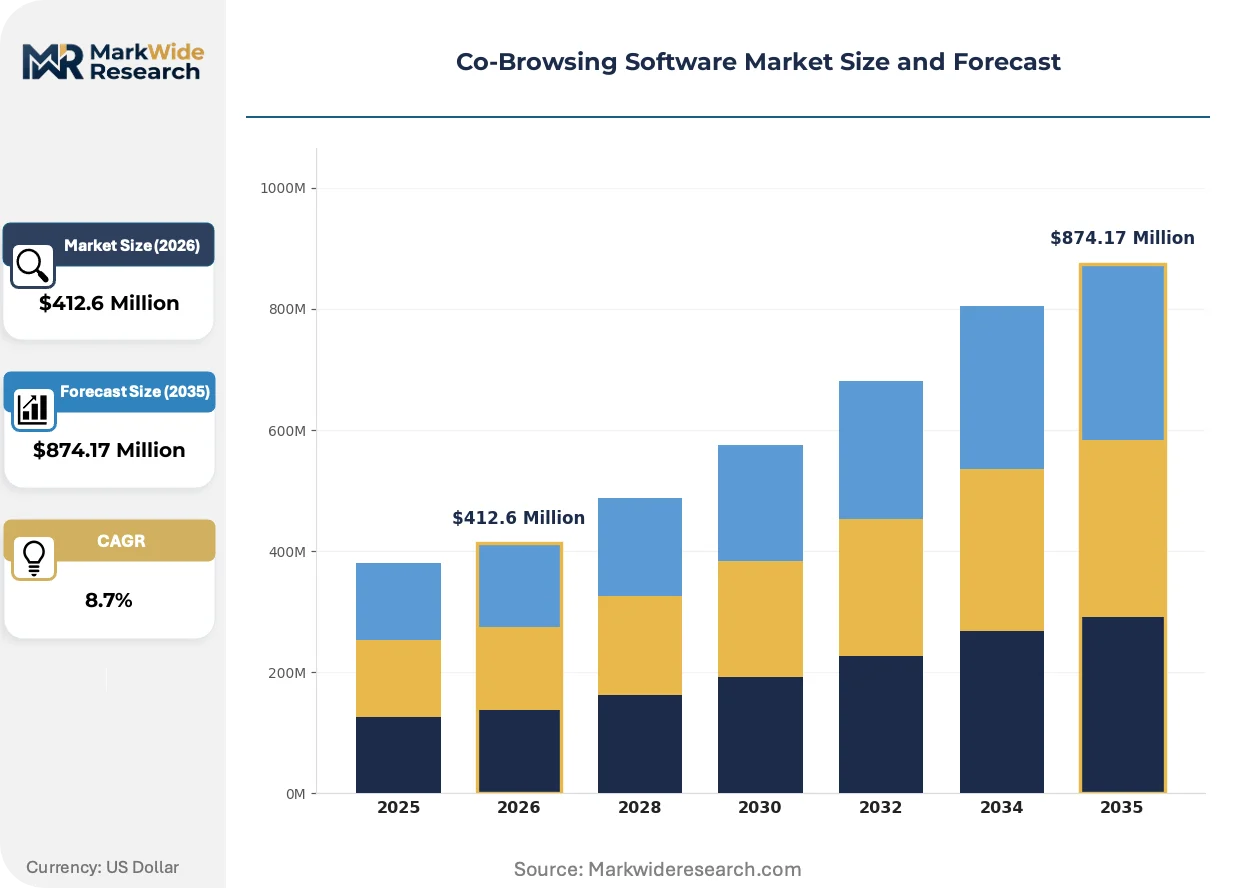
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Self-Hosted End User: Retail, Banking, Telecom, Healthcare Feature: Integrated Chat, Screen Sharing, Data Analytics, Session Recording Industry Vertical: E-Commerce, Customer Support, Education, Financial Services |
| Companies Covered | Surfly, cobrowse.io, Glia, Upscope, TeamViewer, Zoho Assist, Zendesk, Salesforce, Genesys Cloud CX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Co-Browsing Software Market Trends and Innovations
Agentic AI overlays and zero-trust security architectures are compressing the traditional separation between co-browsing vendors and adjacent customer experience platforms. These forces demand architectural rethinking rather than incremental feature addition.
Pixel-streaming fallback protocols for unsupported browsers is miniaturizing the compatibility burden that once required dedicated client software. Banking IT departments in Germany and France are deploying these lightweight alternatives to extend co-browsing to mobile Safari and legacy Internet Explorer instances still present in corporate environments. The technology is miniaturizing deployment friction from weeks to hours, collapsing the pilot-to-production timeline that previously favored incumbent vendors with established client relationships.
EU AI Act transparency requirements for automated decision-making are forcing session-logging architectures that expose AI-generated suggestions to audit trails. Vendors serving European financial institutions must now implement explainable annotation systems where algorithmic recommendations carry attribution metadata. Healthcare providers in the Netherlands and Belgium face parallel pressure from national implementations of the AI liability directive, accelerating demand for human-in-the-loop session controls.
Subscription unbundling is fragmenting traditional per-agent pricing into consumption-based models tied to actual session minutes. Mid-market SaaS buyers in the United Kingdom are rejecting annual seat commitments in favor of event-driven billing that aligns co-browsing costs with seasonal support volume. This shift pressures vendor revenue predictability while opening access to episodic users who previously found minimum commitments prohibitive.
Co-Browsing Software Market Segmentation
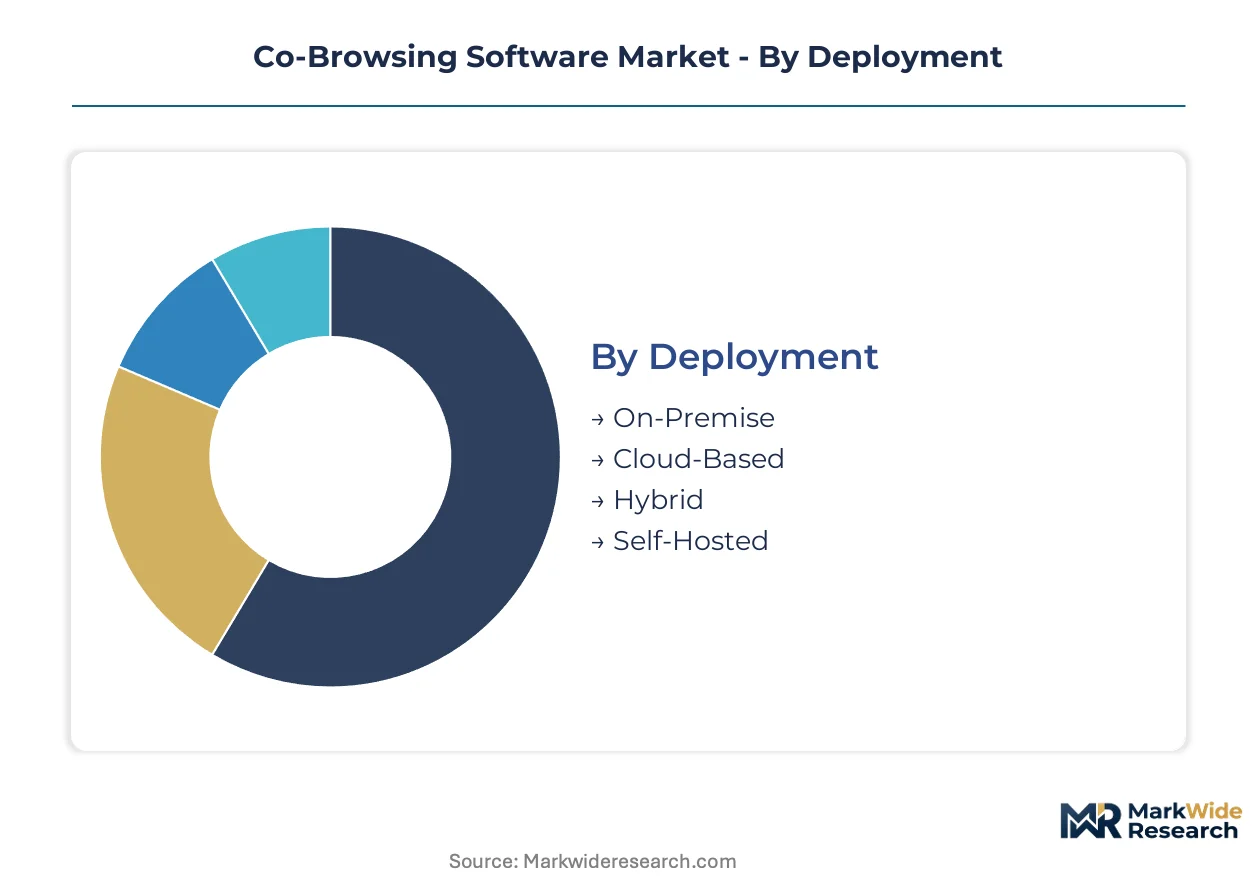
Deployment architecture determines compliance posture and infrastructure ownership in co-browsing procurement. End-use concentration in regulated sectors shapes feature bundling and pricing tiers across vendor portfolios.
Deployment:
Cloud-based configurations face substitution pressure from hybrid alternatives as data localization mandates harden across European jurisdictions.
- Cloud-Based:JavaScript-injection protocols enable elastic scaling without fixed infrastructure commitments. Demand concentrates among US healthcare providers navigating HIPAA encryption requirements for telehealth guidance, with procurement teams prioritizing SOC 2 Type II attestation over self-hosted alternatives.
- Hybrid:Split architectures route sensitive session data through on-premise nodes while leveraging cloud orchestration for load balancing. German financial institutions favor this configuration to satisfy Bundesbank operational resilience guidelines without surrendering vendor-managed elasticity.
- On-Premise:Complete infrastructure control satisfies air-gapped security requirements in defense and classified government environments.
- Self-Hosted:Single-tenant deployments appeal to mid-market buyers with existing Kubernetes expertise seeking to avoid per-seat SaaS premiums.
Cloud-based retains volume leadership; hybrid holds the steepest expansion curve.
End User:
Cost tier stratification separates audit-ready enterprise deployments from scaled-down mid-market configurations.
- Banking:Real-time co-browsing for complex transaction guidance demands TLS 1.3 encryption and ISO 27001 certification. European institutions under ECB supervision require consent-managed session architectures that log every annotation for audit trail compliance.
- Healthcare:HIPAA obligations mandate encrypted session recording with granular access controls for telehealth navigation assistance. US providers face OCR enforcement actions that elevate procurement scrutiny around business associate agreements.
- Retail:Conversion-focused deployments prioritize cart abandonment rescue over compliance depth, driving demand for lightweight JavaScript widgets.
- Telecom:Technical support use cases require pixel-streaming fallback for legacy device compatibility across heterogeneous customer hardware bases.
Banking commands premium pricing; healthcare is expanding most quickly.
Feature:
Application maturity separates commodity functionality from differentiated platform integration.
- Integrated Chat:Synchronous text channels embedded within co-browsing sessions reduce context switching for agents. Demand clusters in UK SaaS buyers rejecting siloed communication stacks.
- Session Recording:Immutable audit logs satisfy EU AI Act transparency requirements for algorithmic decision documentation. French financial regulators require explainable attribution metadata on every AI-generated annotation.
- Screen Sharing:One-to-many broadcast capabilities support educational webinar use cases with presenter-controlled navigation.
- Data Analytics:Post-session interaction mining identifies friction points in customer journey mapping for e-commerce optimization.
Integrated chat captures baseline demand; session recording gains share fastest.
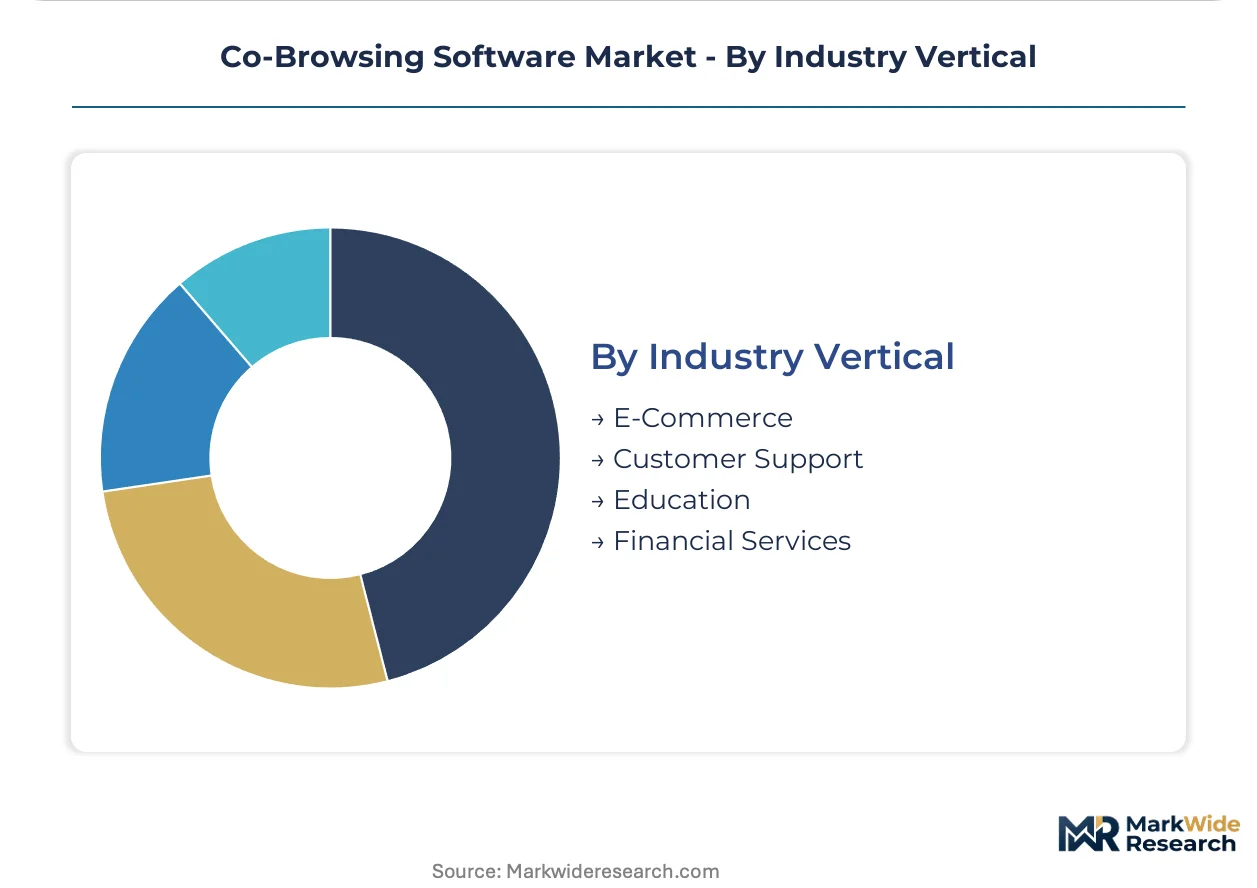
Industry Vertical:
Customer type concentration shapes go-to-market motion and sales cycle duration.
- Financial Services:Compliance-driven procurement cycles extend 9-14 months with extensive security review phases. US institutions prioritize FCC-aligned consumer protection capabilities for digital banking guidance.
- Customer Support:First-contact resolution metrics drive adoption among B2B software vendors seeking to deflect ticket volume through self-service augmentation.
- E-Commerce:Conversion rate optimization focuses deployment decisions, with merchandising teams measuring co-browsing ROI against abandoned cart recovery baselines.
- Education:Remote learning applications require accessibility compliance for screen reader compatibility in guided navigation scenarios.
Customer support leads volume; financial services exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR and the EU AI Act are redirecting procurement budgets toward consent-managed session architectures across European financial institutions. The United States market responds to HIPAA enforcement actions and FCC consumer protection guidelines with encrypted telehealth deployments. Cloud-native delivery dominates in software-forward economies while hybrid configurations gain traction where data localization mandates harden.
United States
Healthcare providers deploy co-browsing for telehealth navigation assistance under OCR scrutiny of business associate agreements. HIPAA mandates encrypted session recording with granular access controls that elevate procurement standards. The Boston-Seattle corridor concentrates healthtech SaaS vendors integrating co-browsing into patient engagement platforms.
Germany
Bundesbank operational resilience guidelines push Mittelstand manufacturers toward audit-ready co-browsing solutions for complex equipment support. The EU AI Act requires explainable attribution metadata on algorithmic annotations in financial services. Bavaria's banking cluster in Munich drives demand for ISO 27001-certified deployments with on-premise data nodes.
United Kingdom
Mid-market SaaS buyers reject annual seat commitments in favor of event-driven billing aligned with seasonal support volumes. FCA consumer duty rules strengthen disclosure requirements for digital financial guidance tools. London's fintech density sustains procurement velocity for integrated customer success platforms.
France
CNIL enforcement of GDPR Article 32 compels session-logging architectures with immutable audit trails for banking co-browsing. National implementation of the AI liability directive accelerates human-in-the-loop session controls in healthcare. The Paris financial services cluster demands TLS 1.3 encryption with consent-managed data routing.
Netherlands
Healthcare providers in Amsterdam and Rotterdam face parallel pressure from national AI liability frameworks for algorithmic decision transparency. The country's digital government initiatives extend co-browsing into citizen service navigation. Dutch e-commerce operators prioritize conversion-focused deployments with lightweight JavaScript widgets.
Co-Browsing Software Market Competitive Landscape
Player mix skews toward security-certified enterprise specialists and platform-integrated SaaS incumbents. The competitive structure bifurcates between audit-ready vendors capturing long-term banking contracts and mid-market providers serving episodic demand. Two strategic archetypes dominate: banking-grade security architects and unified customer experience platform operators. Competitive moves center on ISO 27001 certification acceleration and native CRM embedding to reduce session handoff friction.
Within the security-certified tier, Surfly leverages its Dutch banking heritage to anchor European financial institution contracts. TeamViewer exemplifies the platform-integrated archetype through remote-access convergence with endpoint management. Zendesk occupies a position as the native service-desk embedder, reducing procurement cycles for existing helpdesk customers. These three represent the dominant competitive vectors reshaping vendor positioning.
| Leading Market Players |
|---|
| Surfly |
| cobrowse.io |
| Glia |
| Upscope |
| TeamViewer |
| Zoho Assist |
| Zendesk |
| Salesforce |
| Genesys Cloud CX |
| Others |
Pricing and Supply Chain Analysis
Long-term enterprise seat commitments with annual indexation clauses lock in multi-year revenue visibility for ISO 27001-certified vendors while binding banking clients to predictable per-agent costs. This contract structure concentrates pricing power with audit-ready suppliers serving European financial institutions under ECB supervision, compressing margins for mid-market providers unable to absorb certification overhead.
Pricing Analysis
Cost-plus arrangements with TLS 1.3 certificate cost pass-through dominate enterprise banking procurement. Pricing stratifies across certified premium tiers, standard SaaS bundles, and lightweight economy widgets for retail conversion use cases. Price differentiation hinges on ISO 27001 attestation grade and session recording depth. Cost compression in mid-market segments is intensifying because subscription unbundling shifts buyers toward consumption-based models. Healthcare providers exhibit lowest price sensitivity due to HIPAA enforcement exposure, while UK SaaS buyers show highest elasticity around annual commitments.
Supply Chain Analysis
Ireland and the Netherlands host specialized TLS 1.3 certificate authorities serving European banking deployments. Germany anchors regional cloud infrastructure nodes satisfying Bundesbank data localization guidelines. The supply chain draws from cryptographic module providers, regional hyperscaler capacity, and specialized JavaScript-injection protocol developers. Single-source vulnerability concentrates in certificate authority concentration. Distribution runs through direct enterprise sales teams with embedded security consultants for compliance-heavy sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Native video conferencing platforms with embedded screen sharing threaten standalone co-browsing vendors through functional substitution, forcing incumbents to demonstrate superior security architecture and CRM integration depth.
For Market Incumbents: Shield long-term banking contracts by accelerating EU AI Act-compliant session logging architectures before regulatory deadlines tighten. Deepen backward integration into certificate authority relationships to secure TLS 1.3 supply priority during procurement surges. Vertical integration into zero-trust security modules addresses emerging platform substitution threats from unified communications vendors. For New Entrants and Emerging Players: Anchor in German Mittelstand manufacturing support, where audit-ready co-browsing solutions remain underdeployed for complex equipment guidance. Target consumption-based billing models that align with seasonal support volumes rejected by incumbent annual seat structures. Partner with regional system integrators possessing existing Kubernetes expertise to bypass direct certification overhead. For Investors and Strategic Acquirers: Security-certified mid-market specialists with hybrid deployment capabilities represent the most defensible acquisition profile as data localization mandates harden. Long-term viability centers on regulatory compliance moats rather than feature differentiation. Watch for AI liability directive implementation timelines as inflection signals for human-in-the-loop session control demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native CRM embedding reduces session handoff friction for Salesforce and Microsoft Dynamics instances. |
| Certification Acceleration | ISO 27001 and SOC 2 Type II attestation unlocks ECB-supervised banking procurement cycles. |
| Geographic Expansion | Munich and Bavaria banking clusters demand on-premise data nodes under Bundesbank guidelines. |
| Strategic Partnership | Regional system integrators bypass direct certification overhead for mid-market manufacturing clients. |
| Product Launch | AI-assisted annotation overlays with explainable metadata satisfy CNIL audit trail requirements. |
Research Methodology
Initial hypotheses were tested against primary input from CTOs, IT procurement officers, platform engineers, and integration specialists and refined through secondary validation across SEC filings, hyperscaler capex disclosures, App Annie/Sensor Tower data, and vendor security attestation databases. Bottom-up deployment modeling triangulated with top-down market sizing across cloud-native, hybrid, and on-premise configurations.
Variance decomposition across deployment architecture, organization size, vertical compliance depth, integration complexity, and regional adoption pattern shaped the analytical framework. CAGRs were derived from segment-level trajectory blending across the projection horizon. Forecast inputs incorporated TLS 1.3 certificate cost curves and EU AI Act implementation timelines.
Underlying assumptions cover regulatory enforcement intensity, certificate authority capacity expansion, and banking procurement cycle duration, with deviation risk concentrated in cross-border data localization mandate fragmentation. Recalibration cycles align with material shifts in ECB supervisory guidance and FCC consumer protection rulemaking.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Maintenance Management Software Market
Software & Services
Chemical Manufacturing Software Market
Software & Services
Global Voting Software Market
Software & Services
Japan Qualitative Data Analysis Software Market
Software & Services
E-Invoicing Software Market
Software & Services
Video Management Software (VMS) Market
Software & Services
Global CMMS Software Market
Software & Services
Computer Software Market
Software & Services
Global Text to Speech (TTS) Software Market
Software & Services
Interior Design Software Market
Software & Services
Global Survey Software Market
Software & Services
HVAC Solution Software Market
Software & Services
Machine Translation Software Market
Software & Services
Poultry Farm Management Software Market
Software & Services
Global Development Tools Software Market
Software & Services
Global Local SEO Software Market