
 Short Sleep Syndrome Treatment Market | 2026-2036
Short Sleep Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Short Sleep Syndrome Treatment Market Analytics
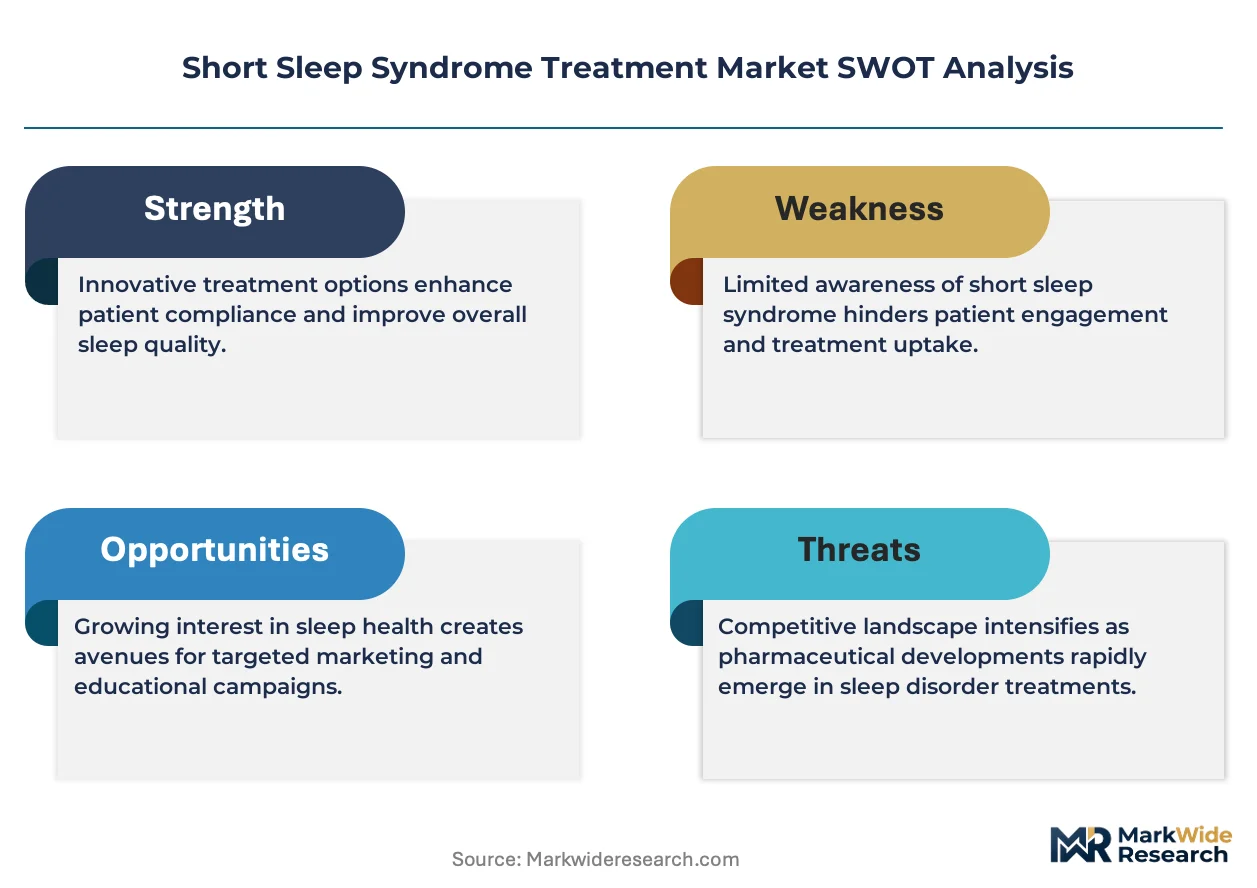
Subscription-based digital therapeutics and remote monitoring platforms is recalibrating how short sleep syndrome interventions reach patients. Jazz Pharmaceuticals, Inc. leverages its specialty neurology infrastructure to sustain dominance in controlled-release sleep therapeutics. Takeda anchors its position through deep R&D investment in orexin-targeting mechanisms. Eli Lilly and Company differentiates via behavioral health integration with its broader neuroscience portfolio.
Short sleep syndrome denotes a chronic condition where individuals consistently sleep fewer than six hours nightly without daytime impairment, requiring polysomnographic validation and differential diagnosis from insomnia disorders. The condition demands precise identification of circadian phase markers and homeostatic sleep drive parameters to distinguish pathological brevity from benign variation. Pharmacological treatment captures the dominant margin pool due to chronic prescribing patterns and limited generic penetration in novel mechanisms. Cognitive behavioral therapy for insomnia adaptations represents the fastest-growing treatment method as payers prioritize non-pharmacological first-line protocols. Home care settings expand most rapidly, driven by telehealth reimbursement expansion and wearable-validated sleep tracking.
The FDA regulates all pharmacological candidates through its Division of Psychiatry Products, while the DEA schedules controlled substances used in sleep therapeutics, directly constraining formulary placement and prescribing flexibility. The American Academy of Sleep Medicine publishes clinical practice guidelines that shape payer coverage determinations and treatment algorithms. Stakeholders must monitor evolving digital therapeutic classification pathways and integrated benefit designs that bundle behavioral and pharmacological interventions.
Market Dynamics
The DEA's scheduling of controlled substances for sleep therapeutics creates a structural bottleneck that constrains prescribing flexibility and formulary placement, forcing stakeholders to navigate parallel regulatory pathways for non-controlled alternatives.
Growth Catalysts
- Telehealth reimbursement expansion:CMS and private payers in the United States have broadened coverage for remote sleep medicine consultations, accelerating patient access to diagnostic and therapeutic services outside traditional clinic settings.
- Orexin receptor antagonists:Novel pharmacological mechanisms targeting wake-promoting neuropeptides are expanding the addressable patient population beyond traditional GABA-A modulator candidates.
- Behavioral health integration mandates:The American Academy of Sleep Medicine's updated clinical practice guidelines now prioritize cognitive behavioral protocols as first-line intervention, redirecting reimbursement toward non-pharmacological treatment pathways.
Market Restraints
- Controlled substance scheduling:DEA Schedule IV classification for benzodiazepine receptor agonists imposes dispensing limits, refill restrictions, and prescriber registration requirements that compress commercial flexibility.
- Polysomnography capacity constraints:Diagnostic bottlenecks at accredited sleep centers create wait times exceeding eight weeks in major US metropolitan markets, delaying treatment initiation.
- Generic penetration in legacy mechanisms:Zolpidem and eszopiclone commoditization has eroded margin pools in the GABA-A modulator segment, compressing R&D recapture timelines for novel mechanisms.
Strategic Opportunities
- Wearable-validated sleep tracking:Integration of consumer-grade actigraphy with clinical diagnostic workflows enables home-based phenotyping and treatment monitoring at scale.
- Digital therapeutic classification:FDA's evolving guidance on prescription digital therapeutics creates a regulatory pathway for software-based interventions to achieve formulary parity with pharmacological options.
- Integrated benefit designs:Payers in the United States are piloting bundled reimbursement models that combine behavioral coaching, remote monitoring, and pharmacological management under single episode-based payments.
Industry Challenges
- Board-certified sleep medicine physician scarcity:Fellowship training program output has plateaued while patient volume expands, creating workforce gaps that telehealth protocols only partially address.
- Differential diagnosis complexity:Distinguishing short sleep syndrome from insomnia disorder, insufficient sleep syndrome, and circadian rhythm disorders requires specialized polysomnographic interpretation that strains laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short Sleep Syndrome Treatment Market |
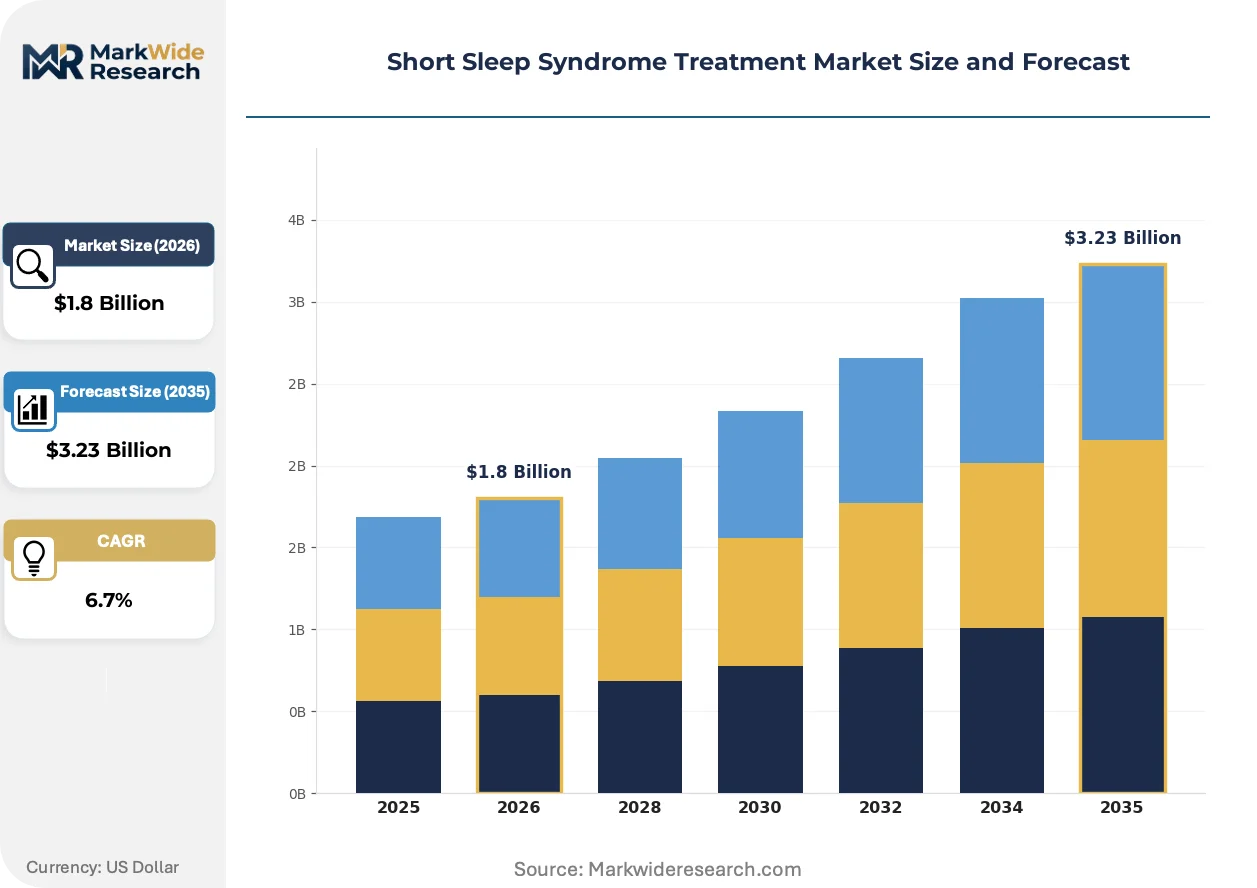
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Behavioral Therapy, Sleep Aids, Nutritional Supplements Treatment Method: Cognitive Behavioral Therapy, Pharmacological Treatment, Light Therapy, Relaxation Techniques Care Setting: Outpatient Clinics, Sleep Centers, Home Care, Hospitals Patient Demographics: Adults, Adolescents, Geriatric Patients, Shift Workers |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, Takeda, Merck, Eisai, Jazz Pharmaceuticals, Inc., Viatris Inc., Sanofi, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short Sleep Syndrome Treatment Market Evolving Landscape
Digital phenotyping and remote therapeutic monitoring are compressing the traditional diagnostic-to-treatment interval, while regulatory frameworks struggle to keep pace with hybrid physical-digital intervention models.
Dual orexin receptor antagonists are absorbing market attention as the next-generation pharmacological platform for sleep-wake disorders. Sleep centers and academic medical centers are adopting these agents at accelerating velocity for patients with comorbid psychiatric conditions. The technology is absorbing prescribing volume from traditional hypnotics by offering improved next-day residual effect profiles and lower abuse liability.
The FDA's Division of Psychiatry Products has issued draft guidance on patient-reported outcome measures for sleep disorder trials, tightening evidentiary standards for subjective endpoints. This policy shift is forcing sponsors to incorporate objective wearable-derived metrics into pivotal study designs. Phase III programs for novel hypnotics now face higher regulatory capital requirements and extended timelines.
Subscription-based digital therapeutics are displacing traditional fee-for-service sleep medicine encounters among commercially insured populations. Employers and health plans are contracting directly with platform developers for population sleep health management. This shift is most visible in technology sector employee health benefits, where absenteeism costs from untreated sleep disorders drive procurement decisions.
Short Sleep Syndrome Treatment Market Segmentation
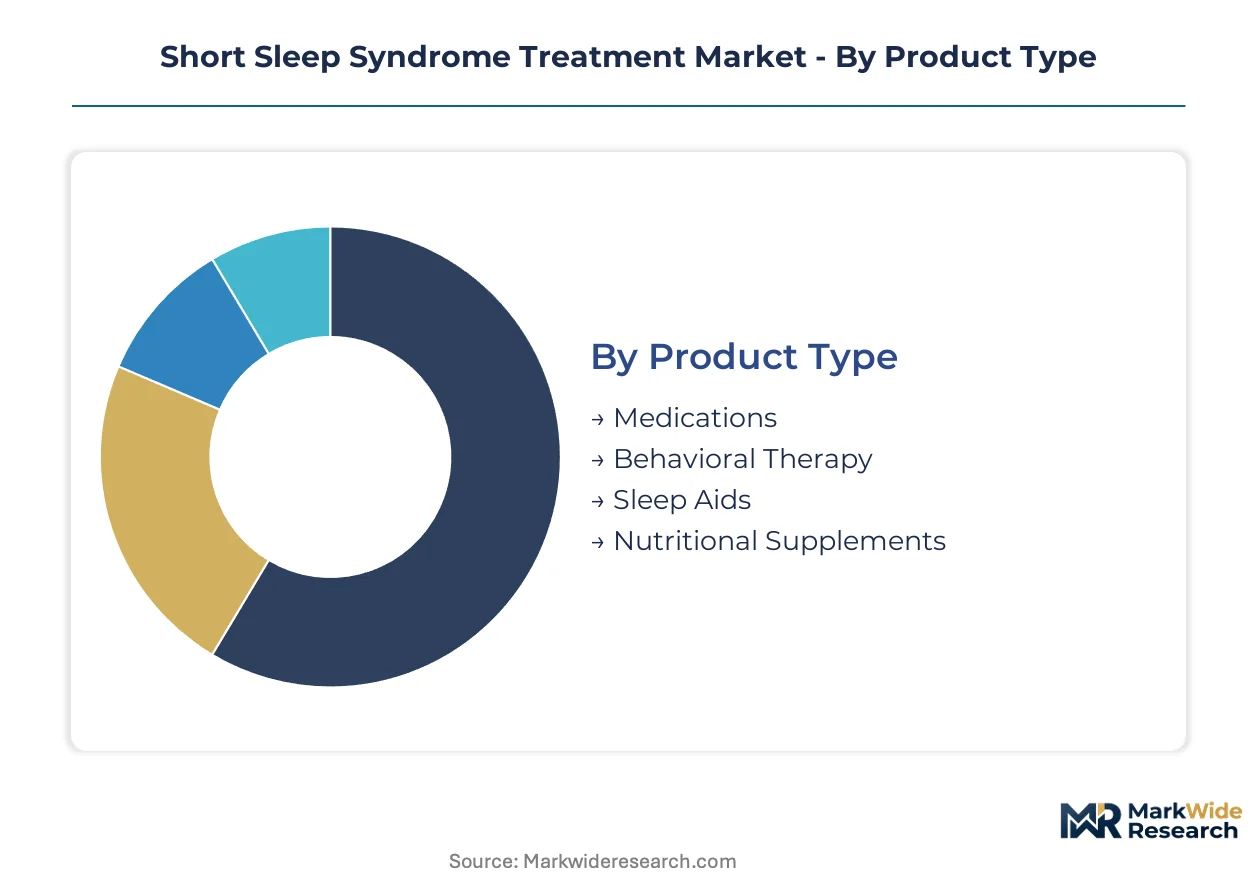
Short sleep syndrome treatment markets fragment across intervention modalities and care delivery sites, with reimbursement pathways and diagnostic infrastructure determining segment viability. Patient phenotyping complexity drives heterogeneous demand patterns across pharmacological and non-pharmacological alternatives.
Product Type:
Medications command premium pricing tiers due to chronic prescribing patterns and novel mechanism patent protection, while behavioral and nutritional alternatives compete on volume accessibility.
- Medications:Controlled-release formulations targeting orexin and GABA-A pathways dominate commercial margin pools. FDA Division of Psychiatry Products oversight shapes development timelines and labeling claims for hypnotic candidates.
- Behavioral Therapy:Cognitive behavioral protocols adapted for short sleep phenotyping are climbing the fastest as payers mandate non-pharmacological first-line protocols under American Academy of Sleep Medicine guidelines.
- Sleep Aids:Consumer-grade devices and over-the-counter preparations serve price-sensitive segments outside formal diagnosis pathways.
- Nutritional Supplements:Melatonin and magnesium formulations occupy regulatory gray zones between food and drug classifications, limiting formulary integration.
Mature deployment sits with Medications. Newer deployment is concentrated in Behavioral Therapy.
Treatment Method:
Intervention selection hinges on differential diagnosis precision, with polysomnographic validation requirements filtering patients toward specialized or scalable alternatives.
- Cognitive Behavioral Therapy:Adapted protocols for circadian phase assessment and sleep compression therapy require board-certified sleep psychologist delivery. CMS telehealth reimbursement expansion is accelerating home-based protocol deployment.
- Pharmacological Treatment:Dual orexin receptor antagonists and controlled-release GABA-A modulators capture patients with comorbid psychiatric conditions. DEA Schedule IV constraints impose dispensing limits that compress commercial flexibility.
- Light Therapy:Timed bright light exposure targets circadian misalignment subtypes. Device reimbursement remains inconsistent across commercial payers.
- Relaxation Techniques:Biofeedback and progressive muscle relaxation serve as adjunctive interventions with limited standalone efficacy data.
Established practice patterns favor Pharmacological Treatment. Emerging adoption centers on Cognitive Behavioral Therapy.
Care Setting:
Diagnostic capacity constraints and reimbursement geography determine where patients enter treatment pathways, with site-of-care economics shifting toward lower-acuity venues.
- Sleep Centers:Accredited facilities with polysomnography suites provide definitive diagnosis but face eight-week wait times in major US metropolitan markets. AASM accreditation requirements limit site expansion velocity.
- Outpatient Clinics:General neurology and behavioral health practices are absorbing mild-to-moderate case volumes through wearable-validated screening protocols. These settings are expanding most quickly due to telehealth integration and lower overhead structures.
- Home Care:Remote therapeutic monitoring and direct-to-patient digital therapeutics bypass traditional facility requirements entirely.
- Hospitals:Inpatient consultation-liaison psychiatry manages acute sleep disruption in medical-surgical populations, not chronic short sleep syndrome.
Diagnostic authority remains with Sleep Centers. Volume growth is concentrated in Outpatient Clinics.
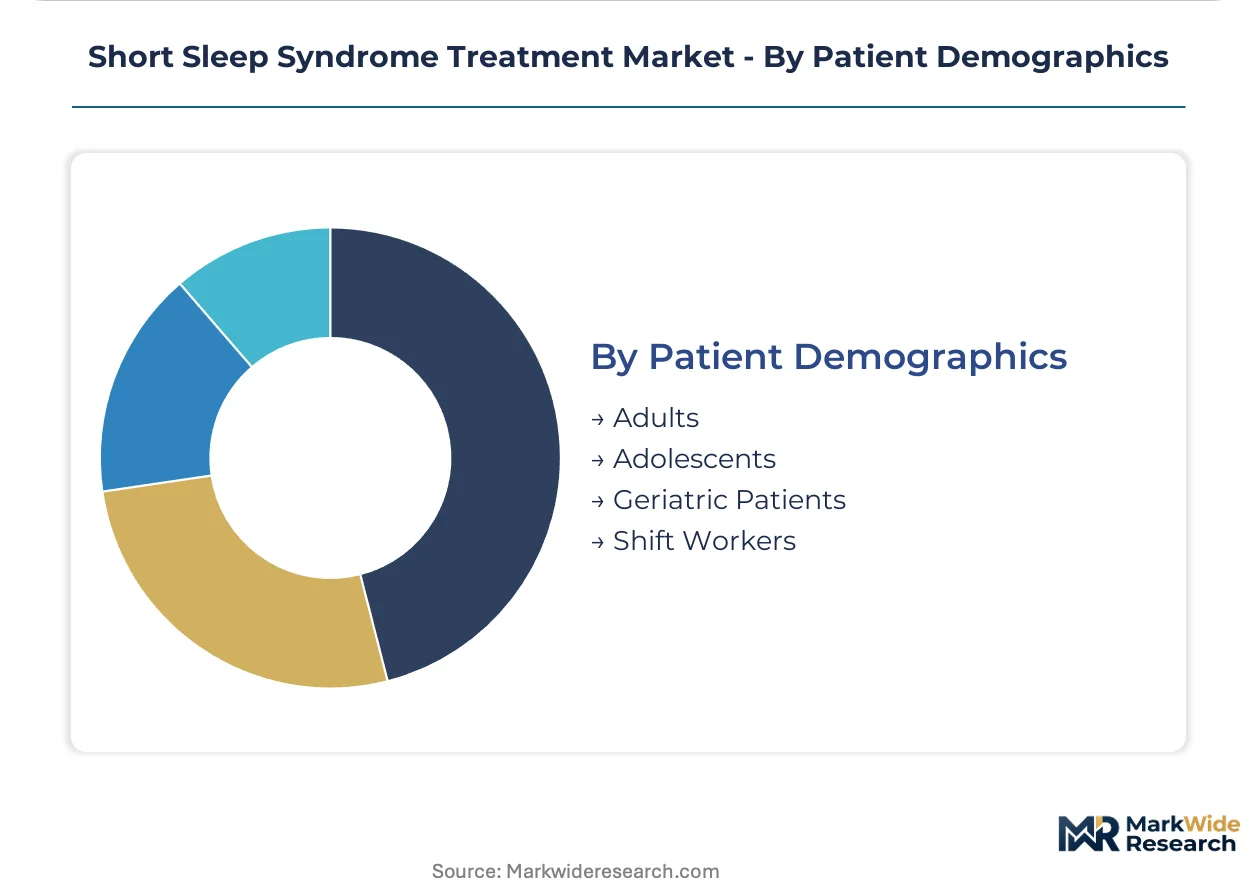
Patient Demographics:
Age-dependent sleep architecture changes and occupational circadian disruption create distinct phenotypic subpopulations with differential treatment responsiveness.
- Adults:Working-age patients aged 18-64 present the largest addressable population, with occupational performance concerns driving treatment-seeking behavior.
- Shift Workers:Rotating and night-shift schedules produce circadian misalignment that overlaps phenotypically with short sleep syndrome, complicating differential diagnosis and requiring specialized chronobiological intervention.
- Adolescents:Delayed sleep phase tendencies in school-age populations require distinct behavioral protocols and parental involvement structures.
- Geriatric Patients:Age-related sleep fragmentation and polypharmacy concerns limit hypnotic tolerability, favoring non-pharmacological approaches.
Commercial focus targets Adults. Unmet need concentrates in Shift Workers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors specialized sleep medicine infrastructure, hosting academic medical centers that shape clinical practice guidelines and train board-certified sleep physicians for national distribution.
United States
Specialized sleep centers in Stanford, California and Boston, Massachusetts drive diagnostic protocol innovation. FDA Division of Psychiatry Products regulates all hypnotic candidates through centralized review pathways. The American Academy of Sleep Medicine in Darien, Illinois publishes reimbursement-shaping clinical guidelines that redirect treatment algorithms toward cognitive behavioral first-line protocols.
Germany
Heidelberg and Mannheim university hospitals pioneer polysomnographic phenotyping methodologies for differential diagnosis. EMA centralized procedures govern orexin-targeting therapeutic approvals across member states. The Charité-Universitätsmedizin Berlin cluster coordinates multi-center trials validating wearable-derived sleep metrics for regulatory submission.
Japan
Tokyo's Jikei University School of Medicine advances circadian chronobiology research for shift worker populations. PMDA reviews novel hypnotic mechanisms through its Office of New Drug I, with priority review vouchers available for sleep-wake disorder innovations. Osaka-based pharmaceutical development sites concentrate formulation expertise for controlled-release sleep therapeutics.
United Kingdom
London's Guy's and St Thomas' NHS Foundation Trust operates one of Europe's largest accredited sleep disorder centers. NICE technology appraisals determine formulary placement for digital therapeutics and pharmacological interventions. The Oxford Sleep and Circadian Neuroscience Institute translates basic research into clinical trial endpoints for regulatory qualification.
Switzerland
Zurich's University Hospital integrates sleep medicine with behavioral health services under single episode-of-care contracts. Swissmedic maintains streamlined review timelines for novel mechanisms addressing unmet neurological needs. The Basel pharmaceutical corridor hosts R&D facilities developing dual orexin receptor antagonists for global registration.
Short Sleep Syndrome Treatment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the short sleep syndrome treatment landscape, with integrated pharmaceutical conglomerates maintaining manufacturing infrastructure while biotechnology specialists license novel mechanisms to larger partners. The vendor base concentrates around three strategic tiers: specialty neurology-focused firms with controlled-substance distribution expertise, diversified pharmaceutical conglomerates with behavioral health integration capabilities, and emerging digital therapeutic developers seeking formulary parity. Competitive positioning hinges on M&A activity targeting orexin pathway intellectual property and strategic partnerships bundling pharmacological and non-pharmacological interventions under single reimbursement contracts.
Within the specialty neurology tier, Jazz Pharmaceuticals, Inc. and Takeda occupy positions defined by controlled-release formulation expertise and orexin-targeting R&D investment respectively. Eli Lilly and Company exemplifies the behavioral health integration archetype, leveraging broader neuroscience portfolio synergies. These three entities anchor competitive dynamics as the FDA tightens evidentiary standards for subjective endpoints and payers mandate non-pharmacological first-line protocols.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| Takeda |
| Merck |
| Eisai |
| Jazz Pharmaceuticals, Inc. |
| Viatris Inc. |
| Sanofi |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Network & Pricing Analysis
Commercial payers and self-insured employers concentrate purchasing power for short sleep syndrome interventions, anchoring a value-based pricing model that ties reimbursement to measurable sleep outcomes and reduced absenteeism costs. This buyer concentration forces manufacturers to demonstrate polysomnographic validation and next-day functional metrics rather than competing on unit cost alone.
Pricing Analysis
Value-based contracts anchored to patient-reported outcome measures and wearable-derived sleep efficiency metrics dominate reimbursement negotiations between manufacturers and large employers. Pricing stratifies across premium, standard, and economy tiers based on FDA Division of Psychiatry Products labeling tier and DEA scheduling status, with novel orexin antagonists commanding premium positioning over generic GABA-A modulators. Cost compression in the legacy hypnotic segment is intensifying because zolpidem commoditization has eroded margin pools, while behavioral health integration bundles face pricing pressure from payers mandating non-pharmacological first-line protocols. Self-insured employers exhibit highest price sensitivity due to direct cost absorption, whereas Medicare Advantage plans demonstrate lowest sensitivity where star-rating bonuses reward quality outcomes over unit economics.
Supply Chain Analysis
FDA Division of Psychiatry Products oversight and DEA manufacturing quotas create certification gating that constrains active pharmaceutical ingredient sourcing to qualified facilities in the United States, Ireland, and Switzerland. Controlled-release formulation expertise rests on specialized excipient supply from German and Japanese chemical suppliers, while orexin-targeting synthetic chemistry draws from Swiss and Massachusetts-based biotechnology manufacturing clusters. Single-source vulnerability in dual orexin receptor antagonist API supply creates exposure to manufacturing inspection delays and import restrictions. Distribution runs through specialty pharmacy networks with controlled-substance licensing rather than traditional wholesale channels, adding dispensing complexity and patient access friction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual orexin receptor antagonists are displacing legacy GABA-A modulators as the pharmacological backbone of short sleep syndrome treatment, creating a technology-transition window where orexin pathway intellectual property determines competitive positioning. Stakeholders must calibrate strategic moves to this mechanism shift while navigating tightened FDA evidentiary standards for subjective endpoints.
For Market Incumbents: Deepen vertical integration into orexin-targeting API manufacturing to secure supply continuity amid DEA quota constraints and FDA inspection backlogs. Consolidate specialty pharmacy distribution relationships to defend formulary placement against emerging digital therapeutic entrants seeking reimbursement parity. Priority lever: controlled-release formulation patents. For New Entrants and Emerging Players: The mid-market pricing gap between premium orexin antagonists and commoditized zolpidem generics creates white-space opportunity for wearable-validated digital therapeutics and subscription-based behavioral coaching platforms. Target outpatient clinic settings where telehealth reimbursement expansion lowers capital requirements for patient acquisition. Go-to-market angle: employer direct contracting for population sleep health management. For Investors and Strategic Acquirers: The window for entry favors biotechnology specialists with orexin pathway intellectual property and digital therapeutic developers with FDA prescription software classification. Long-term viability hinges on bundled reimbursement contracts combining pharmacological and behavioral interventions. Acquisition target archetype: mid-stage orexin antagonist programs with Phase IIb sleep architecture data. Signal to watch: American Academy of Sleep Medicine guideline updates elevating digital therapeutics to first-line status.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III programs incorporating wearable-derived objective endpoints satisfy FDA Division of Psychiatry Products draft guidance on patient-reported outcome measures. |
| Regulatory Approval Pathway | DEA Schedule IV classification negotiations determine dispensing limits and prescriber registration requirements for novel hypnotic mechanisms. |
| Licensing Agreement | Partnerships bundling pharmacological candidates with digital therapeutic platforms align with integrated benefit designs piloted by commercial payers. |
| Manufacturing Scale-Up | Controlled-release capacity expansion in FDA-inspected facilities addresses API supply constraints for orexin-targeting formulations. |
| Reimbursement Strategy | CMS telehealth coding advocacy and employer direct contracting secure formulary placement outside traditional pharmacy benefit manager channels. |
Research Methodology
Multi-period observation of polysomnography capacity utilization, DEA manufacturing quota allocations, and telehealth reimbursement policy changes anchored the trend analysis, supplemented by interviews with drug development executives at specialty neurology firms, regulatory affairs leads navigating FDA Division of Psychiatry Products oversight, formulary directors at national pharmacy benefit managers, and payer access specialists at commercial health plans. Secondary validation drew from FDA filings, ClinicalTrials.gov protocol registrations, American Academy of Sleep Medicine guideline publications, and CMS Medicare telehealth claims data. Bottom-up patient volume estimates across care settings were triangulated against top-down pharmaceutical revenue disclosures.
Input-output matrices modeled patient flow from diagnostic validation through treatment initiation across pharmacological and non-pharmacological pathways, with segmentation dimensions including intervention modality, care setting tier, and patient demographic archetype. CAGRs were derived from trend extrapolation of historical adoption curves adjusted for regulatory inflection points and reimbursement policy shifts. Forecast inputs incorporated DEA scheduling decisions, FDA digital therapeutic classification determinations, and AASM guideline revision timelines.
Inputs from FDA advisory committee meeting minutes and payer coverage policy databases were available through the study window; gaps in real-world evidence generation for digital therapeutics introduce uncertainty bands around behavioral health segment projections. Forecasts reflect assumptions regarding telehealth reimbursement permanence and orexin antagonist formulary placement velocity. A model refresh is warranted upon material change in FDA guidance on prescription digital therapeutics or DEA controlled substance scheduling determinations for novel hypnotic mechanisms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Parasomnia Treatment Market
Sleep Medicine
Oral Sleep Apnea Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Home Sleep Apnea Testing Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Home Sleep Screening Devices Market
Sleep Medicine
Non-Wearable Sleep Tracker Market
Sleep Medicine
Sleep Soother Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Sleep Movement Disorders Market
Sleep Medicine
Global Wearable Sleep Trackers Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Insomnia Market
Sleep Medicine
Sleep Disorder Market
Sleep Medicine
Sleep Study Equipment Market