
 Hydrolyzed Bovine Collagen Market | 2026-2036
Hydrolyzed Bovine Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrolyzed Bovine Collagen Market Foresight
Buyer concentration across nutraceutical private labels is rebalancing as mid-sized functional food brands fragment procurement while large healthcare formulators consolidate supply agreements. Gelita AG leverages its German manufacturing scale to dominate pharmaceutical-grade collagen peptide output. Rousselot anchors European supply through its integrated hide-processing infrastructure. Darling Ingredients competes via vertical control over rendering-to-peptide operations across North American slaughterhouse networks.
Hydrolyzed bovine collagen comprises enzymatically cleaved peptides derived from cattle hides and bones, typically yielding molecular weights between 3,000 and 5,000 Daltons for optimal intestinal absorption and tissue bioavailability. Powder formulations occupy the largest volume share due to bulk manufacturing efficiency and stability in dry-blend nutraceutical processing. Nutraceutical applications lead value generation as clinical positioning around joint health and skin elasticity commands premium pricing. Liquid formats represent the fastest-growing segment, driven by ready-to-drink protein positioning and convenience-oriented consumer preferences in functional beverages.
FDA oversight of bovine-sourced ingredients under BSE-related feed and food safety rules shapes import documentation burdens, while EFSA novel food evaluations constrain European market entry for non-traditional collagen delivery formats. The USDA and FSIS jointly regulate collagen processing facility inspections, creating compliance cost differentiation between domestic and imported supply. Stakeholders must monitor evolving EFSA health claim substantiation requirements for collagen-specific structural and beauty positioning claims.
Market Dynamics
Enzymatic hydrolysis efficiency gains are compressing production costs while FDA and EFSA purity mandates simultaneously elevate compliance burdens, creating divergent margin trajectories between scaled pharmaceutical-grade suppliers and commodity nutraceutical processors.
Growth Catalysts
- Sports nutrition end-use expansion:Functional beverage brands in the United States are formulating hydrolyzed bovine collagen into ready-to-drink protein portfolios, pulling volume from traditional whey isolates.
- EFSA novel food pathway maturation:Streamlined safety evaluations for enzymatically processed collagen peptides are accelerating European market entry for liquid delivery formats previously restricted to powder.
- Joint health clinical positioning:Published trials on collagen peptide bioavailability are expanding reimbursement discussions with German and Japanese health insurers for osteoarthritis adjuvant therapy.
Market Restraints
- BSE-related feed safety documentation:Cross-border shipments into the United States require USDA-APHIS veterinary certificates tracing cattle origin to BSE-free herds, adding 4-6 week clearance delays.
- Cattle hide supply concentration:Rendering capacity clusters in Midwestern US packing plants and Brazilian slaughterhouse networks, exposing buyers to regional disease outbreak disruptions.
- Plant-based protein substitution:Pea and rice protein isolates with comparable amino acid profiles are capturing price-sensitive clean-label positioning in mass-market sports nutrition.
Strategic Opportunities
- Indian nutraceutical white space:FSSAI functional food regulations are clarifying collagen peptide import pathways, opening formulation partnerships with Ayurveda-positioned domestic brands.
- Cosmeceutical topical delivery:Micronized collagen peptide serums are penetrating Korean and Japanese dermocosmetic channels, commanding per-gram premiums over ingestible formats.
- EU Green Deal biowaste valorization:Incentives for circular processing of slaughterhouse byproducts are subsidizing hide-to-peptide facility upgrades in France and the Netherlands.
Industry Challenges
- Peptide characterization expertise scarcity:Analytical chemists skilled in molecular weight distribution validation via HPLC-SEC are concentrated in pharmaceutical hubs, constraining mid-tier processor quality expansion.
- Multi-jurisdiction certification timelines:Synchronizing FDA GRAS self-affirmation, EFSA novel food approval, and Health Canada natural health product licensing extends product launch cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrolyzed Bovine Collagen Market |
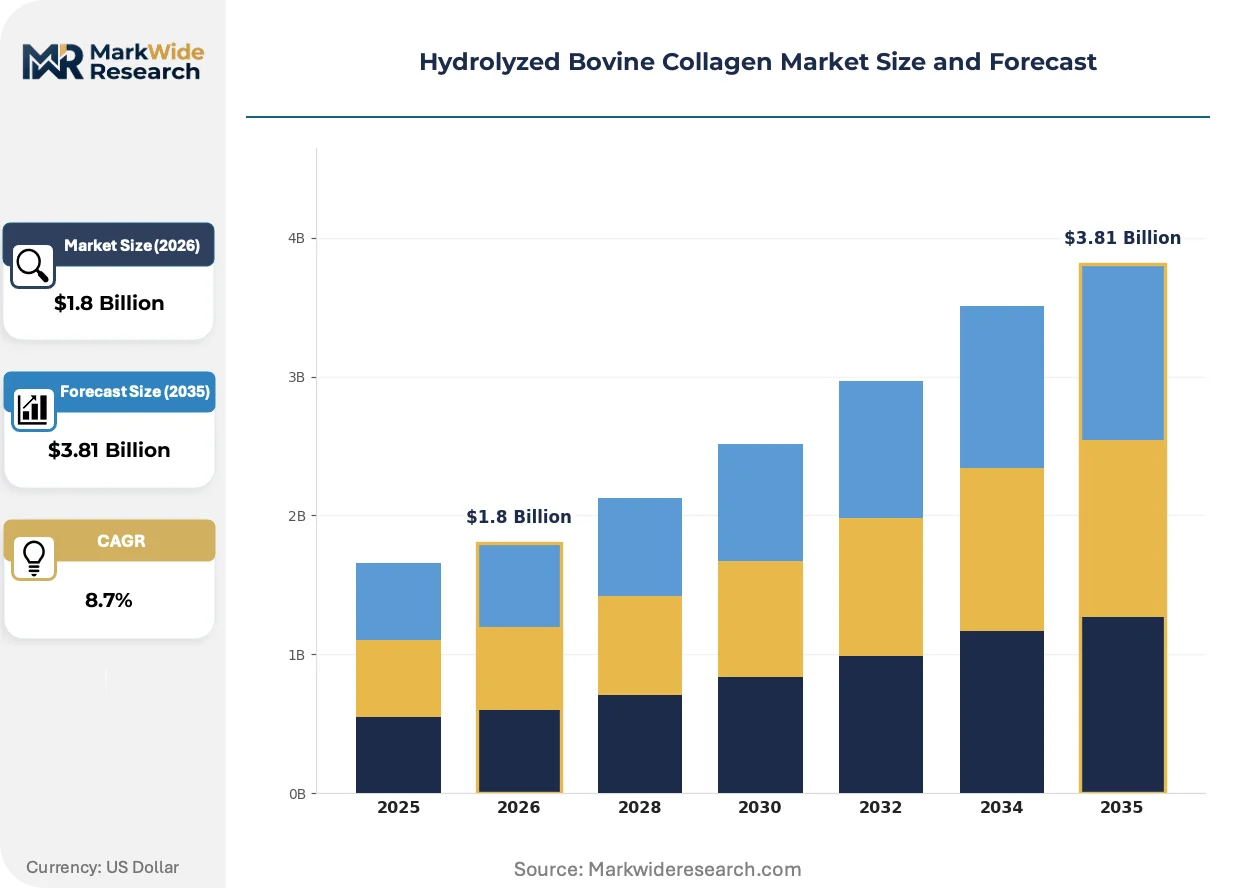
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Liquid, Gummies End User: Healthcare, Personal Care, Food & Beverage, Nutraceuticals Application: Joint Health, Skin Care, Muscle Recovery, Bone Health Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Gelita AG, Rousselot, Nitta Gelatin, Weishardt, Darling Ingredients, PB Leiner, Vital Proteins, Nippi Inc., ConnOils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrolyzed Bovine Collagen Market Shifts & Advancements
Continuous enzymatic reactor technology is displacing batch processing economics while regulatory digitization of supply chain traceability is rewriting procurement qualification protocols across pharmaceutical and nutraceutical buyer segments.
Membrane filtration-enzymatic hydrolysis hybrid systems are consolidating small-mid processor competitive positions by reducing energy intensity 30-40% versus traditional thermal hydrolysis. German and Swiss equipment vendors are deploying these units across North American and European contract manufacturing facilities. The technology is consolidating regional supply bases as capital-intensive upgrades favor multi-tonne daily output operations over artisanal batch producers.
EFSA's 2023 updated guidance on collagen-specific health claim substantiation is tightening clinical trial design requirements for structural and beauty positioning. Manufacturers must now demonstrate peptide-specific bioactivity rather than generic protein equivalence. Premium nutraceutical brands with existing dermatological and orthopaedic clinical programs are accelerating dossier preparation while commodity suppliers retreat to generic protein positioning.
Direct-to-consumer subscription models are fragmenting traditional distributor control over collagen peptide volume allocation. US-based functional food startups are bypassing legacy nutraceutical wholesalers, negotiating directly with Rousselot and Gelita AG for branded ingredient supply. This channel compression is most pronounced in anti-aging and gut health verticals where influencer-driven trial conversion rates exceed retail shelf velocity.
Hydrolyzed Bovine Collagen Market Segmentation
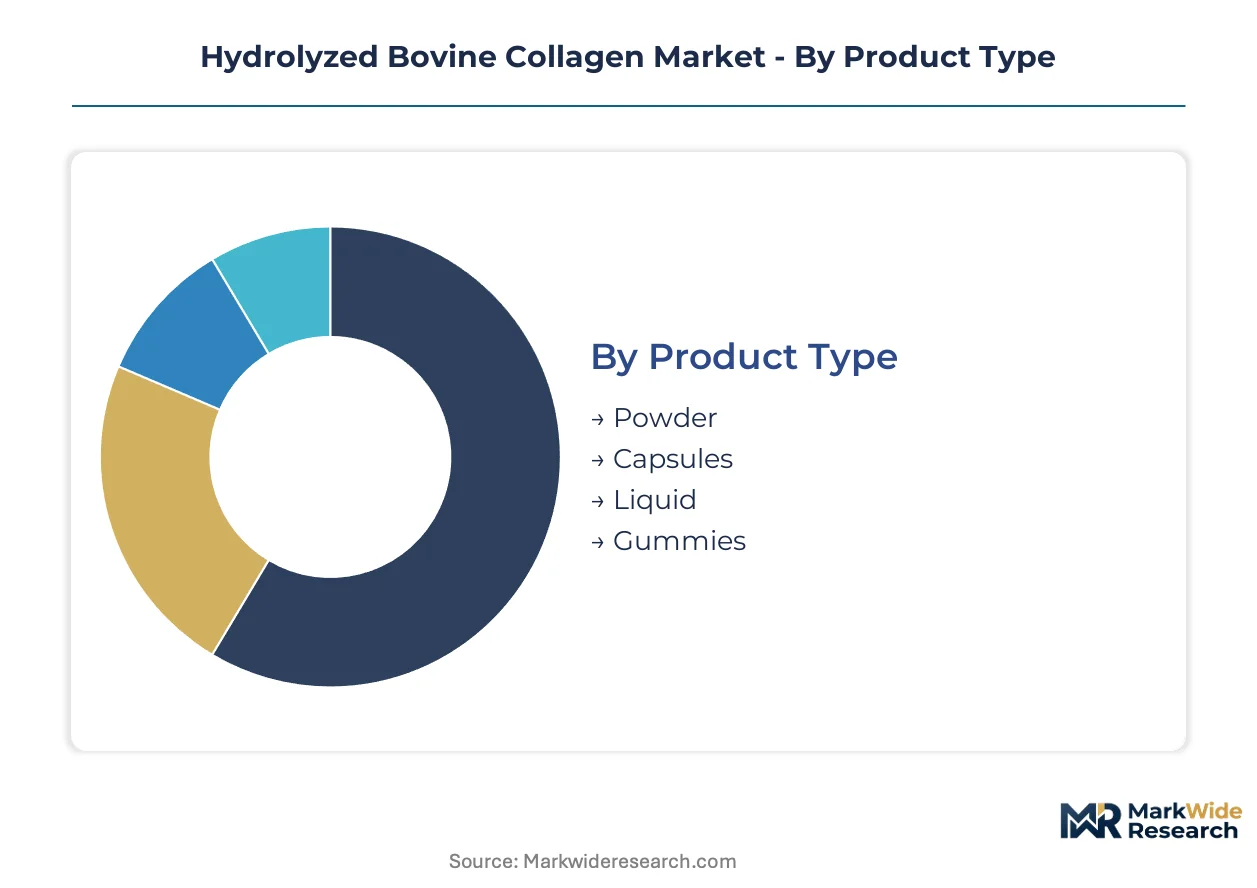
Segmentation in hydrolyzed bovine collagen reveals how formulation formats, end-use specifications, and channel economics fragment procurement strategies across pharmaceutical, nutraceutical, and cosmeceutical buyers. Each dimension carries distinct margin profiles and regulatory burdens that reshape competitive positioning.
Product Type:
Buyers differentiate primarily by manufacturing scalability and stability requirements in downstream processing.
- Powder:Dry-blend formulations dominate bulk nutraceutical manufacturing due to shelf stability and ease of incorporation into protein matrices. United States sports nutrition brands source powder grades for high-volume ready-to-mix applications where cost-per-serving drives procurement decisions.
- Liquid:Ready-to-drink delivery formats require cold-chain or aseptic processing capabilities. Functional beverage startups in North American direct-to-consumer channels are pulling volume into liquid collagen as convenience positioning commands subscription pricing premiums.
- Capsules:Encapsulation suits pharmaceutical-grade peptide dosing with precise unitization for joint health adjuvant therapy.
- Gummies:Confectionery-positioned formats target compliance-sensitive demographics in beauty and wellness verticals.
Powder leads volumes today; liquid is gaining share fastest.
End User:
Margin capture varies sharply by the clinical rigor of health claims and certification requirements each vertical demands.
- Nutraceuticals:Dietary supplement brands command premium positioning through dermatological and orthopaedic clinical substantiation. EFSA health claim dossiers and FDA GRAS self-affirmation create regulatory moats that commodity suppliers cannot cross.
- Healthcare:Hospital and clinic procurement of collagen peptides for wound healing and osteoarthritis management requires pharmaceutical-grade GMP certification. German and Japanese health insurers are expanding reimbursement discussions for peptide-specific bioactivity demonstrations.
- Personal Care:Topical collagen serums in Korean and Japanese dermocosmetic channels extract per-gram premiums over ingestible formats through micronization and transdermal delivery claims.
- Food & Beverage:Functional food integration faces EFSA novel food evaluations for non-traditional delivery formats, constraining European market entry timelines.
Nutraceuticals anchor value generation; healthcare is climbing the fastest as reimbursement frameworks mature.
Application:
Clinical trial investment and health claim substantiation intensity separate premium positioning from commodity protein equivalence.
- Joint Health:Osteoarthritis adjuvant therapy positioning requires peptide-specific bioactivity validation under EFSA's tightened guidance. Published trials on collagen peptide bioavailability are expanding German and Japanese insurer discussions.
- Skin Care:Beauty-from-within and topical anti-aging claims command the highest consumer willingness-to-pay in direct-to-consumer subscription models.
- Muscle Recovery:Sports nutrition brands formulate collagen into protein portfolios alongside traditional isolates, though plant-based substitution pressure is acute in price-sensitive mass market tiers.
- Bone Health:Calcium-collagen co-formulation targets aging demographics with density maintenance positioning.
Joint health dominates clinical investment; skin care shows the steepest expansion trajectory in premium channels.
Distribution Channel:
Channel control determines volume allocation and pricing power as legacy wholesale structures fragment.
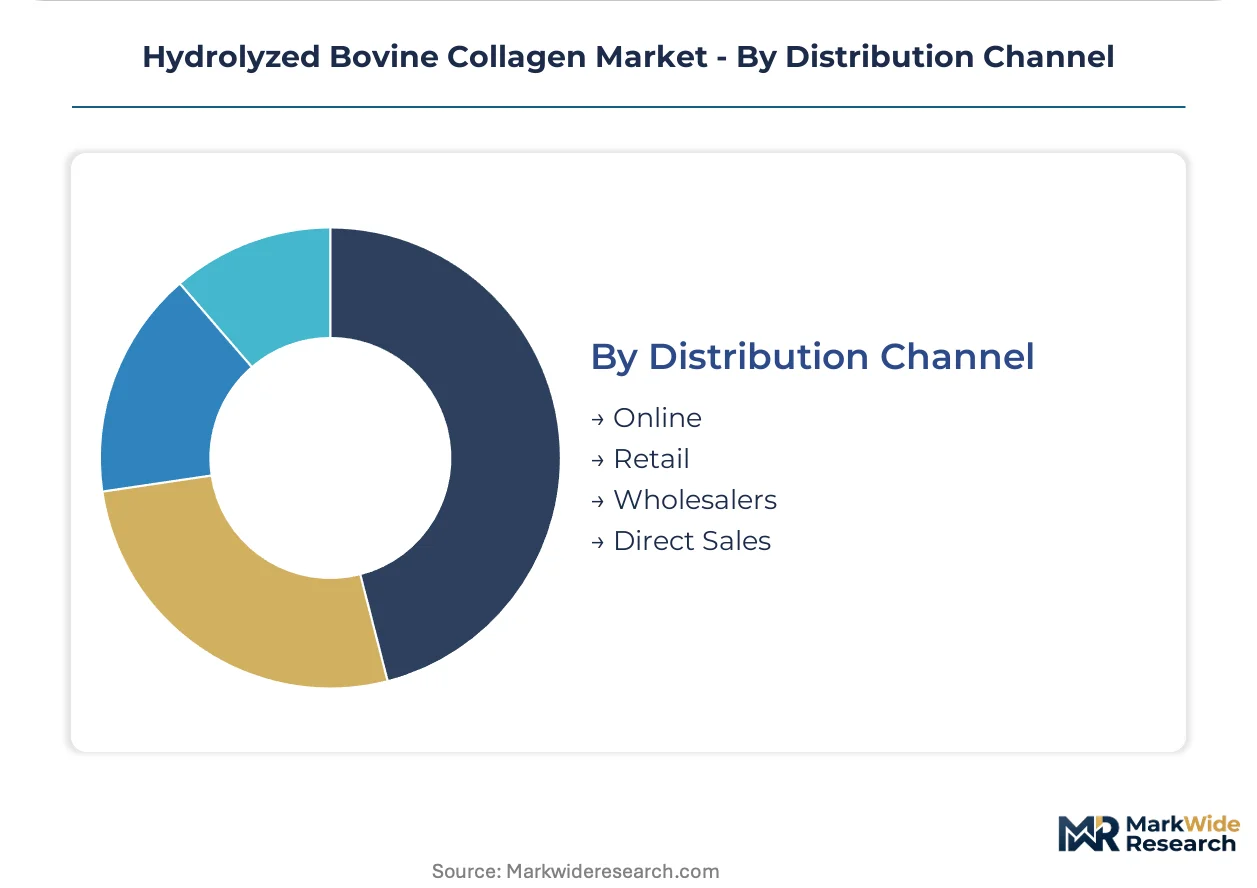
- Online:Direct-to-consumer subscription models bypass traditional distributors. US functional food startups negotiate directly with ingredient suppliers for branded peptide supply, compressing channel margins.
- Retail:Mass-market shelf placement in pharmacies and specialty stores requires trade spend and slotting fee structures that favor scaled suppliers.
- Wholesalers:Legacy nutraceutical distributors retain control over commodity powder volumes but lose share in influencer-driven verticals.
- Direct Sales:Practitioner and clinic channels capture premium pricing for pharmaceutical-grade certifications.
Online channels are expanding most quickly; retail retains bulk volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pharmaceutical-grade peptide certification standards while Brazil leverages integrated slaughterhouse networks for raw material access. Regulatory divergence between EFSA's tightened health claim requirements and FDA's BSE-related import protocols fragments procurement strategies across Atlantic trade lanes.
United States
Sports nutrition brands in California and Texas drive premium collagen sourcing for ready-to-drink protein portfolios. FDA oversight under BSE-related feed safety rules requires USDA-APHIS veterinary certificates tracing cattle origin, adding clearance delays for cross-border shipments. Midwestern packing plants in Illinois and Iowa concentrate rendering capacity, exposing buyers to regional disease outbreak disruptions.
Germany
Healthcare formulators in Bavaria and North Rhine-Westphalia consolidate supply agreements for pharmaceutical-grade GMP certification. EFSA's 2023 updated guidance on collagen-specific health claim substantiation tightens clinical trial design requirements for structural and beauty positioning. Gelita AG leverages its Eberbach manufacturing scale to dominate peptide output for German and European hospital procurement.
Brazil
Mid-sized functional food brands fragment procurement while large meatpackers integrate hide-to-peptide operations. ANVISA regulates novel food evaluations for enzymatically processed collagen peptides, constraining import pathways for non-traditional delivery formats. São Paulo and Minas Gerais slaughterhouse networks anchor rendering capacity, subsidizing facility upgrades through circular processing incentives.
Japan
Health insurers in Tokyo and Osaka expand reimbursement discussions for osteoarthritis adjuvant therapy using peptide-specific bioactivity demonstrations. PMDA pharmaceutical-grade certification requirements differentiate premium positioning from commodity protein equivalence. Kansai region dermocosmetic channels extract per-gram premiums for micronized collagen peptide serums in topical anti-aging applications.
India
Ayurveda-positioned domestic brands in Maharashtra and Gujarat seek formulation partnerships as FSSAI functional food regulations clarify collagen peptide import pathways. CDSCO and FSSAI joint oversight creates multi-jurisdiction certification timelines extending product launch cycles. Karnataka nutraceutical startups bypass legacy wholesalers, negotiating directly with ingredient suppliers for branded peptide supply.
Hydrolyzed Bovine Collagen Market Competitive Landscape
German producers anchor the pharmaceutical-grade tier; North American specialists hold rendering-to-peptide integration advantages. The vendor base stratifies between scaled GMP-certified suppliers and commodity nutraceutical processors. Three archetypes dominate: integrated meatpacker-chemical processors, pure-play peptide specialists, and diversified gelatin-to-collagen converters. Capacity expansion and strategic partnerships constitute the dominant competitive moves as mid-tier processors face margin compression from enzymatic efficiency gains.
Among German fabricators, Gelita AG exemplifies the diversified gelatin-to-collagen converter archetype through its pharmaceutical-grade certification depth. Rousselot occupies a position within the pure-play peptide specialist tier, representing European supply integration through hide-processing infrastructure. Darling Ingredients anchors the integrated meatpacker-chemical processor archetype, exemplifying vertical control over rendering operations across North American slaughterhouse networks.
| Leading Market Players |
|---|
| Gelita AG |
| Rousselot |
| Nitta Gelatin |
| Weishardt |
| Darling Ingredients |
| PB Leiner |
| Vital Proteins |
| Nippi Inc. |
| ConnOils |
| Others |
Supply & Pricing Matrix
Cattle hide futures pricing from the Chicago Mercantile Exchange cascades through enzymatic hydrolysis cost structures into three-tier pricing stratification across pharmaceutical-grade, nutraceutical-standard, and commodity-economy peptide tiers. Midwestern rendering capacity concentration and Brazilian slaughterhouse network economics anchor raw material pass-through mechanics that differentiate margin capture between integrated meatpackers and toll-processing specialists.
Pricing Analysis
Capacity additions in Germany and Switzerland are reshaping price floors for pharmaceutical-grade peptide certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified hospital supply from nutraceutical dry-blend grades and commodity protein positioning. Cost compression in standard nutraceutical tiers is intensifying because enzymatic efficiency gains outpace brand premium capture. Mass-market sports nutrition brands exhibit highest price sensitivity, while Japanese dermocosmetic channels show lowest elasticity for micronized serum formats.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian slaughterhouse networks for hide supply to European hydrolysis facilities. Geographic concentration centers on the United States, Brazil, and Germany for rendering-to-peptide operations. Raw material dependencies draw from cattle hides, bones, and specialized protease enzymes for hydrolysis. Tariff exposure on cross-border hide shipments creates structural risk for Atlantic trade lanes. Distribution runs through direct-to-consumer subscription channels and legacy nutraceutical wholesalers in parallel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrolyzed bovine collagen functions as a stable compounder anchored by demographic aging and clinical reimbursement expansion for joint health adjuvant therapy. Sports nutrition and cosmeceutical verticals provide sustained volume pull with predictable pricing power.
For Market Incumbents: Extend pharmaceutical-grade certification depth into Japanese PMDA and German GMP hospital procurement channels to defend against plant-based protein substitution in mass-market tiers. Backward integration into captive hide rendering through Midwestern packing plant partnerships secures raw material cost control. Accelerate EFSA health claim dossier preparation for peptide-specific bioactivity positioning before 2025 guidance enforcement tightens further.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for Ayurveda-positioned collagen peptides targeting Maharashtra and Gujarat wellness markets. White-space opportunities concentrate in Indian FSSAI-compliant functional food formulations and Korean dermocosmetic topical delivery partnerships. Micronized serum co-development with established K-beauty brands provides fastest credibility transfer.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier enzymatic processors possessing membrane filtration-enzymatic hydrolysis hybrid technology but lacking multi-jurisdiction certification breadth. Five-to-ten year viability favors specialists with demonstrated EFSA novel food approval timelines and existing German or Japanese health insurer dialogue. Watch for FDA GRAS self-affirmation completion rates as inflection signal for premium tier margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering | Captive hide supply from Midwestern packing plants insulates against Brazilian network disruption. |
| EFSA Health Claim Dossier Investment | Peptide-specific bioactivity validation unlocks German and Dutch hospital procurement premiums. |
| Membrane Filtration Technology Upgrade | Energy intensity reduction of 30-40% consolidates regional supply base around scaled processors. |
| Direct-to-Consumer Channel Launch | Bypassing legacy wholesalers captures subscription pricing premiums in anti-aging verticals. |
| Indian FSSAI Partnership Development | Ayurveda-positioned domestic brand alliances open formulation pathways in Maharashtra and Gujarat. |
Research Methodology
Multiple input streams — procurement director interviews at nutraceutical formulators, regulatory affairs consultations with EFSA and FDA specialists, and customs trade data analysis — were reconciled to construct supply-demand balances. Primary engagement with sports nutrition brand managers, pharmaceutical peptide procurement leads, and enzymatic equipment vendors was cross-validated against secondary sources including FDA BSE-related feed safety filings, EFSA novel food submission databases, and SEC 10-K disclosures from integrated meatpackers. Bottom-up capacity modeling and top-down consumption estimates were triangulated across the analysis window.
Historical shipment patterns were cross-referenced against expert panel input from German healthcare formulators and Brazilian slaughterhouse operations directors. Segmentation modeling incorporated product format, end-use vertical, application claim substantiation intensity, and distribution channel economics. CAGRs were derived through regression analysis of enzymatic hydrolysis capacity expansion timelines and clinical trial publication trajectories for joint health positioning. Forecast inputs included EFSA health claim approval velocity and Japanese health insurer reimbursement discussion progression.
The model assumes a particular technology adoption path; alternative pathways for continuous enzymatic reactor displacement of batch processing would alter the outlook. Forecasts reflect assumptions around regulatory digitization of supply chain traceability and EFSA guidance enforcement timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Cognitive Health Ingredients Market
Nutraceuticals
UK Pet Nutraceuticals Market
Nutraceuticals
Healthy Care Coenzyme Q10 Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
Levocarnitine Market
Nutraceuticals
Cordyceps Militaris Extract Market
Nutraceuticals
Postbiotics Market
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
Anti-Inflammatory Peptides Market
Nutraceuticals
Global 5-Hydroxytryptophan (5-HTP) Market
Nutraceuticals
North America Effervescent Tablet Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
Tetrahydropalmatine Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
US and China Glucose Market