
 North America Effervescent Tablet Market | 2026-2036
North America Effervescent Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
North America Effervescent Tablet Market Analytics
Premium effervescent formulations is bifurcating the North America effervescent tablet market into clinically validated and commodity-grade tiers. Bayer AG leverages its pharmaceutical heritage to sustain credibility in condition-specific effervescent lines. Pfizer Inc. anchors its position through R&D intensity in bioavailable mineral complexes. Perrigo Company plc competes aggressively in private-label effervescent offerings across drugstore channels.
North America effervescent tablets are water-dissolvable dosage forms containing sodium bicarbonate and citric acid or tartaric acid as effervescent couples, designed to release carbon dioxide upon contact with water for rapid absorption of active ingredients. These formulations serve primary commercial purposes in nutritional supplementation, over-the-counter analgesia, and sports hydration where gastric tolerance and onset speed matter. Vitamin supplements occupy the largest revenue pool as preventive health routines expand among aging demographics. Electrolyte products represent the fastest-growing segment as fitness enthusiasts and athletic programs adopt effervescent rehydration protocols. Online retailers capture disproportionate margin expansion through subscription-based replenishment models and direct-to-consumer personalization.
The FDA enforces Current Good Manufacturing Practice regulations for dietary supplements while Health Canada's Natural and Non-prescription Health Products Directorate mandates site licensing and product licensing for effervescent entries. These frameworks elevate compliance costs for new entrants but reinforce quality differentiation among established manufacturers. Stakeholders must monitor evolving monograph updates and state-level labeling precedents to anticipate reformulation requirements and channel eligibility shifts.
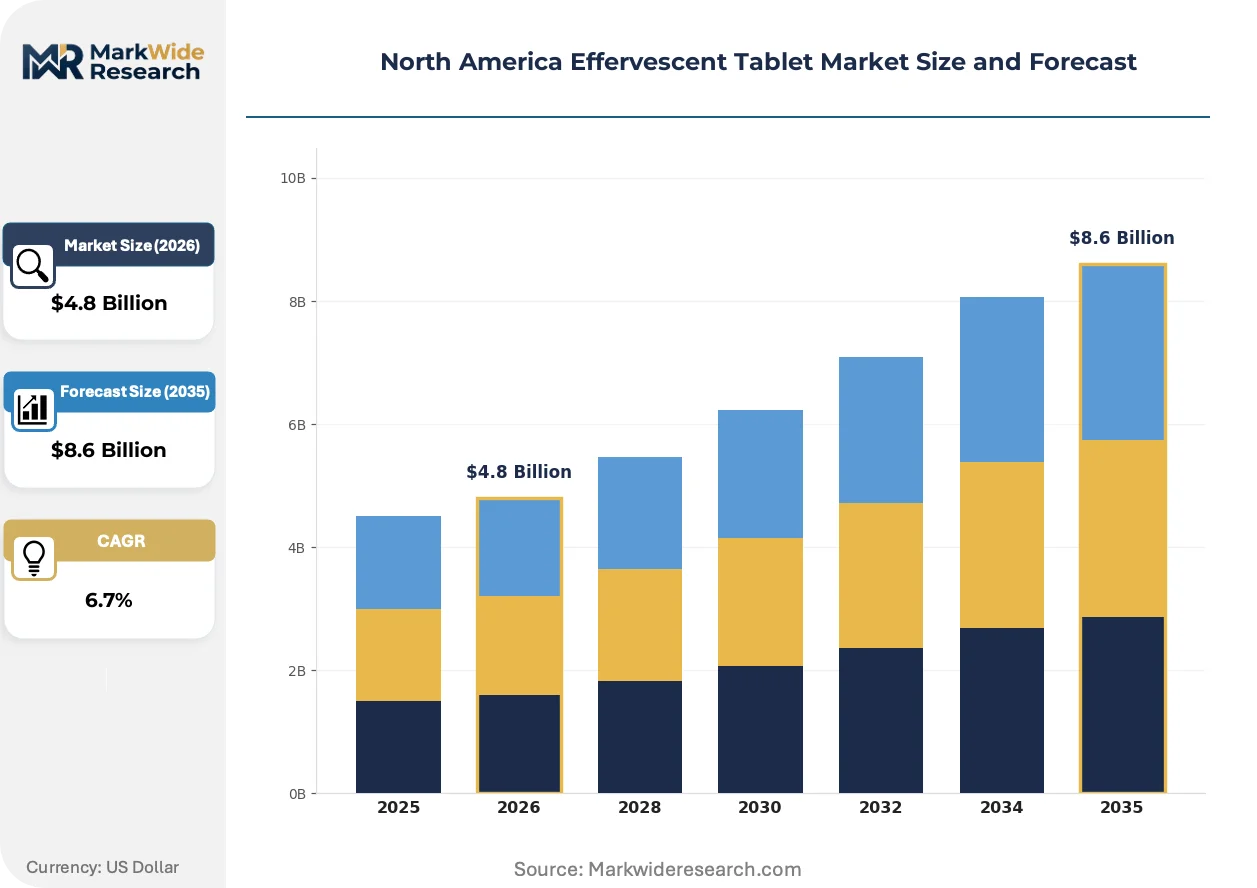
Market Dynamics
The North America effervescent tablet market is bifurcating into clinically validated and commodity-grade tiers as FDA labeling requirements tighten and preventive health routines expand among aging demographics.
Growth Catalysts
- Fitness Enthusiast Demand:Sports nutrition applications are widening as athletic programs adopt effervescent rehydration protocols. This segment now drives disproportionate volume in electrolyte formulations.
- CGMP Enforcement:The FDA's Current Good Manufacturing Practice regulations for dietary supplements elevate quality benchmarks. Compliance investments by established manufacturers reinforce brand differentiation.
- California Wellness Concentration:The state's health-conscious consumer base generates outsized demand for premium vitamin and mineral effervescent products.
Market Restraints
- Sodium Bicarbonate Volatility:Input cost fluctuations for effervescent couples compress margin structures, particularly for private-label producers without captive chemical supply.
- Site Licensing Burden:Health Canada's Natural and Non-prescription Health Products Directorate mandates dual site and product licensing, extending time-to-market for new Canadian entries.
- Tablet Format Substitution:Gummy vitamins and liquid shot formats capture younger demographics seeking flavor variety over effervescent fizz mechanics.
Strategic Opportunities
- Subscription Replenishment Models:Direct-to-consumer personalization through online retailers captures recurring revenue streams and reduces customer acquisition costs.
- Condition-Specific Lines:Immune support and sleep-focused effervescent formulations address underpenetrated need states beyond general multivitamin positioning.
- Northeast Pharmacy Corridors:The region's dense retail pharmacy network offers shelf-space expansion for clinically positioned effervescent brands.
Industry Challenges
- Reformulation Complexity:State-level labeling precedents force continuous ingredient adjustments, complicating regional SKU management and inventory planning.
- Monograph Update Uncertainty:Evolving FDA dietary supplement monographs create compliance timeline risk for products with borderline ingredient status.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Effervescent Tablet Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin Supplements, Mineral Supplements, NSAIDs, Electrolyte Products End User: Retail Consumers, Health Professionals, Pharmacies, Fitness Enthusiasts Distribution Channel: Online Retailers, Drugstores, Supermarkets, Specialty Shops Formulation: Fruit-Flavored, Sugar-Free, Caffeinated, Herbal Infused |
| Companies Covered | Bayer AG, Pfizer Inc., GlaxoSmithKline plc, Abbott Laboratories, Novartis AG, Reckitt Benckiser Group PLC, Perrigo Company plc, Bristol Myers Squibb Company, CHIESI SAS, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Effervescent Tablet Market Evolving Landscape
Bioavailability enhancement technologies and channel disintermediation are compressing traditional competitive advantages while elevating R&D intensity across formulation science.
Clean-label effervescent bases utilizing potassium bicarbonate and malic acid couples are displacing conventional sodium-heavy formulations. Health-conscious buyers in California and the Pacific Northwest are accelerating adoption of these reduced-sodium alternatives. This chemistry shift is compressing market share for legacy effervescent brands dependent on standard bicarbonate-citric systems.
The FDA's tightening enforcement of 21 CFR Part 111 dietary supplement regulations is elevating documentation burdens for contract manufacturers. Facilities must now maintain batch records and testing protocols that match pharmaceutical-grade standards. Small and mid-sized effervescent producers in the United States are responding by consolidating manufacturing partnerships or exiting the market entirely.
Replenishment automation through pharmacy-integrated subscription platforms is fragmenting traditional retail purchasing patterns. Consumers in the Northeast and Midwest are migrating toward auto-ship models that bypass in-store selection. This behavioral shift is most visible among chronic-condition users of daily effervescent supplements who prioritize convenience over brand exploration.
North America Effervescent Tablet Market Segmentation
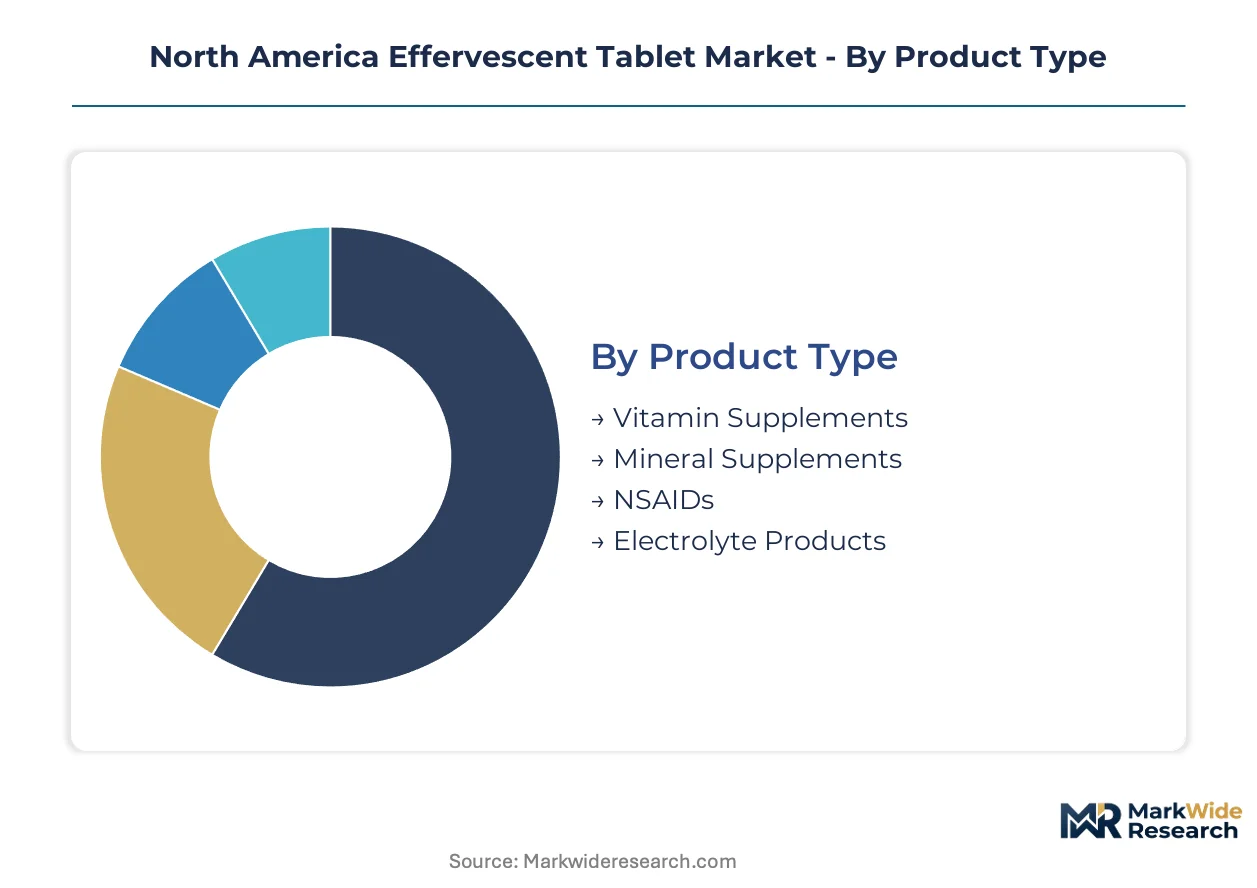
Effervescent tablet segmentation in North America reveals distinct margin architectures across product chemistry, buyer sophistication, and channel control points. Manufacturers calibrate R&D investment and pricing power differently across each dimension.
Product Type:
Vitamin supplements command the deepest margin pools due to recurring purchase frequency and premium positioning in preventive health routines.
- Vitamin Supplements:Formulations deliver water-soluble vitamins (C, B-complex) and fat-soluble vitamins (D, E) in bicarbonate-citric acid matrices for rapid gastric emptying. Demand concentrates among aging demographics in California and the Northeast pursuing daily preventive regimens under FDA dietary supplement labeling requirements.
- Electrolyte Products:Sodium, potassium, and magnesium complexes target rapid rehydration through osmotic balance restoration. Athletic programs and fitness enthusiasts in the Pacific Northwest and Texas are adopting these formulations fastest as training protocols formalize.
- Mineral Supplements:Calcium and iron effervescents address bioavailability limitations of conventional tablet formats.
- NSAIDs:Analgesic effervescents prioritize onset speed for acute pain management.
Vitamin supplements hold installed capacity. Electrolyte products are rotating up the share rankings.
End User:
Retail consumers generate the highest absolute volumes, though health professionals extract superior per-unit economics through clinical credibility premiums.
- Retail Consumers:Individual purchasers selecting self-directed supplementation for wellness maintenance and minor ailment management. California's wellness-oriented consumer base and the Northeast's pharmacy-dense corridors drive disproportionate volume in premium formulations.
- Fitness Enthusiasts:Systematic users integrating effervescent products into structured training and recovery protocols. Sports nutrition applications are widening as collegiate and professional athletic programs adopt standardized rehydration protocols.
- Health Professionals:Physicians and nutritionists recommending condition-specific effervescent formulations.
- Pharmacies:Institutional purchasers managing inventory for front-of-store supplement categories.
Retail consumers hold installed capacity. Fitness enthusiasts are rotating up the share rankings.
Distribution Channel:
Online retailers capture the most favorable margin expansion through subscription-based replenishment models and reduced customer acquisition costs.
- Online Retailers:Direct-to-consumer platforms leveraging personalization algorithms and auto-ship mechanics. Consumers in the Midwest and Northeast are migrating toward replenishment automation that bypasses in-store selection.
- Drugstores:CVS, Walgreens, and independent pharmacy chains controlling shelf-space allocation for clinically positioned brands. The Northeast corridor offers dense retail pharmacy networks for expansion.
- Supermarkets:Mass-market channels emphasizing price-competitive commodity-grade formulations.
- Specialty Shops:Nutrition stores and wellness boutiques curating premium and clean-label selections.
Drugstores hold installed capacity. Online retailers are rotating up the share rankings.
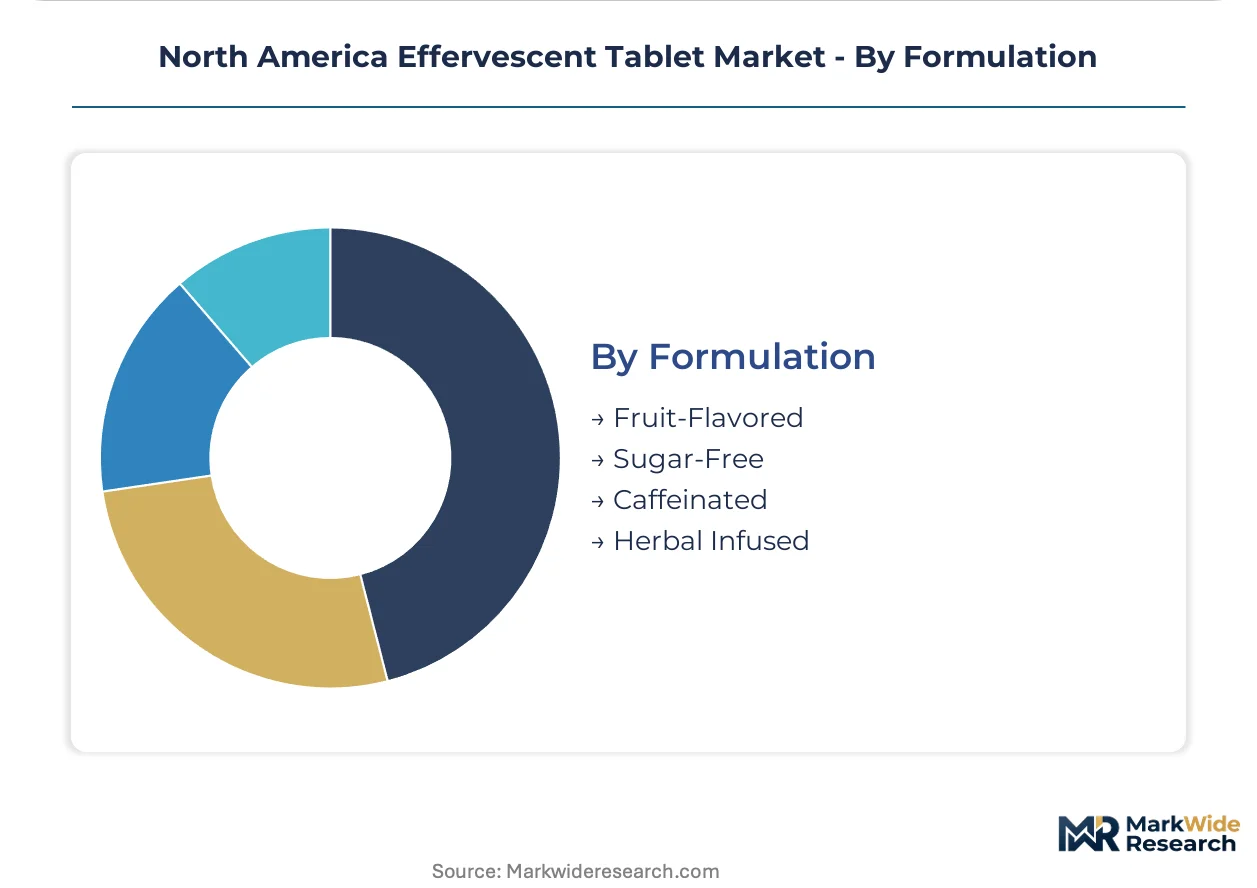
Formulation:
Sugar-free variants command pricing premiums aligned with metabolic health positioning and diabetic-friendly claims.
- Sugar-Free:Aspartame, sucralose, or stevia-sweetened bases targeting glycemic-conscious users and diabetic populations. Health Canada and FDA labeling requirements for sugar content claims elevate compliance investment.
- Fruit-Flavored:Citrus, berry, and tropical profiles masking alkaline mineral aftertastes. California and Pacific Northwest consumers accelerate adoption of natural flavor systems over artificial alternatives.
- Caffeinated:Energy-positioned formulations combining effervescent delivery with stimulant effects.
- Herbal Infused:Botanical extracts (ginger, turmeric, echinacea) layered onto mineral or vitamin bases.
Fruit-flavored holds installed capacity. Sugar-free is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Mexico exhibit the highest price elasticity, gravitating toward value-tier effervescent formulations, while consumers in the United States absorb premium pricing for clinically validated products with minimal volume sensitivity.
United States
Fitness enthusiasts and aging preventive health adopters drive effervescent demand across California and the Northeast pharmacy corridors. The FDA enforces Current Good Manufacturing Practice regulations under 21 CFR Part 111, elevating documentation burdens for contract manufacturers. Los Angeles and San Francisco clusters concentrate clean-label formulation innovation as reduced-sodium alternatives displace conventional bicarbonate-citric systems.
Canada
Health-conscious consumers in Ontario and British Columbia accelerate adoption of premium vitamin and mineral effervescents. Health Canada's Natural and Non-prescription Health Products Directorate mandates dual site and product licensing, extending time-to-market for new entries. The Toronto-Waterloo corridor hosts specialized contract manufacturing facilities serving both domestic demand and cross-border private-label production.
Mexico
Mass-market retail consumers in Mexico City and Guadalajara drive volume for commodity-grade effervescent supplements at price-sensitive tiers. The country's national pharmaceutical regulator applies evolving labeling standards that increase compliance costs for imported formulations. Northern border states concentrate distribution infrastructure facilitating cross-border supply integration with United States retail networks.
North America Effervescent Tablet Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America effervescent tablet market. Pharmaceutical heritage companies anchor the clinically validated tier with bioavailability-focused R&D investments, while private-label specialists dominate commodity-grade production through manufacturing scale. Three archetypes define competitive positioning: condition-specific innovators, private-label volume producers, and diversified healthcare conglomerates. Strategic moves concentrate on portfolio diversification into clean-label formulations and backward integration into captive chemical supply.
Among European-heritage pharmaceutical conglomerates, Bayer AG and Novartis AG exemplify the condition-specific innovation archetype, leveraging legacy credibility in clinically positioned effervescent lines. Pfizer Inc. occupies a position within the bioavailability-focused tier, representing R&D-intensive mineral complex development. Perrigo Company plc sits within the private-label manufacturing archetype, anchoring cost-competitive production across drugstore channels.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Abbott Laboratories |
| Novartis AG |
| Reckitt Benckiser Group PLC |
| Perrigo Company plc |
| Bristol Myers Squibb Company |
| CHIESI SAS |
| Others |
Value Network & Pricing Analysis
FDA Current Good Manufacturing Practice enforcement gates both supplier qualification and price differentiation simultaneously, as only manufacturers maintaining pharmaceutical-grade batch documentation can access premium-tier shelf placement in CVS and Walgreens networks. This regulatory filter bifurcates the market into clinically validated and commodity-grade supply pools with divergent margin structures.
Pricing Analysis
Subscription replenishment revenue drives lifetime value for effervescent brands, with auto-ship models capturing recurring revenue streams that reduce customer acquisition costs. Three-tier pricing structure across premium, standard, and economy levels separates clinically positioned Bayer lines from private-label Perrigo offerings and Mexican value-tier imports. Cost compression in private-label tiers is intensifying because sodium bicarbonate input volatility compresses margin structures for producers without captive chemical supply. Retail consumers in Mexico exhibit highest price sensitivity, while aging preventive health adopters in California absorb premium pricing with minimal volume resistance.
Supply Chain Analysis
Port congestion across Los Angeles-Long Beach trade lanes elevates inbound logistics costs for citric acid and tartaric acid shipments originating from Chinese and Brazilian chemical producers. Active pharmaceutical ingredient sourcing draws from India, China, and domestic United States facilities, with effervescent couple manufacturing concentrated in Germany, China, and domestic specialty chemical plants. Single-source vulnerability persists for potassium bicarbonate inputs required in clean-label formulations. Distribution runs through pharmacy-integrated subscription platforms that fragment traditional retail purchasing patterns in the Northeast and Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
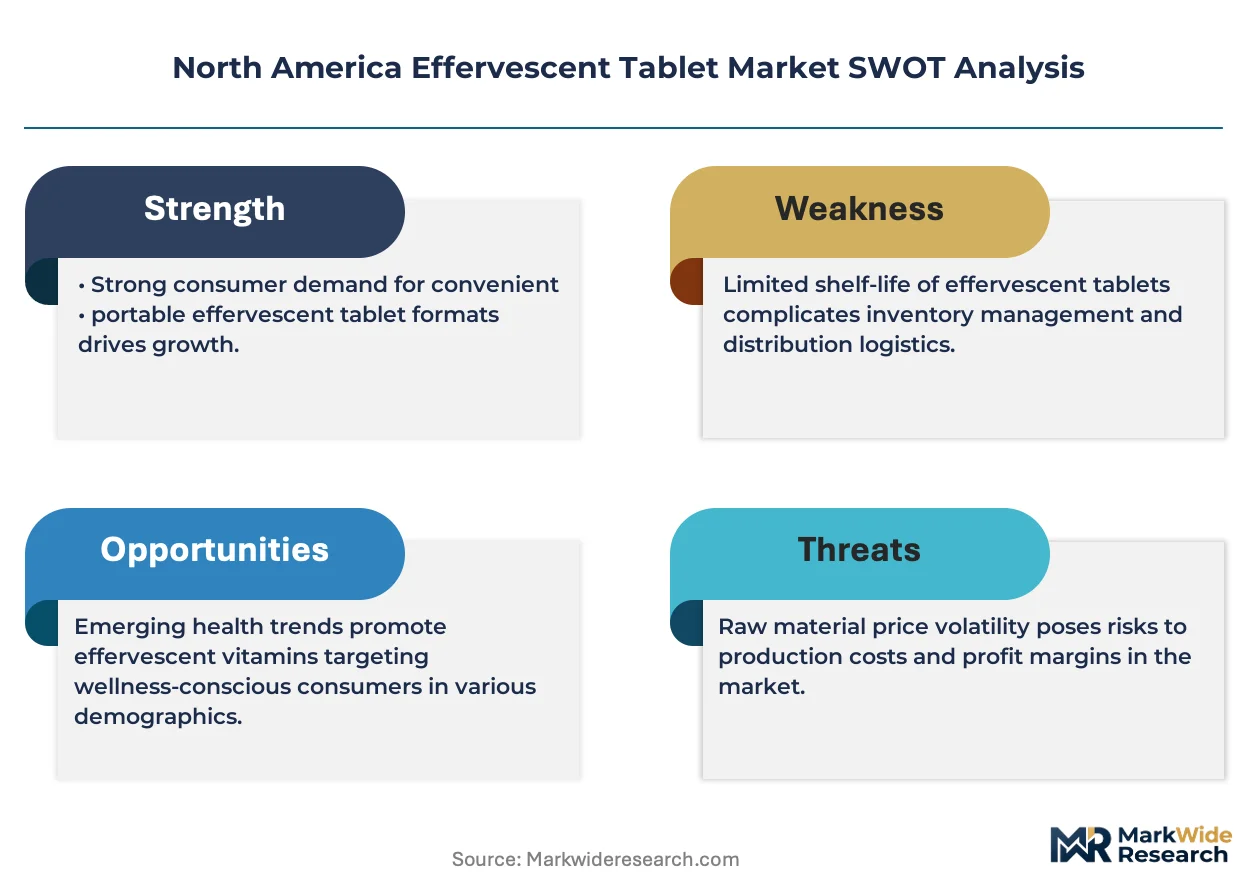
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA site licensing and Health Canada product approvals create switching costs that protect incumbent positions against unqualified entrants.
For Market Incumbents: Consolidate manufacturing partnerships to secure captive sodium bicarbonate supply and defend against margin compression from input volatility. Acquire specialized contract manufacturing facilities in the Toronto-Waterloo corridor to preempt private-label competitors from scaling Canadian production capacity.
For New Entrants and Emerging Players: Condition-specific subscription services represent the most penetrable white-space, as incumbents under-serve sleep-focused and immune-support formulations with direct-to-consumer personalization. Target fitness enthusiasts in Texas and the Pacific Northwest through athletic program partnerships that bypass established pharmacy channel gatekeepers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed contract manufacturers lacking backward integration into effervescent couple production. Long-term viability favors acquiring facilities with Health Canada site licensing and FDA 21 CFR Part 111 compliance already embedded. Monitor Health Canada monograph updates as the signal to watch for regulatory-driven consolidation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Formulation Transition | Potassium bicarbonate and malic acid couples displace sodium-heavy systems in California wellness clusters. |
| Subscription Platform Integration | Pharmacy-integrated auto-ship models bypass in-store selection for chronic-condition users in the Northeast. |
| Backward Integration into Chemical Supply | Captive sodium bicarbonate production insulates margin structures from commodity price volatility. |
| Health Canada Site Licensing Expansion | Dual jurisdiction compliance enables cross-border private-label production serving United States retailers. |
| Condition-Specific Line Extension | Sleep and immune formulations address underpenetrated need states beyond general multivitamin positioning. |
Research Methodology
A standing panel of pharmaceutical manufacturing executives, regulatory affairs specialists, pharmacy category buyers, and contract formulation scientists provided ongoing calibration across the study period. Primary interview data combined with secondary validation from FDA 21 CFR Part 111 guidance documents, Health Canada Natural and Non-prescription Health Products Directorate filings, and Nielsen retail audit data for supplement categories. Bottom-up volume modeling and top-down value triangulation anchored market size estimates.
Consistency checks validated effervescent tablet volume and value outputs against external benchmarks including customs trade data for sodium bicarbonate imports and pharmaceutical industry capacity disclosures. Segmentation dimensions spanned product chemistry, end-user sophistication, distribution channel control, and regional regulatory clusters. CAGRs were derived from regression analysis of historical consumption patterns and projected adoption curves for electrolyte formulations among fitness enthusiasts.
Forecasts assume regulatory continuity in FDA dietary supplement enforcement and Health Canada licensing regimes; material policy shifts would require re-modeling. Specific risk factors include evolving monograph updates affecting ingredient eligibility and state-level labeling precedents forcing reformulation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Immunostimulants Market
Nutraceuticals
Pet Nutraceuticals Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
Healthy Care Coenzyme Q10 Market
Nutraceuticals
Magtein Market
Nutraceuticals
Postbiotics Market
Nutraceuticals
Chondroitin Market
Nutraceuticals
Middle East and Africa Effervescent Tablet Market
Nutraceuticals
Hair Growth Supplement and Treatment Market
Nutraceuticals
Global 5-Hydroxytryptophan (5-HTP) Market
Nutraceuticals
Nootropics Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Anti Aging Agent Market
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
Hydrolyzed Bovine Collagen Market
Nutraceuticals
North America Collagen Market