
 North America OTC Health Products Market | 2026-2036
North America OTC Health Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America OTC Health Products Market Intelligence
Aftermarket consultation and pharmacist-directed self-care revenue is reconfiguring margin capture away from pure product sales toward advisory services embedded in retail channels. Johnson & Johnson leverages its heritage brand equity and shelf positioning across multiple therapeutic categories. Bayer sustains competitive density through analgesic specialization and consistent clinical messaging. Haleon anchors pharmacy relationships with digestive health and respiratory portfolios that dominate front-end merchandising.
OTC health products encompass non-prescription therapeutics formulated to active pharmaceutical ingredient standards with defined dosages, stability profiles, and labeled indications for self-diagnosed conditions. Manufacturing employs direct compression, wet granulation, or liquid fill processes with dissolution specifications typically targeting minutes for immediate-release oral forms, delivering symptom relief without clinician supervision. Analgesics and cold and cough segments carry mature volume bases with thin margins, while digestive health commands premium positioning through probiotic and acid-reduction innovations. E-commerce distribution channels represent the fastest-expanding access point, though retail pharmacies still control the majority of first-contact purchases through pharmacist trust transfer.
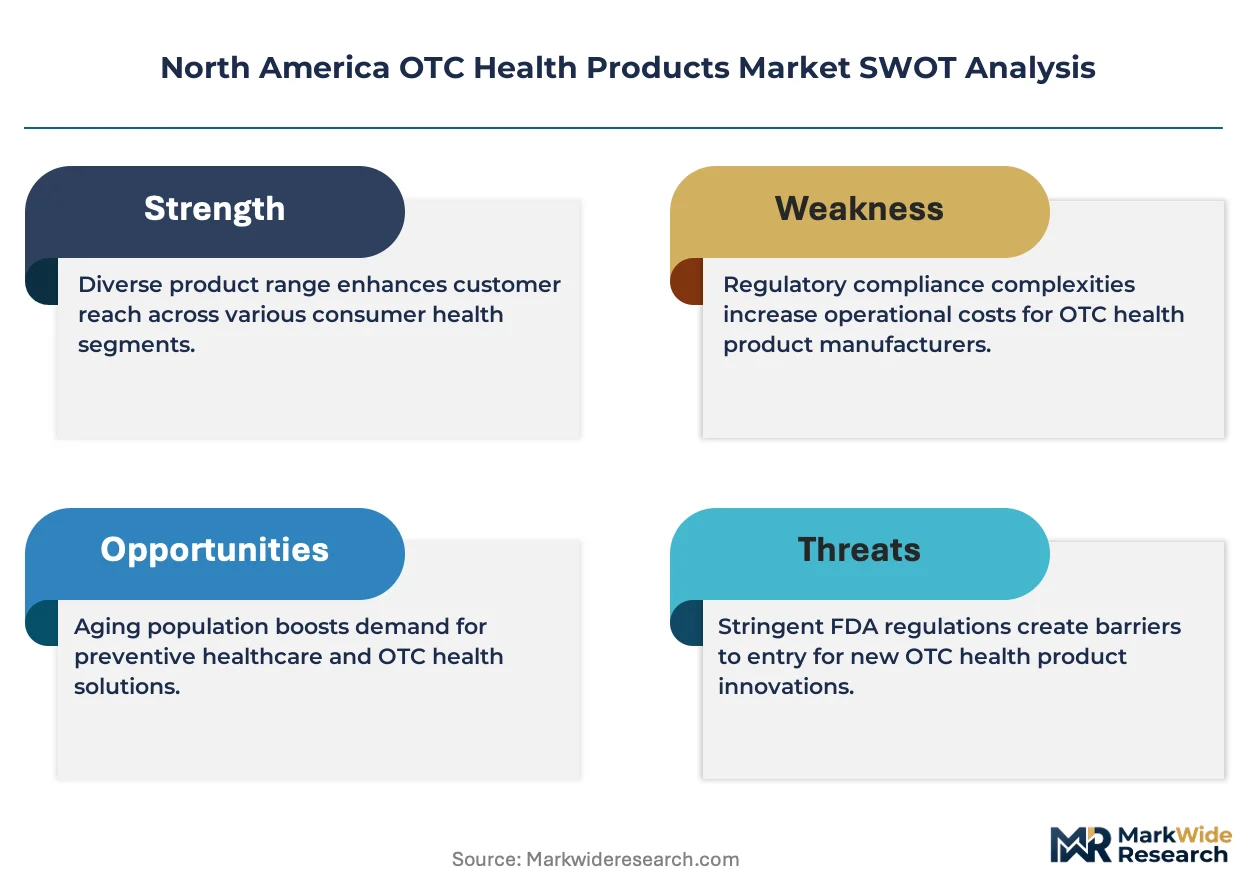
FDA monograph system oversight and Health Canada's Natural and Non-prescription Health Products Directorate jointly define permissible ingredients, labeling claims, and good manufacturing practice requirements across the United States and Canada. These frameworks elevate compliance costs for new entrants while protecting incumbent positions through established monograph eligibility. Stakeholders must monitor pending monograph updates and state-level pharmacy scope-of-practice expansions that could reshape channel control and advisory service monetization.
Market Dynamics
Pharmacist-directed self-care advisory services are capturing margin that previously accrued to pure product sales, reconfiguring how OTC health products generate revenue across pharmacy retail chains and direct-to-consumer digital platforms.
Growth Catalysts
- FDA Monograph Reforms:Streamlined approval pathways for eligible active ingredients reduce time-to-market for reformulated analgesics and acid-reduction products, compressing regulatory friction for established manufacturers.
- Self-Medication Among Aging Adults:Demographic concentration in the United States and Canada drives sustained demand for digestive health and respiratory portfolios that address chronic condition management without clinician supervision.
- NHPID Digitization:Health Canada's Natural and Non-prescription Health Products Directorate modernization accelerates label claim approvals and good manufacturing practice certifications for cross-border product launches.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient sourcing for ibuprofen, acetaminophen, and pseudoephedrine concentrates in Asian manufacturing clusters, exposing formulators to geopolitical disruption and shipping volatility.
- Monograph Compliance Burden:FDA's ongoing updates to over-the-counter drug monographs require continuous label revisions and stability testing, elevating fixed costs for multi-SKU portfolios.
- Clinical Substitutes:Telehealth platforms and retail clinic expansion offer low-cost prescription alternatives for conditions previously managed through self-selection, compressing addressable volume in cough-cold and analgesic segments.
Strategic Opportunities
- Pharmacist Service Monetization:Scope-of-practice expansions in California, Florida, and Ontario enable medication therapy management billing, creating new revenue streams attached to OTC recommendation protocols.
- Probiotic-Pharma Convergence:Microbiome-targeted formulations meeting drug-grade stability specifications open premium positioning in digestive health previously occupied by prescription GI therapies.
- Direct-to-Consumer Subscription Models:Digital-native platforms bypassing pharmacy shelf fees capture recurring revenue for chronic-condition categories including allergy and acid-reduction regimens.
Industry Challenges
- Formulation Talent Scarcity:Shortage of pharmaceutical scientists skilled in immediate-release dissolution optimization and probiotic viability preservation constrains innovation pipeline velocity.
- Legacy System Integration:ERP harmonization between acquired brand portfolios and parent company manufacturing execution systems delays cost synergy realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America OTC Health Products Market |
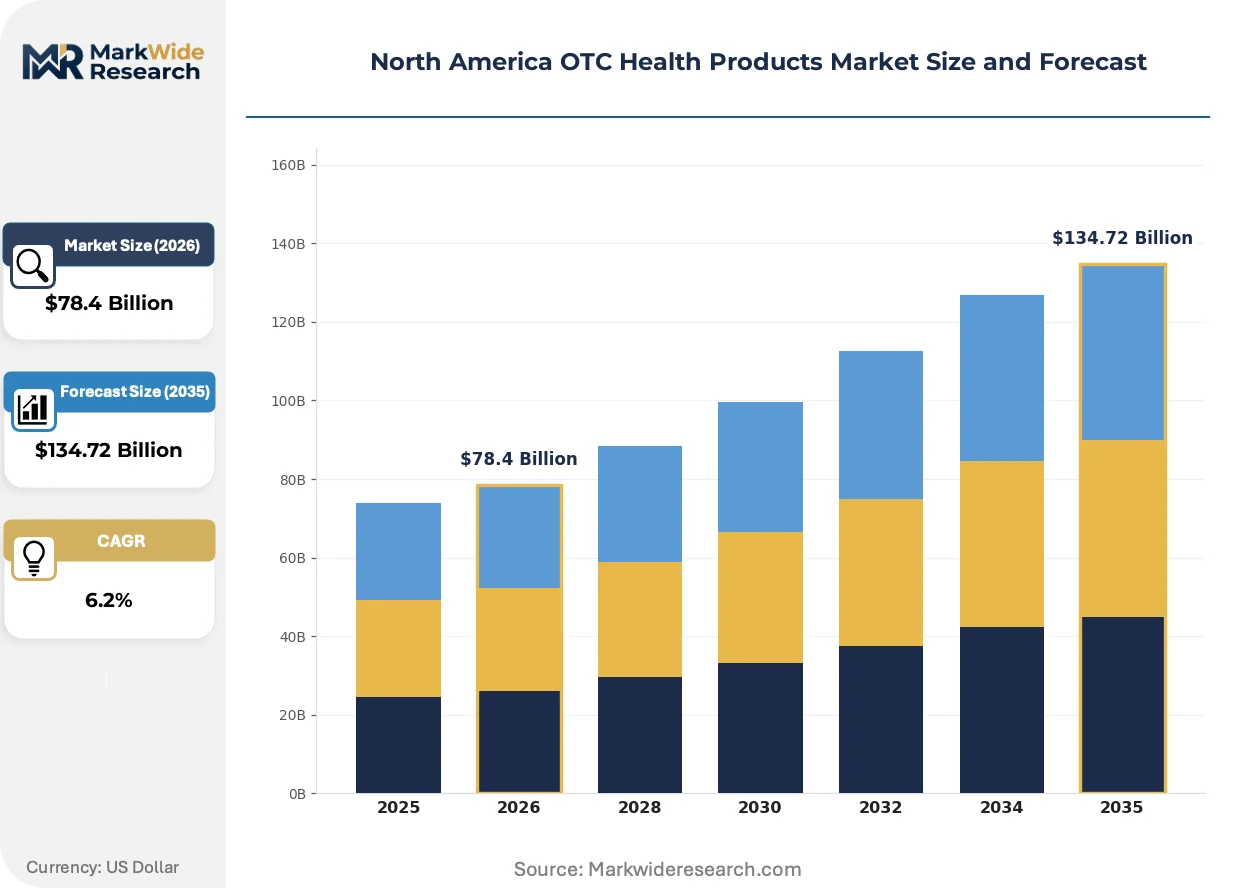
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Cold & Cough, Digestive Health, Allergy End User: Adults, Children, Seniors, Pregnant Women Distribution Channel: Retail Pharmacies, E-commerce, Convenience Stores, Supermarkets Packaging Type: Blister Packs, Bottles, Sachets, Tubes |
| Companies Covered | Johnson & Johnson, Bayer, GlaxoSmithKline, Pfizer, Sanofi, Novartis, Kenvue, Haleon, Herbalife Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America OTC Health Products Market Strategic Shifts & Innovations
Dissolution-engineered immediate-release formats and microbiome-targeted delivery systems are compressing development cycles while regulatory digitization and channel fragmentation simultaneously reshape competitive access.
Dual-layer tablet technology combining rapid-release analgesic cores with gastro-protective buffering is rendering obsolete single-layer immediate-release formats that carried ulcer risk warnings. Pharmacy chains in the United States are accelerating shelf resets toward these differentiated formats. The structural consequence is premium pricing capture in mature analgesic categories previously commoditized by private-label substitution.
Health Canada's NHPID digitization initiative and FDA's proposed OTC monograph administrative order process are compressing approval timelines for reformulated probiotics and acid-reduction products. Manufacturers with established quality management systems gain first-mover access to revised label claims. Canadian digestive health portfolios and US respiratory combinations are repositioning formulation investments around these regulatory pathways.
Subscription-based replenishment for chronic-condition categories is displacing episodic pharmacy purchase patterns for allergy, sleep, and digestive regimens. Direct-to-consumer platforms capture patient adherence data that informs formulation refinement. This behavioral shift concentrates in United States metropolitan markets where pharmacy deserts and convenience preferences intersect.
North America OTC Health Products Market Segmentation
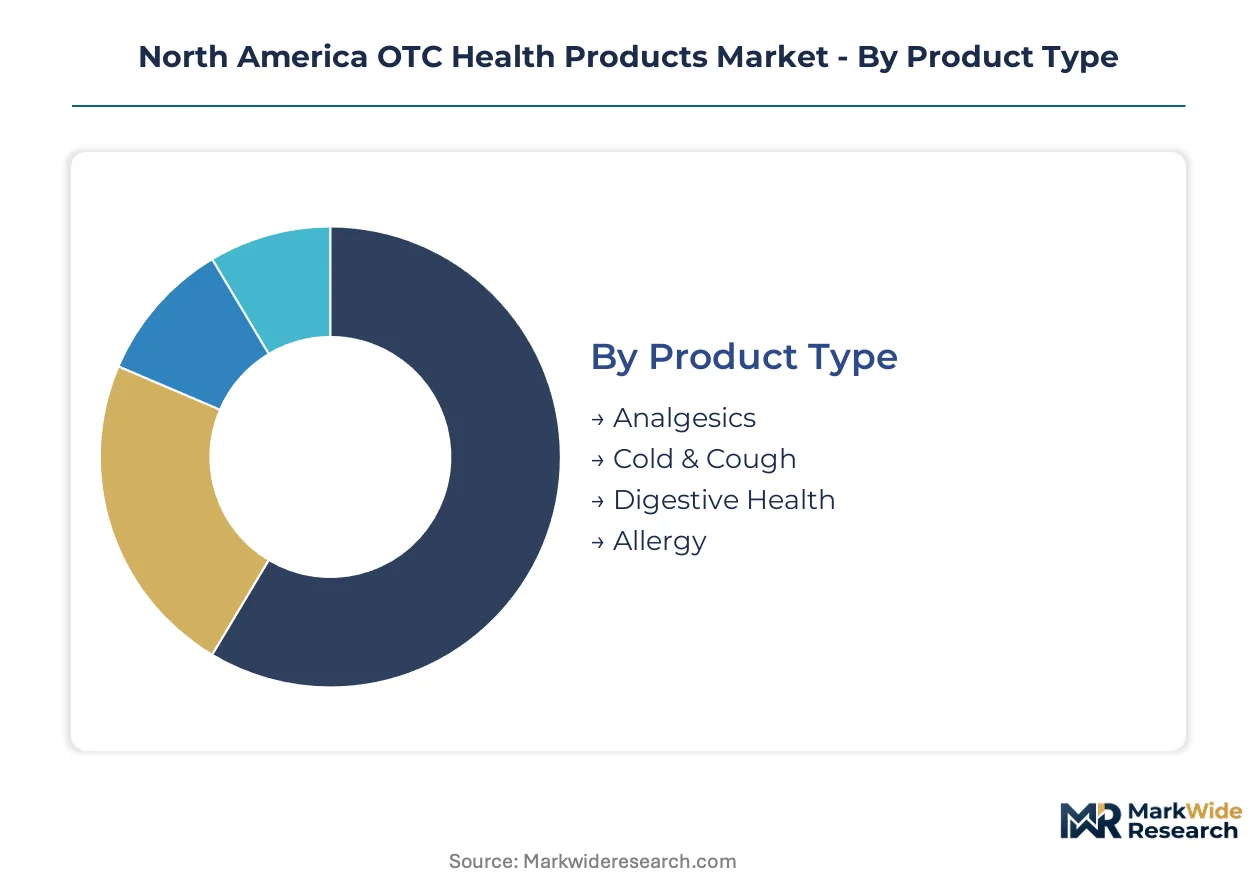
Segmentation in North American OTC health products reveals how formulation specifications, patient demographics, and channel access intersect to determine margin capture. Each dimension carries distinct regulatory requirements and pricing power dynamics that shape manufacturer portfolio strategy.
Product Type:
Cost tier differentiation across therapeutic categories separates premium-positioned digestive innovations from commoditized analgesic volumes.
- Analgesics:Ibuprofen and acetaminophen formulations dominate shelf space with immediate-release dissolution profiles targeting minutes for symptom onset. United States pharmacy chains concentrate volume here, though private-label substitution compresses branded margins and forces dual-layer gastro-protective differentiation.
- Digestive Health:Probiotic and acid-reduction portfolios command the highest price premiums through drug-grade stability specifications and microbiome-targeted delivery systems. Canadian regulatory pathways via NHPID digitization accelerate label claim approvals for these formulations, concentrating investment in cross-border launches.
- Cold & Cough:Pseudoephedrine and dextromethorphan combinations face prescription-alternative pressure from retail clinic expansion.
- Allergy:Antihistamine regimens increasingly migrate to direct-to-consumer subscription models in United States metropolitan markets.
Analgesics commands the established base. The steepest expansion runs through Digestive Health.
End User:
Application-specific dosing and safety profiles segment demand across life-stage requirements with distinct formulation tolerances.
- Seniors:Polypharmacy-aware formulations with reduced drug-interaction risk and pharmacist-directed medication therapy management dominate this segment. United States scope-of-practice expansions in California and Florida enable billing for OTC recommendation protocols attached to chronic condition management.
- Adults:Self-directed purchase patterns concentrate in episodic symptom relief categories with convenience-driven channel selection.
- Children:Liquid suspensions and weight-calibrated dosing requirements elevate manufacturing complexity and stability testing burdens.
- Pregnant Women:Category III safety classifications restrict permissible active ingredients to limited analgesic and antacid options.
Adults generates the highest absolute volume. Seniors delivers the fastest margin expansion through service attachment.
Distribution Channel:
Customer type and purchase occasion determine channel control, with trust transfer mechanisms varying across pharmacy consultation versus digital convenience.
- Retail Pharmacies:Pharmacist-directed self-care advisory services capture margin previously accruing to pure product sales through medication therapy management billing. United States chains leverage front-end merchandising dominance in digestive and respiratory portfolios.
- E-commerce:Direct-to-consumer platforms bypass shelf fees and capture recurring subscription revenue for chronic-condition categories including allergy and acid-reduction regimens.
- Supermarkets:Impulse-driven analgesic and cough-cold purchases compete with private-label substitution pressure.
- Convenience Stores:Travel-size and single-dose formats target immediate-need scenarios with premium unit pricing.
Retail Pharmacies holds the majority of first-contact purchases. E-commerce posts the steepest expansion trajectory.
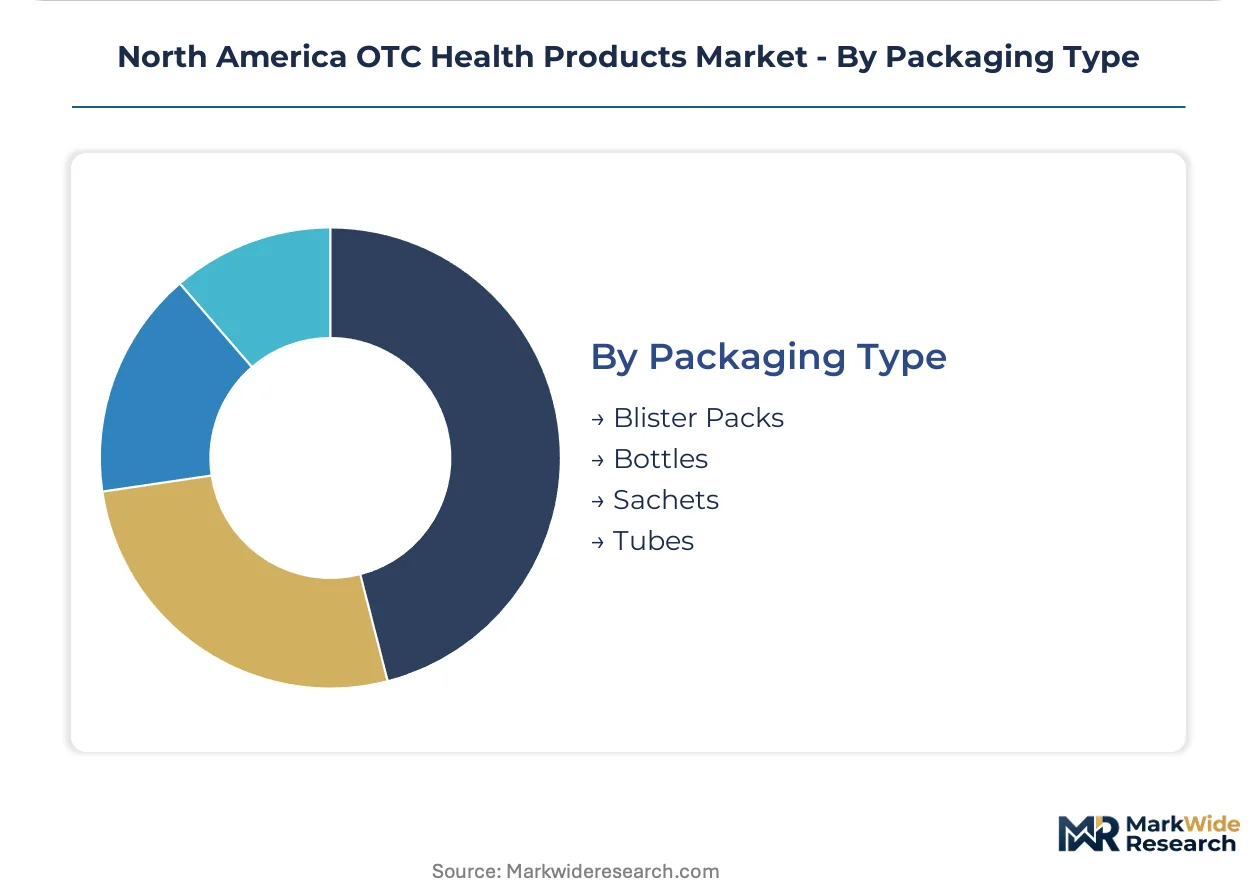
Packaging Type:
Supply concentration in primary packaging materials and secondary conversion capacity shapes cost structures across format selection.
- Blister Packs:Unit-dose compliance packaging for chronic regimens and travel formats commands material premiums through aluminum-PVC lamination and child-resistant specifications. United States senior-targeted portfolios increasingly specify calendarized blister configurations.
- Bottles:High-volume analgesic and cough syrup containers concentrate blow-molding capacity with desiccant integration for moisture-sensitive probiotics.
- Sachets:Powder and granule formats for on-the-go digestive health dosing.
- Tubes:Topical analgesic and dermatological applications with crimp-seal integrity requirements.
Bottles anchors volume production. Blister Packs gains share fastest through adherence programming and premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across North American jurisdictions, with United States pharmacy chains driving volume through promotional discounting while Canadian regulatory premium positioning sustains margin resilience.
United States
Pharmacist-directed self-care advisory services and medication therapy management billing in California and Florida reshape revenue capture toward service attachment. FDA monograph reforms streamline approval pathways for reformulated analgesics and acid-reduction products. Manufacturing clusters in New Jersey and Pennsylvania concentrate on dual-layer gastro-protective tablet production for national pharmacy chain distribution.
Canada
Cross-border digestive health demand and probiotic stability specifications command premium positioning through NHPID digitization. Health Canada's Natural and Non-prescription Health Products Directorate accelerates label claim approvals for microbiome-targeted formulations. Toronto and Montreal anchor formulation development for export-ready portfolios targeting United States metropolitan markets.
Mexico
Private-label analgesic manufacturing and regional pharmacy chain consolidation expand accessible price-tier offerings. COFEPRIS regulatory alignment with FDA standards enables contract manufacturing for United States brands. Industrial corridors in Mexico City Metro and Guadalajara concentrate on high-volume immediate-release tablet production for North American distribution networks.
North America OTC Health Products Market Key Industry Players
Diversified health conglomerates and specialized consumer health spin-offs split the market between heritage brand equity and focused portfolio agility. The structure tilts toward consolidation through serial divestiture and acquisition activity. Heritage pharmaceutical manufacturers and consumer health pure-plays represent the dominant archetypes. Competitive moves concentrate on portfolio rationalization and direct-to-consumer platform development.
Within the heritage conglomerate tier, Johnson & Johnson and Bayer exemplify multi-category shelf dominance through established analgesic and digestive health positioning. Haleon occupies a position as the consumer health spin-off archetype, anchoring pharmacy relationships through respiratory and digestive portfolios. These three entities represent distinct strategic postures: diversified manufacturing scale, therapeutic specialization, and channel-focused portfolio concentration.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Bayer |
| GlaxoSmithKline |
| Pfizer |
| Sanofi |
| Novartis |
| Kenvue |
| Haleon |
| Herbalife Nutrition |
| Others |
Cost & Logistics Intelligence
New Jersey and Pennsylvania manufacturing clusters concentrate dual-layer gastro-protective tablet capacity for national pharmacy chain distribution, translating upstream formulation specialization into downstream pricing power for differentiated analgesic formats.
Pricing Analysis
Aftermarket pharmacist advisory services drive lifetime value beyond pure product margins. Three-tier pricing structure across premium, standard, and economy levels separates drug-grade probiotic formulations from private-label analgesic commodities. Cost compression in mature cough-cold segments is intensifying because telehealth substitutes erode episodic purchase volume. Pharmacy chains exhibit highest price sensitivity in commoditized immediate-release categories, while direct-to-consumer platforms capture least-sensitive adherence-based subscription revenue.
Supply Chain Analysis
Tariff exposure between China and the United States dominates API sourcing risk for ibuprofen, acetaminophen, and pseudoephedrine feedstocks. Active pharmaceutical ingredient supply draws from India, China, and selected European specialist manufacturers. Raw material dependencies center on acetaminophen precursors, probiotic strain cultures, and gastro-protective polymer coatings. Single-source vulnerability concentrates in pseudoephedrine alkaloid extraction. Distribution runs through pharmacy retail chains controlling front-end merchandising, with e-commerce platforms capturing fastest-expanding last-mile access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmacist-directed self-care advisory services constitute a platform-economics inflection, with medication therapy management billing interoperability between United States and Canadian regulatory frameworks reshaping margin capture architecture.
For Market Incumbents: Harden pharmacy relationship exclusivity through medication therapy management billing certification in California and Florida scope-of-practice expansions. Deepen vertical integration into probiotic strain cultivation and stability testing to defend against microbiome-targeted entrants. Anchor shelf positioning through dual-layer gastro-protective tablet differentiation that private-label substitutes cannot replicate.
For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure for allergy and acid-reduction chronic regimens in United States metropolitan pharmacy deserts. Target digestive health probiotic segments where drug-grade stability specifications create certification barriers for legacy manufacturers. Deploy adherence-data capture platforms that inform formulation refinement and secure recurring revenue attachment.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors consumer health pure-plays with pharmacy channel concentration and regulatory digitization readiness over diversified pharmaceutical conglomerates. Long-term viability rests on NHPID-aligned quality management systems enabling cross-border label claim agility. Acquisition target archetypes include microbiome formulation specialists and medication therapy management billing platforms. Watch FDA monograph administrative order implementation velocity as inflection indicator for reformulation investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacist Service Monetization | Medication therapy management billing in California and Florida scope-of-practice expansions captures advisory revenue previously lost to product margins. |
| Probiotic-Pharma Convergence | Drug-grade stability specifications for microbiome-targeted formulations open premium positioning previously occupied by prescription GI therapies. |
| Direct-to-Consumer Subscription Launch | Digital-native platforms bypass pharmacy shelf fees and capture recurring adherence data for chronic-condition regimen refinement. |
| NHPID Regulatory Alignment | Health Canada digitization accelerates cross-border label claim approvals for digestive health portfolios targeting United States metropolitan markets. |
| Dual-Layer Formulation Differentiation | Gastro-protective buffering technology renders obsolete single-layer immediate-release formats vulnerable to private-label substitution. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with pharmacy chain formulary directors, medication therapy management billing specialists, FDA regulatory affairs leads, and probiotic formulation scientists; and secondary validation through FDA monograph filings, Health Canada NHPID submission databases, pharmacy retail audit data, and United States scope-of-practice legislative tracking. Bottom-up SKU-level volume builds and top-down therapeutic category spend estimates underwent iterative triangulation.
Forecast inputs spanned product type, end-user life stage, distribution channel control, and packaging format specifications across the analysis window. Segmentation dimensions modeled include therapeutic category concentration, patient polypharmacy risk profile, pharmacist scope-of-practice jurisdiction, and digital platform penetration. CAGRs derived from regression against demographic aging trajectories and regulatory digitization implementation curves, with cross-border launch velocity and subscription adoption rates as industry-specific modifiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by telehealth platforms or microbiome-targeted entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Native Collagen Market
Nutraceuticals
Pet Nutraceuticals Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
US Collagen Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
Coenzyme Q10 Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Eye Health Ingredients Market
Nutraceuticals
Magtein Market
Nutraceuticals
Nattokinase Market
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
Cissus Quadrangularis Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
LAMEA Digestive Enzymes Market
Nutraceuticals
Phosphatidylserine Market