
 Chondroitin Sulfate Market | 2026-2036
Chondroitin Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Chondroitin Sulfate Market Intelligence
Skilled extraction technicians capable of pharmaceutical-grade purification is redrawing competitive boundaries in chondroitin sulfate production. TSI Group Ltd. leverages vertically integrated bovine sourcing to sustain margin control across European nutraceutical channels. Bioiberica S.A.U. anchors its position through proprietary enzymatic processing that differentiates output purity benchmarks. Seikagaku Corporation specializes in hyaluronan-chondroitin co-production systems that dominate Japanese pharmaceutical supply.
Chondroitin sulfate is a sulfated glycosaminoglycan composed of alternating N-acetylgalactosamine and glucuronic acid units, typically extracted from bovine trachea or avian sternum cartilage through enzymatic or alkaline hydrolysis processes yielding molecular weights between 10,000 and 50,000 Daltons. Pharmaceutical grade material commands premium positioning due to injectable and prescription oral applications requiring USP-NF or EP monograph compliance, while nutraceutical grade experiences volume expansion through direct-to-consumer joint health formulations. Osteoarthritis management applications lead value generation as prescription and medical-food channels maintain stringent certification requirements, whereas skin care formulations represent an emerging absorption pathway for cosmetic-grade variants.
The US FDA cGMP framework for dietary supplements and the European Pharmacopoeia monograph for chondroitin sodium sulfate collectively elevate analytical and documentation burdens on raw material suppliers seeking market access. China's NMPA pharmaceutical ingredient registration requirements create additional compliance layers for domestic producers targeting export qualification. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and Chinese pharmacopeia standards as divergence in sulfate content specifications could fragment sourcing strategies.
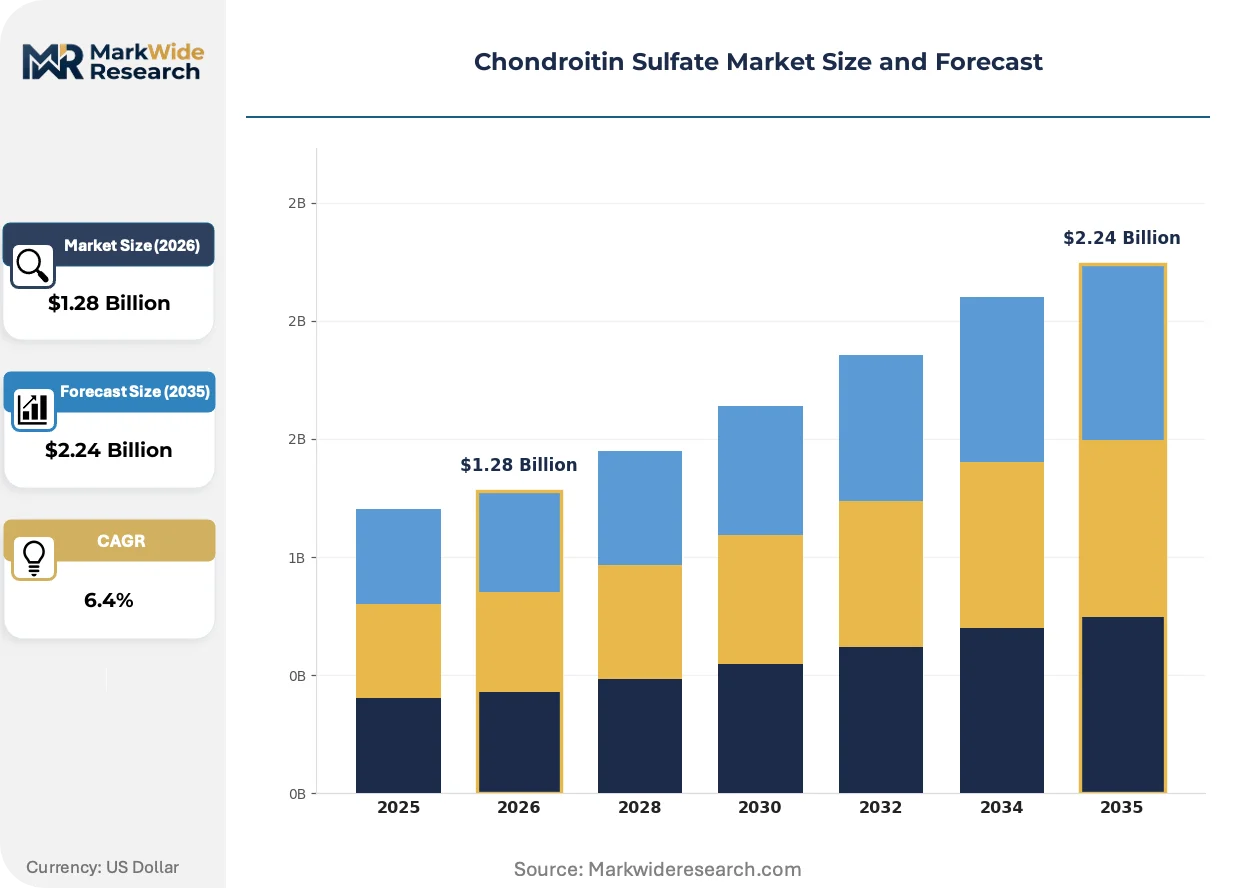
Market Dynamics
Pharmaceutical-grade extraction capacity scarcity is redrawing competitive boundaries as cGMP certification requirements tighten raw material qualification windows. The divergence between nutraceutical volume demand and prescription-grade supply reliability is forcing producers to choose between margin protection and market expansion.
Growth Catalysts
- Osteoarthritis Therapeutic Demand:Aging demographics in Germany and Japan are expanding prescription chondroitin sulfate volumes for joint disease management, with medical-food channels adding incremental offtake.
- FDA cGMP Enforcement:Elevated quality barriers for imported dietary supplement raw materials are compressing the qualified supplier base and rewarding domestic US producers with certification infrastructure.
- Enzymatic Hydrolysis Advancement:Proprietary processing technologies are enabling tighter molecular weight control, differentiating output for injectable applications against traditional alkaline extraction methods.
Market Restraints
- Bovine Trachea Supply Concentration:Raw material sourcing clusters in specific cattle-producing regions, exposing processors to livestock disease quarantine protocols and rendering availability volatility.
- EP-USP Monograph Divergence:Differing sulfate content specifications between European Pharmacopoeia and United States Pharmacopeia standards are fragmenting batch qualification requirements for multinational suppliers.
- Glucosamine Substitution Pressure:Single-ingredient joint health formulations and combination products with alternative glycosaminoglycans are capturing shelf space in mass-market retail channels.
Strategic Opportunities
- Cosmetic-Grade Absorption Pathways:Transdermal delivery formulations for skin hydration applications represent an emerging volume channel with less stringent certification burdens than pharmaceutical segments.
- NMPA Pharmaceutical Ingredient Registration:China's domestic producers scaling export-qualification capacity can capture premium positioning as international buyers seek qualified alternative supply sources.
- Hyaluronan-Chondroitin Co-Production:Integrated manufacturing systems leveraging shared cartilage feedstock and purification infrastructure are reducing unit economics for dual-output facilities.
Industry Challenges
- Pharmaceutical-Grade Purification Expertise Gap:Skilled extraction technicians capable of USP-NF compliance are concentrated among legacy producers, constraining new entrant scale-up timelines.
- Dual Pharmacopeia Harmonization Delays:Protracted alignment processes between USP, EP, and Chinese pharmacopeia standards are forcing parallel batch testing and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chondroitin Sulfate Market |
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Cosmetic Grade, Nutraceutical Grade Application: Osteoarthritis Management, Joint Health Supplements, Skin Care Formulations, Wound Healing Products End User: Pharmaceutical Manufacturers, Dietary Supplement Producers, Cosmetic Companies, Research Laboratories Form: Powder, Capsules, Tablets, Liquid Concentrates, Topical Creams |
| Companies Covered | TSI Group Ltd., Bioiberica S.A.U., Seikagaku Corporation, Qingdao WanTuMing Biological Products, Hebei SanXin Industrial Group, Synutra Ingredients, Shandong Runxin Biotechnology, Sioux Pharm, Sino Siam Biotechnique Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chondroitin Sulfate Market Strategic Shifts & Innovations
Enzymatic processing architectures are displacing legacy alkaline hydrolysis as the dominant extraction paradigm, compressing capital recovery timelines while elevating purity benchmarks. This technological rotation is enabling new competitive entrants to bypass historical scale advantages.
Membrane filtration and chromatographic purification is supplanting conventional precipitation methods in pharmaceutical-grade production lines. European nutraceutical contract manufacturers are adopting these systems to secure FDA audit readiness, compressing the cost gap between premium and standard grade outputs while enabling real-time molecular weight monitoring that alkaline processes cannot replicate.
REACH registration requirements for imported cartilage-derived substances are tightening substance documentation obligations for EU market access. The European Chemicals Agency's evolving endpoint specifications are forcing non-European producers to establish analytical partnerships with European contract laboratories, with prescription oral applications facing the steepest compliance cost escalation.
Direct-to-consumer subscription models are disrupting traditional wholesale distribution for nutraceutical-grade formulations. US-based telehealth platforms and specialized joint health direct marketers are capturing patient acquisition data that retail pharmacy channels cannot access, with this channel rotation most visible in the American market where healthcare cost transparency pressures accelerate self-directed purchasing behavior.
Chondroitin Sulfate Market Segmentation
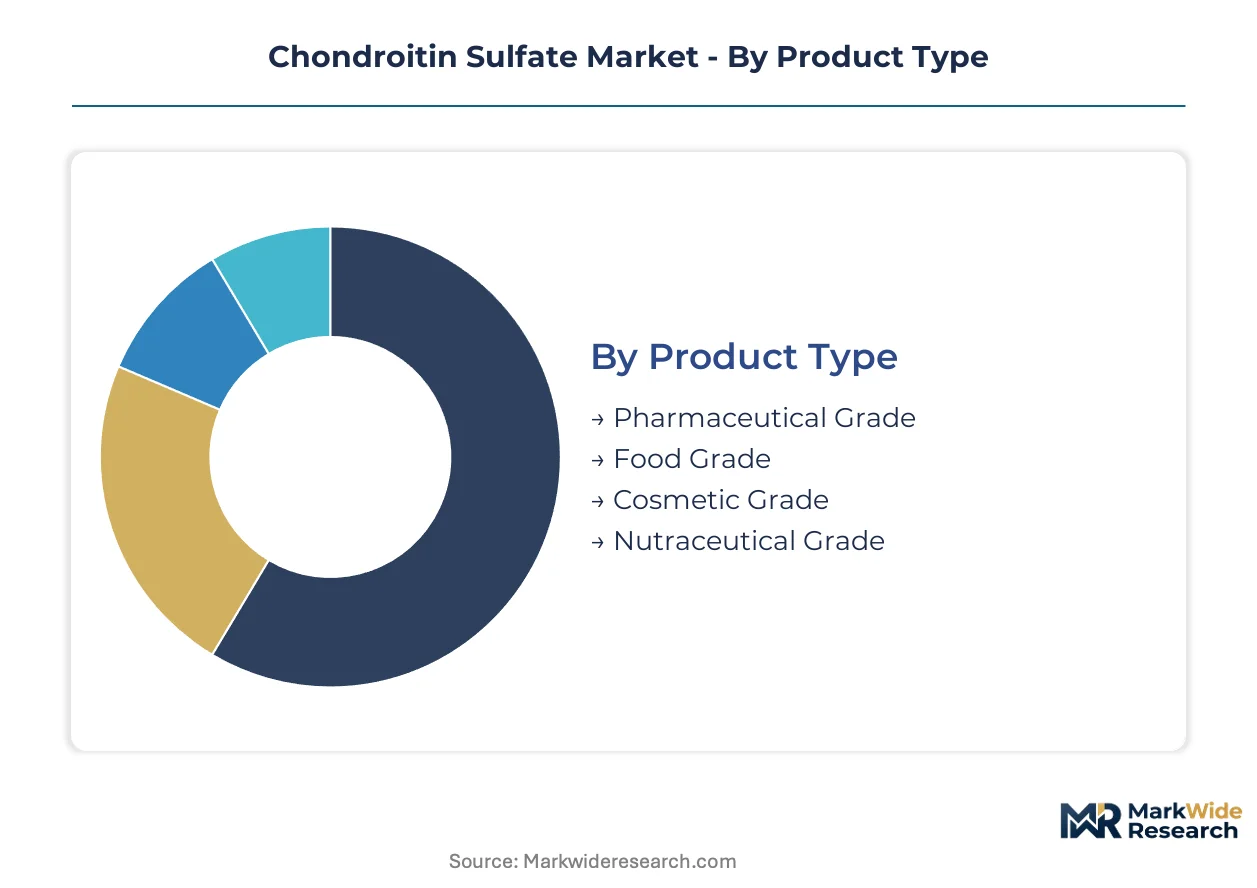
Segmentation in chondroitin sulfate production determines access to margin pools that vary dramatically by certification burden and end-use qualification. Pharmaceutical-grade pathways command substantial premiums over nutraceutical volumes, while cosmetic applications offer lower barriers with compressed returns.
Product Type:
Margin concentration tracks directly to pharmacopeial compliance intensity, with injectable-grade specifications creating the steepest entry barriers.
- Pharmaceutical Grade:USP-NF or EP monograph-compliant material with sulfate content between 90-105% and molecular weight specifications between 10,000-50,000 Daltons. Demand concentrates in German and Japanese prescription markets for osteoarthritis injectables, where FDA and PMDA audits restrict qualified supplier pools. The dominant share belongs to Pharmaceutical Grade, while Cosmetic Grade is closing the gap fastest.
- Nutraceutical Grade:Dietary supplement-grade material meeting cGMP documentation standards without full pharmacopeial certification. US direct-to-consumer channels and European pharmacy retail drive volume, with FDA enforcement actions elevating documentation burdens on imported raw material.
- Food Grade:Material meeting food safety specifications for functional food applications. Japanese and South Korean markets absorb volumes through medical-food regulatory pathways.
- Cosmetic Grade:Lower-purity material for topical applications with reduced sulfation requirements. Transdermal delivery research in French and Swiss cosmetic laboratories is expanding absorption studies beyond traditional joint health positioning.
Pharmaceutical Grade captures the dominant margin pool, while Cosmetic Grade climbs fastest as formulation science advances.
Application:
End-use diversification is fragmenting demand across prescription, wellness, and aesthetic channels with diverging growth velocities.
- Osteoarthritis Management:Prescription oral and injectable therapeutics requiring full pharmacopeial compliance. German statutory health insurance reimbursement and Japanese medical fee schedules sustain volume, with medical-food channels adding incremental offtake in US functional medicine practices.
- Joint Health Supplements:Dietary supplement formulations combining chondroitin with glucosamine or hyaluronic acid. US telehealth subscription models and European pharmacy private labels are displacing traditional wholesale distribution.
- Skin Care Formulations:Cosmetic applications leveraging glycosaminoglycan hydration properties. South Korean and Swiss cosmetic manufacturers are advancing transdermal delivery research.
- Wound Healing Products:Specialized medical devices and regenerative medicine applications. German and US wound care specialists are evaluating chondroitin-hyaluronan matrices for chronic wound management.
Osteoarthritis Management retains the largest revenue footprint, though Skin Care Formulations is gaining share fastest through cosmetic channel expansion.
End User:
Customer concentration patterns reflect vertical integration incentives and raw material security priorities across value chain positions.
- Pharmaceutical Manufacturers:Integrated producers and contract manufacturers requiring batch-level pharmacopeial documentation. Japanese and German prescription drug producers dominate procurement with long-term supply agreements.
- Dietary Supplement Producers:Brand owners and contract manufacturers serving US and European retail and direct-to-consumer channels. FDA cGMP enforcement is compressing the qualified supplier base for imported raw material.
- Cosmetic Companies:Formulators seeking glycosaminoglycan inputs for hydration and anti-aging claims. South Korean and French cosmetic houses are expanding ingredient sourcing teams.
- Research Laboratories:Academic and commercial R&D facilities evaluating novel therapeutic applications. US and Swiss regenerative medicine institutes are advancing cartilage tissue engineering protocols.
Pharmaceutical Manufacturers command the dominant procurement volume, while Cosmetic Companies are expanding purchasing fastest.
Form:
Delivery format selection tracks to end-use channel requirements and bioavailability optimization research.
- Powder:Bulk active pharmaceutical ingredient for further processing and compounding. European and Chinese manufacturers dominate supply for downstream formulation.
- Capsules:Single-ingredient and combination products for dietary supplement retail. US direct-to-consumer brands are capturing patient acquisition data through subscription models.
- Tablets:Compressed formulations for pharmacy and mass-market retail distribution. German and US private label producers are consolidating procurement.
- Liquid Concentrates:Medical-food and functional beverage applications. Japanese beverage manufacturers are evaluating joint health positioning in aging-consumer products.
- Topical Creams:Transdermal delivery systems for localized joint discomfort and cosmetic hydration. French and Swiss cosmetic formulators are advancing permeation enhancement research.
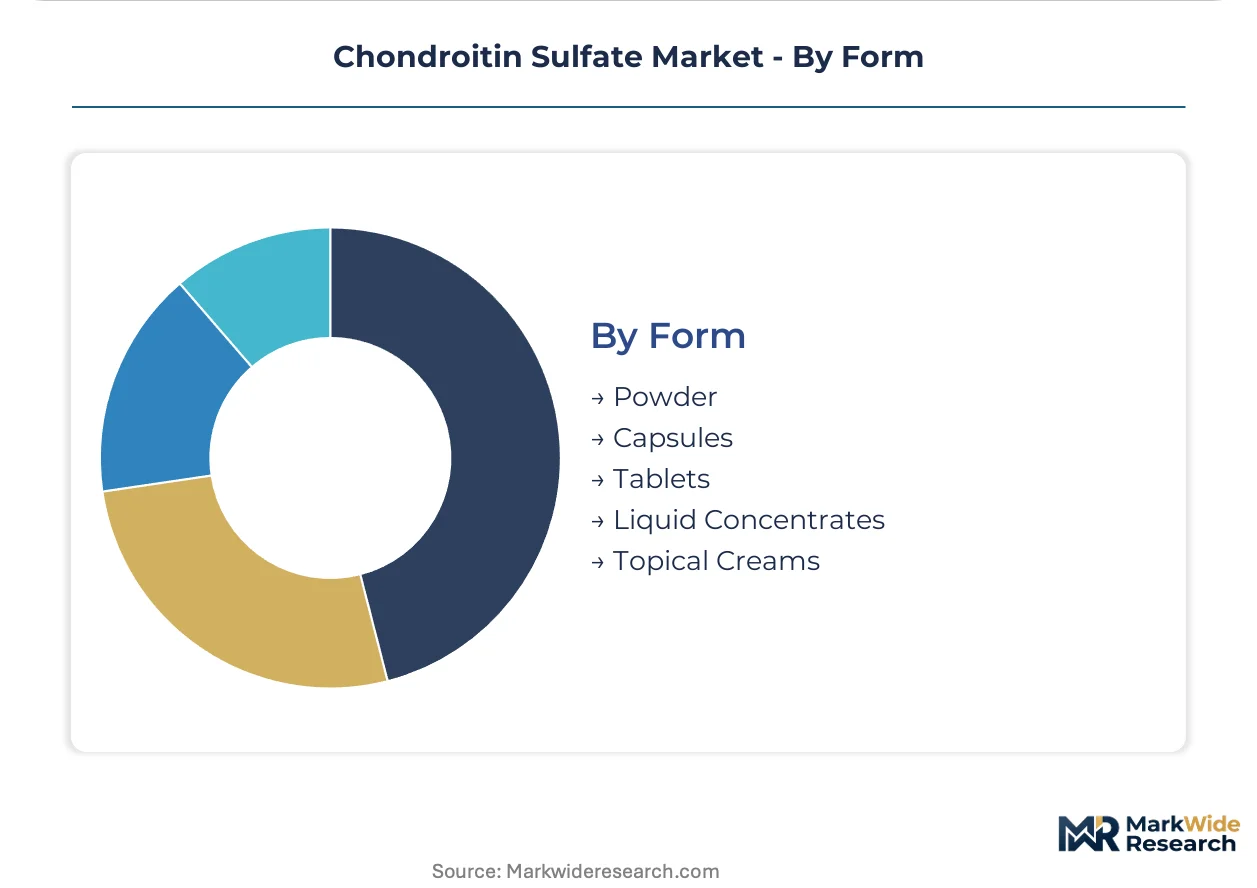
Powder maintains the foundational position in supply chains, while Topical Creams is expanding fastest through cosmetic and topical therapeutic channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cGMP enforcement in the United States has elevated quality barriers for imported chondroitin sulfate raw materials, compressing the qualified supplier base and rewarding domestic producers with certification infrastructure. Demand concentration varies across major pharmaceutical and nutraceutical manufacturing clusters, with regulatory divergence between pharmacopeial standards fragmenting batch qualification requirements.
United States
Prescription osteoarthritis therapeutics and direct-to-consumer subscription models drive US demand, with telehealth platforms capturing patient acquisition data that retail pharmacy channels cannot access. FDA dietary supplement cGMP enforcement actions have eliminated marginal importers, consolidating procurement around domestic producers with analytical documentation capabilities. New Jersey and California host the dominant pharmaceutical formulation clusters, where medical-food channels are adding incremental chondroitin sulfate offtake.
Germany
German statutory health insurance reimbursement sustains prescription chondroitin sulfate volumes for osteoarthritis injectables, with medical-food regulations enabling functional positioning in aging-consumer products. The European Pharmacopoeia monograph for chondroitin sodium sulfate governs market access, with REACH registration requirements tightening substance documentation obligations for imported cartilage-derived substances. Bavaria and North Rhine-Westphalia concentrate pharmaceutical-grade extraction capacity, where contract manufacturers are adopting membrane filtration systems to secure FDA audit readiness.
China
Domestic producers are scaling pharmaceutical-grade extraction capacity to capture premium positioning as international buyers seek qualified alternative supply sources. NMPA pharmaceutical ingredient registration requirements create additional compliance layers for producers targeting export qualification, with dual carbon goals pressuring energy-intensive alkaline hydrolysis operations. Shandong and Zhejiang provinces dominate bovine trachea sourcing and enzymatic processing infrastructure, where backward integration into captive cattle rendering is reducing raw material volatility.
Japan
PMDA audits restrict qualified supplier pools for prescription chondroitin sulfate, with medical fee schedules sustaining volume in joint disease management applications. METI industrial policy supports hyaluronan-chondroitin co-production systems that leverage shared cartilage feedstock and purification infrastructure. The Kanto region around Tokyo anchors pharmaceutical manufacturing, where Seikagaku Corporation's integrated facilities dominate domestic supply.
Switzerland
Swissmedic certification requirements and proximity to French cosmetic formulators are expanding transdermal delivery research for skin hydration applications. The country's precision chemical processing heritage supports pharmaceutical-grade purification expertise that legacy producers elsewhere struggle to replicate. Basel and Geneva host specialized glycosaminoglycan research institutes advancing cartilage tissue engineering protocols.
Chondroitin Sulfate Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in chondroitin sulfate production, with vertical control over bovine sourcing and enzymatic processing creating durable margin advantages. The upper tier commands pharmaceutical-grade certification infrastructure that new entrants cannot replicate within relevant timelines. Three archetypes dominate: vertically integrated cattle processors with captive rendering operations, specialized enzymatic technology licensors, and regional contract manufacturers serving nutraceutical private labels. Capacity expansion and pharmacopeial harmonization partnerships represent the dominant competitive moves, with producers seeking dual USP-EP qualification to avoid parallel batch testing burdens.
Within the integrated leader tier, TSI Group Ltd. and Bioiberica S.A.U. exemplify the archetype of producers combining upstream cattle sourcing with proprietary extraction capabilities. Seikagaku Corporation occupies a distinct position through its hyaluronan-chondroitin co-production specialization. Among Chinese producers, Qingdao WanTuMing Biological Products and Hebei SanXin Industrial Group represent the scale-driven segment scaling pharmaceutical-grade capacity for export qualification. Sioux Pharm anchors North American supply as a domestic producer benefiting from FDA cGMP enforcement compression of the import base.
| Leading Market Players |
|---|
| TSI Group Ltd. |
| Bioiberica S.A.U. |
| Seikagaku Corporation |
| Qingdao WanTuMing Biological Products |
| Hebei SanXin Industrial Group |
| Synutra Ingredients |
| Shandong Runxin Biotechnology |
| Sioux Pharm |
| Sino Siam Biotechnique Company Ltd. |
| Others |
Cost & Logistics Intelligence
Enzymatic hydrolysis adoption displacing alkaline extraction methods simultaneously concentrates processing capacity in Shandong and Zhejiang provinces while compressing capital recovery timelines for pharmaceutical-grade certification investments. This substitution dynamic fragments legacy pricing benchmarks as new entrants bypass historical scale advantages through membrane filtration architectures.
Pricing Analysis
Chinese-origin pharmaceutical-grade material commands a 15-25% discount against European-sourced equivalents in German procurement contracts. Three-tier pricing structure across pharmaceutical, nutraceutical, and cosmetic grades tracks sulfate content certification intensity, with USP-NF compliance creating the steepest premium tier. Cost compression in nutraceutical channels is intensifying because FDA cGMP enforcement has eliminated marginal importers. Dietary supplement brand owners exhibit highest price sensitivity, while Japanese prescription drug producers demonstrate lowest elasticity due to PMDA audit requirements.
Supply Chain Analysis
Inventory cycles for bovine trachea feedstock extend 90-120 days due to livestock rendering seasonality and quarantine protocol variability. Supply concentrates in China, Spain, and the United States, with Shandong province anchoring enzymatic processing capacity and Catalonia retaining legacy alkaline extraction infrastructure. Raw material sourcing draws from cattle-producing regions in Brazil, Argentina, and Australia, exposing processors to foot-and-mouth disease containment disruptions. Distribution runs through pharmaceutical ingredient distributors for prescription channels and direct-to-consumer platforms for nutraceutical volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chondroitin sulfate market is recovering from a cyclical trough as osteoarthritis therapeutic demand rebounds in aging Japanese and German populations, with prescription volumes expanding through statutory reimbursement pathways.
For Market Incumbents: Fortify pharmacopeial certification infrastructure against NMPA registration requirements tightening for Chinese export qualification. Deepen backward integration into captive cattle rendering operations in Brazil and Argentina to neutralize raw material volatility. Prioritize dual USP-EP batch qualification to eliminate parallel testing burdens fragmenting multinational supply strategies. For New Entrants and Emerging Players: FDA cGMP fast-track certification for dietary supplement raw materials opens procurement access to US direct-to-consumer channels compressed by enforcement actions. Target cosmetic-grade production for South Korean and Swiss formulators advancing transdermal delivery research, where certification barriers remain lowest. Pursue enzymatic technology licensing from European specialists to bypass alkaline extraction capital intensity. For Investors and Strategic Acquirers: NMPA pharmaceutical ingredient registration reshapes the acquisition landscape by privileging Chinese producers with export-qualification infrastructure. Long-term viability centers on integrated facilities combining hyaluronan-chondroitin co-production capabilities with captive feedstock security. Monitor PMDA audit pass rates as the inflection signal for Japanese prescription market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Harmonization Partnership | Dual USP-EP qualification eliminates parallel batch testing costs for multinational suppliers. |
| Enzymatic Processing Scale-Up | Membrane filtration adoption compresses pharmaceutical-grade capital recovery timelines against alkaline methods. |
| Backward Integration into Rendering | Captive bovine trachea sourcing neutralizes livestock disease quarantine exposure in Brazil and Argentina. |
| Cosmetic-Grade Capacity Expansion | Transdermal delivery research in Swiss and South Korean laboratories opens lower-certification volume channels. |
| NMPA Registration Investment | Export-qualification infrastructure captures premium positioning as international buyers diversify from European supply. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA warning letters, EMA inspection databases, and NMPA registration filings to establish qualified supplier pool dynamics. Extraction plant managers, pharmaceutical procurement directors at German and Japanese drug producers, dietary supplement brand owners, and cosmetic formulators in France and Switzerland provided operational data. Trade customs records, pharmacopeial monograph revisions, and clinical trial registrations for osteoarthritis therapeutics supplied volume triangulation. Bottom-up capacity assessments and top-down demand modeling converged on segment-level outputs.
Segmentation dimensions modeled include product grade tier, application pathway, end-user vertical, and delivery form across the projection horizon. CAGRs derive from volume trajectory analysis calibrated against regulatory enforcement intensity and substitution elasticity for glucosamine combinations. Molecular weight specification evolution and sulfate content harmonization progress between USP, EP, and Chinese pharmacopeia standards inform grade-specific growth differentials. Patient demographic projections for osteoarthritis prevalence in Germany and Japan anchor prescription demand assumptions.
Decision-makers should treat outputs as directional under stable pharmacopeial standards and continued FDA cGMP enforcement intensity; material deviation in regulatory alignment or livestock disease containment would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Tetrahydropalmatine Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
Postbiotics Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
Cordyceps Sinensis and Militaris Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
Micro-Ecological Regulators Market
Nutraceuticals
Cartino Collagen Market
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
Cissus Quadrangularis Market
Nutraceuticals
Nattokinase Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Magtein Market
Nutraceuticals
Chondroitin Market